
 Canada Waste-To-Energy Market | 2026-2036
Canada Waste-To-Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Waste-To-Energy Market Outlook
Plasma gasification and advanced combustion control is narrowing the efficiency gap between mass-burn incineration and combined cycle power plants. Covanta Holding Corp leverages its operating footprint across North American facilities to sustain long-term service contracts. Waste Management Inc anchors its competitive position through vertical control of collection-to-energy logistics. Veolia Environnement differentiates via integrated water-waste-energy platforms in Canadian provinces.
Waste-to-energy converts municipal solid waste, industrial refuse, and biomass feedstocks into electricity, heat, or synthetic fuels through thermal or biological processes, typically operating at combustion temperatures exceeding 850 degrees Celsius to ensure complete pollutant breakdown and energy recovery. Incineration technology occupies the dominant installed base due to proven reliability and lower capital thresholds for municipal sponsors. Gasification competes for new project finance as provinces seek higher electrical efficiency and reduced residual ash. Anaerobic digestion specializes in organic fraction streams from agricultural residues and food processing waste, capturing methane for grid injection or fleet fuel.
Health Canada and Environment and Climate Change Canada jointly administer emission standards under the Canadian Environmental Protection Act, while provincial regulators in Ontario and Quebec layer site-specific air quality permits that dictate stack monitoring protocols and residue disposal pathways. The federal carbon pricing backstop elevates landfill tipping fees, redirecting waste volumes toward thermal treatment alternatives. Stakeholders must monitor provincial renewable natural gas mandates and interconnection queue reforms that determine project revenue stacking.
Market Dynamics
Federal carbon pricing and methane regulations are tightening landfill diversion requirements across Canadian provinces, redirecting municipal waste volumes toward thermal treatment infrastructure while elevating tipping fee economics for incineration and gasification projects.
Growth Catalysts
- Carbon Pricing Framework:The federal backstop mechanism elevates landfill operating costs, improving project finance viability for waste-to-energy facilities in Ontario and Quebec.
- Plasma Gasification:Advanced thermal conversion technology narrows efficiency gaps with combined cycle plants, attracting provincial utility procurement in British Columbia.
- Industrial Corridor Demand:Quebec's manufacturing belt generates concentrated organic waste streams suitable for anaerobic digestion with renewable natural gas capture.
Market Restraints
- Capital Intensity:Front-loaded engineering and construction timelines for gasification plants strain municipal balance sheets beyond mass-burn alternatives.
- Residual Ash Disposal:Provincial air quality permits dictate costly hazardous waste pathways for fly ash, compressing operating margins.
- Interconnection Queues:Grid connection reforms in Ontario delay revenue recognition for new generating capacity.
Strategic Opportunities
- Agricultural Biogas:Prairie provinces present underpenetrated feedstock reserves for farm-scale anaerobic digestion with biomethane upgrading.
- Renewable Natural Gas Mandates:British Columbia's low-carbon fuel standard creates guaranteed offtake channels for landfill gas and digester projects.
- Heat Network Integration:District heating infrastructure in the Greater Toronto Area enables combined heat and power configurations.
Industry Challenges
- Emissions Compliance Expertise:Health Canada and Environment and Climate Change Canada joint administration requires specialized air quality monitoring capabilities.
- Feedstock Sorting Infrastructure:Contamination rates in municipal solid waste streams degrade thermal efficiency and accelerate refractory maintenance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Waste-To-Energy Market |
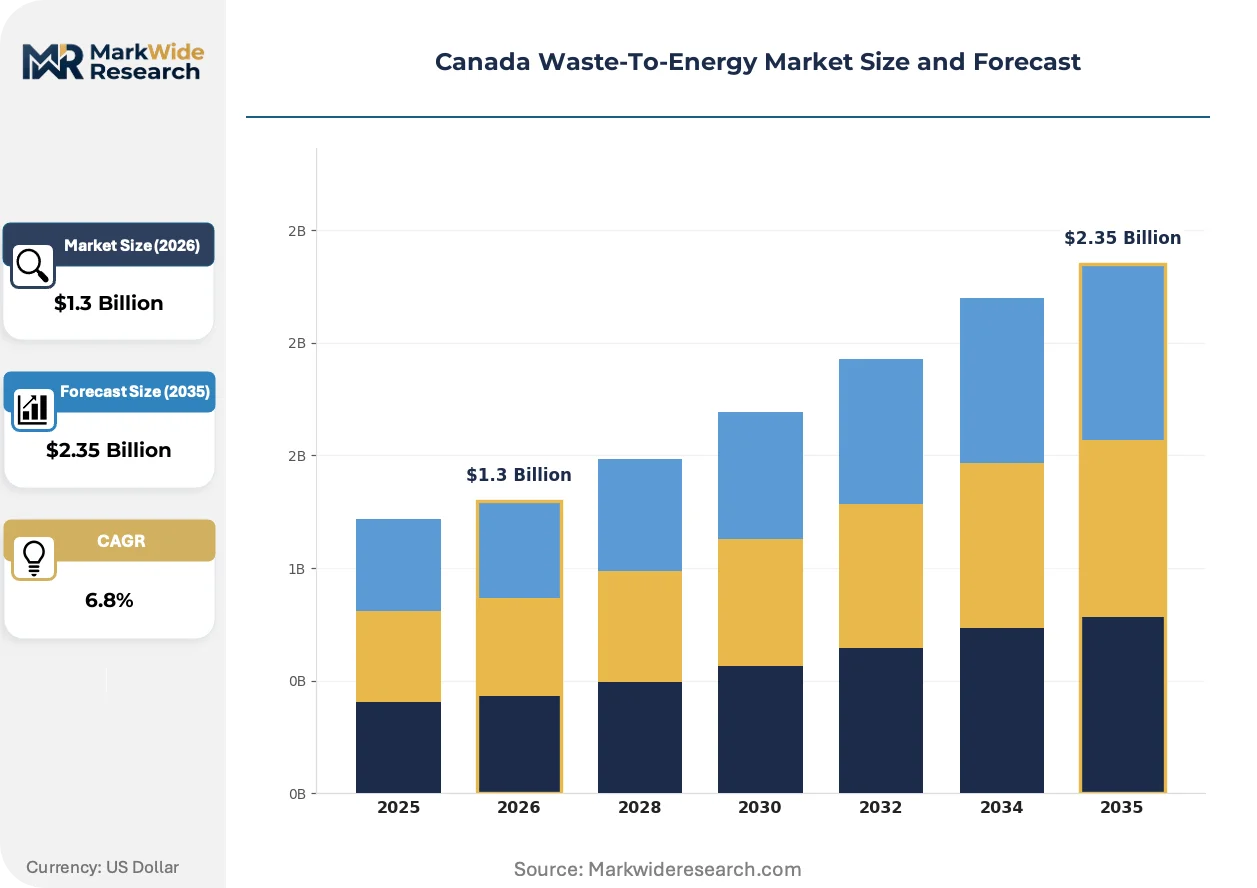
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Gasification, Anaerobic Digestion, Pyrolysis Feedstock Type: Municipal Solid Waste, Industrial Waste, Agricultural Residues, Biomass End User: Energy Producers, Waste Management Companies, Local Governments, Industrial Users Application: Electricity Generation, Heat Production, Fuel Production, Combined Heat and Power |
| Companies Covered | Covanta Holding Corp, Waste Management Inc, Veolia Environnement, Suez SA, Martin GmbH, Wheelabrator Technologies Inc, Varme Energy, Babcock & Wilcox Enterprises, Generate Upcycle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Waste-To-Energy Market Strategic Shifts
Technology migration, regulatory layering, and procurement model evolution are restructuring competitive positioning across Canadian waste-to-energy development. Three forces merit particular attention.
Plasma gasification is migrating from pilot demonstration to commercial-scale deployment in Ontario and British Columbia. Municipal utilities with long-term service agreements are adopting this technology to achieve higher electrical efficiency and reduced residual waste volumes. The shift is compressing market share for conventional mass-burn incineration in new project finance.
Health Canada and Environment and Climate Change Canada jointly administer emission standards under the Canadian Environmental Protection Act. Provincial regulators in Quebec layer site-specific air quality permits that dictate stack monitoring protocols. Facility operators are responding with advanced combustion control systems and continuous emissions monitoring investments.
Long-term power purchase agreements with integrated heat off-take are displacing merchant electricity exposure in project structuring. Industrial hosts in Quebec's manufacturing corridor are securing baseload thermal supply through behind-the-meter configurations. This arrangement is most visible in the Greater Toronto Area where district heating networks anchor project bankability.
Canada Waste-To-Energy Market Segmentation
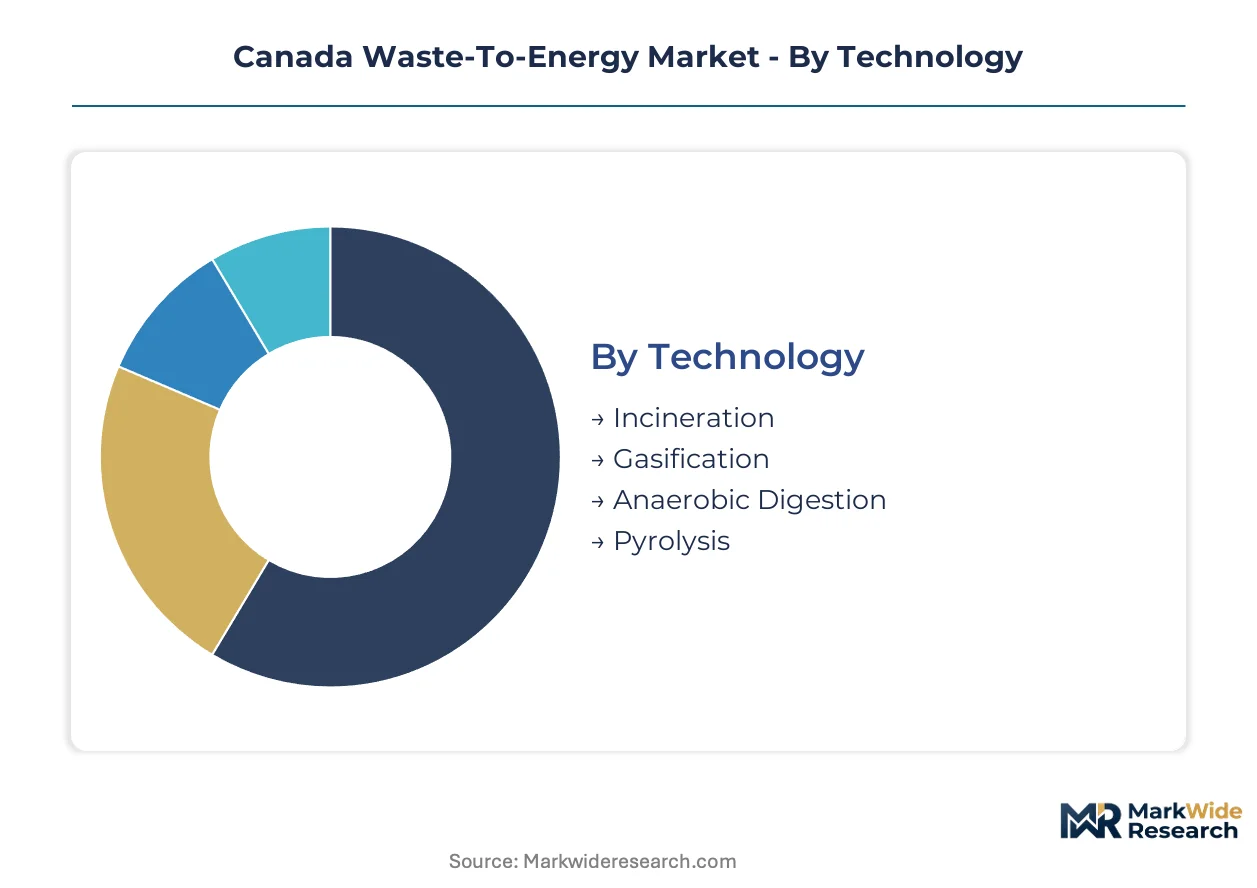
Technology choice determines capital intensity, emission profiles, and revenue stacking potential for Canadian waste-to-energy developers. Feedstock availability and end-user contracting structures further fragment procurement patterns across provinces.
Technology:
The use-case spectrum spans high-volume municipal processing to specialized industrial waste conversion, with efficiency and residual output characteristics driving site selection.
- Incineration:Mass-burn systems operate at combustion temperatures exceeding 850 degrees Celsius, ensuring complete pollutant breakdown through proven refractory designs. Ontario municipal utilities anchor procurement for baseload electricity and district heat supply, leveraging lower capital thresholds against constrained balance sheets.
- Gasification:Advanced thermal conversion employs controlled oxygen environments to produce syngas for combined cycle power generation. British Columbia provincial procurement targets higher electrical efficiency and reduced residual ash volumes, attracting project finance for greenfield development.
- Anaerobic Digestion:Biological methane capture from organic waste streams serves Quebec's industrial corridor and agricultural biogas facilities.
- Pyrolysis:Thermal decomposition in oxygen-absent environments yields synthetic fuels and carbon char from plastic-rich feedstocks.
Established volume favors incineration; emerging adoption favors gasification.
Feedstock Type:
Cost tier differentiation separates high-volume municipal contracts from premium-priced industrial and agricultural streams.
- Municipal Solid Waste:Mixed household and commercial refuse constitutes the dominant feedstock base, with contamination rates directly impacting thermal efficiency and maintenance cycles. The Greater Toronto Area generates concentrated waste volumes requiring diversion from federally regulated landfill methane emissions.
- Industrial Waste:Manufacturing byproducts and process residues command premium tipping fees due to specialized handling requirements. Quebec's manufacturing belt produces consistent organic waste streams suitable for renewable natural gas capture and behind-the-meter energy supply.
- Agricultural Residues:Prairie provinces present underpenetrated manure and crop residue reserves for farm-scale digestion.
- Biomass:Forestry and agricultural biomass supplements thermal feedstock supply in British Columbia and Ontario.
Municipal contracts deliver volume certainty; industrial streams command margin premiums.
End User:
Customer type determines contracting duration, offtake pricing mechanisms, and operational risk allocation.
- Energy Producers:Independent power developers and provincial utilities procure waste-to-energy capacity through long-term power purchase agreements with integrated heat off-take, displacing merchant electricity exposure in project bankability.
- Waste Management Companies:Integrated collection-to-energy operators leverage vertical control of logistics to secure feedstock supply and tipping fee revenue.
- Local Governments:Municipal sponsors in Ontario and British Columbia expand procurement of thermal treatment capacity under federal carbon pricing and methane regulations.
- Industrial Users:Manufacturing hosts secure baseload thermal supply through behind-the-meter configurations in Quebec's industrial corridor.
Utility contracting favors scale; industrial offtake favors heat integration.
Application:
Revenue model selection hinges on grid interconnection access, thermal demand density, and fuel market development.
- Electricity Generation:Grid-connected power sales dominate revenue structures, though Ontario interconnection queue reforms delay recognition for new capacity.
- Heat Production:District heating infrastructure in the Greater Toronto Area enables combined heat and power configurations with improved project economics.
- Fuel Production:Renewable natural gas upgrading for pipeline injection serves British Columbia's low-carbon fuel standard mandates.
- Combined Heat and Power:Cogeneration maximizes energy recovery efficiency, attracting procurement from industrial hosts with concurrent thermal and electrical demand.
Power sales dominate revenue; heat integration maximizes efficiency recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario exports thermal treatment expertise and equipment to Quebec and British Columbia, while Atlantic Canada imports European gasification technology through maritime trade corridors.
Ontario
The Greater Toronto Area generates concentrated municipal solid waste volumes requiring diversion from federally regulated landfill methane emissions. Environment and Climate Change Canada carbon pricing backstop elevates tipping fees across the province. Municipal utilities in Toronto and Hamilton expand procurement of mass-burn incineration capacity with integrated district heating supply.
Quebec
Quebec's manufacturing belt produces consistent organic waste streams suitable for renewable natural gas capture and behind-the-meter energy supply. The provincial renewable natural gas mandate creates guaranteed offtake channels for anaerobic digestion projects. Industrial hosts in Montreal and Quebec City secure baseload thermal supply through cogeneration configurations.
British Columbia
Vancouver and Victoria metropolitan areas face constrained landfill capacity under the federal methane regulations. Health Canada emission standards under the Canadian Environmental Protection Act drive stack monitoring investments. Provincial procurement targets plasma gasification for higher electrical efficiency and reduced residual ash volumes.
Alberta
Prairie provinces present underpenetrated agricultural feedstock reserves for farm-scale anaerobic digestion with biomethane upgrading. The federal carbon pricing framework improves project finance viability for biogas facilities. Agricultural clusters near Calgary and Edmonton develop manure-to-energy infrastructure with pipeline injection capability.
Atlantic Canada
Maritime provinces import European gasification technology through Halifax and Saint John port infrastructure. Provincial regulators layer site-specific air quality permits atop federal standards. Smaller municipal sponsors in Nova Scotia and New Brunswick pursue modular thermal treatment solutions with lower capital thresholds.
Canada Waste-To-Energy Market Competitive Environment
Channel-controlling players compete with product-specialist players across technology tiers. The vendor base concentrates around integrated waste management conglomerates with captive collection networks and independent power developers with utility contracting expertise. Two strategic archetypes dominate: vertically integrated operators controlling feedstock logistics from collection to energy recovery, and technology licensors supplying gasification and anaerobic digestion equipment to municipal sponsors. Competitive moves center on long-term service contract extensions and strategic partnerships with provincial utilities for greenfield development.
Among North American integrated operators, Covanta Holding Corp, Waste Management Inc, and Wheelabrator Technologies Inc occupy positions exemplifying the channel-control archetype through captive waste collection infrastructure and long-term municipal service agreements. These entities anchor competitive positioning by securing feedstock supply certainty and tipping fee revenue streams. European specialists including Veolia Environnement and Suez SA represent the technology-platform archetype, offering integrated water-waste-energy solutions to provincial regulators seeking comprehensive environmental services.
| Leading Market Players |
|---|
| Covanta Holding Corp |
| Waste Management Inc |
| Veolia Environnement |
| Suez SA |
| Martin GmbH |
| Wheelabrator Technologies Inc |
| Varme Energy |
| Babcock & Wilcox Enterprises |
| Generate Upcycle |
| Others |
Value Chain & Pricing Dynamics
The Saint Lawrence Seaway freight corridor shapes cost dynamics for European gasification equipment imports, concentrating supply leverage among Ontario-based EPC contractors while forcing price differentiation between mass-burn incineration and advanced plasma systems.
Pricing Analysis
The technology-generation pricing gap separates legacy mass-burn incineration from emerging plasma gasification and next-generation anaerobic digestion with biomethane upgrading. Project-based long-term offtake contracts dominate, with price differentiation driven by carbon credit eligibility under the federal backstop and after-sales service bundling for refractory maintenance. Cost compression in conventional incineration intensifies due to feedstock contamination rates degrading thermal efficiency. Municipal utilities in Ontario and Quebec exhibit highest price sensitivity; industrial hosts in manufacturing corridors show lowest sensitivity due to behind-the-meter thermal value capture.
Supply Chain Analysis
Canadian Environmental Protection Act export-control alignments with European Union dual-use technology frameworks restrict plasma torch and advanced combustion control system flows. Geographic supply concentration centers on Germany, Denmark, and Japan for gasification reactor vessels, syngas cleanup trains, and continuous emissions monitoring systems. Raw material dependencies include high-grade refractory ceramics, specialty alloys for corrosive gas environments, and precision instrumentation for stack monitoring. Single-source vulnerability runs through German plasma torch manufacturers. Distribution runs through EPC-led turnkey contracting with provincial utility direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against landfill methane capture with renewable natural gas upgrading, which threatens to divert organic waste feedstocks from thermal treatment at lower capital intensity.
For Market Incumbents: Harden feedstock supply certainty through backward integration into municipal collection contracts in the Greater Toronto Area and Quebec's industrial corridor. Expand service contract extensions to lock in tipping fee revenue against anaerobic digestion competitors targeting organic waste streams. Prioritize plasma gasification capacity additions in British Columbia to capture provincial utility procurement favoring higher electrical efficiency. For New Entrants and Emerging Players: Establish a beachhead in Prairie province agricultural biogas, where underpenetrated manure and crop residue reserves lack incumbent collection infrastructure. Target farm-scale anaerobic digestion with pipeline injection capability near Calgary and Edmonton, leveraging federal carbon pricing economics without competing for municipal waste contracts. Pursue technology licensing partnerships with European equipment suppliers to bypass capital-intensive EPC capabilities. For Investors and Strategic Acquirers: Technology-agnostic mid-scale developers with provincial permitting expertise and utility interconnection relationships offer the strongest acquisition profile. Long-term viability hinges on exposure to renewable natural gas mandate expansion rather than pure electricity merchant risk. Watch British Columbia's low-carbon fuel standard compliance credit pricing as the inflection indicator for biogas project returns.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Power Purchase Agreement | Ontario municipal utilities anchor project bankability through integrated heat off-take contracting. |
| Backward Integration into Collection | Captive feedstock logistics secure tipping fee revenue against organic waste diversion competitors. |
| Technology Licensing Partnership | European plasma gasification equipment suppliers enable greenfield entry without EPC capabilities. |
| Renewable Natural Gas Certification | British Columbia's low-carbon fuel standard creates guaranteed offtake channels for biogas upgrading. |
| District Heating Network Integration | Greater Toronto Area thermal infrastructure maximizes energy recovery efficiency in combined heat and power configurations. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with utility planning officers, IPP project developers, EPC contractors, and provincial environmental regulators; and secondary validation through Environment and Climate Change Canada emission filings, provincial air quality permit databases, and interconnection queue records. Bottom-up project development pipelines were triangulated against top-down federal carbon pricing impact assessments.
Forecast inputs considered technology adoption curves, provincial procurement timelines, and regulatory enforcement intensity across the analysis window. Segmentation dimensions modeled include thermal conversion technology, feedstock contamination tier, end-user contracting structure, and regional regulatory framework. CAGRs were derived from installed capacity buildout trajectories and tipping fee elasticity responses to carbon pricing mechanics.
Macroeconomic conditions sit as an overlay; deviation in federal carbon price escalation schedules or provincial renewable natural gas mandate stringency would shift the trajectory. Forecasts reflect assumptions regarding Health Canada emission standard continuity and interconnection queue reform implementation. Material shifts in landfill methane regulation enforcement or plasma gasification technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Drilling Waste Management Services Market