
 Japan Waste to Energy Market | 2026-2036
Japan Waste to Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Waste to Energy Market Foresight
Aftermarket service revenue for boiler maintenance and flue gas treatment upgrades is reshaping profit pools away from pure equipment sales. Mitsubishi Heavy Industries Environmental & Chemical Engineering leverages its integrated engineering-procurement-construction model to capture long-term service contracts. JFE Engineering Corporation anchors its position through advanced stoker furnace technology and domestic fabrication scale. TAKUMA Co. Ltd specializes in custom waste handling systems that handle Japan's high-moisture municipal solid waste streams.
Waste to energy denotes thermal and biological processes that convert combustible refuse into electricity, heat, or synthetic fuels, typically operating at combustion temperatures exceeding 850°C in mass-burn incinerators to ensure complete dioxin destruction and energy recovery through steam turbine generators. The technology segment shows incineration commanding the installed base while gasification gains traction for industrial waste streams requiring higher efficiency and lower residue output. Among end users, municipalities dominate procurement volume but power plants represent the fastest-growing application as liberalized electricity markets allow merchant offtake arrangements.
METI enforces power generation efficiency standards and waste heat utilization mandates under the Act on Promotion of Global Warming Countermeasures, while JIS standards govern emission limits and operational safety protocols for combustion facilities. Local prefectural governments layer additional siting requirements and environmental impact assessments that extend project development timelines. Stakeholders must track feed-in tariff revision schedules and carbon credit eligibility rules to optimize project financing structures and technology selection decisions.
Market Dynamics
Japan's waste to energy sector is consolidating around long-term service contracts as municipalities prioritize operational reliability over upfront equipment costs. The shift from capital expenditure to lifecycle cost optimization is redistributing value capture toward integrated engineering-procurement-construction operators capable of securing multi-decade maintenance agreements.
Growth Catalysts
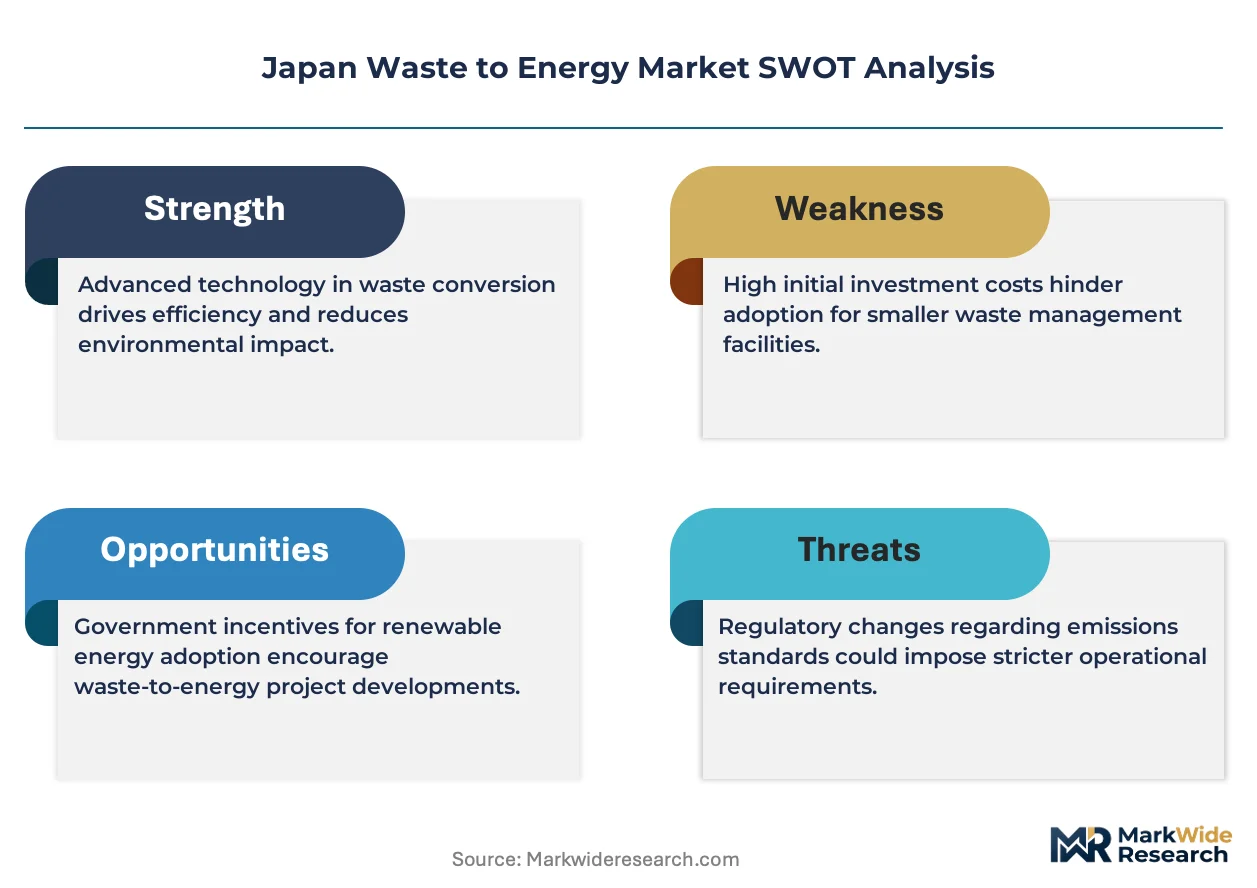
- METI Feed-in Tariff Framework:The guaranteed electricity purchase mechanism stabilizes revenue streams for incineration-based power generation, reducing project financing risk and accelerating municipal procurement cycles.
- Tokyo Metropolitan Demand:Dense population centers generate continuous high-volume waste streams that sustain baseload power operations, creating predictable feedstock economics for facility operators.
- Stoker Furnace Efficiency Gains:Advanced combustion grate designs achieve higher thermal conversion rates while maintaining complete dioxin destruction, satisfying JIS emission standards without secondary treatment systems.
Market Restraints
- Landfill Capacity Scarcity:Limited residual disposal alternatives in the Kanto region force facilities to achieve near-complete ash vitrification, elevating capital intensity for bottom and fly ash processing systems.
- High-Moisture Feedstock Volatility:Seasonal variations in Japanese municipal solid waste moisture content degrade combustion efficiency, requiring adaptive air supply controls and auxiliary fuel supplementation.
- Prefectural Siting Friction:Local environmental impact assessment procedures extend project development timelines by months, inflating carrying costs and compressing developer returns.
Strategic Opportunities
- Kansai Region Underpenetration:Osaka and Kyoto prefectures maintain lower incineration-to-population ratios than Tokyo, presenting greenfield development potential for merchant power arrangements.
- Industrial Waste Gasification Convergence:Plasma arc and fluidized bed systems offer higher efficiency for manufacturing byproduct streams, opening non-municipal revenue channels.
- Carbon Credit Eligibility Expansion:METI's evolving greenhouse gas accounting rules may qualify waste heat utilization for offset markets, enhancing project economics.
Industry Challenges
- Specialized Technician Scarcity:Boiler maintenance and flue gas treatment system expertise concentrates among aging workforces, constraining operational scaling and emergency response capacity.
- Legacy Facility Retrofit Complexity:Pre-2000 incineration plants require sequential upgrades to meet tightened dioxin and mercury emission thresholds, disrupting continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Waste to Energy Market |
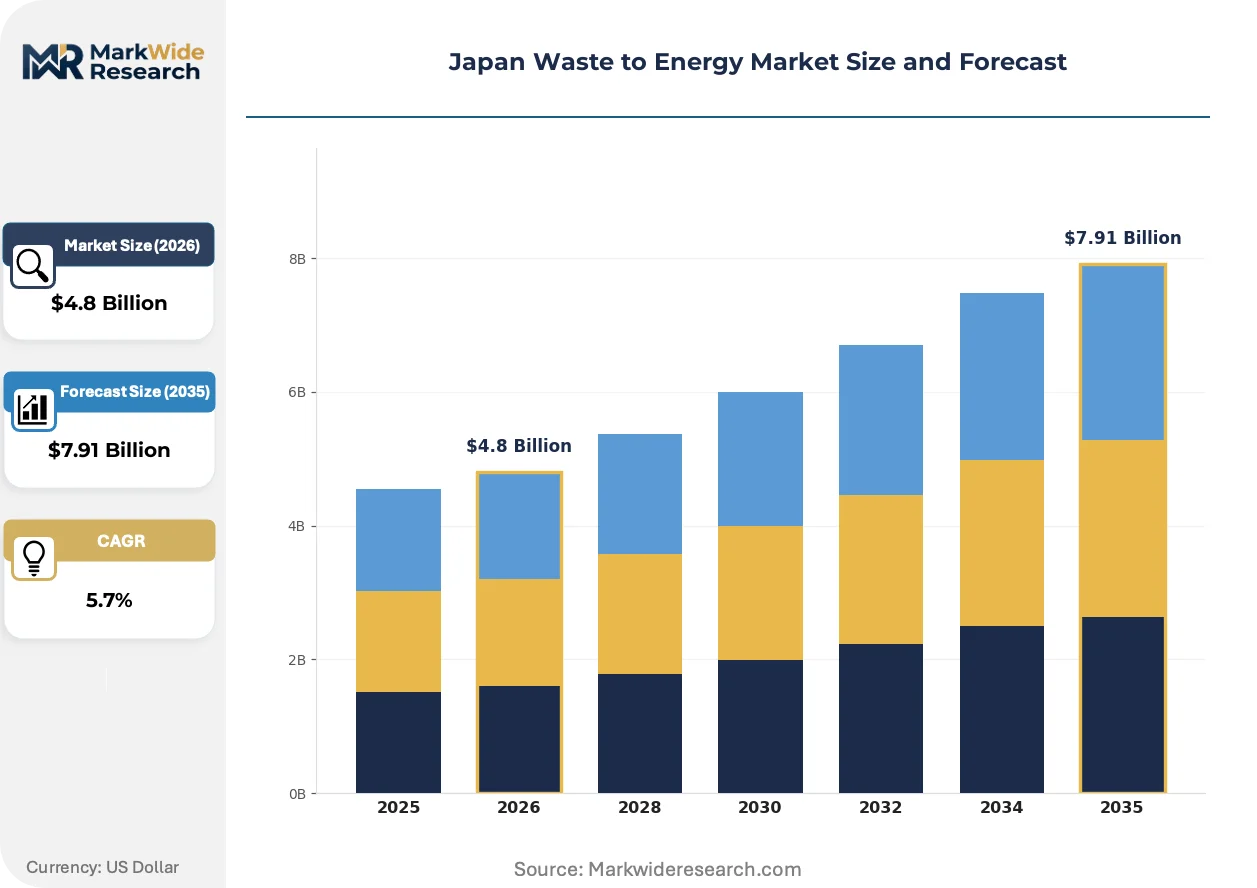
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Gasification, Anaerobic Digestion, Pyrolysis End User: Municipalities, Industries, Power Plants, Waste Management Companies Feedstock Type: Municipal Solid Waste, Industrial Waste, Agricultural Residues, Biomass Application: Electricity Generation, Heat Production, Fuel Production, Resource Recovery |
| Companies Covered | Mitsubishi Heavy Industries Environmental & Chemical Engineering, JFE Engineering Corporation, TAKUMA Co. Ltd, Hitachi Zosen Corporation, Kawasaki Heavy Industries Ltd, Kanadevia Corporation, Doosan Lentjes GmbH, CR-POWER LLC, Mitsubishi Heavy Industries Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Waste to Energy Market Shifts & Advancements
Digital twin technology is penetrating combustion facility management, enabling predictive maintenance and thermal optimization without physical system shutdowns. Equipment vendors and municipal operators are converging on data-driven operational models that compress unplanned downtime.
Advanced sensor arrays and machine learning algorithms are virtualizing traditional combustion control systems. Municipal operators in the Kanto region are deploying these platforms to anticipate grate fouling and optimize excess air ratios in real time. This virtualization is compressing the competitive advantage of pure hardware suppliers while elevating software-integrated service providers.
METI's 2050 carbon neutrality roadmap is tightening power generation efficiency mandates under the Act on Promotion of Global Warming Countermeasures. Waste heat utilization requirements now extend to district heating applications, compelling facility designers to integrate thermal distribution infrastructure. Industrial clusters in the Keihin region are responding with combined heat and power configurations that serve adjacent manufacturing facilities.
Long-term service contracts are displacing transactional equipment procurement as the dominant commercial model. Municipalities facing budget constraints prefer operational expenditure structures that transfer performance risk to vendors. This shift is most visible in Tokyo's 23 wards, where integrated maintenance agreements now span fifteen to twenty year terms.
Japan Waste to Energy Market Segmentation
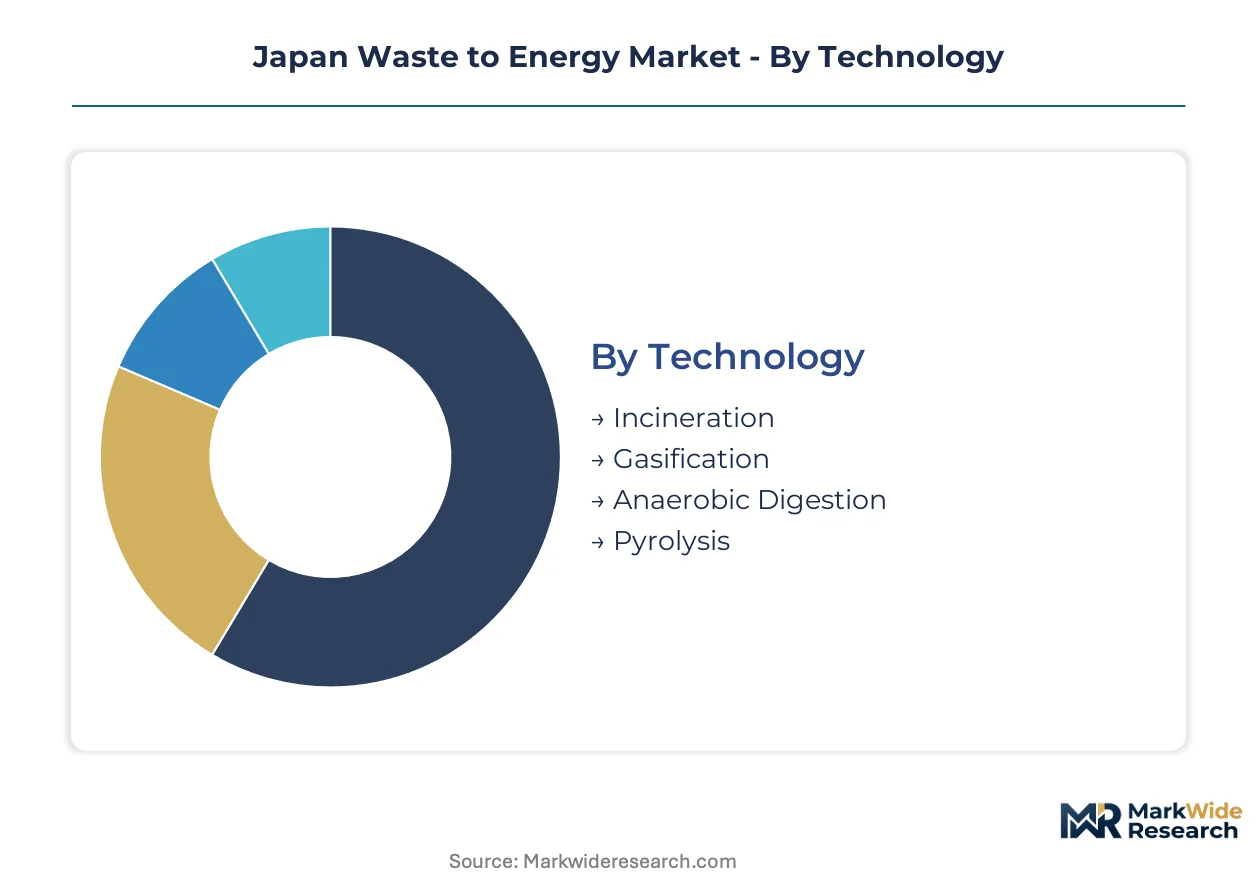
Technology selection determines capital intensity, emission profiles, and revenue stability across Japan's waste to energy installations. Feedstock moisture content, regional landfill scarcity, and METI efficiency mandates drive divergent procurement patterns among municipalities and industrial operators.
Technology:
Cost tier stratification separates mass-burn incinerators from advanced thermal conversion systems requiring secondary syngas cleanup.
- Incineration:Mass-burn grate systems combust unprocessed municipal solid waste at temperatures exceeding 850°C, ensuring complete dioxin destruction under JIS standards. Tokyo's 23 wards and dense Kanto municipalities anchor demand, driven by landfill capacity exhaustion and baseload power purchase agreements under METI's feed-in tariff framework.
- Gasification:Partial oxidation in oxygen-starved environments produces synthetic gas for combined cycle power generation, achieving higher electrical efficiency than grate combustion. Osaka and Kyoto prefectures show accelerating procurement for industrial waste streams requiring lower residual ash output and merchant power offtake flexibility.
- Anaerobic Digestion:Biological decomposition of organic fractions generates biogas for captive heat or grid injection, suited to high-moisture agricultural and food waste streams in rural prefectures.
- Pyrolysis:Thermal degradation in oxygen-absent conditions yields liquid fuels and char, finding niche deployment for plastic-rich industrial byproduct processing.
Incineration commands the established base. The steepest expansion runs through gasification.
End User:
Customer type determines contracting structure, with public procurement favoring lifecycle cost models and private offtake enabling merchant risk exposure.
- Municipalities:City and ward governments dominate installed capacity, operating facilities under long-term service contracts that transfer operational risk to engineering-procurement-construction vendors. Tokyo Metropolitan Government procurement sets technical specifications adopted by adjacent prefectures.
- Industries:Manufacturing clusters in the Keihin and Chukyo industrial zones deploy captive waste heat utilization systems, responding to METI mandates under the Act on Promotion of Global Warming Countermeasures.
- Power Plants:Liberalized electricity markets enable independent power producers to secure merchant offtake arrangements, expanding most quickly in underpenetrated Kansai region prefectures.
- Waste Management Companies:Private collectors and processors operate material recovery facilities with integrated thermal conversion, concentrating in Osaka and Aichi prefectures.
Municipalities anchor procurement volume. Power plants are climbing the fastest.
Feedstock Type:
Volume concentration and calorific stability separate commercially viable streams from auxiliary fuel-dependent inputs.
- Municipal Solid Waste:Household and commercial refuse with seasonal moisture variation between 40-60% wet basis, requiring adaptive combustion controls. Kanto region density sustains continuous feedstock supply for baseload operations.
- Industrial Waste:Manufacturing byproducts including packaging, process residues, and off-spec materials with higher calorific consistency than municipal streams. Aichi and Shizuoka prefectures generate concentrated volumes from automotive and chemical production clusters.
- Agricultural Residues:Rice straw, livestock manure, and food processing waste with high moisture and ash content, biologically treated in rural Hokkaido and Tohoku prefectures.
- Biomass:Woody construction debris and forestry thinnings with lower moisture and higher lignin content, suited to co-firing configurations in combined heat and power facilities.
Municipal solid waste dominates feedstock throughput. Industrial waste is gaining share fastest.
Application:
Margin structure diverges between commoditized electricity sales and premium thermal service contracts.
- Electricity Generation:Steam turbine and combined cycle configurations feeding grid-connected generators, governed by METI feed-in tariff schedules and power generation efficiency standards.
- Heat Production:District heating and industrial process steam delivery, concentrated in Keihin region combined heat and power clusters serving adjacent manufacturing facilities.
- Fuel Production:Syngas upgrading to synthetic natural gas or hydrogen precursors, emerging in demonstration projects targeting carbon neutrality compliance pathways.
- Resource Recovery:Metal extraction from bottom ash and vitrified slag utilization in construction materials, mandated by near-zero landfill policies in Tokyo and surrounding prefectures.
Electricity generation holds the revenue base. Heat production shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese sub-regions deploy waste-to-energy infrastructure at markedly different intensities. Kanto municipalities favor mass-burn incineration for baseload electricity, while Kansai operators experiment with gasification for industrial waste streams. Rural prefectures rely more heavily on biological treatment for agricultural residues.
Kanto/Tokyo
Tokyo's 23 wards generate Japan's densest municipal waste streams per square kilometer. METI's feed-in tariff framework stabilizes revenue for grid-connected incineration facilities. The Keihin industrial corridor hosts combined heat and power configurations serving adjacent manufacturing plants.
Kansai/Osaka
Osaka and Kyoto prefectures maintain lower incineration-to-population ratios than Tokyo, creating greenfield development potential. Local governments layer additional environmental impact assessments that extend project timelines. Merchant power arrangements are accelerating procurement among independent power producers.
Chubu/Nagoya
Aichi Prefecture's automotive and chemical clusters generate concentrated industrial waste volumes. Manufacturing byproducts with higher calorific consistency than municipal streams sustain captive waste heat utilization systems. METI mandates under the Act on Promotion of Global Warming Countermeasures compel facility integration with district heating networks.
Kyushu
Fukuoka and Kitakyushu municipalities balance industrial waste processing with rural agricultural residue treatment. Seasonal moisture variation in feedstocks degrades combustion efficiency, requiring adaptive air supply controls. Prefectural siting requirements add procedural friction to project development.
Hokkaido
Rural prefectures deploy anaerobic digestion for high-moisture agricultural and food waste streams. Livestock manure and rice straw processing concentrates in areas distant from thermal incineration infrastructure. Biological treatment generates biogas for captive heat or limited grid injection.
Japan Waste to Energy Market Competitive Landscape
Capability concentration sits with integrated engineering-procurement-construction operators; scale advantage sits with domestic fabrication specialists. The vendor base stratifies into three tiers: full-service EPC contractors securing multi-decade maintenance agreements, equipment fabricators optimizing stoker furnace designs, and regional specialists handling custom waste handling configurations. Dominant competitive moves include backward integration into boiler manufacturing and technology licensing partnerships for gasification systems.
Within the integrated service tier, Mitsubishi Heavy Industries Environmental & Chemical Engineering exemplifies the engineering-procurement-construction model. JFE Engineering Corporation occupies a position among furnace technology specialists. TAKUMA Co. Ltd represents the custom systems configuration archetype for high-moisture municipal waste applications.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Environmental & Chemical Engineering |
| JFE Engineering Corporation |
| TAKUMA Co. Ltd |
| Hitachi Zosen Corporation |
| Kawasaki Heavy Industries Ltd |
| Kanadevia Corporation |
| Doosan Lentjes GmbH |
| CR-POWER LLC |
| Mitsubishi Heavy Industries Ltd |
| Others |
Supply & Pricing Matrix
Undercapacity in Kansai's gasification infrastructure drives supplier prioritization toward long-term offtake negotiations, compressing spot-market liquidity and elevating pricing leverage for integrated engineering-procurement-construction operators with captive fabrication capabilities.
Pricing Analysis
Long-term service contracts dominate commercial structures, with municipalities favoring fifteen-to-twenty year operational expenditure arrangements that transfer performance risk to vendors. Price differentiation hinges on after-sales service bundling and JIS certification tier, with premium tiers commanding substantial markups for predictive maintenance integration. Cost compression in standard equipment tiers intensifies as stoker furnace technology commoditizes, squeezing pure hardware suppliers. Municipal procurement officers exhibit highest price sensitivity, while industrial power plant developers prioritize efficiency guarantees over upfront capital expenditure.
Supply Chain Analysis
Extended payment terms from municipal clients strain working capital, prompting equipment fabricators to secure supply-chain finance facilities anchored on confirmed service contract receivables. Manufacturing concentration rests on Japan, Germany, and South Korea for precision combustion grates and flue gas treatment systems. Critical dependencies include high-grade refractory ceramics, specialized alloy forgings for boiler pressure vessels, and advanced sensor arrays for emission monitoring. Single-source vulnerability concentrates in plasma arc torch components for gasification systems. Distribution feeds from domestic fabrication hubs through engineering-procurement-construction contractors to municipal end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's waste-to-energy sector sits in early-cycle expansion, with METI's feed-in tariff revisions and carbon neutrality compliance pathways accelerating procurement velocity beyond historical replacement-demand patterns.
For Market Incumbents: Build switching-cost moats through predictive maintenance platform integration and digital twin deployment across installed base. Deepen backward integration into boiler manufacturing to capture margin compression from commoditized stoker furnace competition. Secure multi-decade service contract renewals before feed-in tariff revision windows close, locking out emerging gasification technology entrants. For New Entrants and Emerging Players: Establish a beachhead in Osaka and Kyoto prefectures where incineration-to-population ratios trail Tokyo, creating greenfield merchant power development opportunities. Target industrial waste gasification for automotive and chemical manufacturing clusters seeking lower residual ash output and flexible offtake arrangements. Lead with combined heat and power configurations that satisfy METI waste heat utilization mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gasification technology deployment, favoring asset-light service platform acquisitions over heavy manufacturing footprints. Prioritize targets with captive municipal relationships and fifteen-plus year contract backlogs. Watch for feed-in tariff revision announcements as inflection signals for project financing availability and development pipeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Contract Expansion | Fifteen-to-twenty year maintenance agreements with Tokyo Metropolitan Government transfer operational risk and stabilize revenue visibility. |
| Backward Integration into Boiler Manufacturing | In-house production of pressure vessel components captures margin from refractory ceramic suppliers and reduces lead time exposure. |
| Digital Twin Platform Deployment | Predictive maintenance virtualization compresses unplanned downtime for Kanto region baseload facilities and differentiates integrated service providers. |
| Gasification Technology Licensing | Plasma arc and fluidized bed system partnerships open Osaka and Kyoto industrial waste streams with higher efficiency and lower residue output. |
| Combined Heat and Power Configuration | Waste heat utilization integration satisfies METI mandates under the Act on Promotion of Global Warming Countermeasures and serves Keihin manufacturing clusters. |
Research Methodology
A spread of perspectives from EPC project directors, municipal procurement officers, METI policy specialists, and stoker furnace maintenance technicians converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through METI feed-in tariff filings, JIS standard revision notices, prefectural environmental impact assessment records, and municipal waste management authority procurement databases. Bottom-up installation capacity tallies triangulated against top-down power generation efficiency mandate trajectories.
Demand-supply balance modeling tracked feedstock availability constraints against incineration and gasification capacity expansion pipelines across the projection horizon. Segmentation dimensions included technology type, end-user category, feedstock composition, and regional regulatory cluster. CAGRs derived from capacity-weighted average efficiency improvement curves and tariff-adjusted revenue per ton throughput. Industry-specific inputs incorporated seasonal moisture variation patterns and ash vitrification cost escalation for near-zero landfill prefectures.
Stress conditions across feed-in tariff revision schedules, refractory ceramic price volatility, and specialized technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on METI mandate enforcement timing and municipal budget cycle phasing. Macroeconomic contraction, regulatory delay, or breakthrough biological treatment adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Netherlands Waste to Energy Market