
 ORC Waste Heat to Power Market | 2026-2036
ORC Waste Heat to Power Market Size, Share, and Industry Trends Forecast 2026-2036
ORC Waste Heat to Power Market Analysis
Multi-source equipment procurement is repositioning how project developers secure ORC expanders and heat exchangers. Turboden leverages its Italian engineering base to dominate large-scale biomass and geothermal-linked installations. Siemens Energy sustains technology leadership through integrated turbomachinery solutions that span power islands and grid coupling. ElectraTherm specializes in small-scale distributed systems, occupying a niche below 500 kW where deployment velocity outpaces centralized alternatives.
Organic Rankine Cycle waste heat recovery converts low-to-medium temperature thermal energy into electricity using organic working fluids with boiling points below water, typically operating between 80°C and 350°C heat sources to serve industrial efficiency and emissions reduction goals. Single-stage ORC systems anchor current deployment volumes due to proven reliability and lower capital thresholds, while multi-stage ORC configurations capture margin pools in high-temperature chemical and steel applications where efficiency premiums justify complexity. Scroll expander technology leads the sub-megawatt segment through compact packaging and reduced maintenance intervals, whereas screw expander designs compete in geothermal and marine contexts where two-phase flow tolerance matters.
The EU Green Deal and F-Gas Regulation constrain working fluid selections, pushing developers toward lower-GWP refrigerants that reshape component material specifications and supplier qualification timelines. EPA industrial emissions guidelines in the United States create compliance-driven retrofit demand across cement and petrochemical facilities. China's dual carbon goals and GB standards on energy consumption intensity mandate waste heat utilization benchmarks that accelerate domestic ORC manufacturing scale. Stakeholders must monitor working fluid phase-down schedules and certification reciprocity between EMA chemical safety assessments and national environmental permits to avoid project delays.
Market Dynamics
The EU F-Gas Regulation's phase-down of high-GWP refrigerants is forcing ORC developers to redesign heat exchangers and expanders around lower-GWP organic working fluids, compressing supplier qualification timelines and reshaping material specifications across European installations.
Growth Catalysts
- EU Green Deal industrial mandates:Cement and steel producers across Germany, Poland, and Italy face binding decarbonization targets that classify waste heat recovery as qualifying technology for carbon border adjustment compliance.
- Automotive manufacturing clusters:Paint shop and foundry operations in Stuttgart and Wolfsburg generate consistent low-grade thermal streams ideal for sub-megawatt ORC deployment.
- Geothermal hybridization:Binary cycle plants in Tuscany and Bavaria are retrofitting ORC skids to capture additional thermal output from cooling circuits, improving project IRRs without new drilling.
Market Restraints
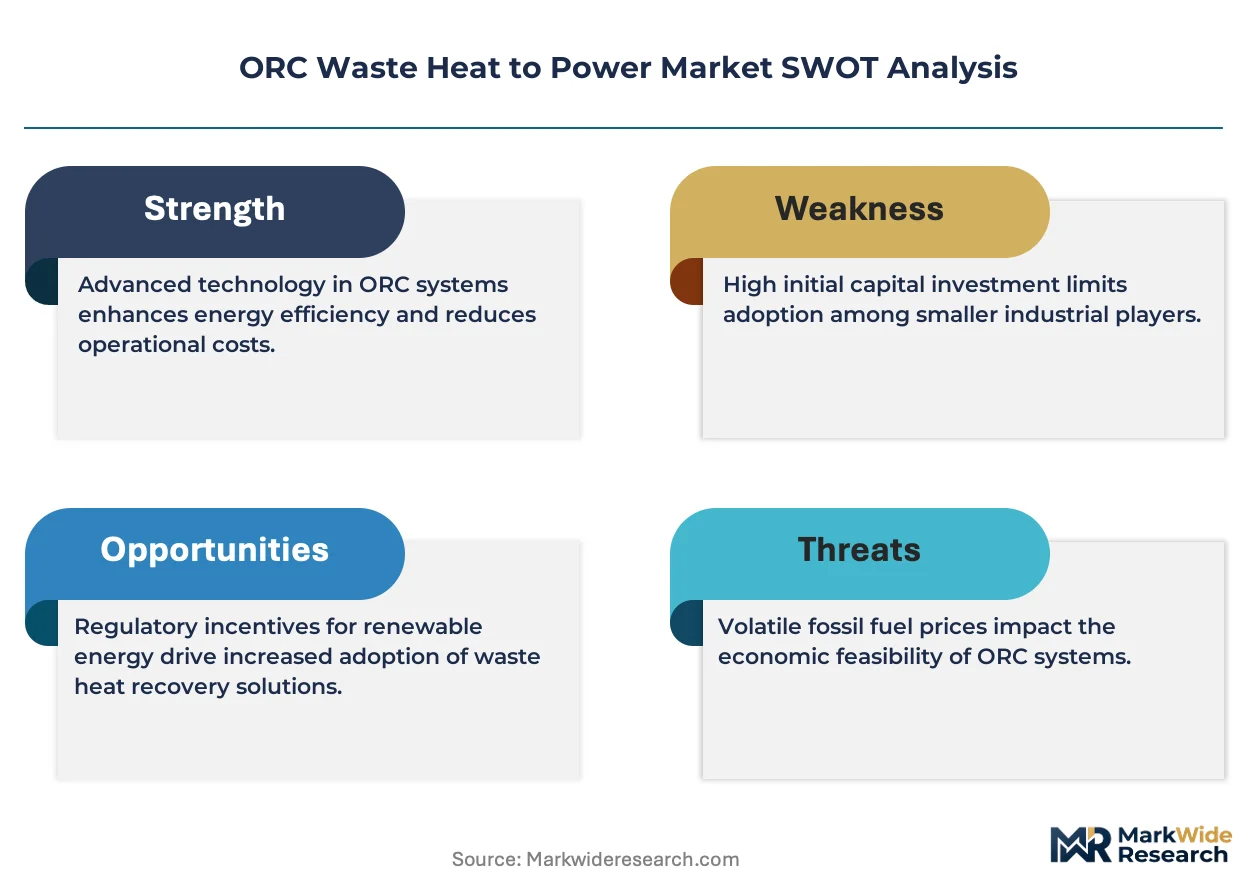
- Working fluid supply concentration:Specialty refrigerant production for ORC applications clusters with three German and Italian chemical suppliers, creating input vulnerability during EMA reauthorization cycles.
- Heat source variability:Batch-process industries like specialty chemicals generate intermittent thermal profiles that degrade ORC capacity factors below economic thresholds.
- Capital intensity barriers:Project payback periods stretch to 6-8 years for sub-500kW installations, excluding smaller industrial facilities without green financing support.
Strategic Opportunities
- Marine waste heat recovery:Two-stroke diesel propulsion systems on container routes between Rotterdam and Hamburg present untapped thermal streams for onboard ORC power generation.
- Data center cooling integration:Liquid-cooled server farms in Frankfurt and Amsterdam are piloting ORC systems to convert 60°C reject heat into electricity for facility loads.
- Carbon contract for difference schemes:Germany's H2Global and similar EU mechanisms provide revenue floors that de-risk ORC investments in hard-to-abate sectors.
Industry Challenges
- Working fluid thermodynamic expertise:The shift from R245fa to lower-GWP alternatives like R1233zd and hydrocarbon blends demands rare combinations of chemical engineering and turbomachinery optimization skills.
- Legacy steam system integration:Industrial sites with existing waste heat boilers require custom ORC interface engineering to avoid production downtime during retrofit installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ORC Waste Heat to Power Market |
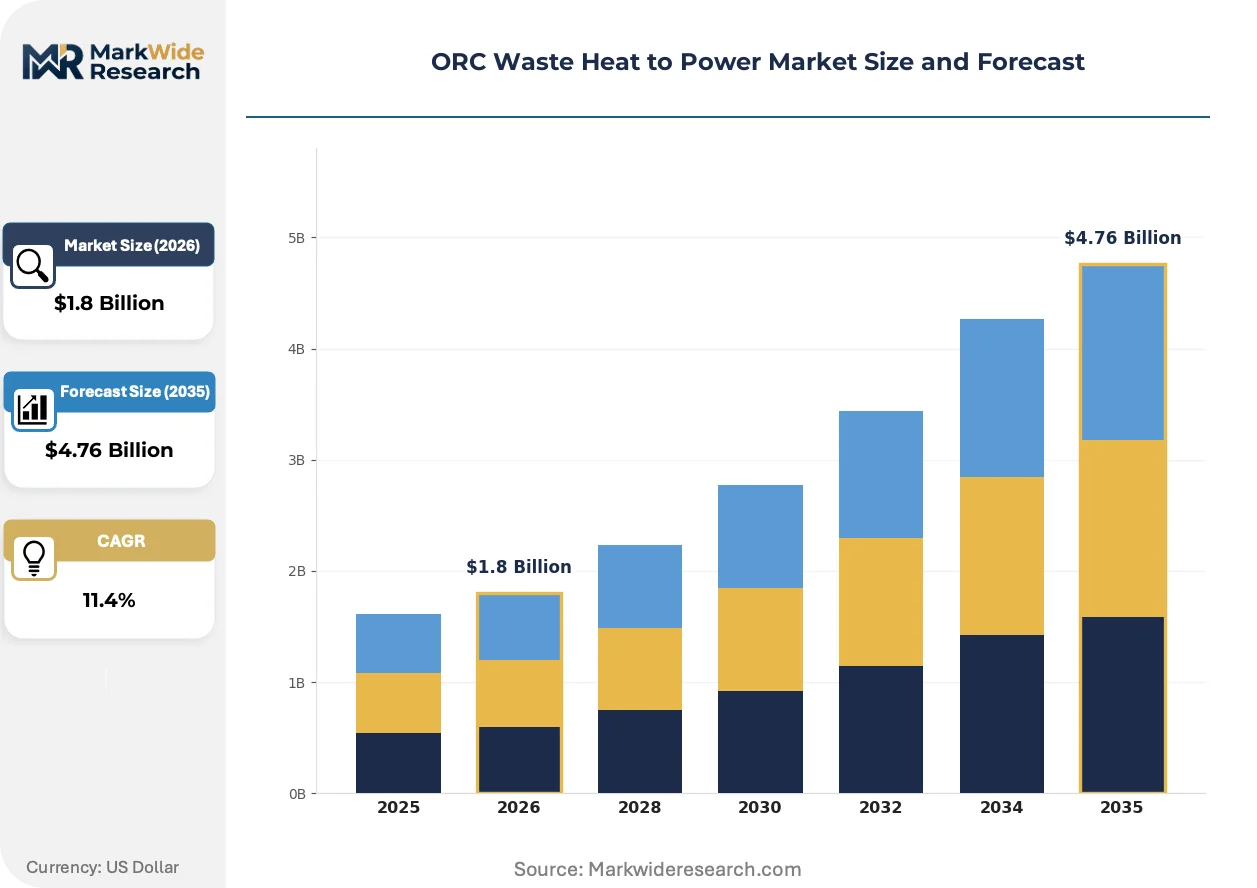
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Systems, Organic Rankine Cycle Systems, Heat Recovery Steam Generators, Waste Heat Boilers Application: Industrial Processes, Power Generation, Marine Applications, District Heating End User: Manufacturing, Oil & Gas, Chemical Plants, Renewable Energy Providers Technology: Single-stage ORC, Multi-stage ORC, Scroll Expander, Screw Expander |
| Companies Covered | Ormat Technologies, Turboden, Mitsubishi Heavy Industries, Exergy International, Enertime, Orcan Energy, ElectraTherm, Siemens Energy, Thermax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ORC Waste Heat to Power Market Emerging Trajectories
ORC system architecture is fragmenting into standardized, containerized sub-assemblies that compress deployment timelines and reduce field engineering costs for distributed industrial applications.
Scroll expander technology is modularizing into skid-mounted units below 100kW, enabling food processors and textile finishers in Northern Italy to deploy waste heat recovery without dedicated plant engineering teams. These plug-and-play configurations cut installation schedules from months to weeks. The approach is compressing vendor margins on engineering services while expanding addressable facility count.
REACH and the F-Gas Regulation are tightening working fluid approval pathways, forcing heat exchanger manufacturers toward stainless steel and aluminum alloys compatible with mildly flammable refrigerants. Chemical producers in Ludwigshafen and Tarragona are reformulating fluid portfolios around hydrofluoroolefins and hydrocarbon blends. The transition extends component validation cycles by 12-18 months for suppliers without existing ECHA dossiers.
Industrial energy managers are consolidating equipment procurement under performance-guaranteed service agreements rather than capital purchase models. EPC firms in the Ruhr region now offer heat-rate-based ORC contracts where payment follows verified electricity generation. The shift transfers operational risk to vendors and accelerates adoption among capital-constrained mid-sized manufacturers.
ORC Waste Heat to Power Market Segmentation
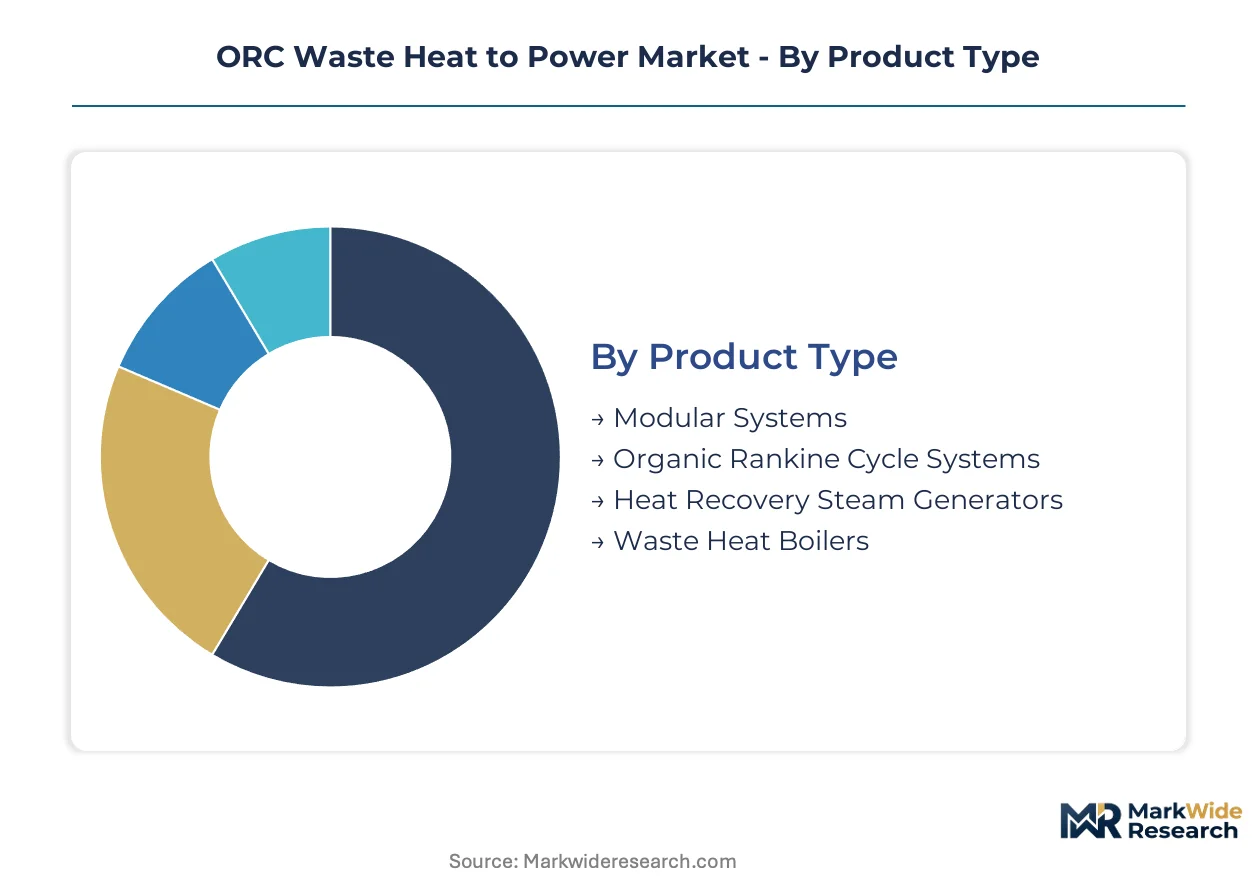
ORC technology configurations vary dramatically in engineering complexity and deployment scale. Project developers must match system architecture to thermal source characteristics, regulatory constraints, and capital availability across industrial, maritime, and power sector contexts.
Product Type:
Standardization dominates at the component level, while system integration demands site-specific customization across this category.
- Modular Systems:Pre-engineered skids with integrated expanders, heat exchangers, and control systems enable rapid deployment in distributed manufacturing contexts. Demand concentrates in German automotive clusters where paint shop waste heat streams require sub-megawatt solutions with minimal engineering overhead. Turboden and Orcan Energy anchor supply capacity for these containerized configurations.
- Organic Rankine Cycle Systems:Custom-engineered power blocks designed around specific working fluid selections and thermal boundary conditions serve large-scale cement and steel installations. Italian engineering firms dominate this segment through decades of geothermal and biomass project execution.
- Heat Recovery Steam Generators:Interface equipment bridging waste heat sources to ORC working fluid loops, common in refinery and petrochemical retrofit projects.
- Waste Heat Boilers:Shell-and-tube and water-tube configurations capturing exhaust thermal energy from gas turbines and industrial furnaces.
Leading the category by volume: Modular Systems. Growing fastest: Organic Rankine Cycle Systems.
Application:
End-use diversification is reshaping equipment specifications and vendor qualification requirements across deployment contexts.
- Industrial Processes:Cement kiln exhaust, steel rolling mill cooling, and chemical reactor off-gas recovery constitute the core demand base. German cement producers under EU Green Deal mandates drive retrofit installations. Capacity factors above 85 percent justify capital intensity in continuous-process environments.
- Power Generation:Binary cycle geothermal plants and biomass-fired CHP facilities anchor large-scale ORC deployment. Tuscany's Monte Amiata field and Bavarian Molasse Basin installations demonstrate mature project economics.
- Marine Applications:Two-stroke diesel waste heat recovery on container routes between Rotterdam and Hamburg represents nascent demand.
- District Heating:Seasonal thermal storage integration and combined heat-and-power optimization in Nordic and Baltic utility networks.
Industrial Processes command the largest installed base. Marine Applications show the steepest expansion trajectory as IMO efficiency regulations tighten.
End User:
Capital availability and emissions compliance urgency create distinct procurement patterns across customer categories.
- Manufacturing:Automotive, food processing, and textile operations with consistent thermal profiles favor sub-megawatt scroll expander configurations. Stuttgart and Wolfsburg manufacturing clusters generate concentrated demand for standardized sub-assemblies.
- Oil & Gas:Refinery fluid catalytic cracker off-gas and gas turbine exhaust recovery projects in Rotterdam and Antwerp require custom engineering and extended validation cycles.
- Chemical Plants:Batch-process specialty chemical facilities in Ludwigshafen face heat source variability challenges that degrade ORC economics.
- Renewable Energy Providers:Geothermal developers and biomass CHP operators seeking efficiency improvements through binary cycle hybridization.
Manufacturing leads procurement volume. Oil & Gas demonstrates the fastest project scale-up as carbon border adjustment mechanisms activate.
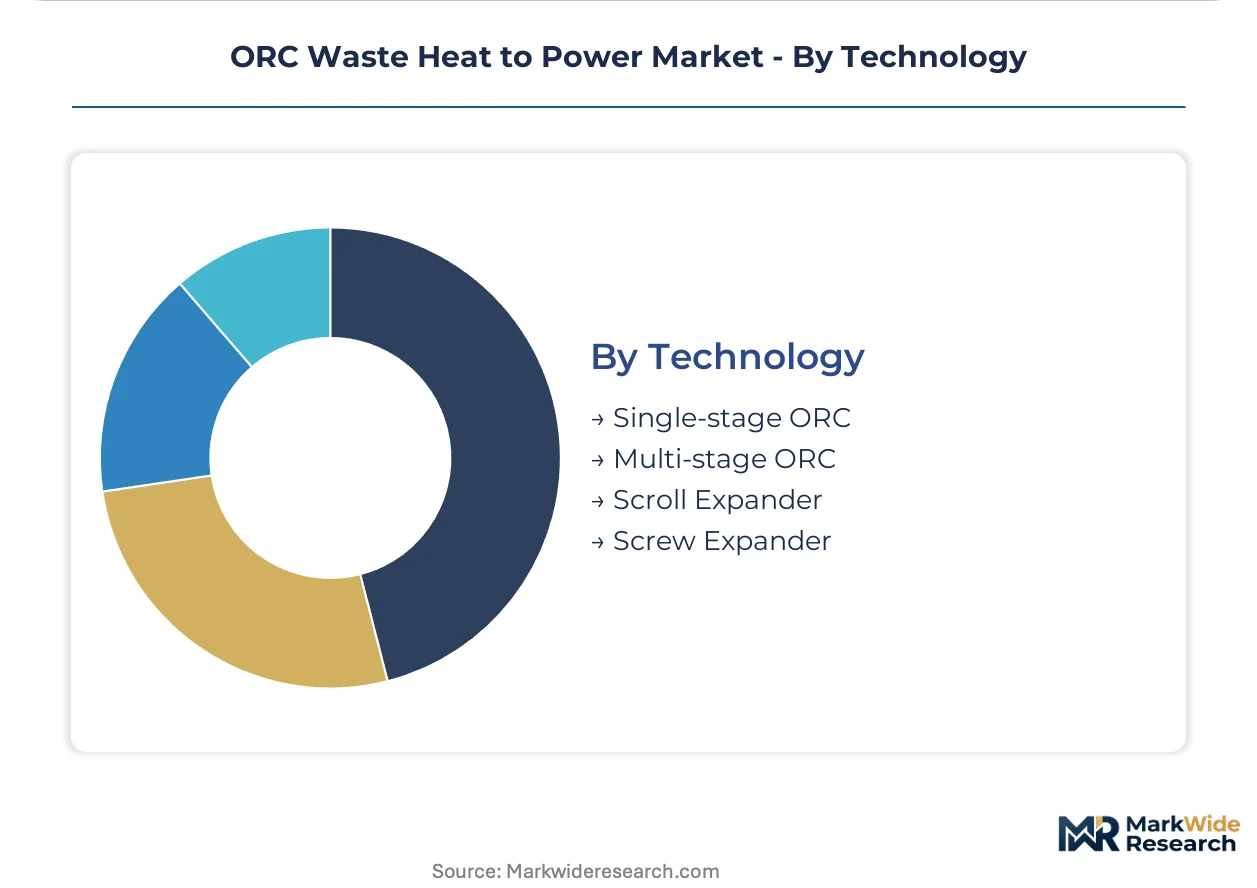
Technology:
Thermodynamic efficiency targets and maintenance accessibility drive divergent technology selections across power classes.
- Single-stage ORC:One evaporator-condenser-expander loop with proven reliability and lower capital thresholds anchors current deployment volumes. Cement and biomass applications in Germany and Italy standardize on this architecture.
- Multi-stage ORC:Cascaded working fluid loops capturing efficiency premiums in high-temperature steel and chemical applications justify added complexity and extended supplier qualification.
- Scroll Expander:Hermetic, oil-free compression technology dominates sub-500kW distributed systems through compact packaging and reduced maintenance intervals.
- Screw Expander:Two-phase flow tolerance suits geothermal brine and marine exhaust applications where working fluid quality varies.
Single-stage ORC claims the greatest installed capacity. Multi-stage ORC is climbing the fastest as high-temperature industrial decarbonization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in Bavaria anchor German ORC component manufacturing, while Italian geothermal corridors in Tuscany concentrate binary cycle engineering expertise. These raw-material and thermal resource localities shape regional competitive positioning across European waste heat recovery infrastructure.
Germany
Cement kiln retrofit demand surges under the EU Green Deal's industrial decarbonization mandates. The F-Gas Regulation's refrigerant phase-down compresses supplier qualification timelines for lower-GWP working fluids. Stuttgart and Wolfsburg automotive clusters deploy sub-megawatt ORC units to capture paint shop and foundry waste heat streams.
Italy
Binary cycle geothermal plants in Tuscany's Monte Amiata field retrofit ORC skids to boost thermal output from cooling circuits. REACH compliance requirements extend heat exchanger validation cycles for hydrofluoroolefin compatibility. Lombardy-based engineering firms dominate custom power block design for biomass and industrial applications.
United States
EPA industrial emissions guidelines drive cement and petrochemical facility retrofits across the Gulf Coast. The Inflation Reduction Act's clean energy tax credits improve project economics for waste heat recovery investments. Texas and Louisiana refinery clusters pilot ORC integration with fluid catalytic cracker off-gas recovery systems.
China
Dual carbon goals and GB standards on energy consumption intensity mandate waste heat utilization benchmarks for steel and cement producers. MIIT industrial efficiency programs accelerate domestic ORC manufacturing scale. Shandong and Hebei provincial clusters concentrate deployment of multi-stage systems in high-temperature metallurgical applications.
Japan
METI energy efficiency directives target industrial heat recovery in chemical and paper processing facilities. JIS certification requirements shape component specifications for domestic ORC installations. Osaka-Kobe manufacturing corridors deploy scroll expander systems below 500kW for consistent thermal profile operations.
ORC Waste Heat to Power Market Vendor Landscape
Global majors compete with regional champions across technology licensing and project execution capabilities. The vendor base stratifies into three tiers: integrated turbomachinery conglomerates with power island portfolios, specialized ORC engineering houses with decade-long geothermal track records, and modular equipment fabricators serving distributed industrial applications. Dominant competitive moves include strategic partnerships for working fluid supply security and geographic expansion through performance-guaranteed service contracts that transfer operational risk to vendors.
Among established engineering specialists, Turboden and Orcan Energy anchor German-Italian industrial clusters with concentrated expertise in biomass and automotive waste heat recovery. ElectraTherm occupies a position within the sub-megawatt distributed systems tier, exemplifying the scroll expander technology archetype where deployment velocity outpaces centralized alternatives. These three represent distinct strategic postures: custom-engineered power blocks, containerized rapid-deployment skids, and compact oil-free compression systems respectively.
| Leading Market Players |
|---|
| Ormat Technologies |
| Turboden |
| Mitsubishi Heavy Industries |
| Exergy International |
| Enertime |
| Orcan Energy |
| ElectraTherm |
| Siemens Energy |
| Thermax |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation mandates for lower-GWP working fluids are compressing supplier qualification timelines and forcing heat exchanger manufacturers toward stainless steel and aluminum alloys, reshaping procurement costs and vendor selection criteria across European ORC installations.
Pricing Analysis
Performance-guaranteed service agreements now dominate ORC procurement, bundling engineering, installation, and long-term maintenance into heat-rate-based contracts where payment follows verified electricity generation. Three-tier pricing structure across premium, standard, and economy levels separates custom-engineered power blocks from containerized skids and compact scroll expander units. Pricing pressure stems from standardized sub-assemblies compressing engineering margins while expanding addressable facility count. Mid-sized manufacturers without green financing support exhibit highest price sensitivity, whereas cement producers under binding decarbonization targets demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements for working fluid supply security now anchor procurement protocols, with project developers mandating qualification of multiple German and Italian chemical suppliers to mitigate input vulnerability during EMA reauthorization cycles. Component manufacturing concentrates in Germany, Italy, and China, with silica sand deposits in Bavaria anchoring domestic production and Shandong clusters feeding multi-stage system assembly. Supply chains draw from specialty refrigerant producers, precision expander fabricators, and heat exchanger specialists. Single-source vulnerability in hydrofluoroolefin production creates exposure. Distribution runs through EPC firms and OEM direct channels to industrial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ORC market sits in a technology-transition phase as multi-stage configurations displace single-stage dominance in high-temperature steel and chemical applications where efficiency premiums justify added complexity.
For Market Incumbents: Acquire working fluid thermodynamic expertise through specialist engineering hires or targeted capability purchases to address the rare skill combination demanded by R1233zd and hydrocarbon blend transitions. Cement retrofit demand under EU Green Deal mandates offers defensive volume, but heat source variability in batch-process specialty chemicals threatens capacity factors. Prioritize backward integration into heat exchanger manufacturing to control material specification timelines. For New Entrants and Emerging Players: Enter via marine waste heat recovery on Rotterdam-Hamburg container routes, where IMO efficiency regulations tighten and incumbent presence remains thin. Data center cooling integration in Frankfurt and Amsterdam represents adjacent white space with consistent thermal profiles. Pursue performance-guaranteed service contracts to transfer operational risk and accelerate adoption among capital-constrained mid-sized manufacturers. For Investors and Strategic Acquirers: The window for entry favors modular equipment fabricators with containerized rapid-deployment capabilities and established ECHA dossiers for lower-GWP refrigerant compatibility. Long-term viability hinges on positioning for carbon contract for difference schemes like Germany's H2Global that de-risk investments in hard-to-abate sectors. Watch working fluid phase-down schedules and certification reciprocity between EMA assessments and national environmental permits as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Working Fluid Portfolio Reformulation | Chemical producers in Ludwigshafen and Tarragona are reformulating around hydrofluoroolefins to meet F-Gas Regulation mandates. |
| Containerized Sub-Assembly Standardization | Pre-engineered skids compress deployment timelines from months to weeks for German automotive paint shop applications. |
| Performance-Guaranteed Service Contracts | EPC firms in the Ruhr region now offer heat-rate-based payment following verified electricity generation. |
| Geothermal Hybridization Retrofits | Binary cycle plants in Tuscany's Monte Amiata field capture additional thermal output from cooling circuits. |
| Carbon Contract for Difference Participation | Germany's H2Global mechanism provides revenue floors that de-risk ORC investments in hard-to-abate sectors. |
Methodological Framework
Multi-period observation of ORC deployment volumes, working fluid approval pathways, and supplier qualification timelines anchored the trend analysis, supplemented by interviews with EPC contractors, plant engineers at cement and steel facilities, procurement leads at automotive OEMs, and aftermarket service heads at expander manufacturers. Secondary validation drew from EIA project databases, IEA industrial efficiency reports, ECHA registration dossiers, and EU emissions trading system filings. Bottom-up facility-level capacity assessments and top-down regulatory mandate sizing were triangulated to establish market boundaries.
The input-output matrix framed capacity expansion against regulatory compliance deadlines and technology substitution curves across the projection horizon. Segmentation dimensions modeled include system architecture, application context, end-user industry, expander technology class, and regional regulatory cluster. CAGRs were derived from facility-level payback period sensitivity and working fluid transition pace. Forecast inputs incorporated EU Green Deal implementation velocity and MIIT industrial efficiency program enforcement intensity.
Revisions become necessary when working fluid phase-down schedules accelerate, EMA-ECHA certification reciprocity breaks down, or carbon border adjustment mechanism scope expands beyond current coverage. Deviation in F-Gas Regulation enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Canada Waste-To-Energy Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market