
 Germany Waste-To-Energy Market | 2026-2036
Germany Waste-To-Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Waste-To-Energy Market Foresight
Modular plant design is pivoting buyer choice across the Germany Waste-To-Energy Market, enabling municipalities to scale capacity in phased increments rather than committing to monolithic installations. EEW Energy from Waste leverages its coastal plant network to dominate maritime logistics for refuse-derived fuel intake. Martin GmbH anchors its competitive position through proprietary grate combustion systems engineered for high calorific variability. ALBA SE extends its value chain backward into waste collection and sorting, securing feedstock quality upstream of thermal treatment.
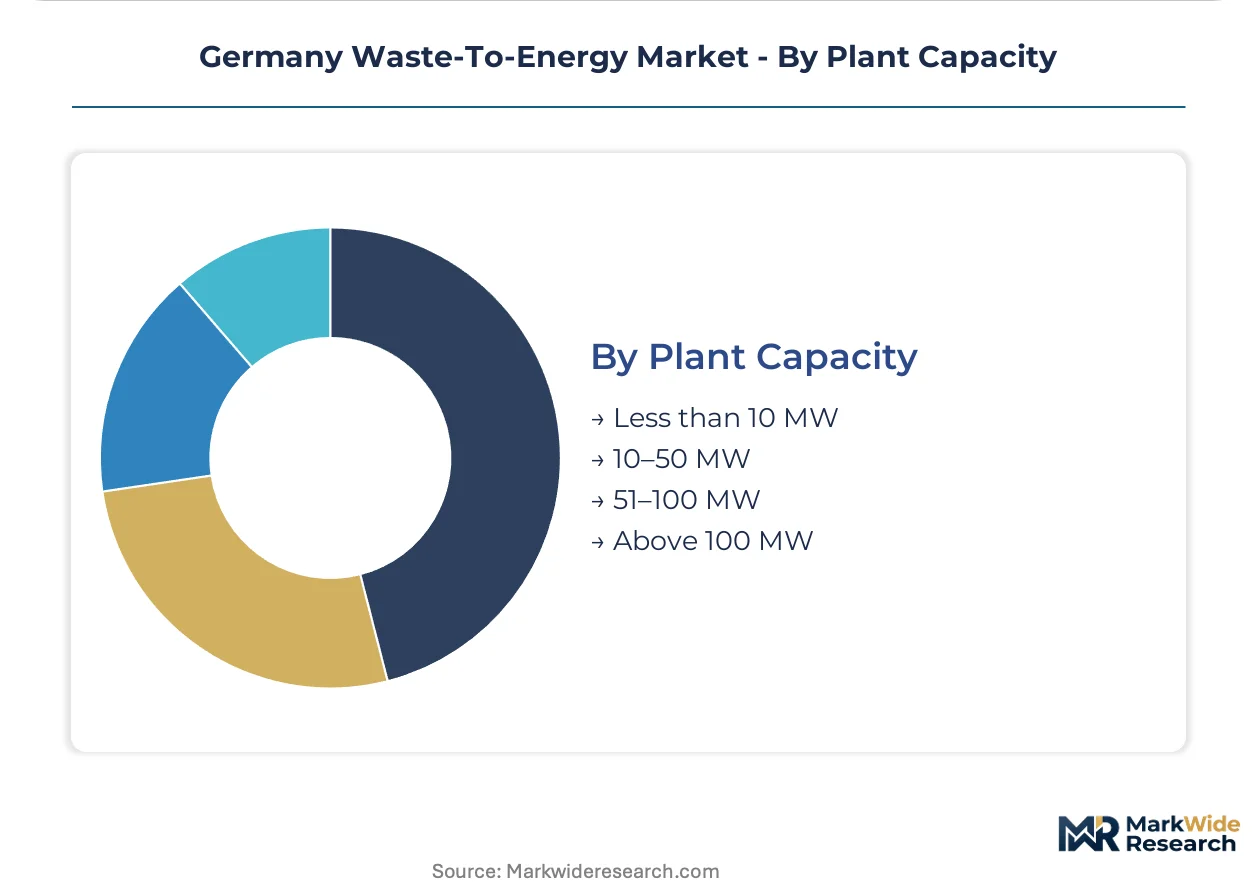
Germany Waste-To-Energy denotes thermal and biological conversion processes that transform non-recyclable waste streams into electricity, district heat, or synthetic fuels, typically operating at combustion temperatures exceeding 850 degrees Celsius to ensure complete dioxin decomposition. Incineration technology sustains the largest installed base and margin pool, while anaerobic digestion captures the fastest expansion trajectory driven by separate organic waste collection mandates. Municipal solid waste anchors feedstock volumes, though industrial waste streams command premium gate fees due to higher energy density and specialized handling requirements. Plant capacity segmentation reveals 51–100 MW facilities as the dominant configuration, balancing economies of scale with siting flexibility in densely populated Länder.
The Federal Immission Control Act (BImSchG) and EU Industrial Emissions Directive shape plant permitting, flue gas limits, and operational compliance costs across German states. KBA oversight of waste transport logistics intersects with BImSchG enforcement to create layered regulatory complexity for cross-border feedstock movements. Stakeholders must monitor proposed amendments to the German Circular Economy Act and their interplay with EU carbon border adjustments to anticipate feedstock cost trajectories and plant profitability thresholds.
Market Dynamics
Modular plant architecture is fragmenting capital deployment across German municipalities, enabling phased capacity builds that reduce single-project risk exposure and align investment cycles with waste volume trajectories.
Growth Catalysts
- EU Green Deal emission mandates:The Industrial Emissions Directive is compelling retrofits of existing facilities with advanced flue gas cleaning systems, sustaining equipment replacement demand.
- District heating network expansion:Municipal utilities in Bavaria and North Rhine-Westphalia are contracting thermal offtake from waste incineration plants, anchoring revenue visibility.
- Separate organic waste collection mandates:Biological conversion capacity is scaling to absorb diverted biowaste streams, diversifying plant feedstock portfolios.
Market Restraints
- Residual plastic contamination:Mechanical recycling advances are siphoning higher-calorific waste fractions, compressing available feedstock energy density for thermal plants.
- Cross-border KBA permitting:The Federal Motor Transport Authority's waste transport oversight intersects with BImSchG enforcement, creating procedural friction for international feedstock sourcing.
- Grid parity pressure:Solar and onshore wind LCOE declines are narrowing the competitive window for waste-derived electricity in wholesale markets.
Strategic Opportunities
- Rhine-Ruhr industrial corridor:Dense manufacturing clusters generate specialized industrial waste streams commanding premium gate fees for high-energy-density thermal treatment.
- Carbon capture retrofit integration:Post-combustion amine scrubbing at existing grate combustion facilities could qualify plants for negative emission credits under evolving EU frameworks.
- Synthetic fuel offtake contracts:Chemical producers are piloting refuse-derived syngas for e-fuel production, opening alternative revenue streams beyond power and heat.
Industry Challenges
- Grate combustion engineering specialization:The shallow talent pool for high-temperature corrosion metallurgy and combustion optimization is extending project commissioning timelines.
- Legacy SCADA integration:Digital twin deployment for predictive maintenance requires costly retrofitting of control systems installed during the 1990s plant construction wave.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Waste-To-Energy Market |
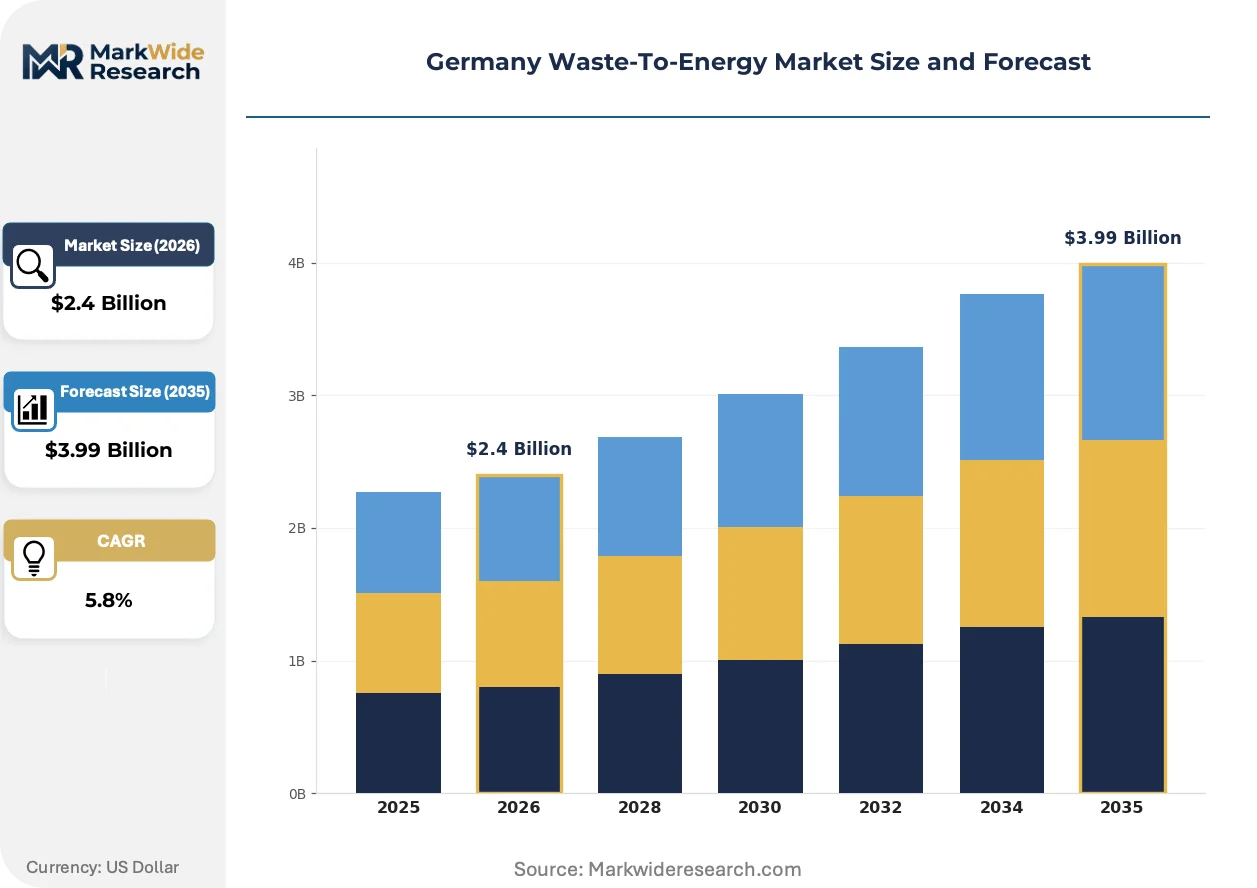
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Gasification, Pyrolysis, Anaerobic Digestion, Plasma Arc Feedstock Type: Municipal Solid Waste, Industrial Waste, Agricultural Residues, Construction Debris, Commercial Waste End User: Waste Management Companies, Energy Producers, Local Authorities, Industrial Facilities Plant Capacity: Less than 10 MW, 10–50 MW, 51–100 MW, Above 100 MW |
| Companies Covered | Martin GmbH, EEW Energy from Waste, STEAG Energy Services GmbH, MVV Energie AG, Veolia Environnement SA, ALBA SE, RWE AG, Envi Con & Plant Engineering GmbH, Tana Oy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Waste-To-Energy Market Shifts & Advancements
Technology convergence and regulatory stringency are compressing plant design cycles while opening new value capture mechanisms across thermal treatment and biological conversion pathways.
Containerized anaerobic digestion units are decentralizing organic waste processing capacity across smaller municipalities previously dependent on centralized regional facilities. Rural districts in Lower Saxony and Mecklenburg-Vorpommern are deploying these systems to reduce transport costs for biowaste collection. The shift is compressing economies of scale assumptions that historically favored large-capital installations.
The EU Carbon Border Adjustment Mechanism is reshaping feedstock cost calculations for plants importing refuse-derived fuel from non-EU sources. German operators are reassessing supply contracts with Eastern European and Turkish waste traders to anticipate embedded carbon tariffs. This regulatory friction is accelerating domestic feedstock sourcing investments and circular economy partnerships with industrial waste generators.
Performance contracting is displacing traditional EPC handoffs in new plant development, with operators retaining long-term O&M accountability and energy yield guarantees. Municipal buyers in Hamburg and Berlin are favoring this model to transfer operational risk to technology providers. The shift is visible most acutely in 51–100 MW greenfield projects where financing institutions demand assured cash flow visibility.
Germany Waste-To-Energy Market Segmentation
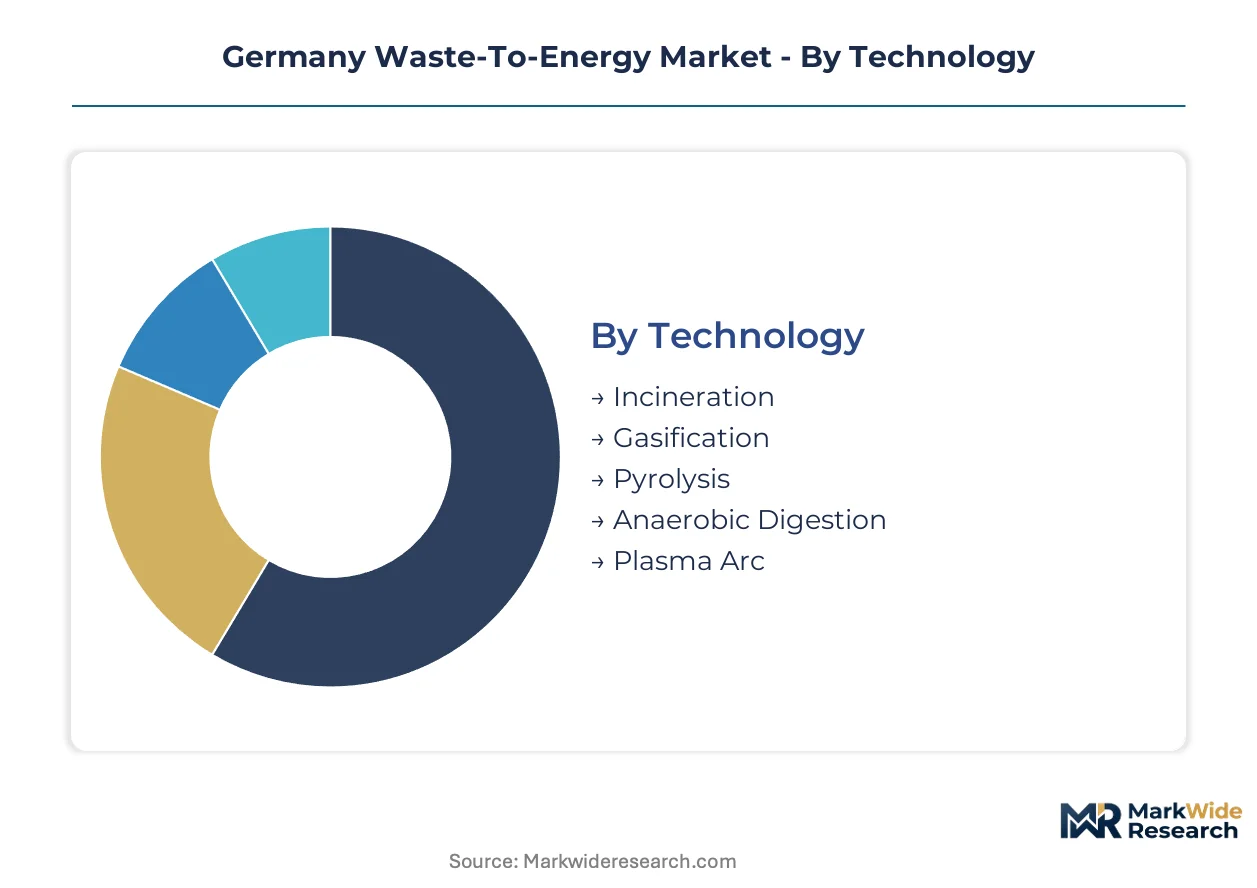
Technology choice determines capital intensity, permitting complexity, and revenue stack composition across German waste-to-energy installations. Feedstock access and district heating integration potential further differentiate investment profiles within each segment.
Technology:
Plant operators select thermal and biological pathways based on feedstock calorific variability, emission compliance costs, and heat offtake contract availability.
- Incineration:Grate combustion systems process heterogeneous municipal solid waste streams at temperatures exceeding 850 degrees Celsius, ensuring complete dioxin decomposition. Bavarian and North Rhine-Westphalian utilities anchor thermal offtake demand from these facilities, securing revenue visibility through long-term district heating contracts.
- Anaerobic Digestion:Biological conversion of separately collected organic waste generates biogas for grid injection or combined heat and power generation. Lower Saxony and Mecklenburg-Vorpommern municipalities are deploying containerized units to reduce rural biowaste transport costs, accelerating capacity expansion outside metropolitan clusters.
- Gasification:Partial oxidation at controlled oxygen levels produces syngas for chemical synthesis or power generation, suited for homogeneous industrial waste streams with consistent composition.
- Pyrolysis:Thermal decomposition in oxygen-absent environments yields char, oil, and gas fractions, finding niche application for plastic-rich waste fractions unsuitable for mechanical recycling.
- Plasma Arc:Ultra-high-temperature ionized gas treatment vitrifies inorganic residues into slag, commanding premium gate fees for hazardous industrial waste requiring complete destruction.
Volume sits with Incineration; growth tilts toward Anaerobic Digestion.
Feedstock Type:
Energy density, contamination levels, and regulatory classification determine gate fee structures and plant technology matching across German states.
- Municipal Solid Waste:Mixed household refuse streams with residual calorific value after source separation dominate feedstock volumes. Hamburg and Berlin metropolitan clusters concentrate collection infrastructure, though mechanical recycling advances are compressing available energy density.
- Industrial Waste:Manufacturing byproducts and off-specification materials command premium gate fees due to higher energy density and specialized handling requirements. Rhine-Ruhr corridor facilities secure long-term contracts with chemical and automotive producers seeking compliant disposal pathways.
- Agricultural Residues:Crop straw, manure, and food processing waste feed anaerobic digestion capacity in rural Bavaria and Baden-Württemberg, supporting farm-scale biogas installations.
- Construction Debris:Wood fractions and mixed demolition waste require pre-treatment to remove inert materials before thermal processing, limiting viable plant locations to major urban reconstruction zones.
- Commercial Waste:Retail, hospitality, and office sector refuse exhibits seasonal variability and higher packaging content, demanding flexible grate combustion systems or biological pre-sorting.
Revenue concentration favors Industrial Waste; volume expansion tracks Municipal Solid Waste diversion from landfills.
End User:
Contracting structures and risk allocation preferences distinguish buyer categories across German procurement frameworks.
- Waste Management Companies:Integrated operators control collection, sorting, and thermal treatment assets, optimizing gate fee margins through vertical coordination. EEW Energy from Waste and ALBA SE leverage coastal logistics networks and upstream sorting capacity to secure feedstock quality.
- Energy Producers:Municipal utilities and independent power producers prioritize heat offtake contracts and grid connection capacity over waste collection integration, focusing on operational efficiency and emission performance.
- Local Authorities:City and district governments favor performance contracting models that transfer construction and operational risk to technology providers, visible in Hamburg and Berlin greenfield developments.
- Industrial Facilities:Manufacturing sites with captive waste streams invest in on-site treatment capacity to manage disposal costs and regulatory compliance, particularly in chemical and automotive sectors.
Contract volume concentrates with Waste Management Companies; procurement innovation emerges from Local Authorities.
Plant Capacity:
Scale economics intersect with siting constraints and financing availability across German Länder planning regimes.
- 51–100 MW:Mid-scale facilities balance thermal efficiency with siting flexibility in densely populated states, capturing dominant installed capacity share. These configurations optimize district heating integration while maintaining manageable permitting timelines under BImSchG oversight.
- Above 100 MW:Large-scale installations achieve lowest unit capital costs but face extended environmental impact assessments and concentrated local opposition. Coastal locations with maritime feedstock logistics, such as EEW's Rostock and Helmstedt facilities, justify scale through refuse-derived fuel import capacity.
- 10–50 MW:Smaller urban installations serve single municipalities or industrial parks, limiting economies of scale but reducing transmission infrastructure requirements.
- Less than 10 MW:Containerized and modular systems address rural biowaste processing needs in Lower Saxony and Mecklenburg-Vorpommern, enabling phased capacity deployment without centralized facility dependence.
Installed base centers on 51–100 MW; deployment momentum shifts toward modular sub-10 MW configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters along the Rhine-Ruhr industrial corridor and North Sea ports, while thermal offtake demand concentrates in metropolitan heating networks across southern and western states.
North Rhine-Westphalia
District heating utilities in Cologne, Düsseldorf, and Dortmund anchor thermal offtake contracts from waste incineration plants. The BImSchG imposes stringent flue gas emission limits that drive retrofit investments at aging facilities. The Rhine-Ruhr corridor generates specialized industrial waste streams from chemical and steel producers, commanding premium gate fees for high-energy-density thermal treatment.
Bavaria
Munich and Nuremberg municipal utilities expand procurement of waste-derived heat for district heating networks serving dense urban cores. Separate organic waste collection mandates under the German Circular Economy Act accelerate anaerobic digestion capacity deployment across rural districts. Agricultural residues from dairy and crop operations feed farm-scale biogas installations in Upper and Lower Bavaria.
Lower Saxony
Containerized anaerobic digestion units decentralize organic waste processing across rural municipalities previously dependent on centralized regional facilities. KBA oversight of waste transport logistics intersects with state environmental regulations to shape feedstock sourcing economics. The Hannover-Brunswick-Wolfsburg triangle concentrates industrial waste generation from automotive manufacturing supply chains.
Hamburg
Performance contracting models for new plant development transfer construction and operational risk to technology providers, visible in recent greenfield project procurement. Maritime logistics capabilities at the Port of Hamburg enable refuse-derived fuel import for coastal incineration facilities. The metropolitan cluster generates concentrated municipal solid waste volumes with residual calorific value after source separation.
Baden-Württemberg
Stuttgart and Karlsruhe industrial parks generate manufacturing byproducts requiring compliant thermal disposal pathways under EU Industrial Emissions Directive oversight. Precision engineering and automotive supply chains produce specialized waste fractions with consistent composition suited for advanced thermal treatment. The state maintains stringent siting regulations that favor modular plant configurations over large-scale centralized installations.
Germany Waste-To-Energy Market Competitive Landscape
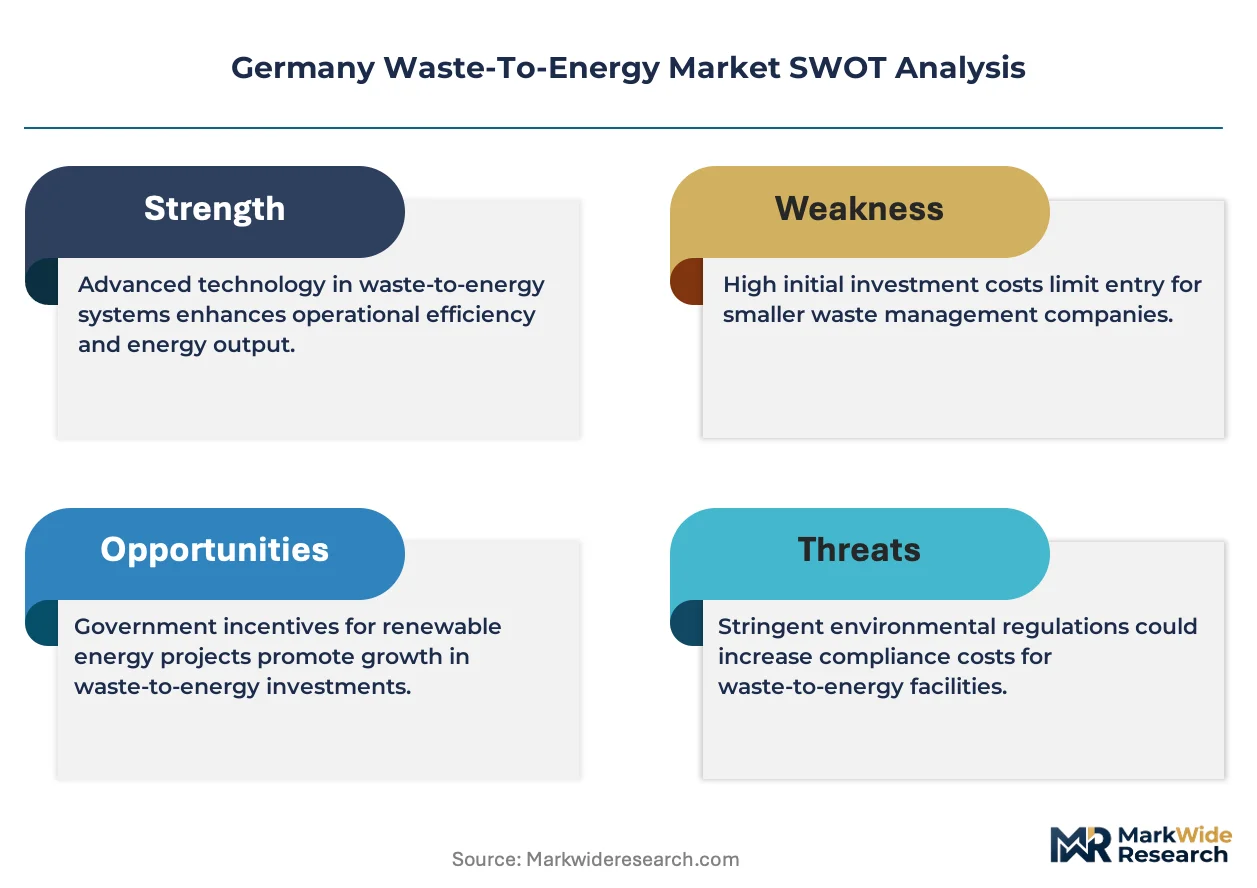
Diversified conglomerates compete with focused pure-play specialists across technology supply and plant operation segments. Market structure tilts toward consolidation among integrated waste management operators controlling collection-through-treatment value chains. Three archetypes dominate: coastal logistics specialists leveraging maritime feedstock access, combustion technology licensors with proprietary grate systems, and vertically integrated municipal service providers. Competitive intensity centers on feedstock security through long-term collection contracts and district heating offtake negotiations.
Within the technology licensor tier, Martin GmbH and EEW Energy from Waste exemplify divergent strategic positioning. Martin GmbH anchors proprietary grate combustion engineering for high-calorific variability feedstocks. EEW Energy from Waste occupies a coastal logistics-specialist position through maritime refuse-derived fuel intake networks. ALBA SE represents backward integration into waste collection and sorting, securing upstream feedstock quality control. These three entities illustrate how technology specialization, geographic positioning, and value chain depth create defensible competitive positions under BImSchG regulatory stringency.
| Leading Market Players |
|---|
| Martin GmbH |
| EEW Energy from Waste |
| STEAG Energy Services GmbH |
| MVV Energie AG |
| Veolia Environnement SA |
| ALBA SE |
| RWE AG |
| Envi Con & Plant Engineering GmbH |
| Tana Oy |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up waste management specialists have consolidated collection infrastructure across German metropolitan clusters, tightening feedstock access and reinforcing gate fee discipline through backward integration into sorting and logistics. This ownership pattern concentrates supply control while amplifying pricing power against municipal buyers seeking long-term thermal offtake security.
Pricing Analysis
Margin tightening in industrial waste processing reflects mechanical recycling advances siphoning higher-calorific fractions from available feedstock pools. Contract-based long-term offtake structures dominate, with price differentiation hinging on waste energy density and BImSchG compliance tier. Cost-down pressure on municipal solid waste gate fees accelerates as solar and onshore wind LCOE declines narrow wholesale electricity competitiveness. Energy producers exhibit highest price sensitivity due to grid parity pressures, while industrial facilities accepting hazardous waste streams demonstrate lowest sensitivity given regulatory disposal constraints.
Supply Chain Analysis
German domestic-content mandates under the Circular Economy Act are reshaping sourcing patterns for refuse-derived fuel, compressing cross-border feedstock volumes from Eastern European and Turkish traders. Equipment supply concentrates in Germany, Denmark, and Austria for combustion grates and flue gas cleaning systems. Raw material dependencies include high-temperature corrosion-resistant alloys, ceramic filter media, and ammonia for SCR systems. Single-source vulnerability sits with specialized grate metallurgy suppliers. Distribution runs through maritime terminals at North Sea ports and rail-connected inland hubs serving Bavarian and North Rhine-Westphalian plant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where feedstock security represents the decisive competitive lever, with operators pursuing upstream control over collection and sorting infrastructure to lock in quality and volume.
For Market Incumbents: Anticipate mechanical recycling capacity expansion siphoning calorific waste fractions by securing long-term industrial waste contracts in the Rhine-Ruhr corridor. Retrofit existing grate combustion facilities with carbon capture readiness to qualify for negative emission credits under evolving EU frameworks. Prioritize district heating offtake negotiations with municipal utilities in Hamburg and Berlin to anchor revenue visibility against wholesale electricity margin compression. For New Entrants and Emerging Players: The premium-to-economy tier gap in containerized anaerobic digestion creates entry space for modular system providers targeting rural municipalities in Lower Saxony and Mecklenburg-Vorpommern. White-space opportunities concentrate in sub-10 MW biowaste processing capacity outside metropolitan clusters. Pursue performance contracting models that transfer operational risk to technology providers, aligning with municipal procurement preferences in Berlin and Hamburg greenfield developments. For Investors and Strategic Acquirers: Distressed-cycle entries favor coastal logistics specialists with maritime refuse-derived fuel import capabilities in North Sea port locations. Long-term viability over the analysis window rests on feedstock contract duration and district heating integration depth. Monitor EU Carbon Border Adjustment Mechanism implementation as the critical inflection signal for domestic sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Integration | Post-combustion amine scrubbing qualifies plants for negative emission credits under EU frameworks. |
| Backward Integration into Collection | Upstream control over waste sorting secures feedstock quality and compresses gate fee volatility. |
| District Heating Contract Expansion | Munich and Cologne municipal utilities anchor thermal offtake visibility under BImSchG compliance. |
| Modular Anaerobic Digestion Deployment | Containerized units reduce rural biowaste transport costs across Lower Saxony districts. |
| Performance Contracting Model Adoption | Risk transfer to technology providers aligns with Hamburg and Berlin municipal procurement frameworks. |
Research Methodology
Multi-period observation of plant capacity utilization, gate fee trajectories, and district heating contract volumes anchored the trend analysis, supplemented by interviews with plant operations directors, municipal utility procurement officers, KBA regulatory specialists, and flue gas equipment engineers. Secondary validation drew from BImSchG enforcement records, EU Industrial Emissions Directive compliance filings, German Federal Statistical Office waste generation data, and EPC contractor project disclosures. Bottom-up plant-level capacity aggregation and top-down macroeconomic demand modeling provided triangulation checks.
Segment-weighting across technology pathways, feedstock classifications, and plant capacity tiers informed volume and value distribution. The analytical framework modeled incineration, anaerobic digestion, gasification, and pyrolysis segments alongside municipal solid waste, industrial waste, and agricultural residue feedstocks through the projection horizon. CAGRs derived from capacity expansion pipelines, retrofit investment cycles, and regulatory compliance cost trajectories. Forecast inputs incorporated EU Green Deal emission mandate timelines and separate organic waste collection mandate implementation rates.
Inputs from federal environmental agency databases and state-level district heating network operators were available through the study window; gaps in real-time industrial waste contract pricing introduce uncertainty bands around gate fee projections. Forecasts reflect documented assumptions regarding BImSchG amendment trajectories and carbon border adjustment implementation scope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Canada Waste-To-Energy Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
North America Waste to Energy Market