
 Waste to Diesel Market | 2026-2036
Waste to Diesel Market Size, Share, and Industry Trends Forecast 2026-2036
Waste to Diesel Market Analysis
North American capacity build-out is rewriting competitive dynamics in waste-to-diesel processing. Clean Harbors leverages its hazardous waste collection network to secure proprietary feedstock streams. Veolia anchors European operations through integrated municipal contracts and refinery partnerships. Waste Management competes by controlling dense urban waste volumes across major U.S. metropolitan corridors.
Waste to diesel converts non-recyclable organic and synthetic feedstocks into hydrocarbon fuel meeting ASTM D975 or EN 590 specifications through thermochemical or catalytic pathways. Hydrothermal liquefaction dominates commercial scale-up due to lower pre-treatment intensity versus pyrolysis, though gasification retains cost advantages for mixed municipal solid waste streams. The feedstock segment splits sharply: used cooking oil and animal fat command premium pricing for renewable diesel offtake, while plastic waste conversion remains technically immature with concentrated margin pools in pilot-scale facilities. End-user demand tilts toward marine and industrial heating applications where emissions compliance obligations are most stringent.
EPA renewable fuel standards and the EU Renewable Energy Directive create enforceable demand floors that shape product certification requirements and market access conditions. California's LCFS and similar state-level programs in Oregon and Washington impose carbon intensity scoring that rewards lower-emission conversion pathways. Stakeholders must monitor feedstock traceability rulemakings and blending mandate expansions as the primary variables determining offtake security and facility economics.
Market Dynamics
Marine shipping decarbonization mandates are compressing the adoption timeline for waste-derived bunker fuels, pulling capital toward hydrothermal liquefaction capacity and certified offtake corridors in Rotterdam and Singapore.
Growth Catalysts
- EU Renewable Energy Directive blending thresholds:Certified renewable diesel pathways secure preferential market access and price premiums across European port infrastructure.
- Hydrothermal liquefaction scale-up:Lower pre-treatment intensity versus pyrolysis accelerates commercial deployment for mixed organic feedstocks.
- California LCFS carbon intensity scoring:State-level programs reward lower-emission conversion pathways with transferable credit value.
Market Restraints
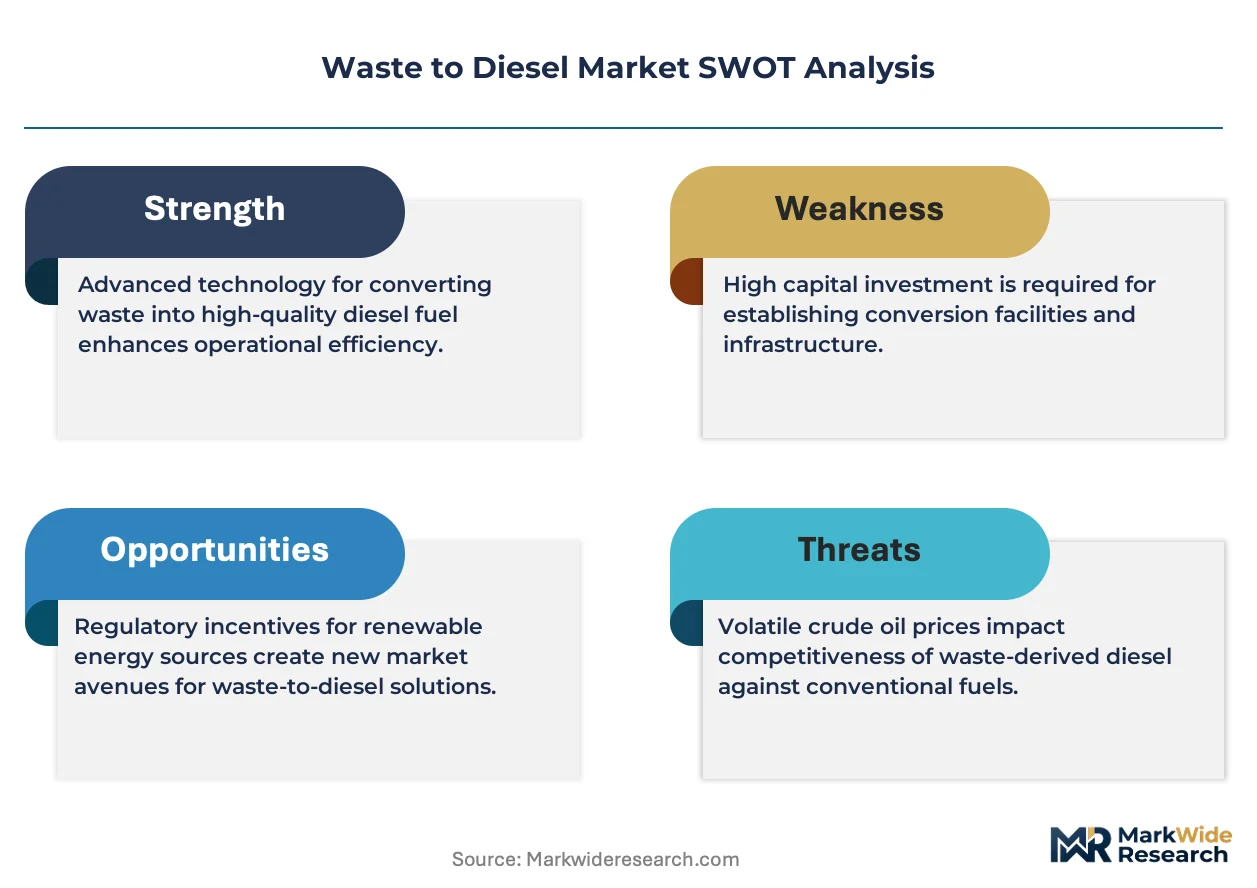
- Feedstock supply concentration:Used cooking oil and animal fat availability clusters in specific agricultural processing regions, creating procurement bottlenecks.
- Plastic waste conversion immaturity:Technical limitations in catalytic depolymerization constrain margin pools to pilot-scale facilities.
- ASTM D975 certification timelines:Extended fuel qualification protocols delay commercial offtake agreements for novel conversion pathways.
Strategic Opportunities
- Southeast Asian port infrastructure:Singapore and emerging hubs in Indonesia lack established waste-to-fuel supply chains, creating first-mover positioning.
- Industrial heating fuel switching:Cement and steel producers face emissions compliance obligations that waste-derived diesel can satisfy.
- Feedstock traceability rulemakings:Anticipated EU expansion of certified pathway requirements will reward early investment in chain-of-custody systems.
Industry Challenges
- Catalytic process engineering talent:Scarce expertise in hydrothermal reactor design and catalyst regeneration limits facility ramp rates.
- Refinery integration complexity:Co-processing waste-derived intermediates with conventional streams requires retrofitting hydrotreater configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste to Diesel Market |
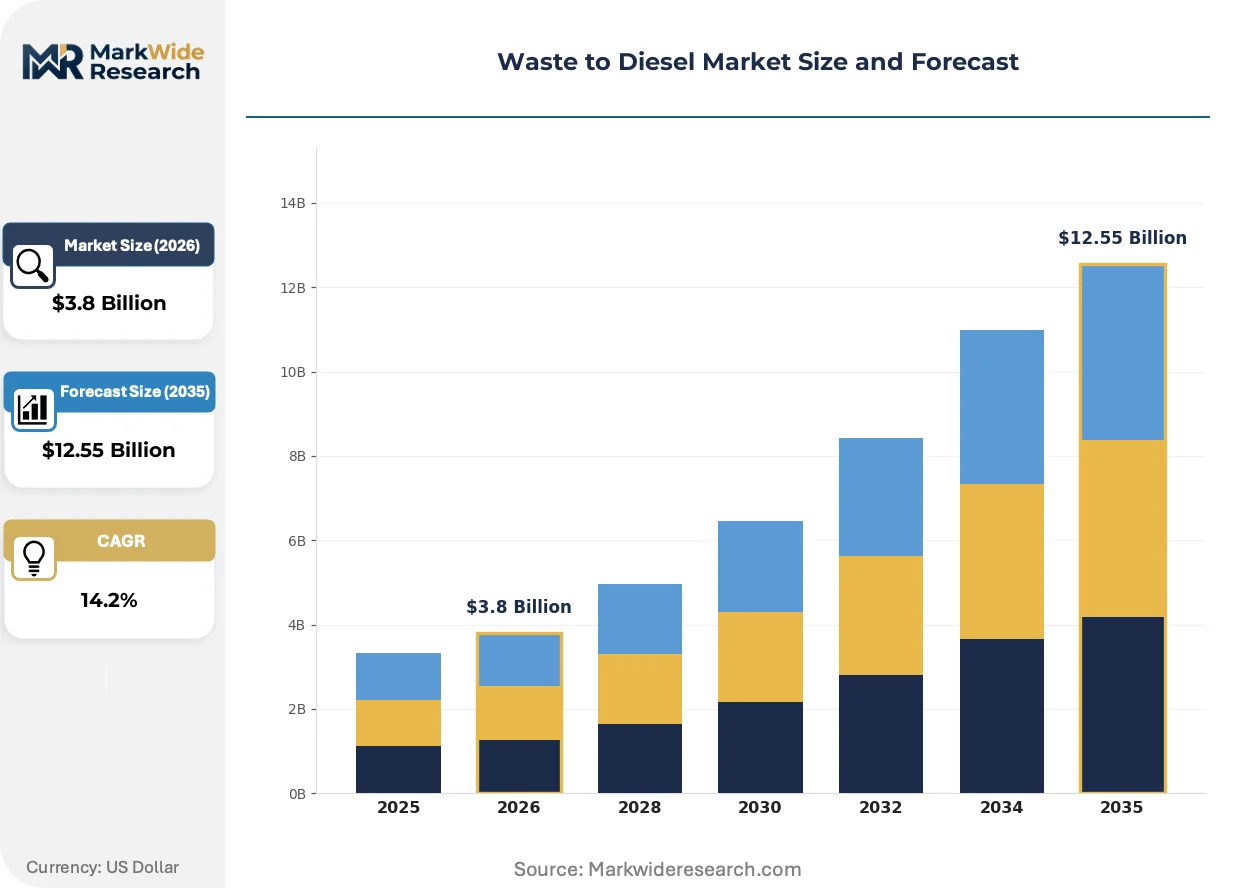
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Used Cooking Oil, Animal Fat, Municipal Solid Waste, Plastic Waste Conversion Technology: Hydrothermal Liquefaction, Pyrolysis, Gasification, Catalytic Cracking End User: Transportation, Industrial Heating, Power Generation, Marine Distribution Channel: Wholesale, Direct Sales, Online Retail, Partnerships |
| Companies Covered | Clean Harbors, Keppel Seghers, Veolia, Eco Energy International, Circularity Fuels, Waste Management, Covanta, All Power Labs, Republic Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste to Diesel Market Emerging Trajectories
Conversion technology maturation and regulatory precision are reshaping how waste streams monetize as fuel products, with certification systems now acting as gatekeepers to premium offtake markets.
Hydrothermal liquefaction with integrated hydrotreating is rendering obsolete standalone pyrolysis systems for wet organic feedstocks. Marine fuel suppliers in Rotterdam and Singapore are adopting these integrated configurations to meet IMO 2030 carbon intensity targets. The technology shift compresses capital deployment timelines by eliminating drying stages that previously dominated energy balances.
California's LCFS and parallel programs in Oregon and Washington impose granular carbon intensity scoring that differentiates conversion pathway economics. Refiners must now document feedstock origins and process emissions to capture full credit value. This regulatory architecture most affects municipal waste processors seeking to upgrade landfill gas and refuse-derived fuel into certified diesel substitutes.
Long-term offtake contracting is displacing spot market transactions as the dominant procurement mode for marine bunkering. Shipping operators in Germany and the Netherlands are locking in decade-long supply agreements to secure compliance pathway certainty. This behavioral shift concentrates buyer power among container lines and bulk carriers with sufficient creditworthiness to underwrite project finance.
Waste to Diesel Market Segmentation
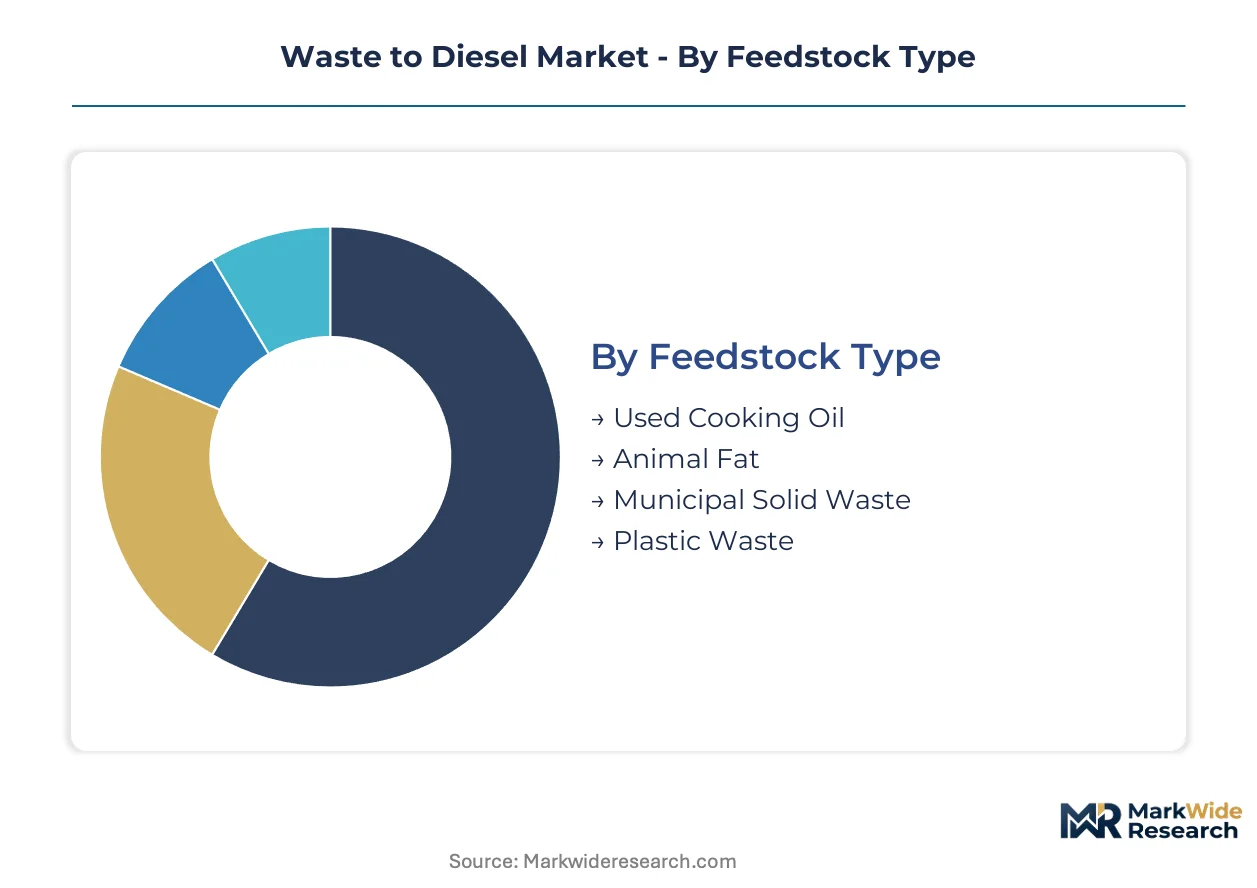
Feedstock chemistry and conversion pathway economics determine facility margin structures in waste-to-diesel processing. Technology selection locks in capital intensity, energy balance, and product slate specifications that shape offtake negotiations. End-use certification requirements and distribution logistics complete the value chain configuration.
Feedstock Type:
Mature pathways command premium pricing while emerging feedstocks face technical scale-up barriers.
- Used Cooking Oil:Low free fatty acid content enables direct hydrotreating to meet ASTM D975 specifications. Demand concentrates in California and Oregon where LCFS carbon intensity scoring rewards the lowest-emission pathway. Collection infrastructure in Germany and the Netherlands supports Rotterdam's marine bunkering corridor.
- Animal Fat:Tallow and poultry fat deliver consistent lipid profiles suitable for renewable diesel co-processing. Rendering facilities in the US Midwest and Brazil's agricultural processing regions anchor supply concentration. EPA renewable fuel standards create enforceable demand floors for this certified pathway.
- Municipal Solid Waste:Mixed organic fraction requires extensive pre-sorting and contaminant removal before conversion. Gasification retains cost advantages for this heterogeneous stream.
- Plastic Waste:Catalytic depolymerization remains technically immature with limited commercial deployment. Pilot-scale facilities in Singapore and Japan are testing pyrolysis-to-diesel configurations.
Used Cooking Oil handles the majority of throughput; Plastic Waste is gaining share fastest despite technical constraints.
Conversion Technology:
Cost tier separation between integrated and standalone systems is reshaping capital deployment priorities.
- Hydrothermal Liquefaction:Wet organic feedstocks process without energy-intensive drying stages. Biocrude intermediate requires integrated hydrotreating to meet finished fuel specifications. Rotterdam and Singapore marine suppliers are adopting this configuration to satisfy IMO 2030 carbon intensity targets.
- Pyrolysis:Thermal decomposition of dry feedstocks produces synthetic crude requiring extensive upgrading. Standalone systems face competitive pressure from integrated liquefaction-hydrotreating trains.
- Gasification:Partial oxidation of mixed municipal streams generates syngas for Fischer-Tropsch synthesis. Higher capital intensity is offset by feedstock flexibility.
- Catalytic Cracking:Fluidized bed systems process plastic waste and heavy hydrocarbon residues. Catalyst regeneration cycles limit continuous operation economics.
Hydrothermal Liquefaction captures the largest installed base; Catalytic Cracking shows the steepest expansion trajectory in plastic waste applications.
End User:
Application-specific certification timelines create divergent customer acquisition economics.
- Marine:IMO 2030 carbon intensity mandates are compressing adoption timelines for waste-derived bunker fuels. Container lines and bulk carriers in Germany and Singapore are executing decade-long offtake agreements to secure compliance certainty.
- Industrial Heating:Cement and steel producers face emissions compliance obligations that waste-derived diesel satisfies. Refinery partnerships in the Netherlands enable direct pipeline delivery to industrial clusters.
- Transportation:Heavy-duty trucking fleets in California access LCFS credit value for renewable diesel consumption. Blending infrastructure limits direct fuel substitution rates.
- Power Generation:Diesel-fired peaking plants represent marginal demand with limited growth trajectory. Grid decarbonization policies favor renewable electricity over liquid fuel switching.
Marine dominates contract value; Industrial Heating is expanding most quickly on compliance-driven fuel switching.
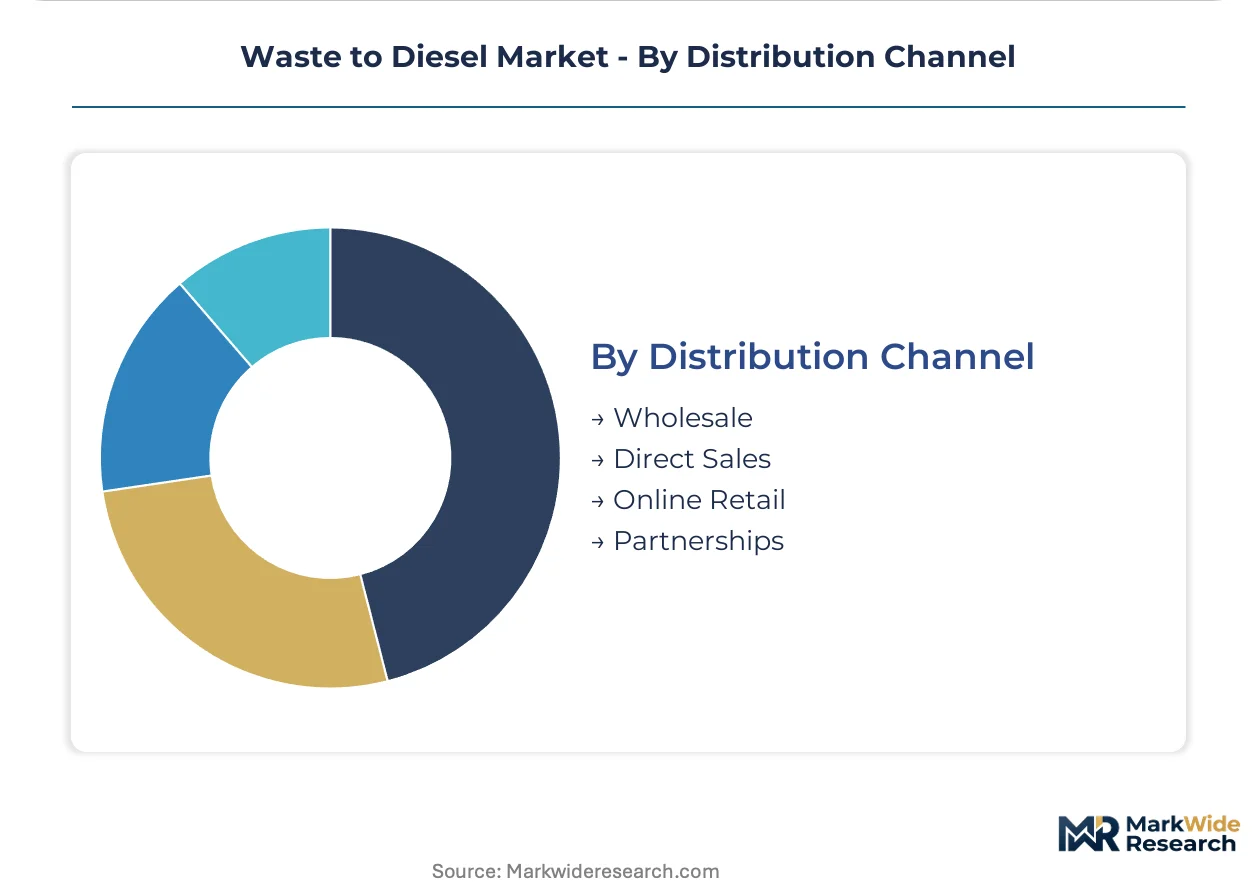
Distribution Channel:
Volume scale and customer creditworthiness determine channel selection for project finance underwriting.
- Wholesale:Marine fuel suppliers and industrial distributors aggregate demand across multiple end-users. Rotterdam and Singapore port infrastructure supports large-scale storage and bunkering logistics.
- Direct Sales:Long-term offtake agreements with container lines and cement producers displace spot market transactions. Creditworthy buyers underwrite facility construction debt.
- Partnerships:Refinery co-processing arrangements leverage existing hydrotreater capacity for biocrude upgrading. Integrated configurations reduce standalone capital requirements.
- Online Retail:Limited applicability for bulk fuel commodities with certification and custody documentation requirements. Niche presence in small-volume renewable diesel sampling.
Wholesale channels move the highest volumes; Direct Sales are climbing the fastest as long-term contracting displaces spot procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedstock collection infrastructure clusters near major port complexes and agricultural processing belts, with regulatory mandates in specific jurisdictions determining where conversion capacity receives financing. Germany, the United States, Singapore, the Netherlands, and Japan concentrate both supply security and offtake contracting.
Germany
Marine bunkering demand at Hamburg and Bremen ports drives waste-derived diesel procurement. The EU Renewable Energy Directive mandates binding renewable fuel quotas that elevate certified pathway premiums. The Ruhr industrial corridor hosts refinery co-processing partnerships upgrading biocrude intermediates.
United States
Midwest rendering facilities supply tallow and poultry fat to renewable diesel hydrotreaters. EPA renewable fuel standards enforce annual blending obligations that secure offtake floors. California's LCFS carbon intensity scoring rewards low-emission pathways, concentrating project finance in the Sacramento Valley and Los Angeles basin.
Singapore
IMO 2030 compliance deadlines accelerate container line contracting for certified bunker fuels. The Maritime and Port Authority of Singapore incentivizes alternative fuel infrastructure through port dues adjustments. Tuas Port development integrates waste-to-fuel storage with automated bunkering logistics.
Netherlands
Rotterdam's status as Europe's largest bunkering port attracts hydrothermal liquefaction capacity investments. The National Climate Agreement imposes sectoral emission ceilings that industrial heating users must satisfy. The Port of Rotterdam Authority coordinates pipeline delivery networks linking conversion facilities to cement and steel clusters.
Japan
Osaka Bay industrial zones seek emissions-compliant heating fuels for steel and chemical operations. METI's Green Transformation program allocates capital subsidies to waste-to-chemicals demonstration projects. Pilot-scale plastic waste pyrolysis facilities in Kawasaki test catalytic depolymerization configurations.
Waste to Diesel Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The waste-to-diesel sector structures around three player categories: hazardous waste collectors with captive feedstock streams, municipal service operators leveraging dense urban volumes, and pure-play conversion technology developers. Consolidation pressures favor entities controlling both collection logistics and offtake certification. Dominant competitive moves include refinery partnership formations and hydrothermal liquefaction capacity expansion.
Among integrated waste management operators, Clean Harbors, Veolia, and Waste Management exemplify distinct strategic postures. Clean Harbors occupies a position anchored in North American hazardous waste collection density. Veolia represents the European municipal contract model with embedded refinery relationships. Waste Management sits within the scale-driven tier commanding metropolitan waste volumes across major U.S. corridors.
| Leading Market Players |
|---|
| Clean Harbors |
| Keppel Seghers |
| Veolia |
| Eco Energy International |
| Circularity Fuels |
| Waste Management |
| Covanta |
| All Power Labs |
| Republic Services |
| Others |
Supply Flow & Price Mechanics
Rotterdam's hydrothermal liquefaction capacity concentration anchors European pricing power for certified marine bunkers, with biocrude intermediate premiums compressing margins for standalone pyrolysis operators lacking integrated hydrotreating.
Pricing Analysis
The EU Renewable Energy Directive dictates the pricing tier structure across European waste-to-diesel corridors, separating certified renewable diesel pathways from uncertified intermediates. ASTM D975 and EN 590 compliance grades command substantial premiums over non-specification fuel oils. Cost compression in pyrolysis-derived synthetic crude is intensifying because hydrothermal liquefaction-hydrotreating integration eliminates energy-intensive drying stages. Container lines and bulk carriers with decade-long offtake agreements exhibit the lowest price sensitivity, while industrial heating buyers without marine compliance obligations remain most responsive to spot market fluctuations.
Supply Chain Analysis
Extended payment terms from marine fuel suppliers are restructuring working capital requirements for hydrothermal liquefaction developers, compressing cash conversion cycles. Feedstock procurement draws from Germany, the Netherlands, and the US Midwest, where rendering facilities and used cooking oil collection networks cluster. Catalyst regeneration chemicals, hydrotreater hydrogen supply, and specialized reactor vessels constitute critical input dependencies. Single-source vulnerability in hydrothermal reactor engineering talent limits facility ramp rates. Distribution runs through Rotterdam and Singapore port storage terminals before bunkering logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waste-to-diesel processing sits in early-cycle expansion, with IMO 2030 carbon intensity mandates accelerating marine contracting velocity beyond current conversion capacity installation rates.
For Market Incumbents: Harden feedstock supply security through backward integration into rendering facility partnerships and municipal collection contracts. Lock in hydrothermal liquefaction capacity additions in Singapore and Rotterdam before catalyst engineering talent scarcity worsens. Defend against emerging pure-play technology developers by accelerating ASTM D975 certification timelines for novel conversion pathways. For New Entrants and Emerging Players: Pursue white-space positioning in Southeast Asian port infrastructure, where Singapore's Tuas Port development lacks established waste-to-fuel supply chains. Target industrial heating applications in Japan's Osaka Bay steel and chemical corridors, where METI Green Transformation subsidies offset facility capital intensity. Lead with refinery co-processing partnerships rather than standalone hydrotreater investments to reduce financing thresholds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors conversion technology developers with demonstrated hydrothermal liquefaction-hydrotreating integration and active ASTM D975 certification protocols. Long-term viability hinges on chain-of-custody system deployment ahead of anticipated EU feedstock traceability rulemaking expansions. Monitor marine offtake contracting velocity as the primary inflection signal, with decade-long agreement execution rates indicating project finance appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrothermal Liquefaction Capacity Expansion | Rotterdam and Singapore marine suppliers adopt integrated configurations to satisfy IMO 2030 carbon intensity targets. |
| Refinery Co-Processing Partnership | Biocrude upgrading through existing hydrotreater capacity reduces standalone capital requirements for conversion developers. |
| Feedstock Traceability System Investment | EU Renewable Energy Directive pathway expansions reward early chain-of-custody infrastructure deployment. |
| Long-Term Offtake Agreement Execution | Container lines in Germany and Singapore lock in decade-long supply contracts to secure compliance certainty. |
| Catalytic Process Engineering Talent Acquisition | Scarce hydrothermal reactor design expertise limits facility ramp rates and constrains competitive entry. |
Methodological Framework
The analysis maps feedstock type, conversion technology, and end-user application segments, each validated through conversion facility operators, marine fuel procurement officers, refinery co-processing managers, and catalyst engineering specialists. Primary interviews with hydrothermal liquefaction developers and secondary validation through EPA renewable fuel standard filings, EU Renewable Energy Directive implementation reports, and IMO marine fuel quality data establish segment boundaries. Customs records tracking used cooking oil and animal fat trade flows complement SEC filings from integrated waste management operators. Bottom-up capacity installation counts and top-down regulatory mandate sizing triangulate market dimensions.
Assumptions hold EU and California low-carbon fuel standards at current stringency levels while varying marine adoption timelines and plastic waste conversion maturation rates across sensitivity scenarios. The analytical framework models feedstock chemistry, conversion pathway economics, and end-use certification requirements throughout the forecast period. CAGRs derive from facility commissioning schedules, offtake contract execution patterns, and carbon intensity scoring evolution. Hydrotreater retrofit requirements and catalyst regeneration cycle economics constitute industry-specific forecast inputs.
Sensitivities concentrate around IMO regulatory enforcement timing, EU feedstock traceability rulemaking scope, and hydrothermal liquefaction scale-up success rates. Forecasts reflect documented assumptions on marine decarbonization compliance deadlines and certified pathway premium sustainability. Macroeconomic contraction affecting container line creditworthiness, regulatory relaxation of blending mandates, or breakthrough plastic waste catalytic depolymerization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Brazil Waste to Energy Market