
 North America Vascular Stents Market | 2026-2036
North America Vascular Stents Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vascular Stents Market Intelligence
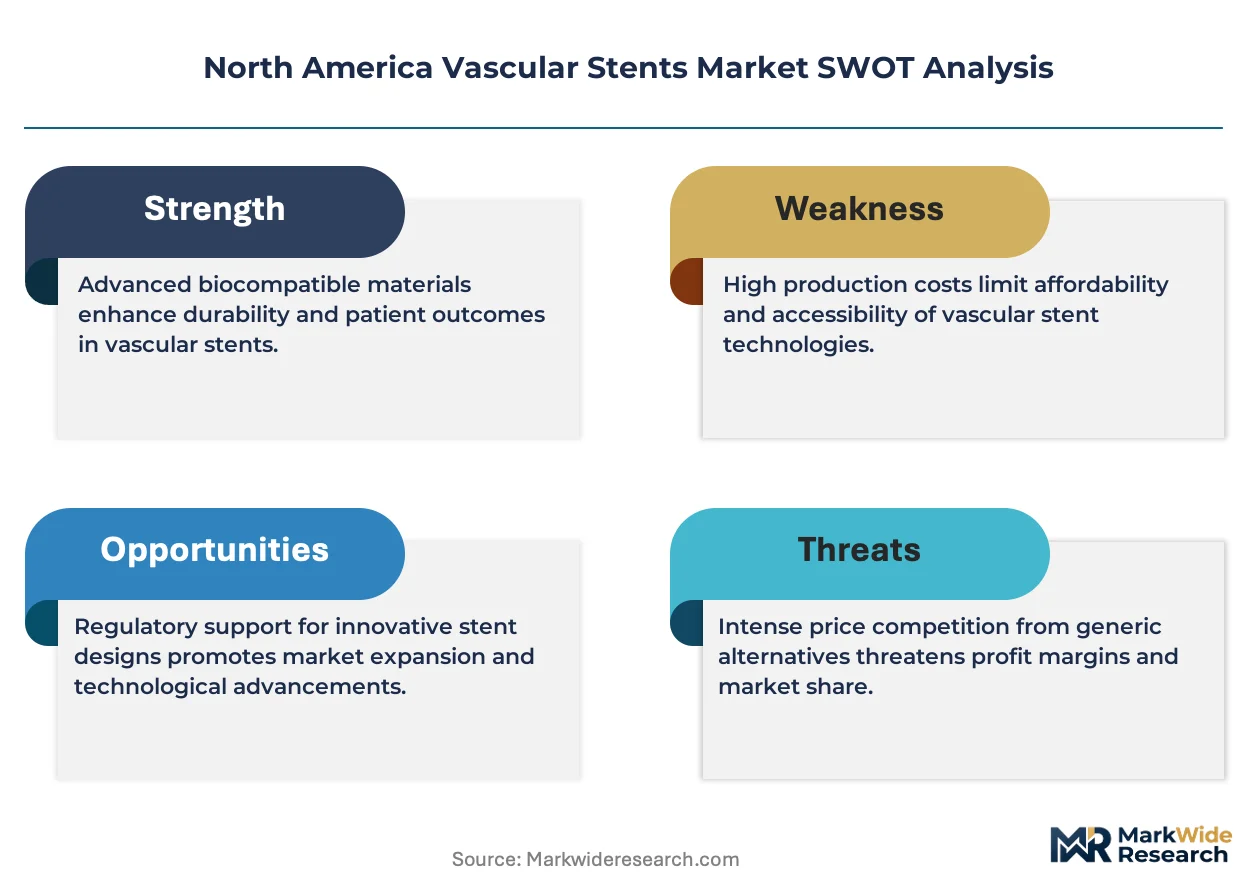
Asset-light leasing models for catheterization lab equipment is tilting competitive dynamics toward vendors with balance-sheet flexibility. Medtronic leverages captive financing arms to lock in multi-year hospital commitments. Boston Scientific Corporation anchors its position through dedicated coronary training centers that deepen physician loyalty. Abbott Laboratories differentiates via vertically integrated supply chains spanning cobalt-chromium alloy sourcing to final sterile packaging.
North America vascular stents are tubular scaffolds typically fabricated from cobalt-chromium, platinum-iridium, or absorbable polymers, deployed percutaneously to restore luminal patency in stenosed or occluded vessels. Their primary purpose is to prevent acute vessel closure and reduce restenosis following balloon angioplasty. Drug-eluting stents command the dominant revenue share due to sustained antiproliferative coating premiums and established clinical outcomes data. Biodegradable polymer platforms represent the fastest-expanding material category as physicians seek to eliminate permanent foreign body retention. Coronary artery disease applications absorb the largest procedure volume, though peripheral artery disease segments are gaining traction as below-the-knee intervention techniques mature.
FDA premarket notification and PMA pathways govern US commercialization, while Health Canada and COFEPRIS regulate Canadian and Mexican market access respectively, collectively elevating bench-to-bedside evidence thresholds. The FDA's evolving guidance on absorbable scaffold durability endpoints is compressing development timelines for polymer-based platforms. Stakeholders must monitor Medicare reimbursement coding shifts for peripheral interventions, as ambulatory payment classification updates will determine site-of-care migration speed and capital deployment priorities.
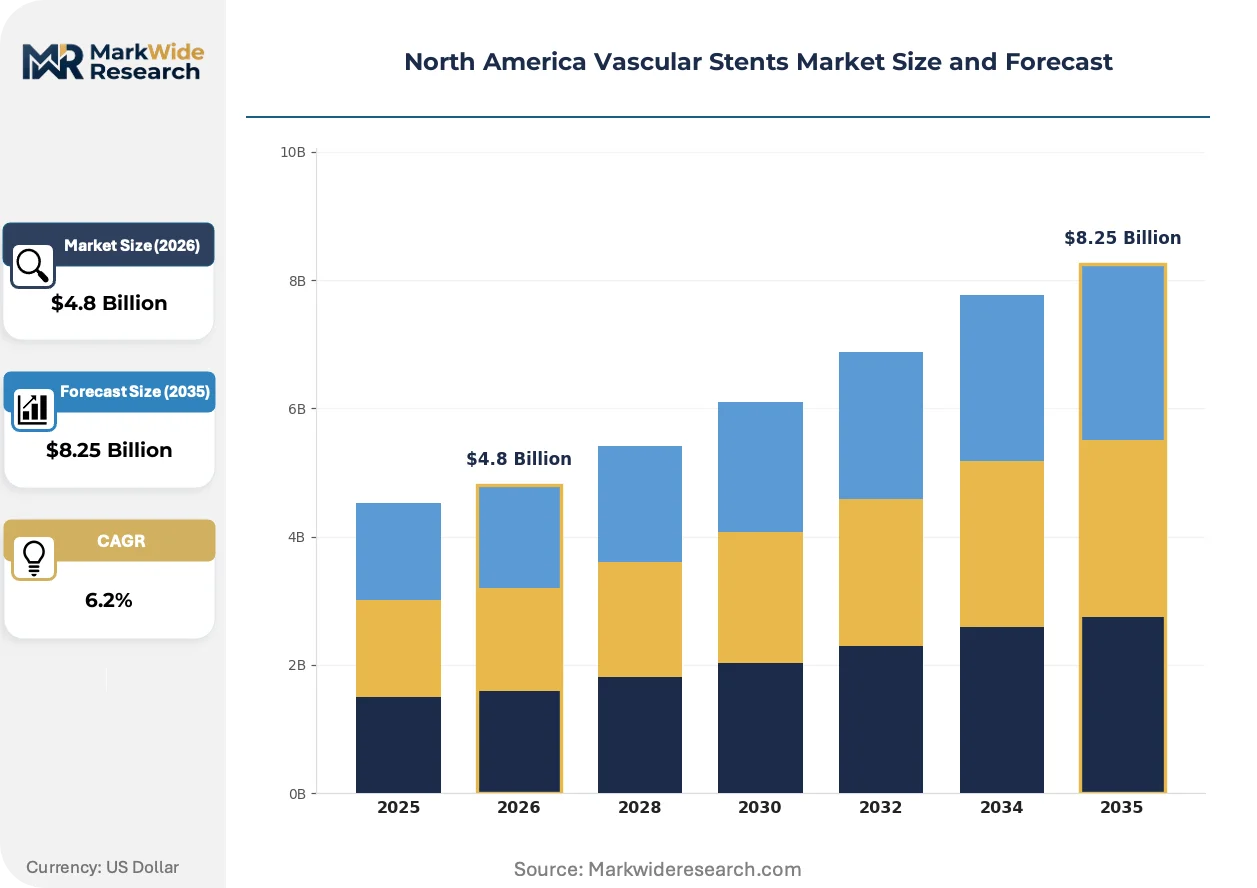
Market Dynamics
Site-of-care migration from inpatient to ambulatory settings is compressing capital deployment timelines and forcing vendors to reconfigure service models around outpatient procedural economics.
Growth Catalysts
- Ambulatory Payment Classification updates:Medicare reimbursement shifts favor outpatient stent placement, accelerating volume migration to ambulatory surgical centers across the United States.
- Biodegradable polymer platforms:Physician preference for absorbable scaffolds eliminating permanent foreign body retention is expanding addressable indications.
- Below-the-knee intervention maturation:Peripheral artery disease techniques are unlocking new procedure volumes in limb salvage applications.
Market Restraints
- PMA pathway duration:FDA premarket approval timelines for novel absorbable scaffolds compress competitive windows for new entrants.
- Cobalt-chromium supply concentration:Specialty alloy sourcing depends on limited North American and European smelter capacity.
- Balloon angioplasty substitution:Drug-coated balloon alternatives threaten bare-metal stent volumes in femoropopliteal segments.
Strategic Opportunities
- Mexico regulatory alignment:COFEPRIS pathway harmonization with FDA standards reduces dual-registration costs for cross-border commercialization.
- Integrated delivery network consolidation:IDN purchasing centralization creates multi-year sole-source contract opportunities for financing-capable vendors.
- Physician training center networks:Dedicated coronary simulation facilities deepen procedural loyalty and device utilization rates.
Industry Challenges
- Absorbable scaffold durability endpoints:FDA evolving guidance on polymer degradation benchmarks demands extended clinical follow-up timelines.
- Catheterization lab capex cycles:Hospital capital allocation constraints delay equipment refresh schedules and stent system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vascular Stents Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon-Expandable Stents, Self-Expanding Stents, Covered Stents, Drug-Eluting Stents End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Cardiac Care Units Material: Metal Stents, Polymer Stents, Biodegradable Stents, Hybrid Stents Application: Coronary Artery Disease, Peripheral Artery Disease, Carotid Artery Disease, Chronic Venous Insufficiency |
| Companies Covered | Abbott Laboratories, Medtronic, Boston Scientific Corporation, B. Braun Melsungen AG, Terumo Corporation, BIOTRONIK, MicroPort Scientific Corporation, Cook Medical, BD, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vascular Stents Market Strategic Shifts & Innovations
Material science advances and reimbursement coding evolution are restructuring competitive advantage around evidence generation speed and supply chain control rather than incremental product iteration.
Drug-eluting stent platforms are migrating from durable polymer coatings to absorbable polymer matrices that eliminate chronic inflammation risks. Academic medical centers in the United States are piloting these scaffolds in complex bifurcation lesions ahead of broader community hospital adoption. The technology is migrating from niche investigational use toward mainstream coronary revascularization as two-year outcome data mature.
FDA guidance on absorbable scaffold durability endpoints is compressing development timelines by clarifying degradation benchmark requirements. Manufacturers must now demonstrate complete polymer resorption within 24-36 months with matched vessel healing metrics. Canadian and Mexican regulators are observing these evidentiary standards through Health Canada and COFEPRIS alignment initiatives.
Hospital procurement teams are consolidating vendor relationships around multi-year capital-plus-consumable bundles that subsume catheterization lab equipment leasing. Integrated delivery networks in the United States are displacing traditional device-only purchasing with full-service partnerships spanning training, inventory management, and outcomes reporting. This consolidation concentrates purchasing power among IDNs operating across multiple states.
North America Vascular Stents Market Segmentation
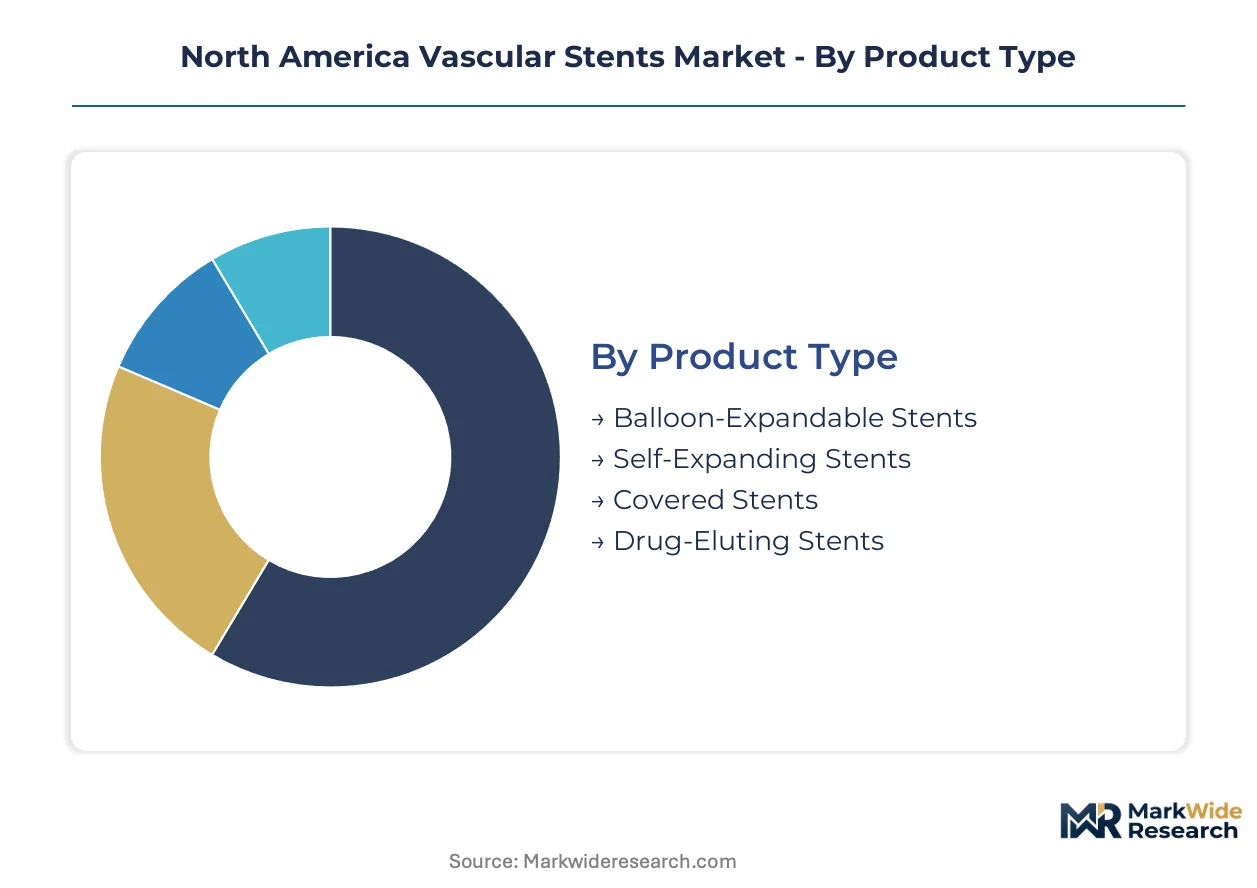
Vascular stent purchasing patterns diverge sharply across clinical settings and material platforms. Procurement teams structure vendor contracts around procedure volume thresholds and site-of-care economics.
Product Type:
After-sales service intensity varies dramatically across stent deployment mechanisms, with complex delivery systems demanding dedicated field engineering support.
- Drug-Eluting Stents:Polymer matrices release antiproliferative agents to inhibit neointimal hyperplasia. United States hospitals anchor demand as Medicare reimbursement codes favor DES over bare-metal alternatives for coronary revascularization.
- Balloon-Expandable Stents:Crimped onto delivery balloons and expanded via controlled inflation pressure. Ambulatory surgical centers in Texas and Florida are expanding volumes as outpatient PCI economics improve under revised payment classifications.
- Self-Expanding Stents:Nickel-titanium alloys deploy via thermal shape-memory recovery in peripheral vessels.
- Covered Stents:Expanded polytetrafluoroethylene barriers contain vessel wall disruption in aneurysmal or ruptured segments.
By volume, Drug-Eluting Stents lead. By expansion trajectory, Balloon-Expandable Stents in ambulatory settings are climbing the fastest.
End User:
Capital equipment bundling requirements reshape vendor relationships differently across acute care versus outpatient facilities.
- Hospitals:Integrated catheterization labs with on-site cardiac surgery backup handle complex multivessel disease. United States teaching hospitals in Boston and Cleveland drive adoption of absorbable scaffold platforms through investigator-initiated trials.
- Ambulatory Surgical Centers:Freestanding facilities optimize throughput for elective diagnostic catheterization and single-vessel intervention. Medicare ASC payment rate updates are accelerating site migration from hospital outpatient departments in California and Arizona.
- Specialty Clinics:Office-based labs concentrate on peripheral vascular access and dialysis circuit maintenance.
- Cardiac Care Units:Emergency revascularization capabilities demand 24-hour stent inventory and immediate device availability protocols.
By procedure count, Hospitals dominate. By volume growth rate, Ambulatory Surgical Centers are gaining share fastest.
Material:
Supply chain concentration for specialty alloys creates procurement risk profiles that differ across metallic versus absorbable platforms.
- Metal Stents:Cobalt-chromium and platinum-iridium alloys provide radial strength and radiopacity for precise deployment. Canadian procurement through Health Canada-regimated distributors concentrates in Ontario and Quebec hospital networks.
- Biodegradable Stents:Poly-L-lactic acid scaffolds resorb completely within 24-36 months, eliminating chronic foreign body response. Mexican academic medical centers in Mexico City are participating in multinational registries tracking long-term vessel healing outcomes.
- Polymer Stents:Durable synthetic matrices serve as drug reservoirs without metallic structural elements.
- Hybrid Stents:Composite constructions combine biodegradable polymers with absorbable metallic elements.
By installed base, Metal Stents lead. By technology transition momentum, Biodegradable Stents show the steepest adoption curve.
Application:
Anatomical site complexity determines reimbursement coding and therefore capital allocation priorities across coronary versus peripheral indications.
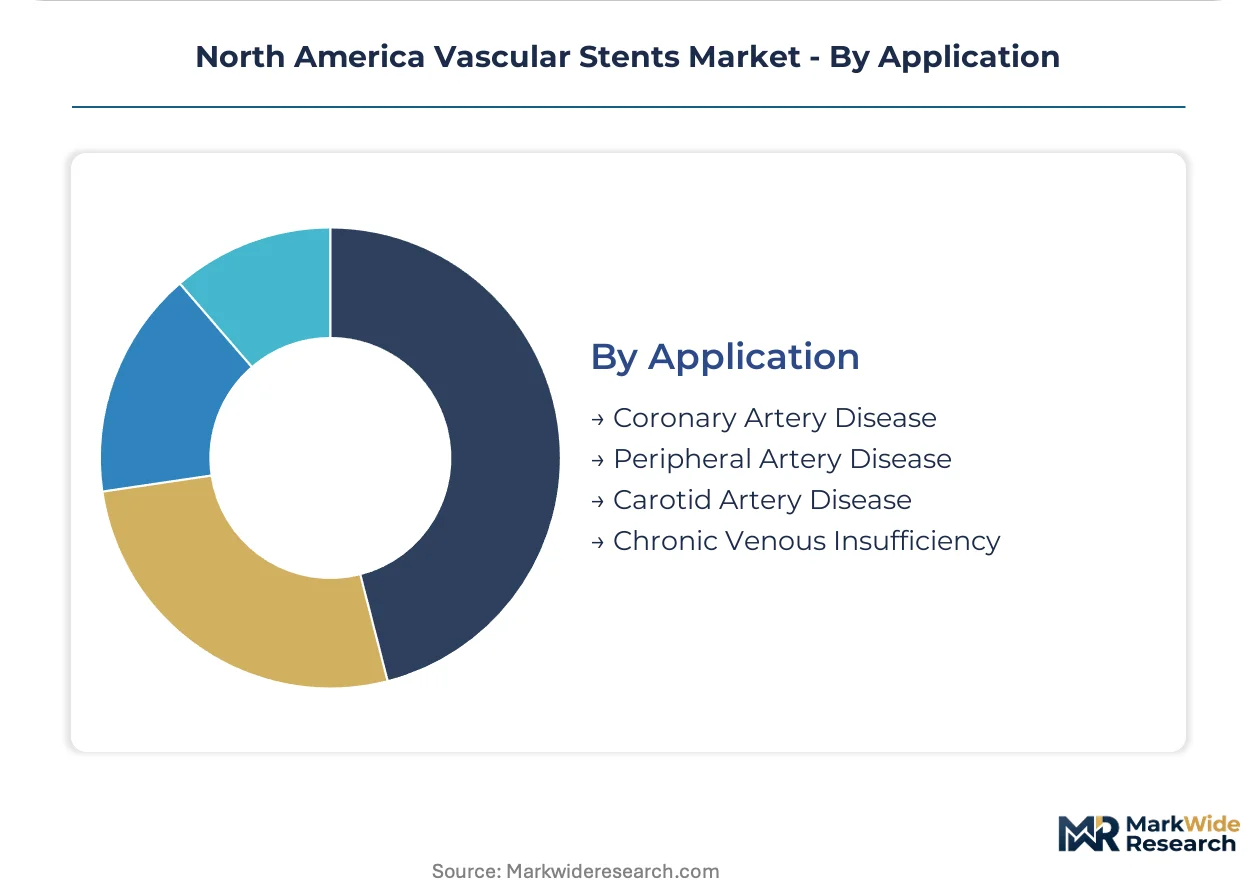
- Coronary Artery Disease:Percutaneous coronary intervention with stent placement restores flow in epicardial vessel stenosis. United States community hospitals in the Southeast are expanding elective PCI programs as transfer agreements with tertiary centers mature.
- Peripheral Artery Disease:Femoropopliteal and infrapopliteal revascularization addresses lifestyle-limiting claudication and critical limb ischemia. Below-the-knee techniques are unlocking new procedure volumes in Texas border regions with high diabetes prevalence.
- Carotid Artery Disease:Embolic protection devices accompany stent deployment to prevent cerebral ischemic events.
- Chronic Venous Insufficiency:Venous stenting addresses iliac vein compression and post-thrombotic obstruction.
By annual procedures, Coronary Artery Disease leads. By expansion pace, Peripheral Artery Disease interventions are accelerating most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement shifts are accelerating site-of-care migration across North America, with ambulatory payment classification updates redistributing procedural volumes toward outpatient facilities in all three countries.
United States
Integrated delivery networks in Texas and Florida are consolidating stent purchasing around multi-year capital-plus-consumable bundles. FDA premarket approval pathways for absorbable scaffolds demand extended clinical follow-up timelines that favor established manufacturers. The Cleveland Clinic and Mayo Clinic anchor investigator-initiated trials for biodegradable polymer platforms.
Canada
Ontario and Quebec hospital networks concentrate procurement through Health Canada-regulated distributors with stringent MDR alignment requirements. Provincial health technology assessment bodies evaluate drug-eluting stent cost-effectiveness before formulary inclusion. Toronto academic medical centers participate in multinational registries tracking long-term vessel healing outcomes.
Mexico
COFEPRIS regulatory pathway harmonization with FDA standards reduces dual-registration costs for cross-border commercialization. Mexico City academic medical centers are enrolling patients in absorbable scaffold durability studies. Northern border states with high diabetes prevalence are expanding below-the-knee intervention volumes.
Southeast United States
Community hospitals in Georgia and North Carolina are expanding elective PCI programs as transfer agreements with tertiary centers mature. Medicare ASC payment rate updates are accelerating volume migration from hospital outpatient departments. Charlotte and Atlanta metropolitan areas concentrate ambulatory surgical center development.
North America Vascular Stents Market Key Industry Players
On the supply side, the industry is consolidating around vendors with balance-sheet flexibility to support asset-light leasing models for catheterization lab equipment. Three strategic archetypes dominate: diversified medtech conglomerates with captive financing arms, dedicated cardiovascular specialists with physician training networks, and vertically integrated manufacturers controlling specialty alloy sourcing. Competitive dynamics center on multi-year sole-source contract capture and outcomes-based partnership structures with integrated delivery networks.
Within the diversified conglomerate tier, Medtronic and Abbott Laboratories anchor positions through financing capability and supply chain control respectively. Boston Scientific Corporation exemplifies the cardiovascular specialist archetype with dedicated coronary training centers that deepen physician loyalty. These three entities represent the premium-tier competitive vector where evidence generation speed and service model reconfiguration determine contract outcomes.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Terumo Corporation |
| BIOTRONIK |
| MicroPort Scientific Corporation |
| Cook Medical |
| BD |
| Others |
Cost & Logistics Intelligence
Cobalt-chromium smelter capacity concentrates in Germany and the United States, tethering margin pools to vendors with captive alloy sourcing or long-term offtake agreements with specialty metals refiners. Hospital procurement consolidation around integrated delivery networks extracts pricing concessions that flow upstream to compress converter margins.
Pricing Analysis
Certification level (FDA PMA versus 510(k) clearance) creates the primary spread between premium drug-eluting platforms and commodity bare-metal alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical evidence depth and after-sales service bundling. Cost compression in bare-metal segments is intensifying because drug-coated balloon substitution threatens femoropopliteal volumes. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with investigator-initiated trial programs show lowest.
Supply Chain Analysis
Export-control regimes governing nickel-titanium shape-memory alloys and cobalt-chromium master alloys limit flows from specialty metals refiners in Germany, Austria, and the United States. Polymer resin feedstocks for absorbable scaffolds draw from pharmaceutical-grade suppliers in Switzerland and Japan. Single-source vulnerability concentrates in platinum-iridium marker band fabrication. Distribution runs through GPO-contracted distributors with consignment inventory at hospital catheterization labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated delivery network consolidation across Texas, Florida, and California has shifted bargaining power toward buyers capable of extracting multi-year sole-source commitments. This fragmentation of vendor access demands strategic repositioning across three stakeholder archetypes.
For Market Incumbents: Pre-empt absorbable scaffold durability endpoint guidance from FDA by accelerating 36-month vessel healing data collection ahead of competitor submissions. Lock in cobalt-chromium supply through backward integration into specialty alloy recycling or smelter joint ventures. Drug-coated balloon substitution in peripheral segments represents the priority threat requiring defensive indication expansion.
For New Entrants and Emerging Players: Mexico City and Monterrey academic medical centers offer underpenetrated entry points for absorbable scaffold trials with lower patient enrollment costs than United States sites. Target COFEPRIS-FDA harmonization pathways to reduce dual-registration capital requirements. Go-to-market leverage rests on physician training center partnerships that build procedural loyalty before device commercialization.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cardiovascular device platforms lacking financing arms to compete for IDN capital-plus-consumable bundles. Long-term viability over a 5-10 year window hinges on absorbable polymer platform durability data maturation. Watch Medicare ASC payment classification updates as volume migration inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA submission for absorbable scaffolds secures premium reimbursement coding ahead of 510(k) competitors. |
| Hospital System Partnership | Multi-year capital-plus-consumable bundles with Texas IDNs displace device-only purchasing relationships. |
| Physician Training Center Network | Dedicated coronary simulation facilities in Florida deepen procedural loyalty and utilization rates. |
| Reimbursement Strategy | Medicare ASC payment rate alignment accelerates site-of-care migration to outpatient settings. |
| Software Companion Development | Imaging integration platforms for absorbable scaffold deployment guidance differentiate complex lesion capability. |
Research Approach
The analysis maps drug-eluting stents, balloon-expandable platforms, self-expanding peripheral devices, and absorbable scaffolds, each validated through interventional cardiologists, catheterization lab directors, GPO contracts managers, and biomedical engineers. Primary interviews with hospital purchasing committees and ASC administrators combined with secondary validation against FDA PMA filings, CMS Medicare reimbursement databases, Health Canada device licenses, and COFEPRIS registration records. Bottom-up procedure volume estimates triangulated with top-down vendor revenue disclosures.
Assumptions held fixed include Medicare reimbursement coding stability and cobalt-chromium alloy supply continuity; varied assumptions encompass absorbable scaffold durability endpoint guidance evolution and ASC payment classification update timing. Segmentation dimensions modeled span product type, material platform, application anatomy, and site-of-care setting across the analysis window. CAGRs derived from logistic diffusion curves for technology substitution and procedure volume elasticity to reimbursement shifts. Forecast inputs incorporated IDN consolidation pace and physician training center network expansion rates.
Practitioners should monitor FDA guidance document publication timelines and Medicare ASC fee schedule final rules for early signals of forecast revision. Cross-checking against CMS Hospital Outpatient Prospective Payment System claims data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Global Vascular Embolization Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Vascular Screening Market