
 Global Gastric Balloons Market | 2026-2036
Global Gastric Balloons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastric Balloons Market Foresight
Silicone elastomer is repositioning legacy polyurethane in gastric balloon construction, improving biocompatibility and deflation resistance across extended dwell times. Boston Scientific leverages vertically integrated silicone sourcing to control raw material quality. Apollo Endosurgery differentiates through specialized endoscopic delivery systems. Allurion Technologies competes with swallowable capsule formats that eliminate procedural sedation requirements.
Gastric balloons are fluid- or gas-filled intragastric space-occupying devices, typically 400-700 mL in fill volume, designed to induce early satiety through mechanoreceptor stimulation of the gastric fundus. These devices serve primary commercial purpose in non-surgical obesity intervention for patients with BMI 30-40 kg/m² who fail lifestyle modification. Intragastric balloon systems dominate current volume due to established reimbursement codes and physician familiarity, while balloon capsule formats represent the fastest-expanding segment as ambulatory surgical centers seek sedation-free workflows. Adjustable balloon systems concentrate margin pools through premium pricing tied to personalized fill-volume titration protocols.
The FDA regulates gastric balloons as Class II medical devices under 510(k) premarket notification pathways, while the EU Medical Device Regulation mandates notified body conformity assessment for intragastric systems marketed in Europe. Brazil's ANVISA has accelerated review timelines for obesity devices under its priority health technology track, expanding Latin American market access. Stakeholders must monitor evolving reimbursement decisions by CMS and parallel agencies in Germany and Japan, as coverage determinations will shape physician adoption velocity more than device innovation cycles.
Market Dynamics
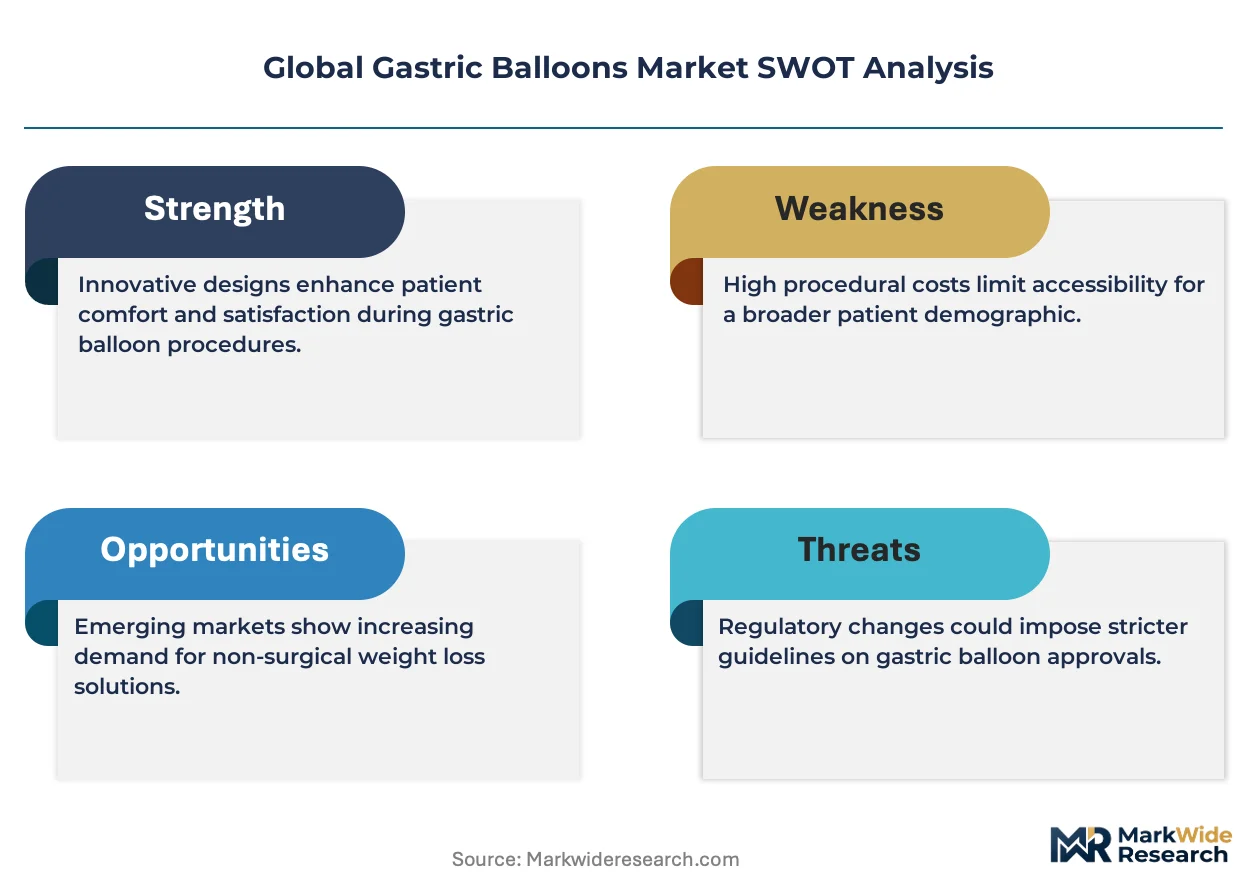
Silicone elastomer chemistry is restructuring competitive positioning in gastric balloon manufacturing, forcing polyurethane-dependent suppliers to reformulate or exit as biocompatibility standards tighten across FDA and EU MDR jurisdictions.
Growth Catalysts
- Outpatient Procedure Expansion:Ambulatory surgical centers in the United States are consolidating balloon placements into same-day discharge protocols, compressing total cost of care and expanding addressable patient pools.
- REACH Silicone Compliance:European silicone suppliers meeting updated REACH substance restrictions are capturing preferential sourcing contracts from device manufacturers seeking MDR technical documentation alignment.
- Swallowable Capsule Formats:Elimination of endoscopic delivery requirements is opening sedation-free eligibility to patients with anesthesia contraindications, broadening the clinical candidate base.
Market Restraints
- Silicone Feedstock Concentration:Medical-grade silicone precursor supply concentrates among German and Japanese chemical conglomerates, exposing balloon manufacturers to input cost volatility and allocation rationing.
- Deflation-Related Safety Reviews:Spontaneous balloon deflation incidents have triggered FDA safety communications requiring enhanced rupture-resistance testing, extending 510(k) clearance timelines.
- Surgical Bypass Substitution:Laparoscopic sleeve gastrectomy maintains durable efficacy advantages for BMI thresholds above 35 kg/m², capping balloon penetration in severe obesity segments.
Strategic Opportunities
- Brazil Priority Track Access:ANVISA's accelerated obesity device review pathway is compressing regulatory lag for intragastric systems, enabling first-mover positioning in Latin America's largest reimbursed market.
- Adjustable Volume Systems:Personalized fill-volume titration protocols command premium pricing and extend dwell-time optimization, differentiating against fixed-volume commodity balloons.
- Telehealth-Integrated Monitoring:Remote patient monitoring platforms paired with balloon therapy are creating subscription revenue streams and improving retrieval compliance rates.
Industry Challenges
- Bariatric Endoscopist Training Bottlenecks:Capsule-based delivery reduces procedural skill requirements, but retrieval and complication management still depend on scarce fellowship-trained specialists.
- Reimbursement Code Fragmentation:CMS Category III code status for swallowable formats creates prior authorization complexity, forcing providers to navigate mixed coverage determinations across commercial and public payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastric Balloons Market |
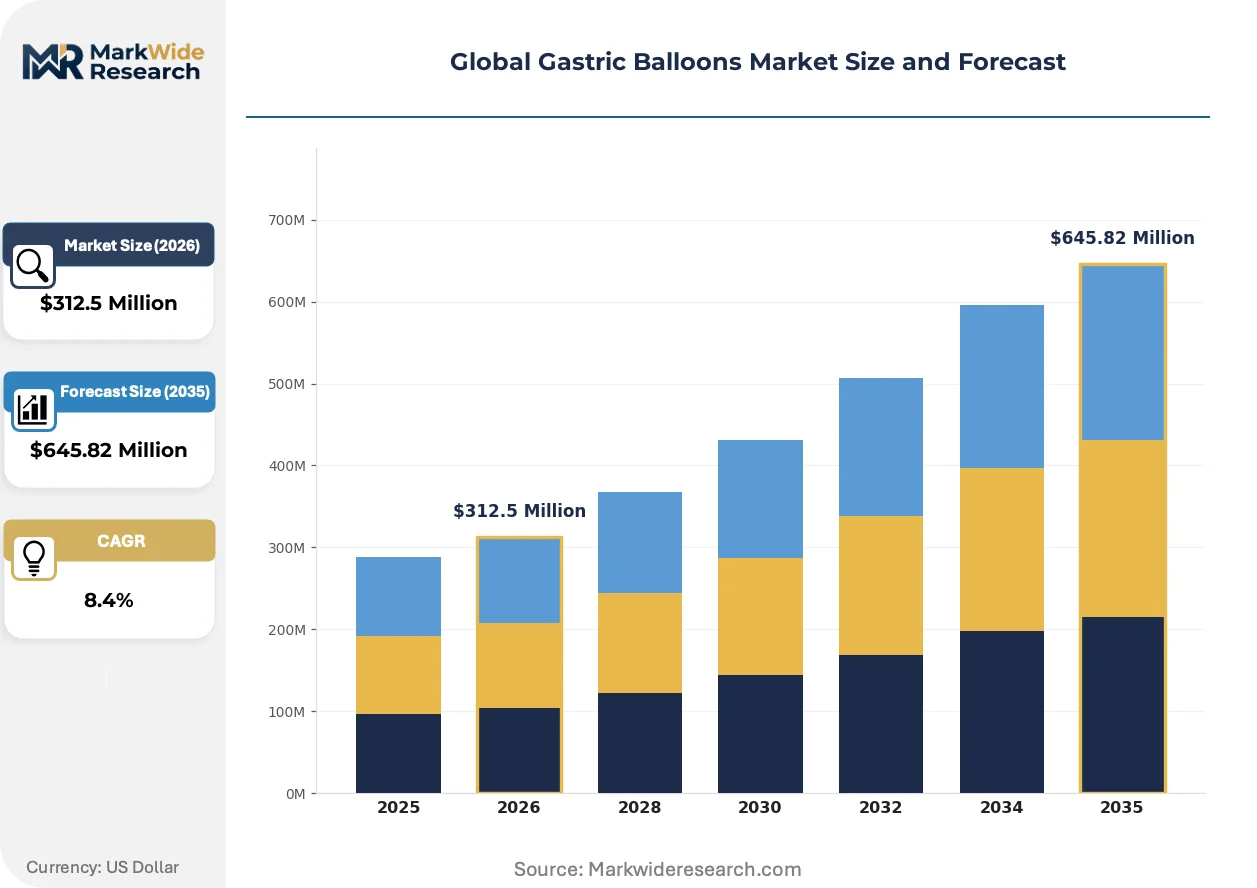
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intragastric Balloon, Adjustable Balloon, Gas-Filled Balloon, Balloon Capsule, Water-Filled Balloon Therapy Area: Obesity Management, Weight Reduction, Metabolic Syndrome, Bariatric Support, Appetite Suppression End User: Bariatric Clinics, Gastroenterology Centers, Ambulatory Surgical Centers, Weight Loss Facilities, Diagnostic Labs Deployment: Outpatient Procedures, Hospital-Based Interventions, Minimally Invasive Surgery, Endoscopic Treatments, Day Care Settings |
| Companies Covered | Boston Scientific, Allurion Technologies, ReShape Lifesciences, Spatz Medical, Helioscopie Medical Implants, Apollo Endosurgery, Endalis, Medispar, Districlass Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastric Balloons Market Shifts & Advancements
Device architecture is converging around patient-centric delivery mechanisms that minimize procedural infrastructure, while regulatory frameworks on both sides of the Atlantic recalibrate safety surveillance intensity.
Silicone elastomer is unifying gastric balloon construction standards by replacing polyurethane across extended-dwell intragastric systems. Bariatric clinics in Germany and the United States are prioritizing silicone-based inventory for 12-month implantation protocols. This material transition is compressing supplier margins for legacy polymer manufacturers unable to achieve medical-grade silicone certification.
The EU Medical Device Regulation's post-market surveillance requirements are intensifying clinical follow-up obligations for intragastric systems marketed in Europe. Manufacturers must now maintain active implant registries and submit periodic safety update reports to notified bodies. Adjustable balloon systems with telemetry-enabled pressure monitoring are capturing disproportionate regulatory attention as higher-risk device subclasses.
Patient self-selection via direct-to-clinic digital channels is displacing traditional physician-referral pathways for initial balloon consultations. Ambulatory surgery centers in Brazil and the United States are investing in patient acquisition platforms that bypass primary care gatekeepers. This channel shift concentrates volume among vertically integrated clinic networks with captive marketing capabilities.
Global Gastric Balloons Market Segmentation
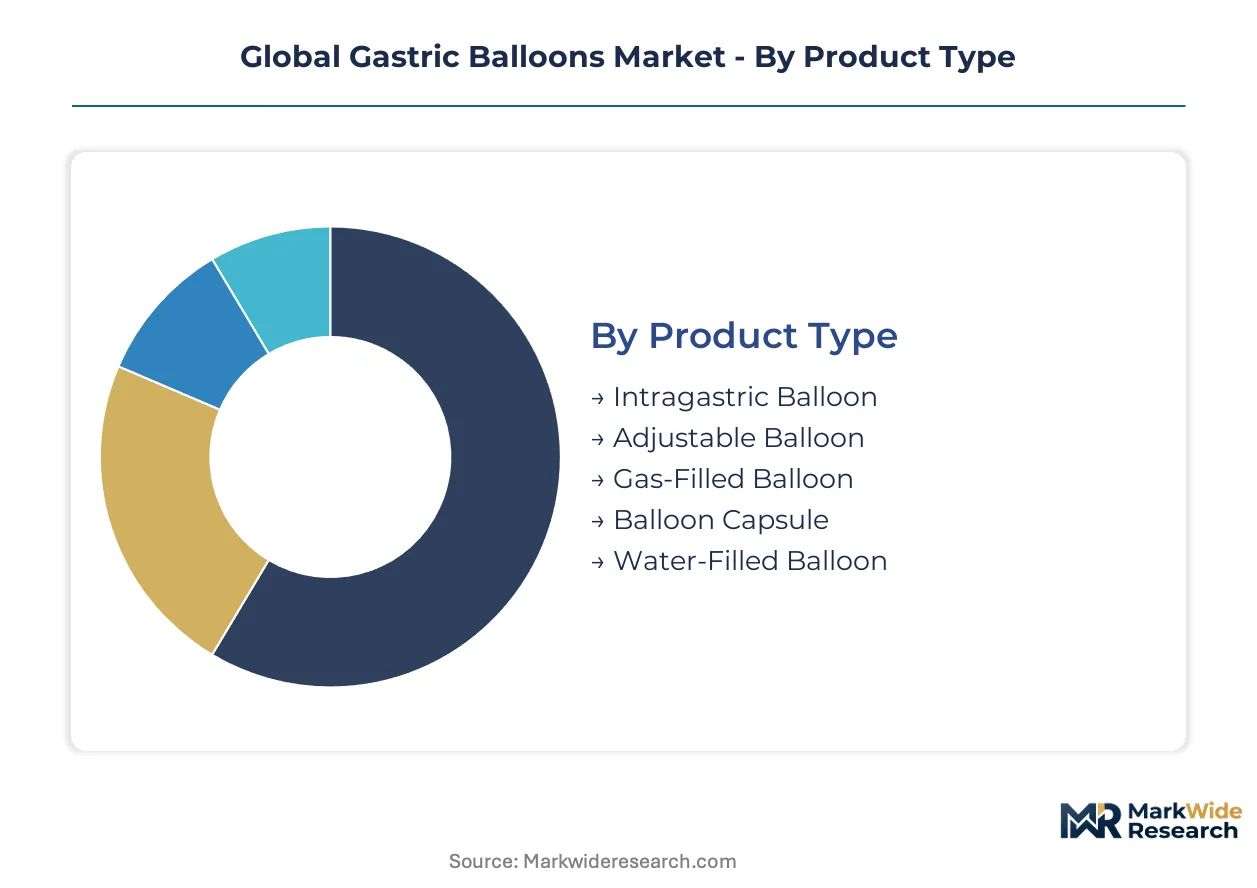
Gastric balloon segmentation reveals distinct regulatory pathways, material specifications, and reimbursement profiles that determine commercial viability across patient populations. Each category isolates variables that shape procurement decisions, from endoscopic infrastructure requirements to therapy duration protocols.
Product Type:
FDA 510(k) clearance pathways diverge sharply between intragastric systems requiring endoscopic retrieval and swallowable formats with spontaneous excretion mechanisms, while EU MDR technical documentation demands escalate for adjustable systems with active implantable characteristics.
- Intragastric Balloon:Fluid-filled silicone elastomer spheres occupying 400-700 mL gastric volume, retrieved endoscopically after 6-12 month dwell periods. Demand concentrates in United States bariatric clinics where established CPT codes streamline prior authorization workflows.
- Adjustable Balloon:Systems enabling post-implantation fill-volume titration via transdermal ports, commanding premium pricing through personalized therapy protocols. German reimbursement authorities have created dedicated procedure codes for adjustable systems, accelerating physician adoption.
- Gas-Filled Balloon:Air or nitrogen-filled alternatives reducing migration risk through lower density.
- Balloon Capsule:Swallowable formats with catheter-attached inflation mechanisms, eliminating procedural sedation requirements entirely.
- Water-Filled Balloon:Saline-based systems with simpler manufacturing specifications but shorter approved dwell times.
Intragastric balloon sits at the top of the volume ranking, with balloon capsule climbing the fastest.
Therapy Area:
Reimbursement intensity correlates with comorbidity documentation requirements, with metabolic syndrome presentations attracting broader coverage determinations than cosmetic weight reduction indications.
- Obesity Management:Primary indication for BMI 30-40 kg/m² patients failing lifestyle intervention, requiring documented 6-month diet history for preauthorization. United States commercial payers increasingly mandate supervised medical weight loss attempts before balloon approval.
- Weight Reduction:Targeted protocols emphasizing percentage total body weight loss endpoints, often bundled with behavioral counseling subscriptions. Brazilian private health plans have expanded coverage for weight reduction indications under ANVISA's priority health technology framework.
- Metabolic Syndrome:Balloon therapy preceding or accompanying pharmacologic intervention for insulin-resistant patients.
- Bariatric Support:Pre-surgical bridging therapy for super-obese patients requiring BMI reduction before sleeve gastrectomy eligibility.
- Appetite Suppression:Mechanoreceptor-focused protocols emphasizing satiety signaling rather than caloric restriction education.
Obesity management generates the deepest procedure volume, with metabolic syndrome gaining share fastest among reimbursed indications.
End User:
Capital equipment requirements and staffing models create distinct procurement patterns across facility types, with sedation capability and endoscopy suite access determining product format compatibility.
- Bariatric Clinics:Specialized facilities with captive patient acquisition and in-house retrieval capability, preferring 12-month dwell silicone systems for recurring revenue optimization. German bariatric networks have consolidated purchasing through group procurement organizations.
- Gastroenterology Centers:Endoscopy-heavy settings with established sedation protocols and fellowship-trained retrieval specialists, capturing complication management referrals from primary placement sites. United States gastroenterology practices are expanding into metabolic disease service lines.
- Ambulatory Surgical Centers:Same-day discharge facilities prioritizing swallowable capsule formats to minimize anesthesia overhead and recovery bay utilization.
- Weight Loss Facilities:Non-surgical wellness centers focusing on behavioral compliance and dietary counseling adjunct to balloon therapy.
- Diagnostic Labs:Imaging and laboratory service providers supporting pre-implantation screening and post-retrieval metabolic monitoring.
Bariatric clinics anchor procedure volume concentration, with ambulatory surgical centers expanding most quickly as sedation-free formats mature.
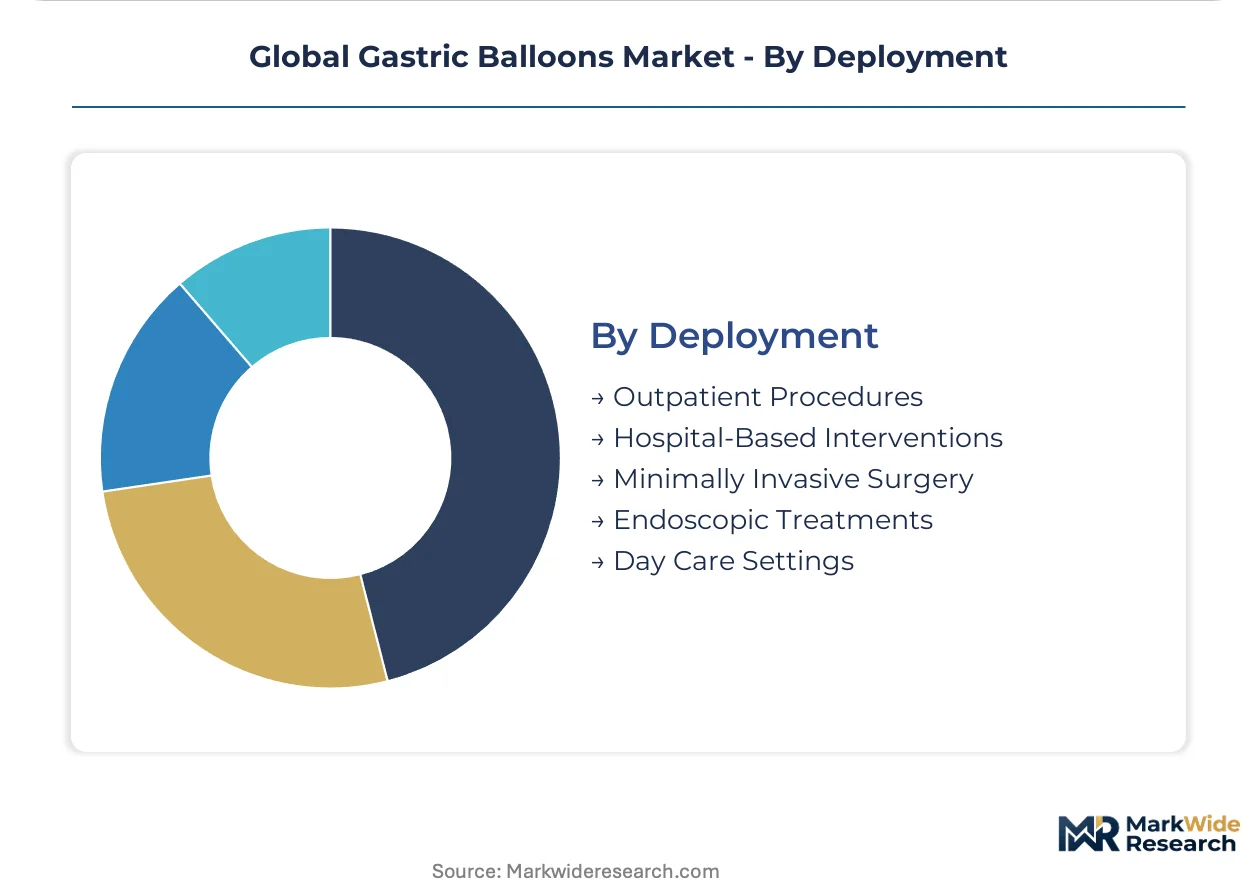
Deployment:
Facility fee structures and nursing intensity requirements differentiate economic outcomes across settings, with day care configurations capturing margin advantages through compressed length-of-stay metrics.
- Outpatient Procedures:Same-day discharge protocols with pre-procedure fasting and post-observation nausea management, standard for swallowable capsule placements. United States ambulatory surgery centers have reduced average encounter costs below hospital-based alternatives.
- Hospital-Based Interventions:Inpatient or hospital outpatient department settings reserved for high-risk patients with anesthesia contraindications or anticipated complication management needs. Brazilian public hospital systems concentrate complex retrievals requiring fluoroscopic guidance.
- Minimally Invasive Surgery:Laparoscopic-assisted balloon placements for patients with altered gastric anatomy or prior bariatric surgery.
- Endoscopic Treatments:Conventional transoral deployment and retrieval requiring conscious sedation and specialized endoscopist training.
- Day Care Settings:Standalone facilities with nursing observation capability but no overnight admission authority, positioned between ambulatory and hospital economics.
Outpatient procedures dominate placement economics, with day care settings emerging fastest as swallowable formats reduce procedural complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bariatric networks anchor procedure volume concentration for intragastric systems, with reimbursement pathways maturing fastest across Western European markets. National regulators are recalibrating coverage determinations as swallowable formats reduce procedural infrastructure requirements.
United States
CMS Category III code status for capsule-based delivery creates prior authorization complexity for ambulatory surgical centers. FDA safety communications on deflation incidents have extended 510(k) clearance timelines for legacy polyurethane systems. Boston-area medical device clusters concentrate silicone sourcing negotiations for 12-month dwell protocols.
Germany
Statutory health insurance funds have established dedicated procedure codes for adjustable balloon systems, accelerating physician adoption in North Rhine-Westphalia. EU MDR post-market surveillance requirements intensify clinical follow-up obligations for intragastric systems. Bavarian bariatric networks consolidate purchasing through group procurement organizations.
Brazil
ANVISA's priority health technology track has compressed regulatory lag for obesity devices, expanding private health plan coverage for weight reduction indications. Public hospital systems in São Paulo concentrate complex retrievals requiring fluoroscopic guidance. Patient self-selection via direct-to-clinic digital channels displaces traditional physician-referral pathways.
Japan
PMDA review timelines for Class II obesity devices lag Western counterparts, constraining swallowable format penetration despite aging demographics. METI industrial policy supports domestic silicone precursor production to reduce import dependency from German and Japanese chemical conglomerates. Tokyo metropolitan bariatric centers prioritize sedation-free workflows for anesthesia-contraindicated patients.
United Kingdom
NICE technology appraisal pathways for intragastric systems remain restrictive compared to German reimbursement benchmarks. NHS England procurement frameworks favor fixed-volume commodity balloons over premium adjustable systems. London-based gastroenterology practices are expanding into metabolic disease service lines with endoscopy-heavy staffing models.
Global Gastric Balloons Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers secure silicone feedstock agreements and distribution networks. The vendor base concentrates among vertically integrated medical device conglomerates and specialized endoscopy firms, with mid-cap entrants challenging through capsule-based delivery formats. Three archetypes define positioning: conglomerate-scale suppliers with captive material sourcing, endoscopy-specialized firms with retrieval expertise, and disruptive entrants eliminating procedural sedation requirements. M&A activity and capacity expansion in medical-grade silicone production represent the dominant competitive moves.
Within the conglomerate-scale tier, Boston Scientific and Apollo Endosurgery exemplify backward integration strategies controlling raw material quality through captive silicone supply chains. Allurion Technologies occupies a disruptive position representing the capsule-format archetype that eliminates endoscopic infrastructure requirements entirely. These three anchors illustrate the material transition from polyurethane to silicone elastomer and the procedural shift toward sedation-free patient workflows.
| Leading Market Players |
|---|
| Boston Scientific |
| Allurion Technologies |
| ReShape Lifesciences |
| Spatz Medical |
| Helioscopie Medical Implants |
| Apollo Endosurgery |
| Endalis |
| Medispar |
| Districlass Medical |
| Others |
Supply & Pricing Matrix
EU REACH silicone substance restrictions gate qualified supply for extended-dwell intragastric systems, separating premium-tier manufacturers with certified elastomer sourcing from commodity competitors facing reformulation costs. This regulatory filter concentrates pricing power among German and Japanese chemical conglomerates while compressing margins for polyurethane-dependent suppliers unable to achieve medical-grade certification.
Pricing Analysis
Medical-grade silicone precursor costs pass through directly to device pricing, with manufacturers bearing volatility from German and Japanese chemical suppliers. Three-tier pricing structure across premium adjustable systems, standard fixed-volume balloons, and economy swallowable formats reflects certification grade and dwell-time performance. Pricing pressure stems from REACH compliance investments and enhanced FDA rupture-resistance testing requirements. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge economics, while German bariatric networks accept premium positioning for 12-month silicone protocols.
Supply Chain Analysis
Direct-to-bariatric-clinic channels handle specialized retrieval-capable inventory, while distributor networks serve ambulatory surgical centers with swallowable formats. Medical-grade silicone production concentrates in Germany, Japan, and the United States, with balloon assembly distributed across FDA-registered and EU MDR-notified facilities. Raw material dependencies center on silicone elastomers, catheter inflation mechanisms, and telemetry-enabled pressure sensors. Single-source vulnerability from German-Japanese chemical conglomerates exposes manufacturers to allocation rationing during supply shocks. Distribution runs through group procurement organizations in Germany and vertically integrated clinic networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastric balloons market functions as a stable compounder anchored by irreversible outpatient procedure expansion across ambulatory surgical centers. Sedation-free workflow adoption creates durable volume growth independent of macroeconomic cycles.
For Market Incumbents: Extend silicone sourcing security through backward integration or long-term offtake agreements with REACH-certified European suppliers. Defend against capsule-format disruption by embedding retrieval services into clinic partnerships, creating switching costs that neutralize sedation-free competitors. Prioritize telemetry-enabled adjustable systems to capture premium pricing and regulatory preference under EU MDR post-market surveillance frameworks.
For New Entrants and Emerging Players: Swallowable capsule telemetry represents the most penetrable technology wedge, targeting anesthesia-contraindicated patients excluded from endoscopic protocols. Brazil's ANVISA priority track offers regulatory fast-lane positioning in Latin America's largest reimbursed market. Direct-to-clinic digital patient acquisition bypasses primary care gatekeepers and concentrates volume among vertically integrated networks.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale bariatric clinic networks because procedure volume concentration enables group purchasing organization leverage and captive patient funnel control. Five-to-ten year viability hinges on reimbursement code maturation for capsule formats. Watch CMS Category III-to-I code conversion as the inflection signal for ambulatory surgical center penetration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Silicone Certification | Unlocks EU MDR market access and premium pricing tier eligibility for extended-dwell systems. |
| Swallowable Format Development | Eliminates sedation infrastructure requirements and expands addressable patient pools in anesthesia-contraindicated populations. |
| Telehealth Monitoring Integration | Creates subscription revenue streams and improves retrieval compliance rates for bariatric clinics. |
| Group Procurement Consolidation | Compresses unit economics for German bariatric networks through centralized silicone-based inventory purchasing. |
| Brazil Priority Track Registration | Accelerates ANVISA clearance timelines and enables first-mover positioning in Latin American reimbursed markets. |
Research Methodology
Direct dialogue with bariatric surgeons, ambulatory surgical center administrators, GPO contracts managers, and biomedical engineers grounded the qualitative foundation, cross-referenced with FDA 510(k) filings, EU MDR notified body documentation, CMS reimbursement databases, and hospital procurement records. Secondary validation drew from ANVISA regulatory bulletins, German statutory health insurance procedure code updates, and trade data on medical-grade silicone imports. Bottom-up and top-down triangulation reconciled facility-level procedure estimates with national reimbursement statistics.
Bottom-up modeling anchored volume projections across product type, therapy area, end user, and deployment setting dimensions, with top-down sanity checks against national obesity prevalence and bariatric procedure penetration rates. CAGRs derived from segmented growth rate blending weighted by addressable patient pools and reimbursement maturity. Forecast inputs incorporated regulatory pathway timelines, silicone feedstock allocation patterns, and telehealth adoption curves.
The model holds under stable FDA Class II oversight and EU MDR notified body capacity; deviation in reimbursement code fragmentation or silicone supply rationing would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Soft Contact Lenses Market
Medical Devices
Global Brain Implants Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Biological Microscope Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Phlebotomy Equipments Market