
 Cardiac Cryoablation Device Market | 2026-2036
Cardiac Cryoablation Device Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Cryoablation Device Market Outlook
FDA premarket notification requirements for Class III cardiac ablation systems is shifting the cost-of-entry calculus toward larger players with dedicated regulatory affairs infrastructure. Medtronic leverages decades of cryoballoon catheter experience to sustain leadership in pulmonary vein isolation procedures. Boston Scientific Corporation anchors its position through integrated mapping and ablation platforms that compete across the full electrophysiology workflow.
Cardiac cryoablation devices employ pressurized refrigerants—typically nitrous oxide or argon—to create controlled tissue necrosis at temperatures reaching minus 80 degrees Celsius, with balloon-based systems achieving circumferential lesion sets around pulmonary vein ostia for treating drug-refractory atrial fibrillation. Catheter-based cryoablation systems occupy the highest margin tier within device type segmentation due to their disposables model and procedural repeatability, while balloon platforms dominate procedure volume in hospital settings where atrial fibrillation ablation constitutes the primary revenue driver. Cold cryoablation technology leads the technology segment by installed base, though cryoenergy platforms are gaining ground in ambulatory surgical centers seeking faster patient throughput.
FDA 510(k) and premarket approval pathways govern device commercialization in the United States, while the EU Medical Device Regulation enforces stricter clinical evaluation and post-market surveillance across European member states. Japan's PMDA maintains distinct quality management system inspections that shape market access timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for catheter ablation procedures and pre-certification requirements that determine which device platforms gain preferred vendor status in consolidated hospital purchasing networks.
Market Dynamics
Balloon-based catheter systems are compressing procedural learning curves while FDA premarket approval pathways for Class III cardiac devices tighten clinical evidence requirements, favoring manufacturers with dedicated regulatory infrastructure and established cryoballoon catheter platforms.
Growth Catalysts
- Pulmonary vein isolation protocols:Electrophysiology labs in the United States are standardizing cryoballoon ablation as first-line therapy for drug-refractory paroxysmal atrial fibrillation, driving repeat procedure volumes through established lesion set repeatability.
- EU Medical Device Regulation:MDR enforcement of stricter clinical evaluation and post-market surveillance is accelerating consolidation around manufacturers with quality management system infrastructure, reducing competitive fragmentation.
- Ambulatory surgical center expansion:Cold cryoablation technology is migrating from hospital catheterization labs to outpatient settings where faster patient throughput and same-day discharge protocols expand addressable procedure volume.
Market Restraints
- Refrigerant supply concentration:Pressurized nitrous oxide and argon sourcing depends on limited specialty gas suppliers, exposing device manufacturers to input cost volatility and geopolitical supply disruptions.
- Technical limitation in persistent AF:Cryoballoon systems achieve less durable lesion sets in persistent atrial fibrillation substrates compared to radiofrequency ablation, restricting addressable patient populations.
- Regulatory friction from FDA PMA pathways:Class III premarket approval requirements demand extensive clinical trials, extending time-to-market for next-generation catheter designs and favoring incumbents with existing approval portfolios.
Strategic Opportunities
- Japan PMDA quality management:Distinct inspection protocols for foreign manufacturers create first-mover advantages for companies establishing localized regulatory affairs infrastructure ahead of competitors.
- Hybrid mapping-cryoablation convergence:Integration of electroanatomic mapping systems with cryoenergy delivery platforms enables single-procedure workflow efficiency, commanding premium pricing in consolidated hospital purchasing networks.
- Germany electrophysiology lab infrastructure:Dense concentration of tertiary cardiac centers with advanced ablation capabilities supports adoption of complex cryoablation procedures beyond pulmonary vein isolation.
Industry Challenges
- Electrophysiologist training pipeline:Specialized catheter manipulation skills for cryoballoon positioning and occlusion verification require extended proctoring periods, constraining procedure capacity expansion.
- Capital equipment amortization:Cryoablation console acquisition and maintenance contracts demand substantial upfront investment, creating adoption barriers for smaller cardiac centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Cryoablation Device Market |
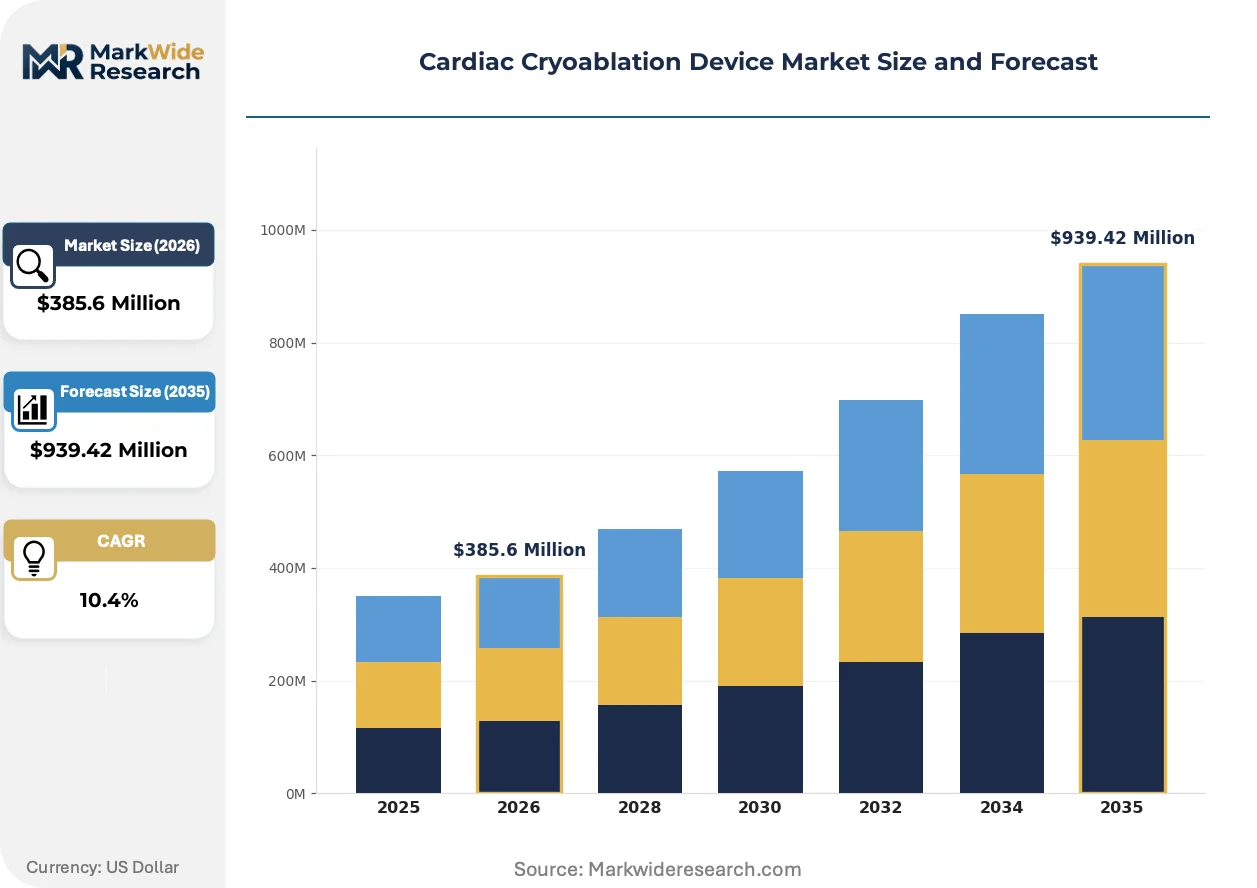
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $939.42 Million |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Balloon, Catheter, Generator, Accessories End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Application: Atrial Fibrillation, Atrial Flutter, Ventricular Tachycardia, Others Technology: Cold Cryoablation, Cryoenergy, Radiofrequency, Laser Ablation |
| Companies Covered | Medtronic, Boston Scientific Corporation, MicroPort Scientific Corporation, AtriCure, Inc., CooperSurgical, Inc., IceCure Medical, AngioDynamics, Johnson & Johnson, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Cryoablation Device Market Strategic Shifts
Next-generation cryoablation platforms are integrating real-time lesion assessment and disposable cost optimization, compressing the gap between procedural efficacy and economic viability while reshaping competitive positioning across the electrophysiology workflow.
Single-shot cryoballoon catheters with improved thermal uniformity are rewriting the economics of atrial fibrillation ablation by reducing procedure time and fluoroscopy exposure. Hospital electrophysiology departments in the United States are adopting these platforms at accelerated replacement cycles. The technology is compressing training requirements and enabling procedure volume expansion in mid-tier cardiac centers previously constrained by physician expertise limitations.
The EU Medical Device Regulation is enforcing enhanced post-market clinical follow-up and periodic safety update reporting for cryoablation systems. Manufacturers must maintain active implant registries and real-world evidence generation infrastructure. High-margin catheter-based disposables face the steepest compliance cost increases, prompting portfolio rationalization toward platforms with established clinical data packages.
Hospital procurement committees are unbundling after-sales service contracts from device purchasing agreements, forcing cryoablation manufacturers to compete on transparent consumables pricing and standalone technical support fees. This shift is most visible in Germany's integrated hospital networks where consolidated purchasing power extracts preferential terms. Device vendors are responding with modular service tiers and remote monitoring subscriptions to defend margin structures.
Cardiac Cryoablation Device Market Segmentation
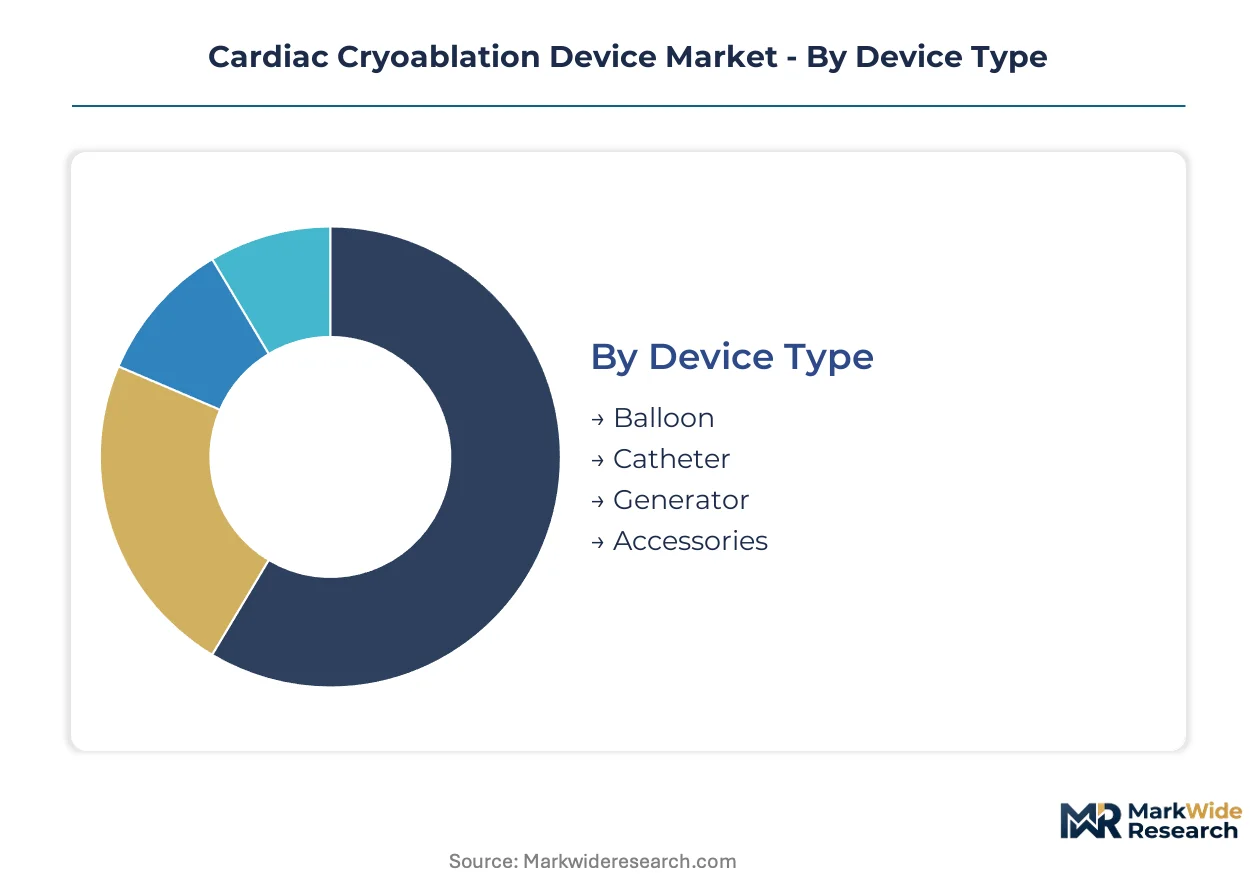
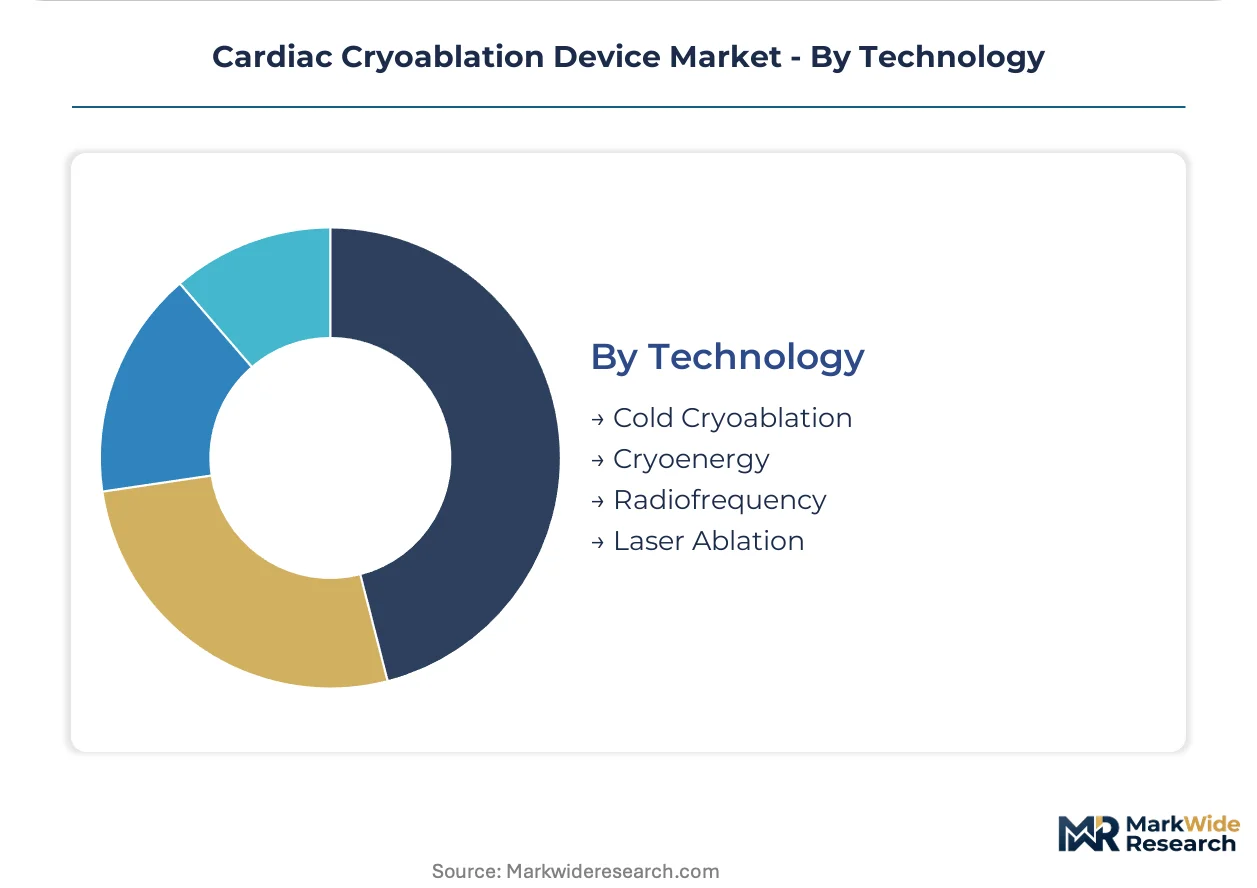
Cardiac cryoablation device segmentation reveals how procedural economics, site-of-care migration, and ablation mechanism selection reshape purchasing priorities across electrophysiology departments. Understanding these divides clarifies where manufacturers must align R&D investment with diverging customer value equations.
Device Type:
Capital intensity and disposables economics separate buyers in this category, with hospital procurement committees weighing upfront console investment against recurring catheter revenue streams.
- Balloon:Cryoballoon systems deploy pressurized refrigerants through compliant balloon membranes to achieve circumferential pulmonary vein isolation in a single energy application. Demand concentrates in United States hospital electrophysiology labs where standardized paroxysmal atrial fibrillation protocols favor predictable lesion sets and compressed procedure times.
- Catheter:Steerable catheter platforms enable point-by-point ablation with precise tip positioning and temperature monitoring, commanding premium pricing through proprietary disposable designs. German tertiary cardiac centers drive adoption for complex anatomical substrates beyond straightforward pulmonary vein isolation.
- Generator:Refrigerant compression and delivery consoles represent capital equipment anchors with multi-year amortization schedules and service contract dependencies.
- Accessories:Sheaths, introducers, and connecting tubing complete procedural sets, typically sourced through bundled purchasing agreements rather than standalone procurement.
Volume sits with balloon platforms; growth tilts toward catheter systems as persistent atrial fibrillation indications expand.
End User:
Reimbursement environment and patient acuity determine site selection, with procedural complexity thresholds filtering which settings can sustain cryoablation programs.
- Hospitals:Tertiary cardiac centers maintain electrophysiology lab infrastructure for complex ablation procedures, absorbing capital equipment costs through high procedural throughput and integrated critical care backup.
- Ambulatory Surgical Centers:Outpatient migration accelerates where same-day discharge protocols and streamlined patient throughput economics outperform hospital-based reimbursement, particularly for straightforward paroxysmal atrial fibrillation cases.
- Clinics:Limited to diagnostic workup and referral coordination rather than interventional ablation due to capital constraints and regulatory licensing requirements.
- Research Institutions:Academic medical centers generate clinical evidence and train electrophysiologists, though commercial procedure volume remains secondary to investigative protocols.
Installed base clusters in hospitals; expansion concentrates in ambulatory surgical centers as payer incentives shift.
Application:
Arrhythmia substrate complexity dictates technology selection and procedural reimbursement levels, with simpler anatomical targets commanding higher automation and standardization.
- Atrial Fibrillation:Drug-refractory paroxysmal atrial fibrillation constitutes the dominant procedural indication, with pulmonary vein isolation protocols driving repeatable cryoballoon utilization across high-volume electrophysiology practices.
- Atrial Flutter:Cavotricuspid isthmus ablation for typical atrial flutter offers straightforward linear lesion sets, though radiofrequency competition limits cryoablation penetration in this segment.
- Ventricular Tachycardia:Substrate-based ablation in scar-related ventricular arrhythmias demands sophisticated mapping integration and remains less suited to single-shot cryoballoon approaches.
- Others:Accessory pathway ablation and atypical atrial flutter represent niche indications with limited dedicated cryoablation protocol development.
Procedure volume anchors in atrial fibrillation; technology development prioritizes persistent substrate expansion.
Technology:
Energy delivery mechanism determines lesion characteristics, equipment compatibility, and competitive positioning against established radiofrequency platforms.
- Cold Cryoablation:Nitrous oxide or argon-based refrigerant systems create controlled tissue necrosis through extracellular ice crystal formation, preserving tissue architecture for reduced thrombogenic risk compared to thermal alternatives.
- Cryoenergy:Next-generation platforms optimize thermal uniformity and real-time temperature monitoring, gaining traction in outpatient settings seeking procedural efficiency gains.
- Radiofrequency:Resistive heating technology maintains dominant installed base and physician familiarity, particularly for complex substrate mapping and ablation.
- Laser Ablation:Optical energy delivery enables precise tissue penetration depth control, though capital cost and technical complexity constrain widespread adoption.
Clinical utilization favors cold cryoablation; cryoenergy platforms are climbing the fastest as workflow integration improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cardiac cryoablation devices concentrates in electrophysiology markets with established reimbursement pathways and dense tertiary cardiac center networks. The United States, Germany, and Japan absorb the dominant share of procedure volume, while regulatory infrastructure and lab capacity determine competitive access in each jurisdiction.
United States
Hospital electrophysiology labs standardize cryoballoon ablation as first-line therapy for drug-refractory paroxysmal atrial fibrillation. FDA premarket approval pathways for Class III cardiac devices tighten clinical evidence requirements, favoring manufacturers with dedicated regulatory affairs infrastructure. The Cleveland Clinic and Mayo Clinic anchor high-volume ablation programs that drive technology adoption curves.
Germany
Tertiary cardiac centers maintain dense electrophysiology lab infrastructure supporting complex ablation procedures beyond straightforward pulmonary vein isolation. EU Medical Device Regulation enforces stricter clinical evaluation and post-market surveillance, accelerating consolidation around quality management system leaders. The Heidelberg and Hamburg university hospital networks generate clinical evidence that shapes European protocol development.
Japan
PMDA quality management system inspections create distinct market access timelines for foreign manufacturers establishing localized regulatory affairs infrastructure. METI reimbursement frameworks determine which device platforms gain preferred vendor status in consolidated hospital purchasing networks. Tokyo and Osaka medical centers concentrate the installed base of cryoablation consoles.
United Kingdom
NHS England specialized commissioning frameworks filter cryoablation procedure authorization to designated cardiac centers with demonstrated outcome metrics. MHRA post-Brexit regulatory alignment with EU MDR maintains clinical evaluation stringency for device commercialization. The London and Manchester cardiac networks drive adoption of integrated mapping-cryoablation platforms.
China
NMPA innovation pathway approvals accelerate market access for cryoablation devices with domestic clinical trial data. Provincial centralized procurement reforms compress pricing margins while expanding addressable patient populations through tiered hospital networks. Beijing and Shanghai tertiary hospitals anchor technology evaluation and physician training pipelines.
Cardiac Cryoablation Device Market Competitive Environment
United States producers anchor the premium-tier segment with integrated electrophysiology platforms; European and Asian specialists hold positions in component supply and regional distribution. The vendor base concentrates around cryoballoon catheter platforms and mapping-integrated systems, with consolidation pressure from regulatory compliance cost escalation. Three archetypes dominate: full-workflow integrators, single-technology specialists, and regional contract manufacturers. Competitive moves center on hybrid mapping-cryoablation convergence and ambulatory surgical center channel expansion.
Within the full-workflow integrator tier, Medtronic and Boston Scientific Corporation occupy positions shaped by decades of cryoballoon catheter experience and electroanatomic mapping integration respectively. AtriCure, Inc. exemplifies the single-technology specialist archetype focused on cardiac ablation substrates. These anchors represent how regulatory infrastructure investment and procedural workflow control determine competitive positioning across consolidated hospital purchasing networks and ambulatory migration channels.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| MicroPort Scientific Corporation |
| AtriCure, Inc. |
| CooperSurgical, Inc. |
| IceCure Medical |
| AngioDynamics |
| Johnson & Johnson |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialty gas suppliers in the United States and Germany control pressurized refrigerant sourcing, compressing device manufacturers' procurement leverage while enforcing rigid contract terms that inflate cryoballoon catheter input costs.
Pricing Analysis
Short lead-time premiums for nitrous oxide and argon deliveries compress margins for manufacturers locked into just-in-time refrigerant contracts. Three-tier pricing structure across FDA PMA-approved, CE MDR-certified, and economy non-certified platforms separates premium cryoablation consoles from standard balloon catheters and unbundled accessories. Pricing pressure stems from hospital procurement committees unbundling service contracts and demanding transparent consumables pricing. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while tertiary cardiac centers in Germany absorb premium pricing for mapping-integrated platforms.
Supply Chain Analysis
Workforce availability constraints in Minnesota and Massachusetts manufacturing clusters limit cryoablation console production scaling. Supply concentrates in the United States for generator assembly, Germany for precision balloon membrane fabrication, and Japan for refrigerant compression components. Raw material dependencies include medical-grade nitrous oxide, compliant elastomer polymers, and cryogenic-grade stainless steel. Single-source vulnerability in specialty gas refining exposes manufacturers to geopolitical disruption. Distribution runs through consolidated hospital purchasing networks and GPO contracts in the United States, direct tender processes in Germany, and METI-influenced vendor designation in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over refrigerant supply and mapping software stacks determines margin defense against radiofrequency competitors and emerging cryoenergy platforms.
For Market Incumbents: Extend cryoballoon catheter platform dominance by acquiring distressed refrigerant distributors in the United States and integrating real-time lesion assessment software that locks hospital customers into recurring disposable revenue. FDA PMA pathway expertise and established clinical data packages provide defensive moats against emerging cryoenergy entrants seeking faster outpatient throughput positioning. For New Entrants and Emerging Players: The price-point gap between premium mapping-integrated systems and economy standalone cryoballoon platforms creates entry space for hybrid platforms targeting mid-tier cardiac centers. White-space targets include persistent atrial fibrillation substrate protocols underserved by current single-shot balloon designs and Japan's PMDA-inspected quality management infrastructure where localized regulatory affairs capabilities yield first-mover advantages. Go-to-market through ambulatory surgical center channel partnerships bypasses incumbent hospital GPO lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor single-technology catheter specialists with FDA 510(k) clearance portfolios in the United States and EU MDR technical documentation readiness in Germany. Long-term viability hinges on reimbursement code stability for catheter ablation procedures and electrophysiologist training pipeline expansion. Watch hybrid mapping-cryoablation convergence adoption curves in Cleveland Clinic and Mayo Clinic networks as inflection indicators for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Class III cardiac device submissions demand extensive clinical trials favoring incumbents with regulatory infrastructure. |
| EU MDR Technical Documentation | Enhanced post-market surveillance requirements accelerate consolidation around quality management system leaders. |
| Hospital System Partnership | Integrated electrophysiology workflow contracts lock in cryoballoon catheter recurring revenue and service dependencies. |
| Software Companion Development | Real-time lesion assessment integration commands premium pricing and compresses physician training curves. |
| Reimbursement Strategy | CPT code optimization for catheter ablation procedures determines addressable patient populations and site-of-care migration. |
Study Parameters
FDA 510(k) and PMA filings, EU MDR technical documentation databases, and CMS Medicare reimbursement records formed the secondary backbone for market sizing and competitive positioning. Primary interviews with electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated procedural volume assumptions and procurement behavior patterns. Bottom-up and top-down triangulation reconciled device shipment data with hospital installed base estimates across the United States, Germany, and Japan.
Bottom-up modeling anchored forecasts in electrophysiology lab capacity expansion, procedure volume trends by arrhythmia substrate, and catheter replacement cycles. Top-down validation cross-checked against cardiac ablation market aggregates and competitor revenue disclosures. Segmentation dimensions included device type, end-user site-of-care, application indication, and technology platform. CAGRs derived from logistic growth curve fitting to procedural adoption S-cycles, with inputs from refrigerant supply constraints and regulatory approval timelines.
Inputs from FDA MAUDE adverse event databases and EU MDR periodic safety update reports were available through the study window; gaps in real-world cryoballoon durability data beyond five-year follow-up introduce uncertainty bands in persistent atrial fibrillation expansion forecasts. Forecasts reflect assumptions regarding electrophysiologist training pipeline throughput and ambulatory surgical center licensing expansion. Material deviation in PMDA inspection timelines, nitrous oxide supply disruptions, or hybrid mapping-cryoablation platform adoption curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Global Vascular Embolization Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Arterial Stabilization Device Market