
 Chronic Brain Damage Management Market | 2026-2036
Chronic Brain Damage Management Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Brain Damage Management Market Outlook
Modular therapy bundling is decoupling acute intervention from long-term rehabilitation, letting providers mix pharmacological and non-pharmacological components based on patient progression. Medtronic plc leverages its neurostimulation platform to anchor the device-intensive segment across hospital systems. Lundbeck specializes in CNS-targeted pharmacological agents that sustain recurring prescription volumes in outpatient clinics.
Chronic brain damage management encompasses sustained clinical interventions for persistent neurological impairment following traumatic injury, hypoxic events, or degenerative conditions, typically involving neurotransmitter modulation, neural pathway stimulation, or structured cognitive retraining protocols. The primary purpose is functional stabilization and incremental recovery of motor, cognitive, or behavioral capacity in patients with lasting deficits. Medications and neurostimulation devices capture divergent margin pools, with the former relying on formulation patents and the latter on hardware-software integration and implant servicing contracts. Rehabilitation equipment trails in growth velocity but occupies a defensive revenue position as institutional procurement cycles lengthen.
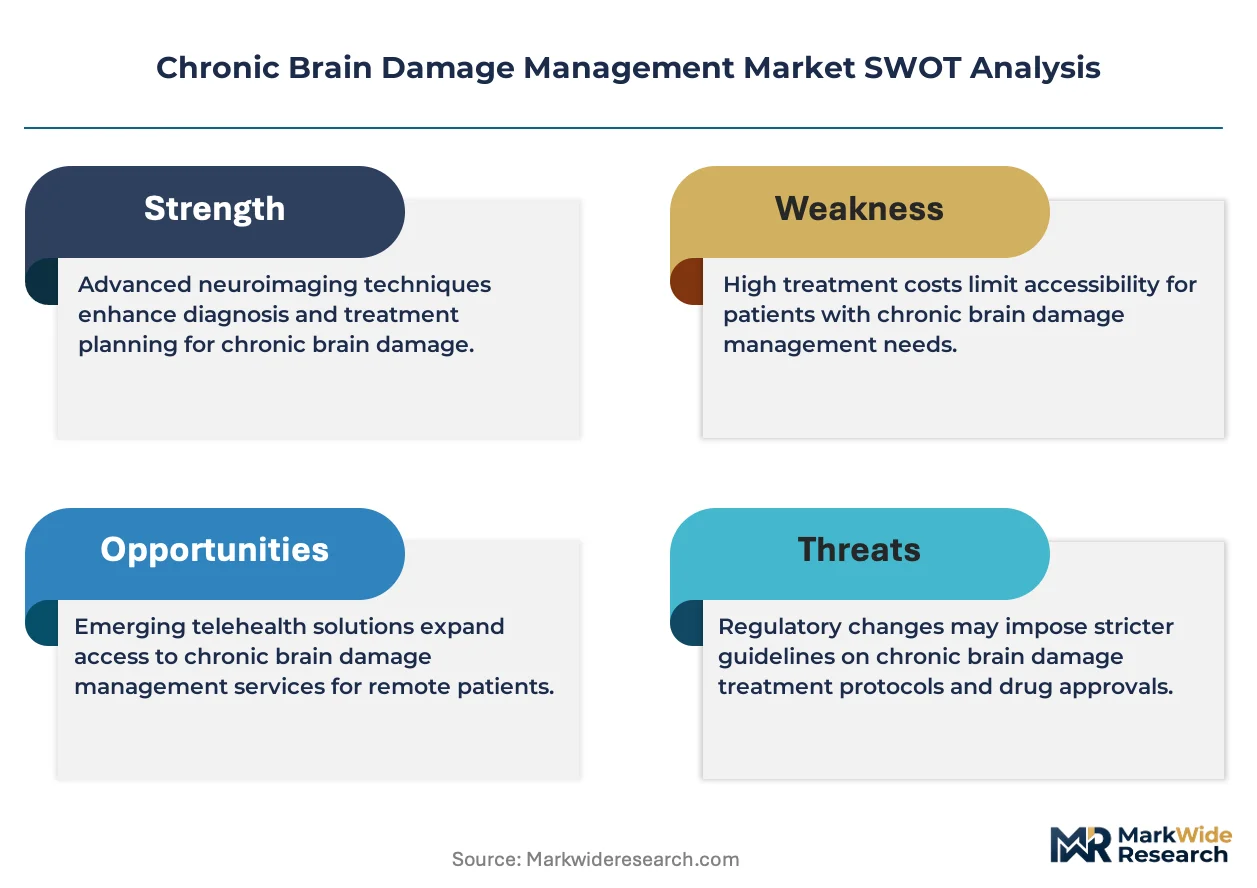
The FDA's breakthrough therapy and humanitarian device exemption pathways shape neurostimulation market access timelines, while the EMA's medical device regulation imposes clinical evidence requirements that filter smaller device developers from European commercialization. Japan's PMDA sakigake designation similarly compresses review periods for novel neuromodulation therapies, concentrating first-mover advantages among firms with established regulatory affairs infrastructure. Stakeholders must monitor reimbursement coding evolution for integrated care protocols, as payor categorization will determine whether bundled therapy models achieve sustainable adoption against unbundled alternatives.
Market Dynamics
Integrated care protocols are decoupling acute intervention from long-term rehabilitation, forcing providers to reconfigure service delivery around patient progression milestones rather than fixed treatment timelines.
Growth Catalysts
- FDA breakthrough therapy designation:The pathway compresses neurostimulation device review periods, accelerating commercialization timelines for novel neuromodulation therapies in hospital systems.
- Japan's PMDA sakigake framework:Priority review status concentrates first-mover advantages among firms with established regulatory affairs infrastructure for brain injury recovery devices.
- Rehabilitation center consolidation:Large institutional networks in Germany and the United States are standardizing procurement of bundled pharmacological and non-pharmacological protocols.
Market Restraints
- EMA MDR clinical evidence requirements:The Medical Device Regulation imposes stringent documentation burdens that filter smaller developers from European commercialization, reducing competitive pressure on established players.
- Implant servicing contract concentration:Hardware-software integration expertise clusters among a limited set of neurostimulation specialists, creating vendor lock-in risks for hospital procurement departments.
- Reimbursement coding fragmentation:Payor categorization varies across federal and private systems, preventing standardized bundled therapy models from achieving predictable revenue recognition.
Strategic Opportunities
- Underpenetrated outpatient cognitive retraining:Community-based clinics in secondary Japanese cities lack structured protocol access, creating whitespace for telehealth-integrated delivery models.
- Pharmacological-neurostimulation convergence:Combined neurotransmitter modulation and neural pathway stimulation protocols show promise for motor deficit subsets currently managed through single-modality approaches.
- IRA Medicare negotiation provisions:Price transparency mandates for CNS-targeted agents create entry points for biosimilar and generic formulations in sustained prescription volumes.
Industry Challenges
- Specialized neurorehabilitation workforce scarcity:Trained therapists capable of administering structured cognitive retraining protocols remain concentrated in tertiary medical centers, constraining protocol rollout.
- Legacy electronic health record integration:Patient progression tracking systems require custom API development to feed data into existing hospital information architectures, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Brain Damage Management Market |
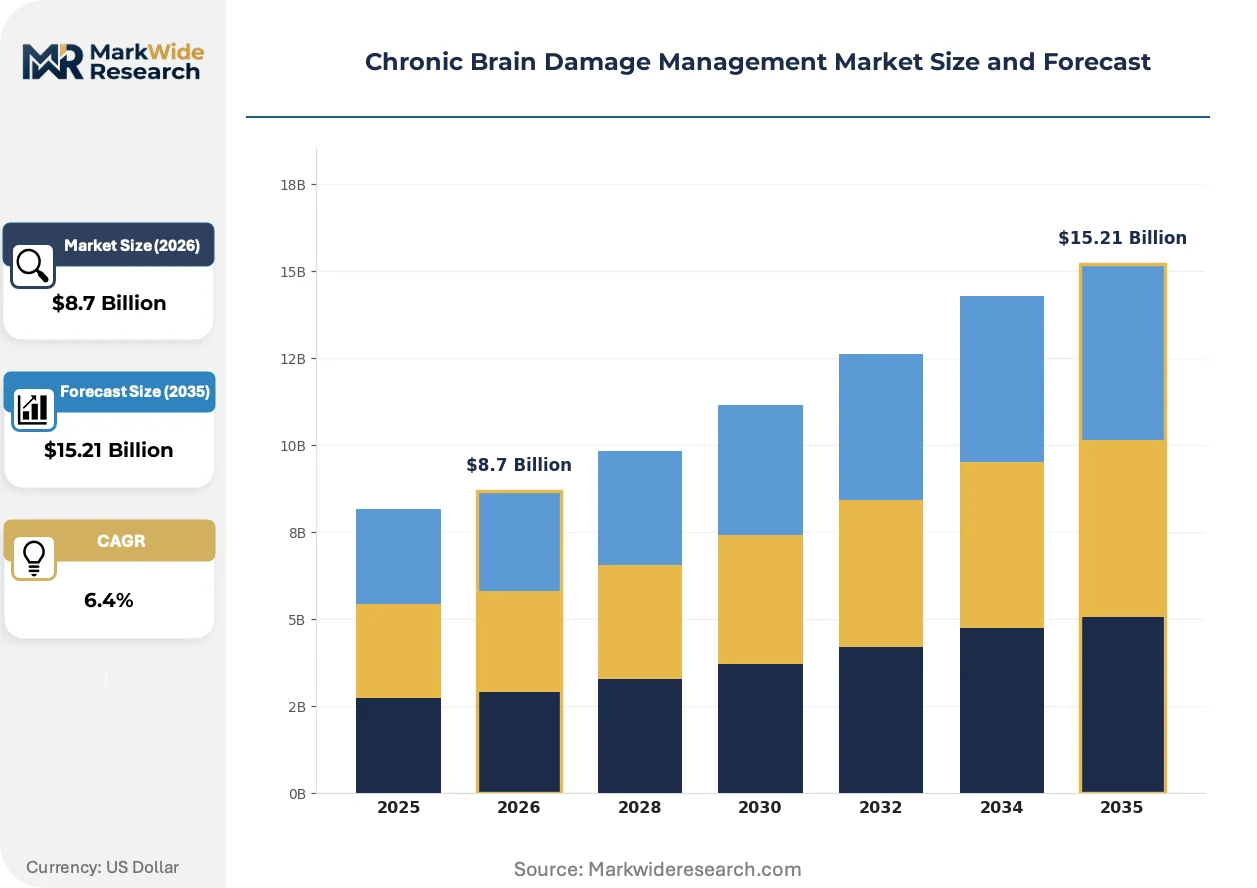
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Rehabilitation Equipment, Neurostimulation Devices Delivery Mode: Oral, Intravenous, Transcutaneous, Intraparenchymal End User: Hospitals, Rehabilitation Centers, Home Care Settings, Outpatient Clinics Treatment Approach: Pharmacological, Non-Pharmacological, Surgical, Integrated Care |
| Companies Covered | Medtronic plc, Abbott Laboratories, Lundbeck, Oxeia Biopharmaceuticals, Hope Biosciences, SHINKEI Therapeutics, BioVie, Oragenics, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Brain Damage Management Market Strategic Shifts
Machine learning algorithms are penetrating patient assessment workflows, compressing the gap between injury characterization and personalized protocol selection in ways that reshape competitive positioning around data infrastructure rather than device hardware alone.
Closed-loop neurostimulation systems are automating real-time parameter adjustment based on neural feedback signals. Rehabilitation centers in the United States are piloting these platforms for motor recovery protocols. The technology is automating the calibration workload previously assigned to specialized technicians, reducing per-patient labor intensity and enabling higher caseload throughput.
The FDA's breakthrough therapy designation pathway is compressing neurostimulation device approval timelines from standard 510(k) or PMA tracks. Manufacturers are restructuring clinical trial designs to meet evidentiary thresholds earlier in development. The hospital systems segment is responding by pre-negotiating procurement frameworks ahead of formal clearance, securing first-access positioning for novel neuromodulation therapies.
Hospital procurement departments are unbundling after-sales service contracts from hardware acquisition agreements. Neurostimulation device vendors face pressure to price implant servicing separately from initial placement. This shift is most visible in German university hospital networks, where tender specifications now mandate multi-vendor maintenance eligibility to prevent single-source dependency.
Chronic Brain Damage Management Market Segmentation
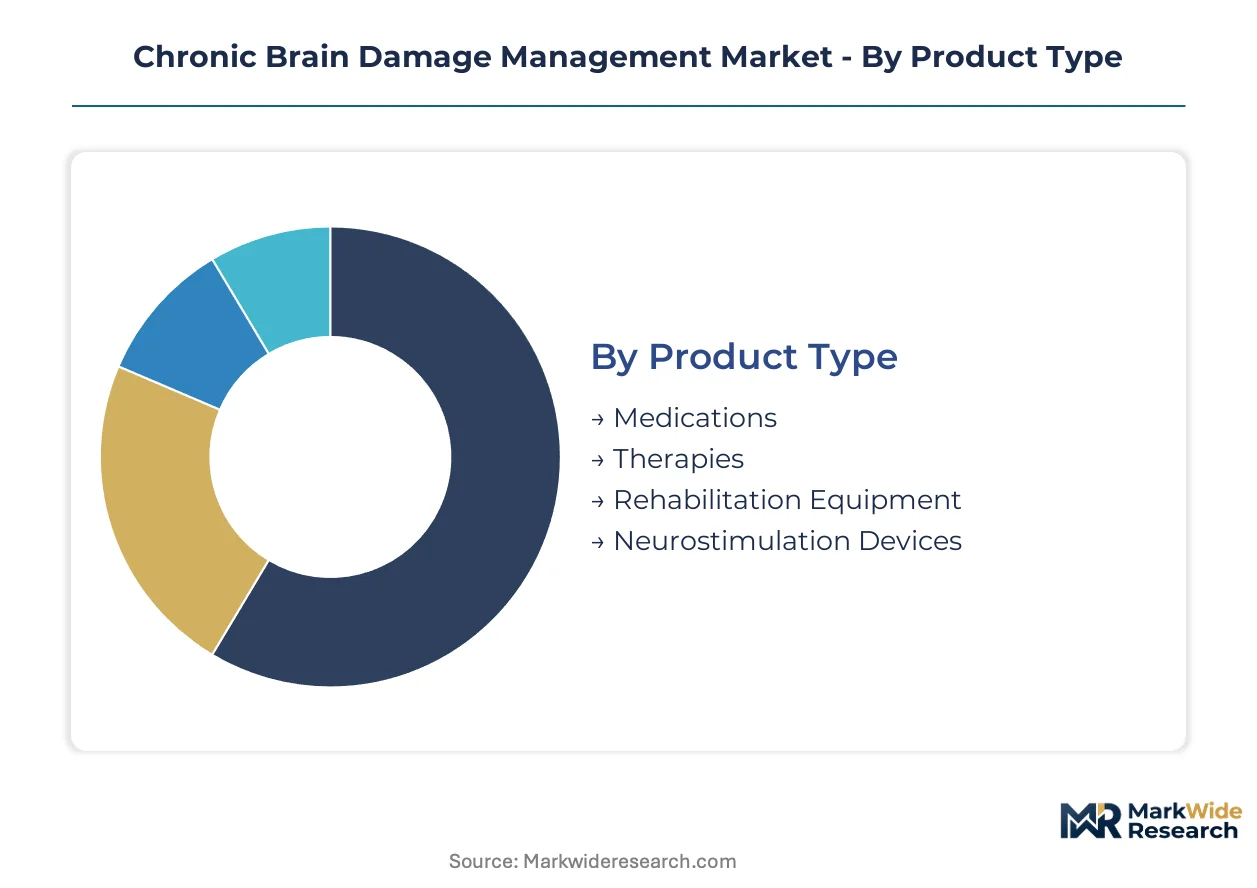
Chronic brain damage management requires precise patient stratification across intervention intensity, delivery invasiveness, and care setting transitions. Segmentation reveals where hardware margins concentrate versus prescription recurring revenue, and which protocols command premium reimbursement.
Product Type:
Medications dominate prescription volumes while neurostimulation devices capture hardware-servicing premiums, creating divergent margin architectures across the value chain.
- Medications:CNS-targeted formulations modulate neurotransmitter pathways through oral and intravenous delivery. Sustained prescription volumes in outpatient clinics and home care settings generate recurring revenue streams anchored by formulation patents and generic substitution dynamics.
- Neurostimulation Devices:Implantable pulse generators and external stimulators deliver targeted electrical modulation to neural circuits. Hospital systems in the United States and Germany pre-negotiate procurement frameworks for FDA-breakthrough-designated platforms, concentrating first-mover advantages among established vendors.
- Therapies:Structured cognitive retraining and behavioral interventions administered by specialized therapists.
- Rehabilitation Equipment:Assistive mobility devices and adaptive technologies for functional recovery protocols.
Today's leader: Medications. Tomorrow's challenger: Neurostimulation Devices.
Delivery Mode:
Route selection tracks intervention acuity, with invasive delivery reserved for refractory cases and transcutaneous methods expanding community-based access.
- Oral:First-line administration for chronic neurotransmitter modulation, enabling patient self-management and minimizing clinical infrastructure requirements.
- Intravenous:Acute-phase delivery in hospital settings for rapid therapeutic plasma concentration.
- Transcutaneous:Non-invasive electrical or pharmacological delivery through intact skin, supporting rehabilitation center and home-based protocols.
- Intraparenchymal:Direct tissue delivery via implanted catheters or injection systems for targeted neuromodulation in specialized neurosurgical centers.
Transcutaneous methods are gaining share fastest as telehealth-integrated delivery models penetrate secondary markets.
End User:
Care setting determines protocol bundling complexity, with institutional purchasers commanding volume discounts and home care segments prioritizing portability.
- Hospitals:Acute intervention and surgical implantation sites with concentrated neurostimulation device procurement authority.
- Rehabilitation Centers:Standardized bundled protocol adoption in consolidated German and United States networks drives integrated care model penetration.
- Home Care Settings:Emerging demand for remote monitoring and patient-administered maintenance therapies.
- Outpatient Clinics:Prescription volume concentration for pharmacological agents and structured cognitive retraining access points.
Rehabilitation centers currently anchor institutional procurement; home care settings show steepest expansion trajectory as remote patient monitoring infrastructure matures.
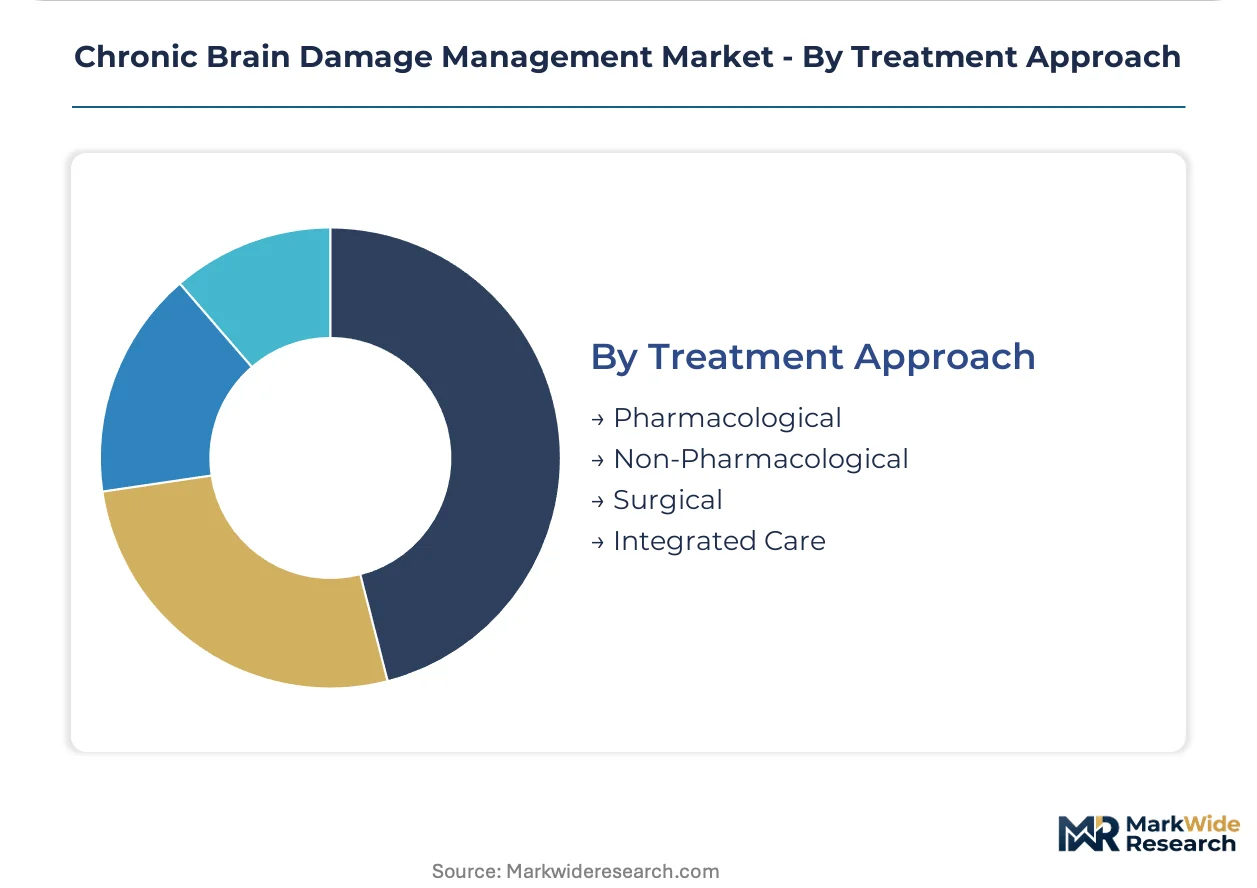
Treatment Approach:
Approach selection reflects disease progression stage, with integrated care protocols decoupling acute intervention from long-term functional recovery milestones.
- Pharmacological:Neurotransmitter modulation through small-molecule and biologic agents, sustaining recurring revenue in outpatient channels.
- Non-Pharmacological:Physical therapy, occupational therapy, and cognitive rehabilitation delivered through structured protocols.
- Surgical:Implantation of neurostimulation hardware and tissue intervention procedures in tertiary medical centers.
- Integrated Care:Modular bundling of pharmacological and non-pharmacological components tailored to patient progression milestones rather than fixed timelines.
Integrated care represents the dominant strategic focus for provider network consolidation; pharmacological approaches face biosimilar pressure under IRA Medicare negotiation provisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The chronic brain damage management industry traces its commercial roots to post-war neurosurgical advances in the United States and Germany, where trauma centers first systematized long-term rehabilitation protocols for veterans with penetrating head injuries.
United States
Hospital systems in the United States concentrate neurostimulation device procurement through pre-negotiated frameworks. The FDA's breakthrough therapy designation compresses review timelines for novel neuromodulation platforms. Rehabilitation networks in Boston and Baltimore anchor integrated care protocol development for traumatic brain injury recovery.
Germany
German university hospital networks unbundle after-sales service contracts from hardware acquisition agreements. The EMA's Medical Device Regulation imposes clinical evidence requirements that filter smaller developers from European commercialization. The Rhine-Ruhr metropolitan region hosts consolidated procurement consortia standardizing bundled pharmacological and non-pharmacological protocols.
Japan
Japan's aging demographic concentrates demand for chronic neurological intervention in tertiary medical centers. The PMDA's sakigake designation grants priority review status for novel brain injury recovery devices. Secondary cities in the Kansai region present whitespace for telehealth-integrated cognitive retraining delivery models.
United Kingdom
The United Kingdom's National Health Service channels pharmacological prescription volumes through specialized outpatient clinics. MHRA post-Brexit regulatory autonomy allows accelerated approval pathways for neurostimulation hardware. London's neurorehabilitation infrastructure trains therapists for structured cognitive retraining protocol administration.
Switzerland
Swissmedic's stringent quality standards attract neurostimulation device manufacturers seeking European credibility markers. The country's cantonal hospital networks purchase rehabilitation equipment through centralized tender processes. Zurich and Geneva anchor specialized brain injury recovery centers serving cross-border patient flows from neighboring jurisdictions.
Chronic Brain Damage Management Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with established neurostimulation platforms. Consolidation pressures favor players with integrated hardware-software capabilities and regulatory affairs infrastructure spanning multiple jurisdictions. Three archetypes dominate: implantable device specialists with servicing contract expertise, CNS-targeted pharmaceutical developers with formulation patent portfolios, and emerging cell therapy platforms pursuing regenerative mechanisms. Competitive moves center on pre-negotiated procurement frameworks with hospital systems and modular therapy bundling partnerships with rehabilitation networks.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories anchor the device-intensive segment with neurostimulation platforms deployed across hospital systems. Lundbeck occupies a distinct position as a CNS-focused pharmaceutical developer sustaining prescription volumes through outpatient clinic channels. These three exemplify how regulatory affairs scale and therapeutic area concentration determine competitive positioning in chronic neurological intervention markets.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Lundbeck |
| Oxeia Biopharmaceuticals |
| Hope Biosciences |
| SHINKEI Therapeutics |
| BioVie |
| Oragenics |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees in the United States and Germany anchor purchasing volume for neurostimulation hardware, concentrating price negotiation leverage around bundled servicing contracts and multi-year maintenance agreements rather than per-unit device costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates neurostimulation device procurement, with FDA breakthrough-designated platforms commanding premium placement against CE-marked alternatives. Price differentiation rests on hardware-software integration depth and implant servicing bundling, with unbundled maintenance eligibility emerging as a cost compression vector in German university hospital tenders. Pricing pressure stems from procurement departments separating after-sales contracts from initial hardware acquisition. Rehabilitation centers show highest price sensitivity due to standardized bundled protocol budgets, while tertiary neurosurgical centers absorb premium tiers for first-mover device access.
Supply Chain Analysis
Japan's PMDA sakigake framework and local-content preferences in medical device procurement are reshaping sourcing patterns for implantable pulse generator components. Manufacturing concentrates in the United States, Germany, and Japan for final device assembly, with semiconductor substrates and biocompatible electrode materials drawing from Taiwanese foundries and Swiss precision component suppliers. Single-source vulnerability clusters around specialized neurostimulator firmware foundries. Distribution runs through hospital system GPO contracts in the United States and cantonal procurement consortia in Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chronic brain damage management market functions as a geographic-arbitrage play between Japan's compressed PMDA review timelines and the EMA's stringent MDR documentation burdens, with regulatory cost differentials exceeding clinical development expense gaps.
For Market Incumbents: Hedge implant servicing revenue erosion by deepening backward integration into biocompatible electrode manufacturing and securing multi-hospital system procurement frameworks ahead of FDA breakthrough designations. Counter unbundling pressure from German procurement consortia through software-locked maintenance protocols that preserve recurring revenue streams.
For New Entrants and Emerging Players: Capture whitespace in secondary Japanese city outpatient cognitive retraining through telehealth-integrated delivery models bypassing tertiary center therapist concentration. Target community-based rehabilitation clinics in the Kansai region with modular pharmacological-neurostimulation convergence protocols priced below institutional bundled care rates.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates with established neurostimulation platforms are the most active acquirers in this space, seeking regulatory affairs infrastructure spanning FDA, EMA, and PMDA jurisdictions. The five-to-ten year viability window favors cell therapy platforms with regenerative mechanisms over pure hardware plays facing biosimilar pressure. Watch IRA Medicare negotiation provisions for CNS-targeted agents as the inflection signal for generic formulation entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Submission | Compresses neurostimulation device review timelines for hospital system first-access positioning. |
| Hospital System Partnership | Secures pre-negotiated procurement frameworks ahead of formal regulatory clearance. |
| Software Companion Development | Enables closed-loop parameter automation reducing per-patient labor intensity. |
| CE Marking Pathway | Opens German and Swiss university hospital networks to European commercialization. |
| Reimbursement Strategy | Determines bundled therapy model sustainability against unbundled alternatives in Medicare coding. |
Study Parameters
Multiple input streams — neurostimulation device regulatory filings, rehabilitation center procurement databases, and CNS pharmaceutical prescription audits — were reconciled through bottom-up and top-down triangulation. Primary interviews with FDA regulatory affairs leads, hospital GPO contracts managers, German rehabilitation network procurement directors, and Japanese PMDA submission consultants informed demand-side validation. Secondary sources included FDA 510(k) and PMA databases, EMA MDR technical documentation, CMS Medicare reimbursement coding updates, and hospital system annual procurement disclosures.
Data-stream reconciliation across product type, delivery mode, end user, and treatment approach segmentation generated volume and value outputs over the projection horizon. CAGRs were derived from patient population epidemiology, device replacement cycles, and prescription volume trajectories modeled through the analysis window. Forecast inputs incorporated neurostimulation hardware-software integration adoption curves and IRA Medicare negotiation provision impacts on pharmacological agent pricing.
Regulatory approval delays, reimbursement coding fragmentation, and neurorehabilitation workforce scarcity are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Italy Neurology Devices Market
Neurology
Neurocutaneous Disorders Market
Neurology
3D Neuroscience Market
Neurology
Sweden Neurology Devices Market
Neurology
Bell Palsy Treatment Market
Neurology
Vocal Cord Paralysis Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Spain Neurology Devices Market
Neurology
Global Acoustic Neuroma Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
South Korea Neurology Devices Market
Neurology
CNS Treatment and Therapy Market
Neurology
Global Sciatica Treatment Market
Neurology
Chile Neurology Devices Market
Neurology
Cognitive Neuroscience Market
Neurology
Neurological Biomarkers Market