
 Distal Embolic Filters Market | 2026-2036
Distal Embolic Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Distal Embolic Filters Market Outlook
North American manufacturing capacity for nitinol-based filter components is narrowing as domestic producers respond to supply chain rebalancing. Boston Scientific Corporation leverages in-house wire-forming capabilities to sustain cost advantages across its embolic protection portfolio. Medtronic plc anchors its position through deep catheter integration with structural heart platforms. Abbott Laboratories differentiates via radiopaque marker technology that enhances fluoroscopic visibility during complex arch interventions.
Distal embolic filters are intravascular devices constructed from laser-cut nitinol or woven polymer meshes, typically ranging from 3.5 to 8.0 mm in expanded diameter, designed to capture atheroembolic debris during endovascular procedures. Their primary commercial purpose is stroke prevention during carotid artery stenting and protection against distal ischemia in saphenous vein graft interventions. Wire mesh filters currently lead procedural volume due to established reimbursement and physician familiarity, while drug-eluting filter technology represents the fastest-growing segment as anti-thrombotic surface coatings reduce periprocedural microembolic events. Hospitals command the dominant end-user channel, though outpatient clinics are gaining share as same-day discharge protocols expand for lower-risk peripheral vascular cases.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence thresholds for market access. Japan's PMDA enforces stringent biocompatibility testing under JIS T 0993 standards that filter manufacturers must satisfy before reimbursement listing. Stakeholders should monitor evolving CMS coverage determinations for transcarotid artery revascularization with embolic protection, as these decisions will directly filter through to hospital procurement priorities and manufacturer R&D allocation.
Market Dynamics
Endovascular repair suites in tertiary hospitals are expanding filter utilization as aging populations in the United States, Germany, and Japan drive procedural volumes. FDA premarket notification pathways and EU MDR conformity requirements are tightening performance benchmarks for embolic protection devices, compressing development timelines and elevating clinical evidence thresholds.
Growth Catalysts
- EU MDR technical documentation:Stricter conformity requirements are accelerating R&D investment in next-generation filter designs with enhanced biocompatibility profiles.
- Carotid artery stenting volumes:Rising stroke prevention procedures in Japanese tertiary centers are expanding addressable demand for distal protection devices.
- Laser-cut nitinol manufacturing:Precision wire-forming capabilities are enabling thinner strut geometries that improve vessel wall apposition and debris capture efficiency.
Market Restraints
- Nitinol supply concentration:North American manufacturing capacity for wire-forming components has narrowed as domestic producers rebalance supply chains.
- FDA 510(k) pathway friction:Premarket notification requirements for predicate device equivalence are extending time-to-market for novel filter geometries.
- Drug-eluting stent substitution:Alternative embolic protection strategies in saphenous vein graft interventions are limiting filter penetration in select cardiac procedures.
Strategic Opportunities
- German outpatient clinic expansion:Same-day discharge protocols for lower-risk peripheral vascular cases are creating new channel access beyond hospital procurement.
- Anti-thrombotic surface coatings:Drug-eluting filter technology convergence with polymer science is opening premium pricing tiers for microembolic event reduction.
- CMS coverage determination tailwinds:Evolving reimbursement policy for transcarotid artery revascularization with embolic protection will redirect hospital procurement priorities.
Industry Challenges
- ISO 10993 biocompatibility certification timelines:Extended cytotoxicity and sensitization testing protocols are delaying PMDA reimbursement listing in Japan.
- Fluoroscopic integration complexity:Radiopaque marker placement precision requirements are demanding specialized catheter engineering talent that remains scarce.
- Legacy hospital IT infrastructure:Digital workflow integration for procedure documentation is creating implementation friction in mid-tier US facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distal Embolic Filters Market |
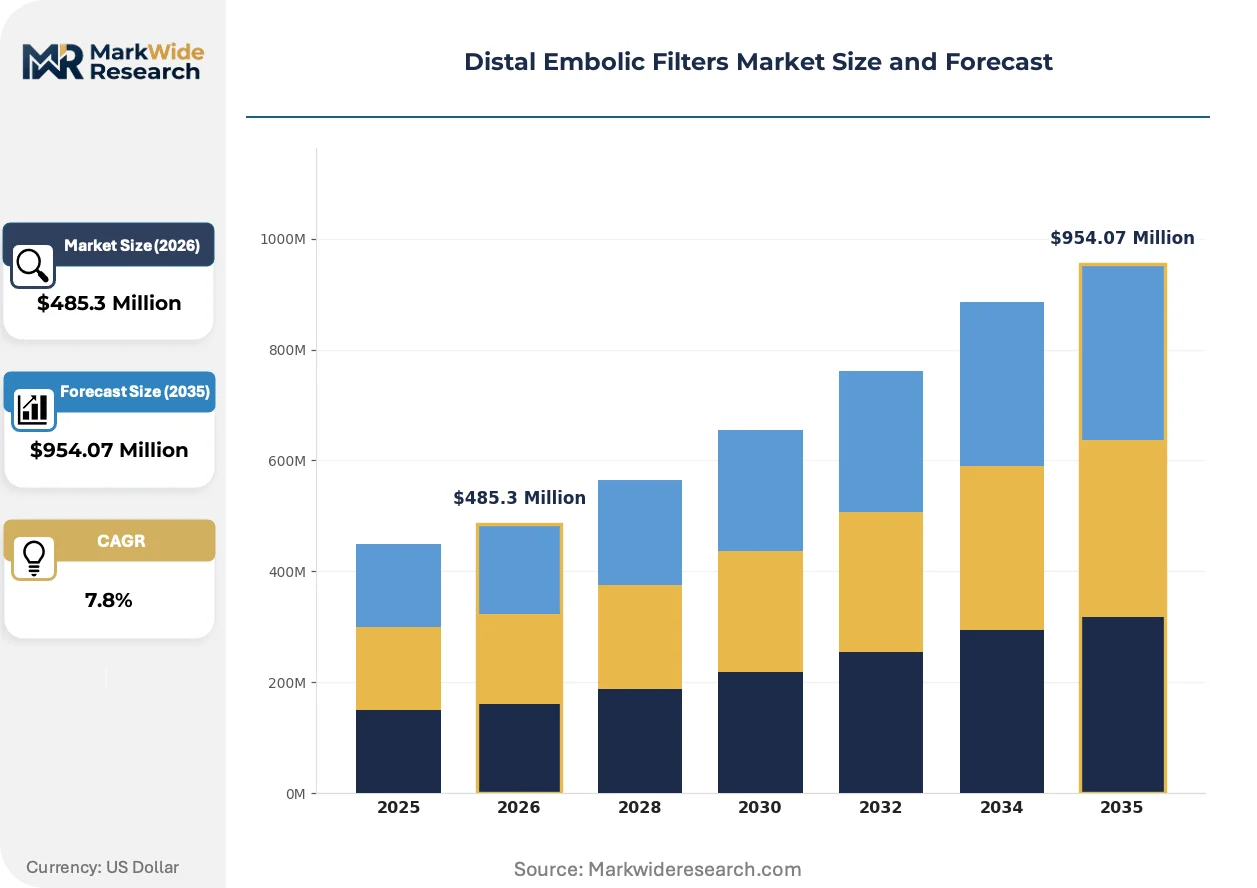
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $954.07 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Filters, Fiber Filters, Wire Mesh Filters, Mechanical Filters Application: Cerebrovascular Procedures, Peripheral Vascular Procedures, Cardiac Interventions, Endovascular Repair End User: Hospitals, Outpatient Clinics, Surgical Centers, Academic Research Institutions Technology: Biodegradable Filters, Radiopaque Filters, Anti-thrombotic Filters, Drug-eluting Filters |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Abbott Laboratories, Cardinal Health, Inc., Terumo Corporation, Cook Medical LLC, Edwards Lifesciences Corporation, W.L. Gore & Associates, Silk Road Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distal Embolic Filters Market Strategic Shifts
Active technological substitution is compressing traditional filter architectures as device manufacturers pursue differentiated clinical outcomes. Regulatory frameworks are simultaneously elevating evidence standards and opening reimbursement pathways that reward innovation.
Drug-eluting filter surfaces with heparin or phosphorylcholine coatings are capturing periprocedural microembolic debris with superior efficiency to bare nitinol meshes. Interventional cardiologists in German and Japanese academic medical centers are adopting these platforms for high-risk carotid interventions. Conventional wire mesh filters without surface modification are rendering obsolete for complex arch anatomy cases where thrombogenicity risk concentrates.
Japan's PMDA has tightened JIS T 0993 biocompatibility testing requirements for intravascular devices, mandating extended cytotoxicity validation that adds six to nine months to regulatory timelines. Manufacturers are responding by front-loading biocompatibility testing into early prototype phases rather than final validation stages. Filter suppliers targeting Japanese reimbursement listing are absorbing these compliance costs to secure priority access to the world's second-largest procedural market.
Hospital procurement committees are consolidating vendor relationships around integrated structural heart platforms rather than standalone embolic protection devices. Cardiovascular service line directors in US health systems are bundling filter procurement with catheter and stent contracts to extract volume discounts. This concentration dynamic is most visible in integrated delivery networks across Texas and Florida, where standardized device formularies are displacing physician-specific product preferences.
Distal Embolic Filters Market Segmentation
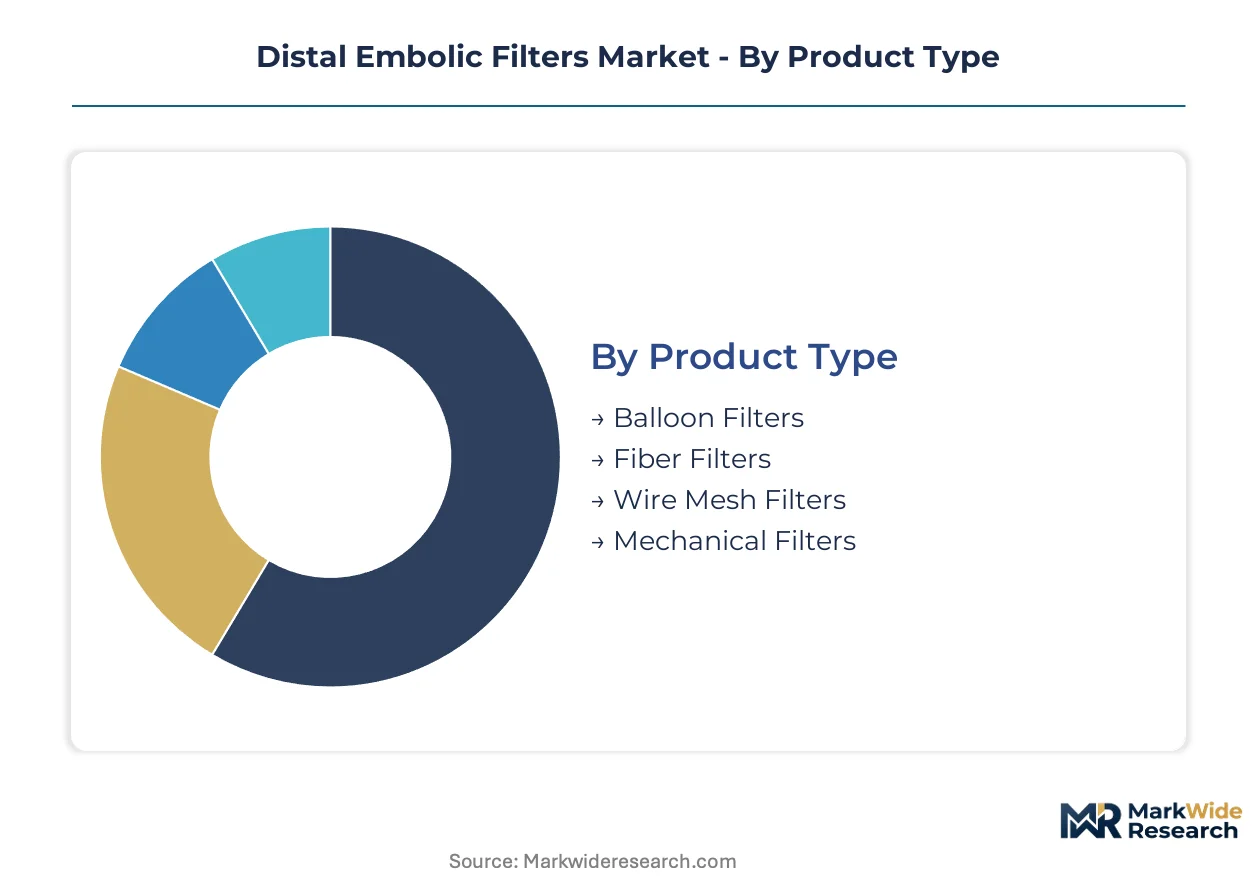
Segmentation in distal embolic filters reveals how procurement committees balance clinical performance against total cost of ownership. Device selection varies sharply by procedural setting, with tertiary hospitals prioritizing integrated platform compatibility while outpatient clinics emphasize single-use economics.
Product Type:
After-sales service intensity concentrates in wire mesh and mechanical filter segments, where device retrieval complications and procedural failure rates drive field engineering support contracts.
- Wire Mesh Filters:Laser-cut nitinol construction delivers radial force consistency across vessel tortuosity. United States tertiary centers favor these platforms for carotid stenting procedures where established reimbursement codes anchor procurement volume.
- Drug-eluting Filters:Anti-thrombotic surface coatings with heparin or phosphorylcholine chemistry reduce periprocedural microembolic events. German academic medical centers are adopting these platforms fastest for high-risk arch interventions where thrombogenicity risk concentrates.
- Balloon Filters:Occlusive balloon designs temporarily arrest flow during debris capture. Compact profiles suit distal vessel applications where anatomical constraints limit filter landing zone options.
- Fiber Filters:Woven polymer mesh architectures offer compliant vessel wall apposition. Lower unit costs attract outpatient clinic procurement committees managing constrained capital budgets.
- Mechanical Filters:Articulated basket mechanisms with independent strut movement adapt to irregular lumen geometries. Complex retrieval protocols demand specialized operator training and dedicated technical support.
Wire mesh filters hold the largest share; momentum sits with drug-eluting platforms.
Application:
Volume concentration patterns diverge between stroke prevention procedures and peripheral vascular interventions, with reimbursement density shaping manufacturer R&D allocation.
- Cerebrovascular Procedures:Carotid artery stenting with embolic protection dominates procedural economics. Japanese tertiary hospitals drive addressable demand as aging demographics expand eligible patient pools.
- Cardiac Interventions:Saphenous vein graft protection during percutaneous coronary intervention captures debris from degenerated conduit disease. Alternative protection strategies including proximal occlusion devices constrain filter penetration in this segment.
- Peripheral Vascular Procedures:Lower extremity arterial interventions utilize smaller-profile filters adapted to tibial and peroneal vessel diameters. Same-day discharge protocols in German outpatient clinics are expanding procedural access beyond traditional hospital settings.
- Endovascular Repair:Thoracic and abdominal aortic procedures deploy filters to protect visceral and renal branches during fenestrated or branched stent-graft deployment. Complex anatomical planning requirements integrate filter selection into preoperative imaging workflows.
Cerebrovascular applications anchor revenue concentration; peripheral vascular procedures are climbing the fastest.
End User:
Customer-type segmentation reveals procurement authority fragmentation between cardiovascular service line directors and materials management departments.
- Hospitals:Integrated delivery networks in Texas and Florida are consolidating vendor relationships around bundled contracts spanning catheters, stents, and protection devices. Standardized formularies increasingly displace physician-specific product preferences.
- Outpatient Clinics:Ambulatory surgical centers in Germany are capturing lower-risk peripheral vascular cases through same-day discharge protocols. Capital equipment constraints favor single-use disposable filters over reusable platform investments.
- Surgical Centers:Dedicated cardiovascular facilities concentrate procedural volume for manufacturer volume discount negotiations. Limited inventory capacity drives preference for universal sizing platforms reducing SKU complexity.
- Academic Research Institutions:Investigational device exemption pathways support next-generation filter evaluation. Publication requirements for novel surface coatings or biodegradable materials extend development timelines.
Hospitals command dominant procurement volume; outpatient clinics are gaining share fastest.
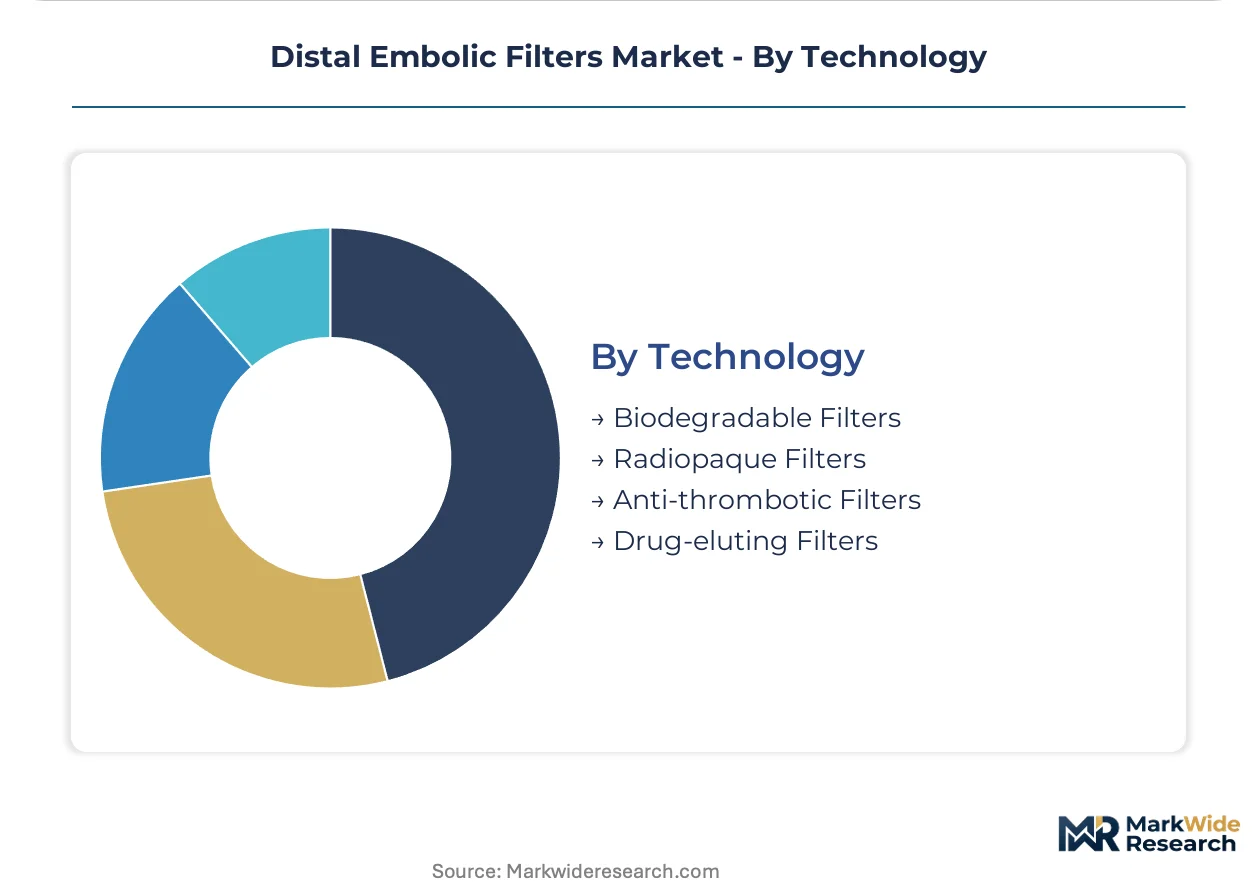
Technology:
Technology segmentation tracks convergence between materials science advances and regulatory evidence requirements for premium reimbursement positioning.
- Radiopaque Filters:Enhanced fluoroscopic visibility through platinum-iridium or tantalum marker integration enables precise deployment in complex arch anatomy. Japanese PMDA biocompatibility testing under JIS T 0993 standards adds six to nine months to regulatory timelines for marker-containing devices.
- Drug-eluting Filters:Polymer-based drug delivery surfaces release anti-thrombotic agents during the highest-risk procedural window. Surface chemistry validation demands extended cytotoxicity protocols that manufacturers are front-loading into early prototype phases.
- Biodegradable Filters:Absorbable polymer matrices eliminate retrieval requirements and reduce late complications. Degradation kinetics must align with procedural debris burden timelines, constraining clinical applicability.
- Anti-thrombotic Filters:Passive surface modifications including phosphorylcholine coatings reduce protein adhesion without pharmaceutical agents. Lower regulatory burden compared to drug-eluting platforms accelerates time-to-market.
Radiopaque technology holds installed base dominance; drug-eluting platforms show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. Japanese tertiary hospitals prioritize biocompatibility certification under JIS T 0993 standards, while German outpatient clinics emphasize single-use economics for same-day discharge protocols. United States integrated delivery networks bundle procurement across structural heart platforms.
United States
Texas and Florida health systems drive procedural volume through standardized device formularies that displace physician-specific preferences. FDA 510(k) premarket notification pathways compress development timelines while elevating predicate device equivalence requirements. The Greater Boston cluster anchors academic medical center adoption of next-generation filter architectures for complex arch interventions.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia capture lower-risk peripheral vascular cases through expanded same-day discharge protocols. EU MDR technical documentation requirements mandate enhanced clinical evidence thresholds for biocompatibility validation. The Baden-Württemberg medical technology corridor concentrates precision wire-forming capabilities for nitinol component manufacturing.
Japan
Aging demographics in the Kanto region expand eligible patient pools for carotid artery stenting procedures in Tokyo academic medical centers. PMDA enforces stringent JIS T 0993 biocompatibility testing standards that extend regulatory timelines by six to nine months. The Osaka-Kansai cluster houses specialized catheter engineering talent for fluoroscopic integration development.
United Kingdom
NHS procurement frameworks prioritize total cost of ownership calculations for embolic protection device selection across cardiovascular service lines. MHRA post-market surveillance requirements align with EU MDR conformity standards following regulatory divergence. The Cambridge-Oxford-London triangle concentrates investigational device evaluation for biodegradable filter platforms.
China
Tier-1 hospitals in Beijing and Shanghai expand endovascular repair suite capacity for thoracic aortic procedures requiring branch protection. NMPA medical device registration pathways demand domestic clinical trial data for imported filter technologies. The Yangtze River Delta manufacturing base develops laser-cut nitinol capabilities to reduce import dependency for wire-forming components.
Distal Embolic Filters Market Competitive Environment
Capability concentration sits with integrated structural heart platform providers; scale advantage sits with diversified cardiovascular device conglomerates. The market structure reflects a tiered hierarchy where deep catheter integration commands premium positioning against standalone filter specialists. Three archetypes dominate: platform-integrated manufacturers with captive supply chains, pure-play embolic protection specialists, and diversified medtech conglomerates leveraging cross-selling networks. Competitive moves center on strategic bundling contracts with integrated delivery networks and upstream control over nitinol wire-forming capacity.
Among diversified cardiovascular conglomerates, Boston Scientific Corporation, Medtronic plc, and Abbott Laboratories occupy positions that exemplify platform integration strategy. Boston Scientific leverages in-house wire-forming capabilities as a structural cost anchor. Medtronic represents deep catheter integration with structural heart ecosystems. Abbott exemplifies differentiated positioning through radiopaque marker technology specialization. These three manufacturers sit within the tier that commands procurement committee attention through bundled contract structures rather than standalone device economics.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Cardinal Health, Inc. |
| Terumo Corporation |
| Cook Medical LLC |
| Edwards Lifesciences Corporation |
| W.L. Gore & Associates |
| Silk Road Medical, Inc. |
| Others |
Value Chain & Pricing Dynamics
North American nitinol wire-forming capacity concentration anchors margin capture for integrated manufacturers while squeezing standalone filter specialists dependent on spot component markets. Laser-cut nitinol struts represent the dominant cost driver, with domestic producers commanding premium pricing for precision geometries below 100-micron tolerance thresholds.
Pricing Analysis
Long-term offtake agreements between integrated device manufacturers and nitinol suppliers anchor pricing stability for wire mesh and drug-eluting filter platforms. Three-tier pricing structure across premium, standard, and economy levels separates drug-eluting coated devices from bare nitinol meshes and fiber-based alternatives. Pricing pressure stems from hospital procurement committee consolidation around bundled structural heart contracts that commoditize standalone filter economics. Outpatient clinics in Germany exhibit highest price sensitivity due to capital equipment constraints, while Japanese academic medical centers absorb premium tiers for PMDA-certified biocompatibility profiles.
Supply Chain Analysis
Extended payment terms from integrated delivery networks in Texas and Florida are compressing working capital for mid-tier filter manufacturers without captive wire-forming capabilities. Supply concentrates in the United States, Germany, and Japan for precision nitinol laser-cutting and polymer mesh weaving. Raw material dependencies center on nickel-titanium alloy feedstock, radiopaque marker alloys, and anti-thrombotic coating polymers. Single-source vulnerability in nitinol wire supply creates procurement risk for non-integrated manufacturers. Distribution runs through GPO contracts and direct hospital procurement channels with limited aftermarket service intensity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized catheter engineering talent scarcity constrains fluoroscopic integration development, creating competitive moats for manufacturers with in-house precision marker placement capabilities. This capability gap widens as PMDA and FDA tighten radiopacity visibility requirements for complex arch interventions.
For Market Incumbents: Build regulatory certification moats by front-loading JIS T 0993 biocompatibility testing and FDA 510(k) predicate device libraries to compress competitor time-to-market. Deepen backward integration into laser-cut nitinol manufacturing to defend margin position against supply chain rebalancing. Consolidate vendor relationships with integrated delivery networks through bundled catheter-stent-filter contracts that displace standalone competitors. Drug-eluting filter substitution and CMS coverage determination shifts represent primary threats requiring reimbursement strategy investment. For New Entrants and Emerging Players: German outpatient clinics for lower-risk peripheral vascular procedures represent the most penetrable entry point, bypassing entrenched hospital procurement committees in the United States and Japan. Anti-thrombotic surface coating partnerships with polymer science specialists offer differentiation without full vertical integration. Target academic research institution investigational device exemption pathways for biodegradable filter platforms to build clinical evidence before commercial scale. Channel strategy should emphasize direct clinic sales bypassing GPO contract complexity. For Investors and Strategic Acquirers: Capital is best deployed toward precision wire-forming specialists with nitinol laser-cutting capabilities and established FDA 510(k) clearances. Long-term viability over the next decade hinges on regulatory certification asset accumulation rather than pure volume scale. Acquisition targets should demonstrate integrated catheter engineering teams with fluoroscopic marker integration expertise. Watch for CMS national coverage determination announcements for transcarotid artery revascularization with embolic protection as the inflection signal redirecting hospital procurement priorities.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Biocompatibility Certification | JIS T 0993 compliance secures priority access to Japan's procedural market and reimbursement listing. |
| Backward Integration into Nitinol Wire-Forming | In-house laser-cutting capabilities reduce dependency on concentrated North American supplier base. |
| Hospital System Partnership | Bundled contracts with Texas and Florida integrated delivery networks displace physician-specific preferences. |
| Drug-Eluting Surface Development | Heparin and phosphorylcholine coatings command premium pricing for microembolic event reduction. |
| Reimbursement Strategy Investment | CMS coverage determination alignment redirects procurement committee priorities toward protected platforms. |
Study Parameters
Desk research of FDA 510(k) filings, EU MDR technical documentation, PMDA reimbursement databases, and hospital procurement records preceded structured interviews with interventional cardiologists, cardiovascular service line directors, GPO contracts managers, and biomedical engineers. Primary fieldwork across tertiary hospitals in the United States, Germany, and Japan validated secondary demand estimates. Bottom-up procedural volume modeling triangulated against top-down manufacturer revenue segmentation across the analysis window.
Assumptions held fixed include prevailing FDA and EU MDR regulatory pathways, CMS reimbursement frameworks, and nitinol supply chain configurations. Variable conditions encompassed PMDA timeline acceleration, German outpatient clinic expansion velocity, and drug-eluting filter adoption curves. Segmentation dimensions spanned product type, application, end user, and technology tier with regional regulatory cluster overlays. CAGRs derived from log-linear trend extrapolation calibrated to procedural volume elasticity against demographic aging patterns.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, nitinol commodity pricing, or transcatheter procedure reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline stability and supply chain concentration persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Digital Intraoral Camera Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Intravaginal Device Market
Medical Devices
Powered Mattress System Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
3D Printed Medical Devices Market