
 Aortic Aneurysm Market | 2026-2036
Aortic Aneurysm Market Size, Share, and Industry Trends Forecast 2026-2036
Aortic Aneurysm Market Intelligence
The European Union's push for sustainable product lifecycles under the Green Deal is recalibrating material selection and disposal protocols for single-use components in aortic repair kits. Medtronic leverages its extensive R&D pipeline to develop next-generation stent grafts with improved deployment accuracy. Cook Medical sustains its market position through a specialized focus on endovascular therapies. W. L. Gore & Associates differentiates with its proprietary ePTFE material technology for highly durable vascular grafts.
Aortic aneurysm treatment involves the reinforcement or replacement of a weakened, bulging section of the aorta. This is achieved using devices like stent grafts, which are fabric tubes supported by a metal mesh, or synthetic vascular grafts for open surgical repair. Stent Grafts for Endovascular Repair constitute the largest product segment, driven by preferences for less invasive procedures. Treatment for Abdominal Aortic Aneurysm holds a dominant share, though Thoracic Aortic Aneurysm procedures show faster adoption rates.
Device approval pathways are governed by stringent bodies, including the US FDA, Europe's EMA which enforces the Medical Device Regulation (MDR), and China's NMPA. These agencies mandate extensive pre-market clinical trials and post-market surveillance, directly influencing product development timelines and market access. Stakeholder success depends on navigating the evolving requirements for long-term clinical evidence and demonstrating superior patient outcomes with new device iterations.
Market Dynamics
The central force shaping the market is the tension between the push for minimally invasive procedures and increasingly stringent clinical evidence requirements from regulators like the FDA and EMA. This dynamic dictates R&D priorities and market access timelines.
Growth Catalysts
- Aging Global Demographics:Rising aneurysm incidence in aging populations, particularly in Japan and Germany, expands the addressable patient pool.
- Minimally Invasive Technology Adoption:Strong clinical preference for EVAR and TEVAR is driven by shorter recovery times and reduced morbidity in cardiac surgery centers.
- Advanced Diagnostic Imaging:Improvements in CT angiography and MRI enable earlier, more accurate aneurysm detection, increasing the volume of identified cases.
Market Restraints
- High Procedure Costs:The expense of stent grafts and endovascular procedures limits patient access in healthcare systems with constrained budgets.
- Anatomical Ineligibility:A patient cohort with complex aortic anatomy, such as severe neck angulation, cannot be treated with standard EVAR devices.
- Post-Implantation Surveillance:The risk of endoleaks necessitates lifelong patient imaging, creating a substantial long-term cost burden for hospitals.
Strategic Opportunities
- Fenestrated and Branched Devices:Developing devices for complex juxtarenal aneurysms opens a market previously only accessible via open surgery.
- Emerging Market Penetration:Expanding access to affordable endovascular solutions in countries like Brazil and India represents a significant growth vector.
- Bio-absorbable Materials:Research into grafts that promote tissue regeneration and dissolve could eliminate long-term device complications and surveillance needs.
Industry Challenges
- Specialized Physician Training:Successful deployment of advanced endovascular devices requires extensive training for vascular surgeons, creating a bottleneck for wider adoption.
- Navigating Global Regulatory Pathways:Securing approval from the FDA, EMA, and NMPA involves long, expensive trials with varying evidence requirements, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aortic Aneurysm Market |
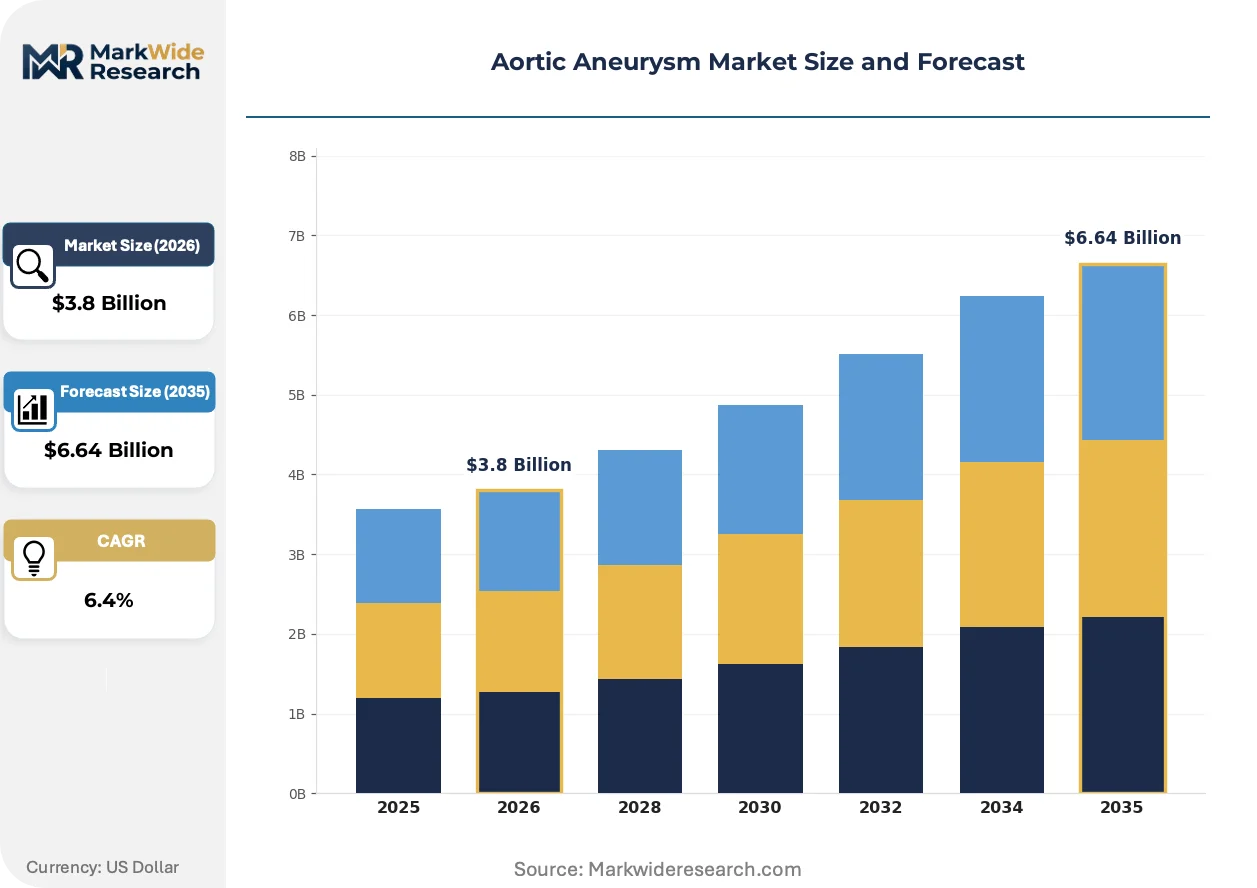
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Grafts, Surgical Sutures, Vascular Grafts, Endovascular Coils Therapy Area: Thoracic Aortic Aneurysm, Abdominal Aortic Aneurysm, Thoracoabdominal Aneurysm, Iliac Artery Aneurysm End User: Cardiac Surgery Centers, Specialized Clinics, Diagnostic Laboratories, Vascular Care Units Delivery Mode: Open Surgery, Endovascular Repair, Hybrid Repair, Non-invasive Monitoring |
| Companies Covered | Boston Scientific Corporation, MicroPort Scientific Corporation, Medtronic, Artivion, Endologix, W. L. Gore & Associates, Terumo Corporation, Cardinal Health, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aortic Aneurysm Market Strategic Shifts & Innovations
Device evolution focuses on improving deployment precision and expanding anatomical applicability. This push for technical sophistication is balanced by regulatory demands for long-term outcome data, influencing material science and clinical trial design.
Smart stent grafts incorporate embedded sensors to provide real-time feedback on pressure and device position. Interventional radiologists in academic medical centers are the primary adopters, though use remains in early stages. This technology is integrating diagnostic capabilities into the therapeutic device, potentially reducing follow-up imaging.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance. This forces manufacturers to conduct more rigorous studies to prove the safety of aortic devices. Stent graft producers are most affected, now needing comprehensive clinical data to maintain CE marking.
A shift toward value-based healthcare is altering how hospitals procure aortic devices. Large hospital networks negotiate contracts based on demonstrated patient outcomes and reduced total cost of care, including fewer re-interventions. This trend is most visible within integrated healthcare systems in the United States.
Aortic Aneurysm Market Segmentation
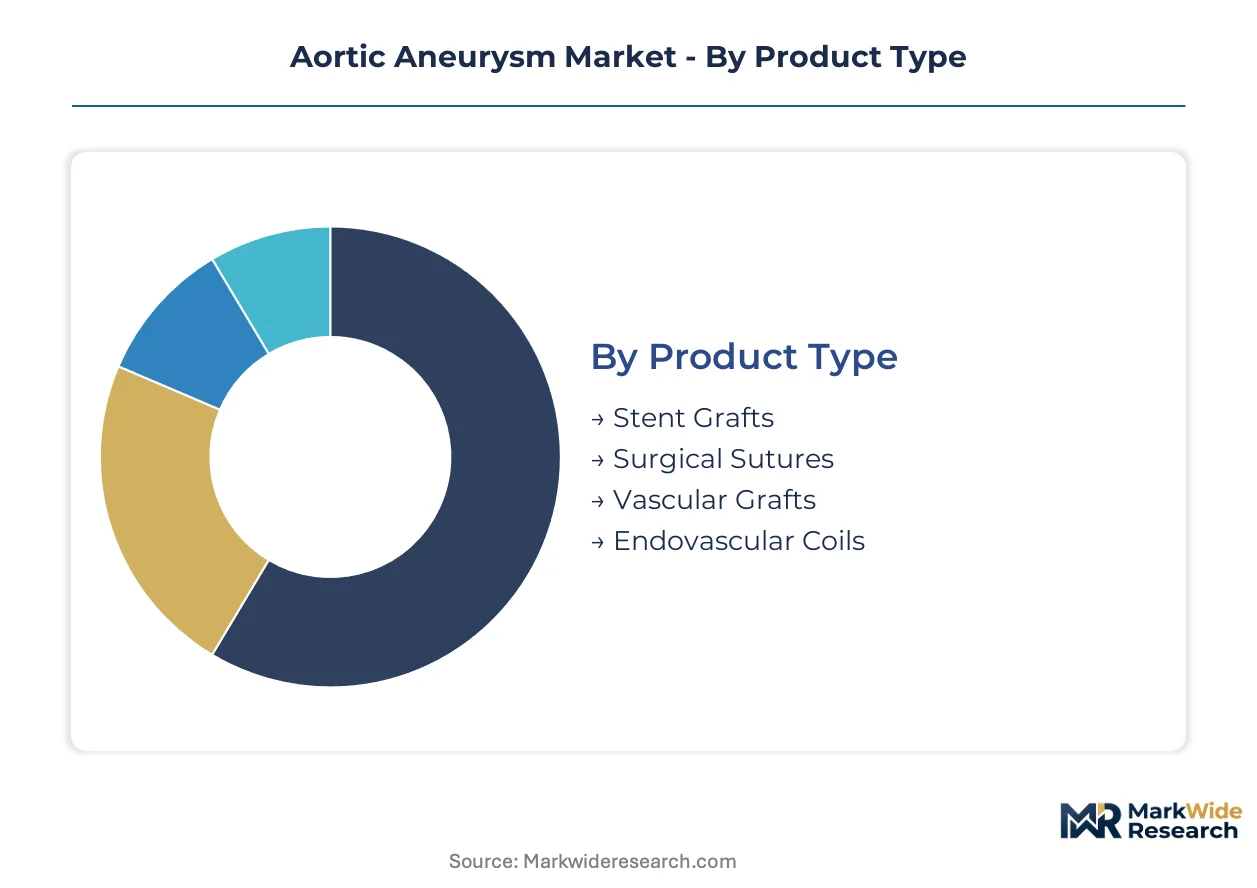
The Aortic Aneurysm Market exhibits diverse segmentation, reflecting the varied approaches to diagnosis, treatment, and patient care. Understanding these distinct segments is crucial for stakeholders to identify areas of unmet need and to tailor product development and market strategies effectively.
Product Type:
Product differentiation across this category reflects a spectrum from highly customized, patient-specific devices to more standardized, off-the-shelf solutions for common anatomical presentations.
- Stent Grafts:These devices are fabric tubes supported by a metal mesh, deployed minimally invasively to reinforce weakened aortic sections. Demand for these advanced devices is concentrating in specialized vascular care units in Germany, driven by preferences for less invasive procedures.
- Vascular Grafts:Synthetic tubes made from materials like ePTFE or Dacron, used for open surgical repair to replace diseased aortic segments. Hospitals in Japan frequently utilize these durable grafts for complex cases where endovascular repair is not feasible.
- Surgical Sutures:Essential consumables for traditional open surgical aneurysm repair, providing secure tissue approximation and wound closure.
- Endovascular Coils:Small, detachable platinum coils used to occlude aneurysms, particularly in smaller vessels or for specific aneurysm morphologies.
Most installed capacity flows through Stent Grafts. Expansion is steepest in Stent Grafts.
Therapy Area:
Therapy areas delineate the specific anatomical locations of aneurysms, guiding device design and procedural specialization.
- Abdominal Aortic Aneurysm:Involves a bulge in the lower part of the aorta, below the diaphragm, representing the dominant share of treated cases. Treatment for this condition sees high procedure volumes in cardiac surgery centers across the United States.
- Thoracic Aortic Aneurysm:Affects the upper part of the aorta, within the chest, and procedures for this condition show faster adoption rates for advanced endovascular techniques. Hospitals in the United Kingdom are increasingly adopting these specialized treatments.
- Thoracoabdominal Aneurysm:A complex condition spanning both thoracic and abdominal segments of the aorta, requiring highly specialized surgical or endovascular approaches.
- Iliac Artery Aneurysm:Involves the iliac arteries branching off the aorta, often managed with smaller endovascular grafts or coils.
Abdominal Aortic Aneurysm treatments generate the largest volume of procedures. Thoracic Aortic Aneurysm procedures are gaining share most rapidly.
End User:
The end-user landscape reflects the specialized infrastructure and expertise required for aortic aneurysm management.
- Cardiac Surgery Centers:Highly specialized facilities equipped for complex open-heart and vascular procedures, experiencing expanding demand for advanced treatment options. These centers in France are key adopters of innovative aortic repair technologies.
- Vascular Care Units:Dedicated units within hospitals focusing specifically on the diagnosis and treatment of vascular diseases, concentrating a significant portion of procedure volume. German vascular care units manage a high caseload of endovascular repairs.
- Specialized Clinics:Outpatient or ambulatory facilities offering diagnostic services and follow-up care for aneurysm patients, often referring complex cases to larger centers.
- Diagnostic Laboratories:Facilities primarily focused on imaging and blood tests for aneurysm detection and surveillance, playing a crucial role in early diagnosis.
Cardiac Surgery Centers represent the primary point of care for complex interventions. Vascular Care Units demonstrate the quickest expansion in patient throughput.
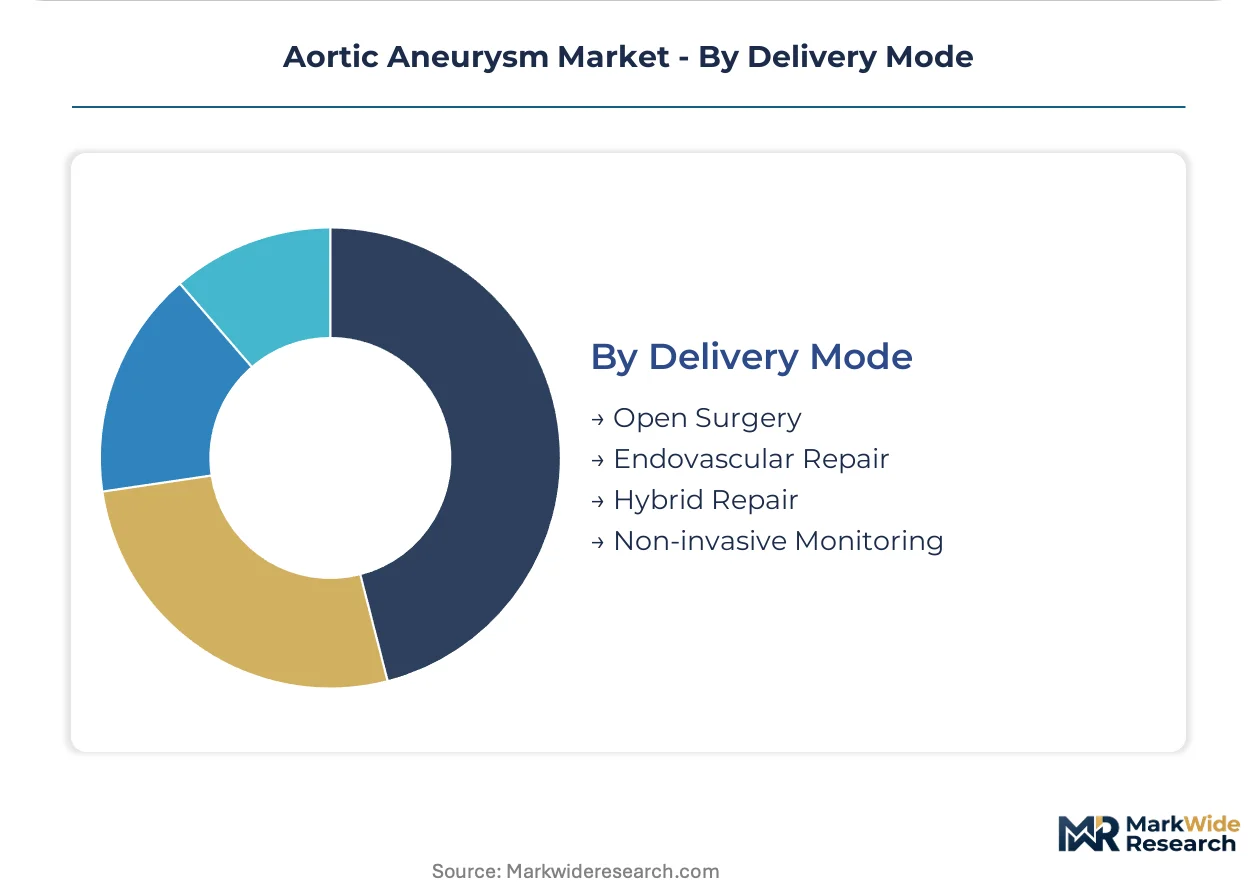
Delivery Mode:
Delivery modes illustrate the procedural approaches employed, ranging from highly invasive to minimally interventional techniques.
- Endovascular Repair:A minimally invasive procedure involving the insertion of stent grafts through small incisions, preferred for its shorter recovery times and reduced morbidity. This approach is widely adopted in Italian healthcare systems for suitable patients.
- Open Surgery:Traditional surgical method requiring a large incision to directly repair or replace the aneurysmal segment, still necessary for complex anatomies or device failures. Hospitals in Canada continue to perform open surgeries for specific patient cohorts.
- Hybrid Repair:Combines elements of both open surgery and endovascular techniques, often used for complex arch or thoracoabdominal aneurysms.
- Non-invasive Monitoring:Involves regular imaging and clinical assessment to track aneurysm growth in patients not yet requiring intervention.
Endovascular Repair procedures hold the largest market share due to patient preference. Non-invasive Monitoring is exhibiting the fastest growth in patient engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled workforce in specialized vascular care units anchors the demand for advanced aortic aneurysm treatments across several key global regions. These specialized facilities drive the adoption of complex endovascular devices. Regulatory frameworks significantly influence market access and product development timelines.
Germany
Demand for advanced stent grafts is concentrating in specialized vascular care units across Germany. The European Union's Medical Device Regulation (MDR) imposes stringent clinical evidence standards for new devices. German vascular care units in cities like Berlin and Munich manage a high caseload of endovascular repairs.
Japan
Japan's aging population expands the addressable patient pool for aortic aneurysm treatments. The Pharmaceuticals and Medical Devices Agency (PMDA) governs device approval pathways, emphasizing safety and efficacy. Hospitals in Tokyo and Osaka frequently utilize durable vascular grafts for complex cases.
United States
Expanding demand for advanced treatment options comes from cardiac surgery centers across the United States. The US FDA mandates extensive pre-market clinical trials and post-market surveillance for aortic devices. Integrated healthcare systems in regions like the Northeast are shifting towards value-based procurement.
United Kingdom
Hospitals in the United Kingdom are increasingly adopting specialized treatments for thoracic aortic aneurysms. The EMA's requirements for CE marking influence product availability and clinical data needs. Vascular centers in London and Manchester are key adopters of innovative endovascular techniques.
France
Cardiac surgery centers in France are key adopters of innovative aortic repair technologies. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) regulates medical device market access. Specialized vascular units in Paris and Lyon are at the forefront of implementing advanced endovascular procedures.
Aortic Aneurysm Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the Aortic Aneurysm Market, creating a tiered competitive structure. Large diversified medical device conglomerates often coexist with specialized niche players. Companies differentiate through proprietary material science or advanced deployment mechanisms. Dominant competitive moves include strategic partnerships for clinical trials and targeted acquisitions of innovative technology firms.
Medtronic, a global medical technology company, represents the archetype of a diversified leader leveraging extensive R&D pipelines for next-generation stent grafts. Cook Medical, a US-based privately held company, exemplifies a specialist focusing on endovascular therapies and maintaining its market position through targeted solutions. W. L. Gore & Associates, known for its innovative material science, occupies a distinct position by offering highly durable vascular grafts based on its proprietary ePTFE technology.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| MicroPort Scientific Corporation |
| Medtronic |
| Artivion |
| Endologix |
| W. L. Gore & Associates |
| Terumo Corporation |
| Cardinal Health |
| Cook Medical |
| Others |
Cost & Logistics Intelligence
Medical-grade titanium costs significantly influence stent graft material expenses, impacting overall device pricing across premium and standard tiers. These fluctuations affect manufacturer margins and hospital procurement budgets across Europe and the United States.
Pricing Analysis
Many aortic devices are sold with bundled services, including technical support and training for complex procedures. Value-based pricing is gaining traction, especially within integrated healthcare systems in the United States. Device customization for complex anatomies and proprietary material science, like W. L. Gore & Associates' ePTFE, drive premium pricing. Pricing softness reflects increasing competition and stringent hospital procurement strategies in Europe. Healthcare systems with constrained budgets, such as public systems in the United Kingdom, are most price-sensitive, while specialized cardiac surgery centers prioritize advanced, high-cost solutions.
Supply Chain Analysis
Direct sales forces and specialized medical distributors manage the distribution of aortic aneurysm devices to cardiac surgery centers and vascular care units. Manufacturing of advanced stent grafts concentrates in the United States, Germany, and Ireland. The supply chain relies on specialized medical-grade polymers, titanium alloys, and advanced textiles for stent graft fabrication. Single-source vulnerability for proprietary materials or specialized components poses a structural risk to production continuity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
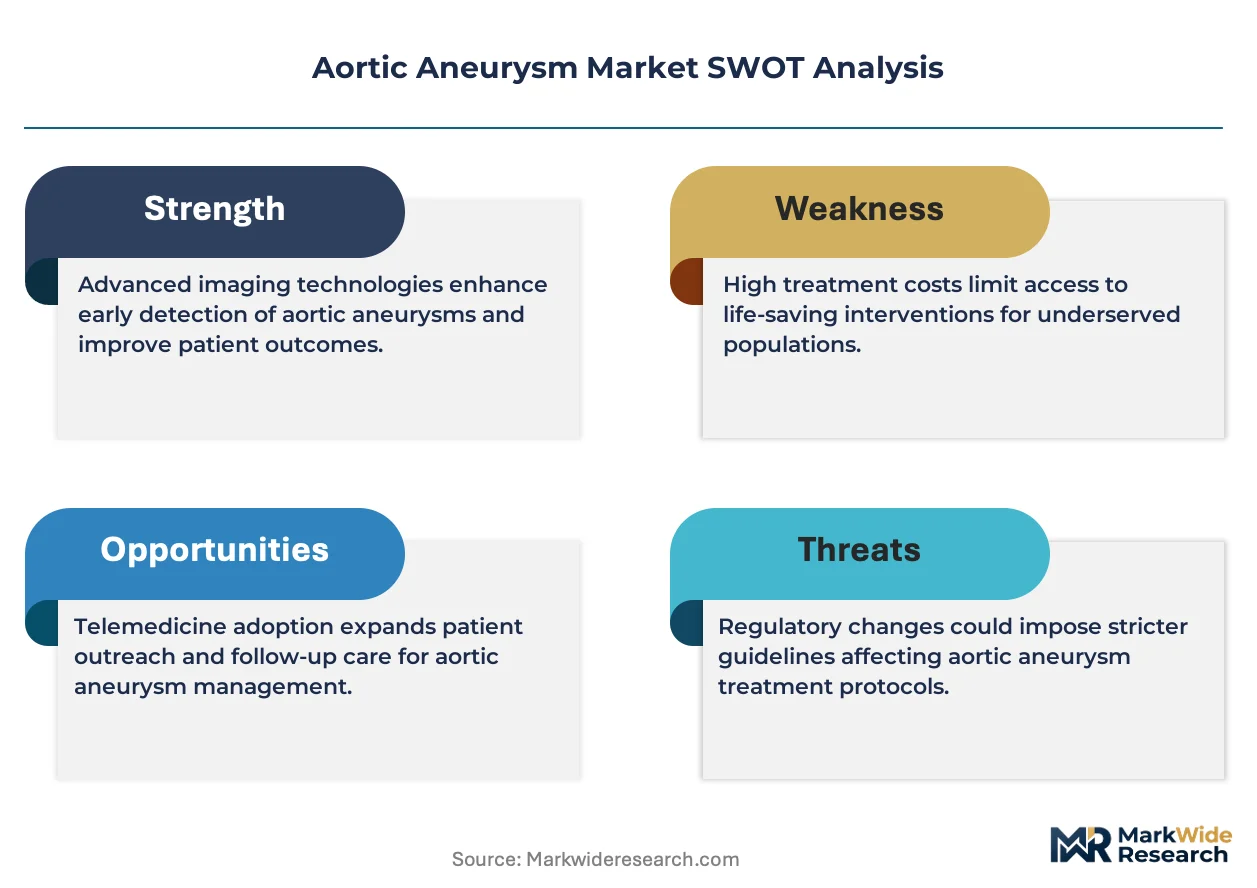
The Aortic Aneurysm Market is evolving into a late-cycle quality story, driven by a demand-shift toward premium stent grafts offering enhanced deployment accuracy. This reflects a maturation phase prioritizing superior patient outcomes.
For Market Incumbents: To counter increasing regulatory scrutiny and the emergence of niche competitors, Medtronic and Cook Medical should deepen R&D investments in bio-absorbable materials. Incumbents must expand their portfolios of fenestrated and branched devices to address complex anatomies, securing market share against specialized firms. Strategic partnerships for long-term clinical trials across Europe can reinforce device efficacy claims. Investment in advanced manufacturing in Germany can enhance production efficiency.
For New Entrants and Emerging Players: Begin with developing affordable endovascular solutions tailored for emerging markets like Brazil and India. Focus on underserved patient populations with less complex anatomies initially. The fastest-growing segment, Thoracic Aortic Aneurysm procedures, offers a penetrable entry point for innovative device designs. A go-to-market strategy centered on superior clinical evidence for specific anatomical challenges can differentiate new offerings.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized technological expertise meets increasing demand for complex aortic repair solutions. Long-term viability hinges on companies demonstrating superior patient outcomes and cost-effectiveness over a 5-10 year window. Target mid-sized firms with proprietary material science, such as advanced ePTFE technology, or innovative deployment systems. The signal to watch is the successful completion of large-scale, long-term clinical trials for next-generation smart stent grafts.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Bio-absorbable Grafts | This reduces long-term complications and surveillance needs for patients in the United States. |
| Expand Fenestrated Device Portfolio | This addresses complex juxtarenal aneurysms, widening the treatable patient pool in Germany. |
| Clinical Trial Partnerships in EU | This ensures compliance with stringent EU MDR requirements, maintaining market access for devices. |
| Emerging Market Product Adaptation | This unlocks significant growth vectors by catering to affordability needs in Brazil. |
| Smart Stent Graft Integration | This offers real-time feedback, potentially reducing follow-up imaging for patients in Japan. |
Research Approach
Direct dialogue with vascular surgeons, hospital procurement managers, regulatory affairs specialists, and device engineers informs the qualitative understanding. This primary research is complemented by extensive secondary validation. Publicly available data from the US FDA, Europe's EMA, and China's NMPA, alongside medical journal articles and company annual reports, provides foundational insights. A bottom-up approach estimates market size, while a top-down validation ensures consistency across the data.
A bottom-up approach estimates market size by aggregating procedure volumes and device ASPs across key geographies over the projection horizon. This is cross-referenced with top-down macroeconomic indicators. Segmentation dimensions modeled include product type, therapy area, end-user, delivery mode, and regional regulatory frameworks. Compound annual growth rates are derived from historical trends, projected patient demographics, and technological innovation rates. Key forecast inputs include aging population statistics and advanced diagnostic imaging adoption rates.
Several conditions sit outside the modeled scope, including specific insurance reimbursement policy changes and unforeseen global economic shocks. Forecasts reflect assumptions regarding current regulatory stability and technological development trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Anticoagulation Market