
 Global Vascular Embolization Market | 2026-2036
Global Vascular Embolization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Embolization Market Foresight
Germany is narrowing its catheter manufacturing deficit through dedicated cleanroom expansions in Baden-Württemberg and Bavaria. Cook Medical leverages vertical integration across coil winding and delivery catheter production to sustain margin control in European supply chains. Terumo Corporation anchors Asia-Pacific distribution through its Tokyo-based interventional systems division, while Boston Scientific Corporation differentiates via polymer science leadership in liquid embolic formulations.
Vascular embolization is a minimally invasive interventional technique that deploys mechanical or biological agents through catheters to occlude blood vessels, typically using platinum-tungsten alloys, polyvinyl alcohol particles, or ethylene-vinyl alcohol copolymers to achieve targeted flow cessation. The procedure serves primary clinical purposes in hemorrhage control, tumor starvation, and aneurysm isolation across interventional radiology and neuroradiology practice settings. Coil systems occupy the most mature margin pool within product type segmentation, while liquid embolics represent the fastest-growing category due to their conformability in complex arteriovenous malformation geometries. Hospital end users dominate volume procurement, though ambulatory surgical centers are capturing growing shares of uterine fibroid embolization cases as outpatient reimbursement frameworks evolve.
FDA premarket notification pathways and CE marking under the EU Medical Device Regulation shape product entry timelines and biocompatibility testing burdens for embolic device manufacturers. ISO 10993 biological evaluation standards and Japan's PMDA quality management requirements further stratify compliance costs across major commercial jurisdictions. Stakeholders must monitor evolving reimbursement decisions for embolization procedures in oncology and women's health as these determinations will redirect capital toward specific application segments.
Market Dynamics
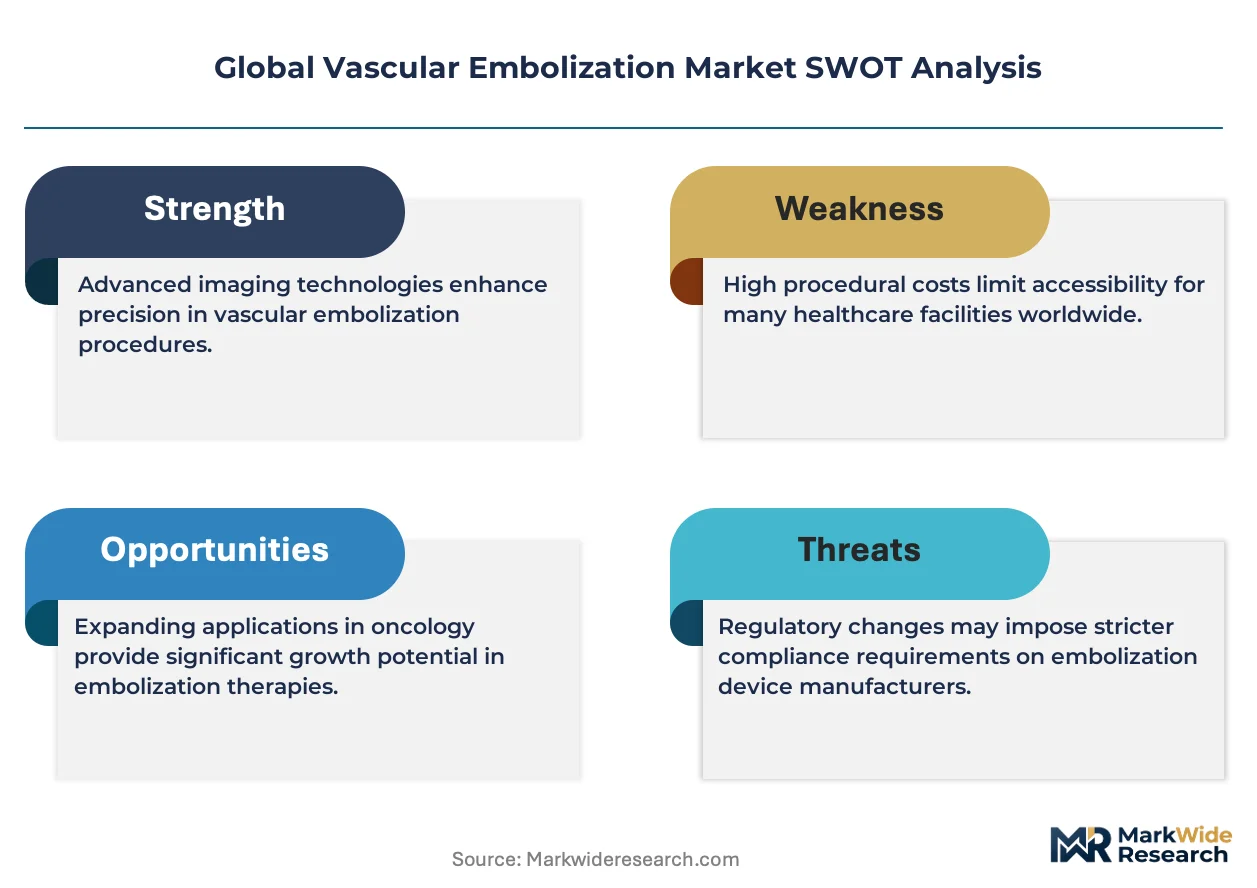
Platinum-tungsten alloy supply concentration in German and Japanese foundries is compressing coil manufacturing margins while forcing catheter OEMs to renegotiate long-term offtake agreements.
Growth Catalysts
- EU MDR biocompatibility mandates:Tighter ISO 10993 testing requirements for permanent implantables are accelerating replacement demand for legacy PVA particle systems with next-generation ethylene-vinyl alcohol copolymers.
- Stroke center construction:United States hospital systems are expanding dedicated neurointerventional suites to capture transferred hemorrhage cases from regional networks.
- Particle engineering advances:Calibrated microsphere production using precision extrusion is enabling sub-100-micron embolic deployment for hypervascular tumor indications.
Market Restraints
- Platinum price volatility:Coil winding operations face margin erosion when London Metal Exchange platinum futures spike above $1,000 per troy ounce.
- Cleanroom capacity bottlenecks:German catheter extrusion facilities in Baden-Württemberg operate at utilization rates exceeding 85%, constraining OEM expansion timelines.
- Liquid embolic learning curves:Complex arteriovenous malformation cases require 50+ supervised procedures before interventional neuroradiologists achieve proficiency with non-adhesive copolymer systems.
Strategic Opportunities
- Brazil stroke infrastructure:ANVISA fast-track pathways for hemorrhage control devices are opening procurement channels as São Paulo and Rio de Janeiro build tertiary neurovascular centers.
- Uterine fibroid outpatient migration:Ambulatory surgical centers in United States markets with evolved reimbursement frameworks are capturing cases previously hospitalized.
- AI-guided catheter navigation:Machine learning integration with fluoroscopy systems is digitizing procedure planning and reducing contrast dye volumes.
Industry Challenges
- Interventional neuroradiologist scarcity:Fellowship-trained specialists capable of complex aneurysm coiling remain concentrated in United States, German, and Japanese academic medical centers.
- FDA premarket notification timelines:510(k) submissions for novel liquid embolic formulations face extended review cycles when predicate device equivalency is disputed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Embolization Market |
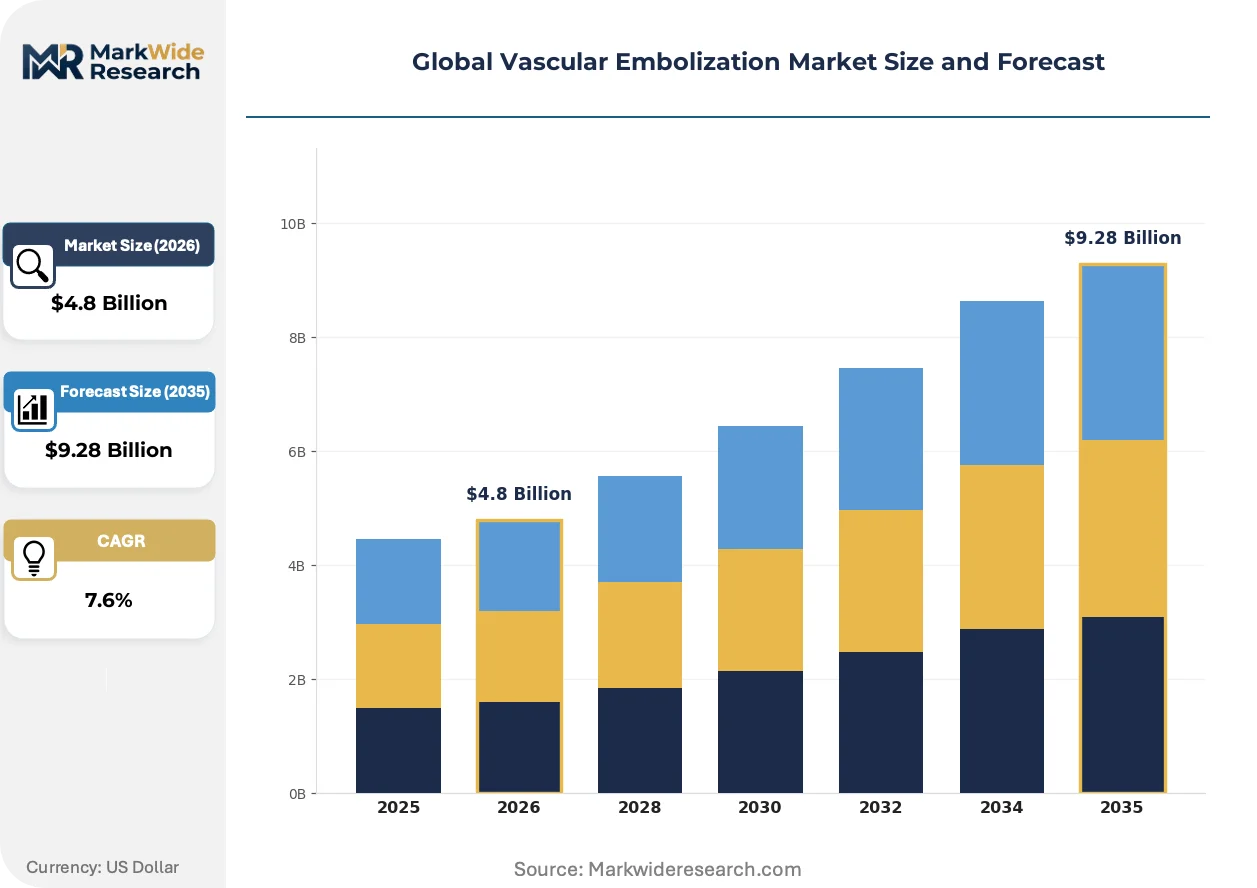
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coils, Particles, Liquids, Plugs, Balloons Application: Aneurysm Treatment, Tumor Devacularization, Gastrointestinal Bleeding, Uterine Fibroids Management, Arteriovenous Malformations End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Centers Deployment Model: Single-use Devices, Reusable Instruments, Disposable Kits, Sterile Packs |
| Companies Covered | Cook Medical, Terumo Corporation, Boston Scientific Corporation, Penumbra, Inc., Johnson & Johnson, Medtronic, Abbott Laboratories, Merit Medical Systems, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Embolization Market Shifts & Advancements
Digital workflow integration and materials science breakthroughs are compressing procedure times while expanding treatable anatomies beyond traditional coil-compatible morphologies.
Flow-diverting stent technology is digitizing aneurysm treatment protocols by enabling endoluminal reconstruction without parent vessel sacrifice. Academic medical centers in Germany and Japan are adopting these braided nitinol systems for giant and fusiform aneurysms previously deemed untreatable. The technology is digitizing surgical decision trees and redirecting volume from clipping procedures toward endovascular suites.
Japan's PMDA revised quality management requirements for class IV medical devices have extended sterilization validation timelines for coil systems manufactured outside the country. Domestic Tokyo-based producers are capturing share from imported devices as foreign OEMs absorb compliance costs. Neuroradiology departments are responding by dual-sourcing from PMDA-registered facilities to ensure supply continuity.
Hospital procurement committees are consolidating embolic device purchasing through single-source agreements tied to procedure volume commitments. United States integrated delivery networks are displacing fragmented catheter-by-catheter ordering with multi-year supply contracts spanning coils, liquid embolics, and delivery systems. This concentration is most visible in Texas and Florida markets where health system mergers have created super-regional purchasing entities.
Global Vascular Embolization Market Segmentation
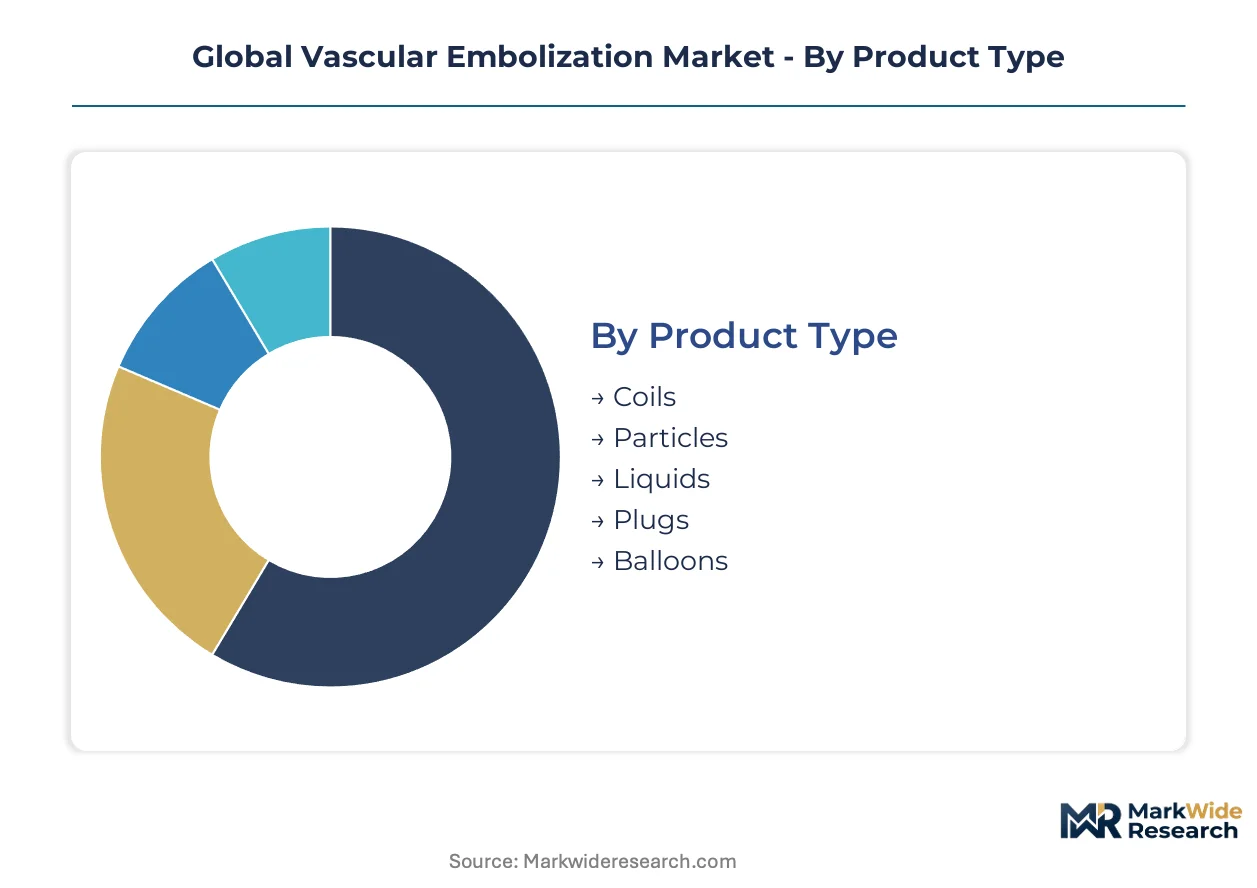
Vascular embolization devices fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct procurement patterns, margin structures, and service intensity requirements that shape vendor positioning.
Product Type:
After-sales service intensity varies sharply across mechanical and liquid platforms. Coil systems demand inventory management support and catheter compatibility verification. Liquid embolics require on-site training and procedural troubleshooting.
- Coils:Platinum-tungsten alloy windings deliver mechanical occlusion through thrombogenic framing and filling configurations. United States stroke centers are standardizing on 0.010-inch and 0.014-inch diameter systems to streamline inventory. Service contracts emphasize next-day coil availability and compatibility matrices across microcatheter brands.
- Liquids:Ethylene-vinyl alcohol copolymers and n-butyl cyanoacrylate formulations achieve conformal filling of complex arteriovenous malformation niduses. German neuroradiology departments are prioritizing non-adhesive copolymers to reduce catheter entrapment risk. Field clinical specialists maintain permanent presence at high-volume centers.
- Particles:Calibrated polyvinyl alcohol or tris-acryl gelatin microspheres enable distal embolization in hypervascular tumors.
- Plugs:Nitinol-based occlusion devices deploy through low-profile delivery systems for large-vessel embolization.
- Balloons:Temporary flow arrest balloons assist liquid embolic injection in high-flow fistulas.
By volume, coils lead. By growth pace, liquids are expanding most quickly.
Application:
Clinical indication determines reimbursement tier and capital equipment requirements. Aneurysm procedures command premium device pricing and specialized biplane angiography suites. Tumor applications operate under tighter cost constraints with higher volume throughput.
- Aneurysm Treatment:Intracranial and peripheral aneurysm coiling demands microcatheter precision and coil detachment reliability. Japanese academic medical centers are consolidating complex case referrals into designated neurovascular hubs. Reimbursement frameworks in Germany support same-day discharge for uncomplicated elective procedures.
- Tumor Devascularization:Hepatocellular carcinoma and renal cell carcinoma embolization requires calibrated particle sizing for target vessel penetration. United States interventional oncology practices are integrating embolization with immunotherapy protocols. Procedure scheduling flexibility drives preference for single-use particle systems.
- Gastrointestinal Bleeding:Emergency transcatheter embolization for upper and lower GI hemorrhage prioritizes rapid device availability.
- Uterine Fibroids Management:Uterine artery embolization for symptomatic fibroids is migrating toward ambulatory settings in evolved reimbursement markets.
- Arteriovenous Malformations:Congenital and acquired AVM embolization combines liquid and particulate agents in staged procedures.
By procedure volume, tumor devascularization leads. By reimbursement rate expansion, uterine fibroid management is climbing the fastest.
End User:
Facility type dictates purchasing authority structure and supply chain integration depth. Hospital systems negotiate enterprise contracts spanning multiple interventional service lines. Ambulatory centers prioritize consignment inventory and simplified logistics.
- Hospitals:Tertiary and community hospital interventional radiology departments maintain broad embolic inventories across all product categories. Texas and Florida integrated delivery networks are consolidating purchasing through super-regional procurement committees. Value analysis committees now require outcome data for liquid embolic adoption.
- Ambulatory Surgical Centers:Freestanding outpatient facilities are capturing uterine fibroid and select tumor embolization cases. United States markets with site-of-service payment differentials show accelerated ASC migration. Inventory models favor pre-packaged sterile kits over component-level ordering.
- Specialty Clinics:Dedicated interventional radiology and neuroradiology clinics concentrate procedure expertise.
- Diagnostic Centers:Imaging facilities with on-site interventional capabilities perform limited embolization procedures.
By installed base, hospitals lead. By growth pace, ambulatory surgical centers are gaining share fastest.
Deployment Model:
Packaging configuration influences sterilization validation burden and logistics complexity. Single-use devices eliminate reprocessing liability. Reusable instruments require hospital sterile processing department integration.
- Single-use Devices:Individually packaged coils, microcatheters, and guidewards arrive sterile and procedure-ready. OEMs are expanding automated packaging lines in Baden-Württemberg to meet United States and EU demand. Track-and-trace serialization is becoming mandatory under EU MDR.
- Disposable Kits:Pre-assembled procedure packs combining coils, microcatheters, and accessories reduce operating room setup time. Japanese stroke centers are adopting kit configurations for emergency aneurysm protocols. Kit customization creates vendor lock-in through proprietary component combinations.
- Reusable Instruments:High-value delivery systems and imaging equipment undergo hospital-based sterilization cycles.
- Sterile Packs:Bulk sterile packaging serves high-volume centers with established inventory management systems.
By shipment volume, single-use devices lead. By customer preference shift, disposable kits are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridors enable just-in-time delivery of platinum-tungsten alloys to German catheter foundries. This maritime infrastructure underwrites European supply chain resilience for coil manufacturing.
United States
Texas Medical Center in Houston and Mayo Clinic in Rochester anchor neurointerventional case volume expansion. FDA 510(k) premarket notification pathways shape liquid embolic entry timelines for ethylene-vinyl alcohol copolymers. Florida's integrated delivery networks are consolidating procurement through super-regional purchasing committees spanning Tampa and Miami markets.
Germany
Baden-Württemberg cleanroom facilities operate at utilization rates exceeding 85%, constraining OEM expansion timelines for catheter extrusion. EU MDR biocompatibility mandates under ISO 10993 accelerate replacement demand for legacy PVA particle systems. Bavarian neuroradiology hubs in Munich and Erlangen standardize on non-adhesive liquid embolic protocols.
Japan
Tokyo-based academic medical centers concentrate fellowship-trained interventional neuroradiologists for complex aneurysm coiling. PMDA revised quality management requirements for class IV devices extend sterilization validation timelines for imported coil systems. Domestic producers in Osaka and Nagoya capture share from foreign OEMs absorbing compliance costs.
Brazil
São Paulo and Rio de Janeiro tertiary neurovascular centers drive hemorrhage control device procurement. ANVISA fast-track pathways open procurement channels for stroke infrastructure expansion. Local distribution partnerships with São Paulo-based interventional radiology clinics accelerate market penetration.
India
Mumbai and Delhi NCR hospital systems expand interventional radiology departments for tumor devascularization cases. CDSCO medical device registration requirements shape import timelines for coil and liquid embolic systems. Hyderabad's emerging medtech manufacturing corridor attracts catheter assembly investments from multinational OEMs.
Global Vascular Embolization Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and precision manufacturing. The vendor base stratifies across three tiers: diversified medtech conglomerates with full interventional portfolios, mid-cap device specialists with category depth, and regional fabricators serving price-sensitive procurement channels. Consolidation pressure intensifies as hospital purchasing committees demand single-source agreements spanning coils, liquid embolics, and delivery systems. Capacity expansion in German cleanroom facilities and strategic partnerships for platinum-tungsten supply security represent dominant competitive vectors.
Among diversified platform operators, Cook Medical, Terumo Corporation, and Boston Scientific Corporation occupy positions spanning coil winding, catheter production, and liquid embolic formulation. Cook Medical exemplifies backward integration across manufacturing stages. Terumo Corporation anchors Asia-Pacific distribution architecture through its Tokyo-based interventional systems division. Boston Scientific Corporation represents polymer science leadership in liquid embolic development. These three entities collectively illustrate the competitive imperative for vertical control over critical supply chain nodes.
| Leading Market Players |
|---|
| Cook Medical |
| Terumo Corporation |
| Boston Scientific Corporation |
| Penumbra, Inc. |
| Johnson & Johnson |
| Medtronic |
| Abbott Laboratories |
| Merit Medical Systems |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Baden-Württemberg cleanroom utilization rates exceeding 85% are compressing catheter OEM expansion timelines while amplifying pricing power for contracted capacity holders. This supply tightness propagates through coil winding operations and liquid embolic formulation, forcing procurement committees toward multi-year volume commitments in exchange for allocation security.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hospital procurement, with premium tiers commanding ISO 10993-certified biocompatibility documentation and dedicated field clinical support. Price differentiation rests on coil detachment reliability ratings and liquid embolic catheter entrapment risk profiles. Cost compression in standard-tier PVA particle systems is intensifying because EU MDR replacement demand is shifting volume toward next-generation copolymers. Ambulatory surgical centers exhibit highest price sensitivity due to site-of-service reimbursement differentials, while Japanese academic medical centers show lowest sensitivity given PMDA compliance cost absorption.
Supply Chain Analysis
Contract manufacturing concentration in German foundries and Japanese precision alloy facilities holds the majority of platinum-tungsten coil winding capacity. Geographic supply concentration centers on Germany, Japan, and United States for catheter extrusion and coil production. Raw material dependencies draw from South African platinum group metals, German nitinol wire, and Japanese precision polymer feedstocks. Single-source vulnerability in platinum-tungsten alloy offtake agreements represents the dominant structural risk. Distribution runs through Rotterdam pharmaceutical logistics corridors for European supply and Tokyo-based interventional systems divisions for Asia-Pacific reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from field clinical specialist deployment and on-site liquid embolic training is expanding faster than hardware sales, making aftermarket integration the critical margin layer for vendor positioning.
For Market Incumbents: Harden coil inventory guarantee programs against platinum price volatility by locking multi-year offtake agreements with Baden-Württemberg foundries. Deepen backward integration into catheter extrusion to defend against cleanroom capacity bottlenecks constraining OEM expansion timelines.
For New Entrants and Emerging Players: Brazil's underpenetrated stroke infrastructure offers the most accessible white-space entry, with ANVISA fast-track pathways reducing regulatory lead time versus FDA or PMDA routes. Target São Paulo tertiary neurovascular centers through local distribution partnerships, prioritizing hemorrhage control devices over complex aneurysm coiling systems.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap device specialists with category depth in liquid embolic formulations and established hospital system partnerships. Long-term viability favors platforms with demonstrated reimbursement strategy execution across oncology and women's health segments. Watch for PMDA sterilization validation timeline extensions as the inflection signal for domestic Japanese producer share capture.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR biocompatibility mandates accelerate ISO 10993-certified product replacement cycles. |
| Hospital System Partnership | Super-regional purchasing committees in Texas and Florida consolidate procurement through single-source agreements. |
| Software Companion Development | AI-guided catheter navigation integration with fluoroscopy systems reduces contrast dye volumes. |
| Reimbursement Strategy | Site-of-service payment differentials drive ambulatory surgical center migration for uterine fibroid cases. |
| Backward Integration | Captive supply of platinum-tungsten alloys insulates coil winding margins from London Metal Exchange volatility. |
Research Methodology
Operator-level perspectives from interventional neuroradiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, PMDA quality management disclosures, hospital procurement databases, and EU MDR technical documentation. Bottom-up procedure volume modeling and top-down market sizing triangulated across the analysis window.
Scenario-bracketing around platinum price volatility bands and cleanroom capacity expansion timelines framed the analytical approach across product type, application, end user, and deployment model dimensions. CAGRs derived from procedure volume trajectories and device pricing elasticity curves, with specific inputs from stroke center construction pipelines and ambulatory surgical center reimbursement evolution.
Practitioners should monitor platinum futures movements, EU MDR implementation enforcement, and PMDA sterilization validation timeline shifts for early signals of forecast revision. Quarterly review of hospital procurement database trends and integrated delivery network merger activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market