
 Drug-Coated Balloon Catheter Market | 2026-2036
Drug-Coated Balloon Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Drug-Coated Balloon Catheter Market Analytics
Modular catheter configurations with detachable drug-payload segments is broadening buyer choice across procurement tiers. Boston Scientific Corporation leverages in-house balloon manufacturing to sustain pricing control in coronary applications. Medtronic anchors its position through upstream control over paclitaxel coating supply chains. B. Braun SE differentiates via specialized production lines for pediatric-sized drug-coated balloons.
Drug-coated balloon catheters are percutaneous transluminal angioplasty devices featuring antiproliferative drug layers—typically paclitaxel or sirolimus—applied to semi-compliant balloon surfaces at densities of 2–3 μg/mm², designed to inhibit neointimal hyperplasia during vessel dilation. The peripheral application segment leads volume due to rising endovascular revascularization for femoropopliteal lesions, while coronary drug-coated balloons represent a faster-expanding margin pool as stent-free strategies gain clinical traction. Bioresorbable coating technology occupies a nascent but strategically watched position, with coating type selection directly influencing reimbursement coding in several European markets.
The FDA maintains stringent premarket approval pathways for drug-device combination catheters, while the EU MDR demands enhanced clinical follow-up data for peripheral vascular indications. Japan's PMDA applies distinct pharmacokinetic exposure thresholds that shape coating formulation choices for manufacturers seeking market entry. Stakeholders must monitor evolving health technology assessment criteria across national payers, as value-based procurement is displacing traditional tender mechanisms in hospital purchasing.
Market Dynamics
EU MDR clinical evidence requirements are compressing the competitive set for Class III vascular devices, forcing manufacturers to consolidate trial data or exit peripheral indications entirely.
Growth Catalysts
- Femoropopliteal lesion prevalence:Aging populations in Germany, Italy, and Japan are expanding the addressable patient pool for endovascular revascularization procedures.
- Stent-free coronary strategies:Interventional cardiologists in cardiac centers are adopting drug-coated balloons for in-stent restenosis cases to avoid permanent metal implants.
- Medicare outpatient reimbursement:The US Centers for Medicare & Medicaid Services favors same-day discharge for peripheral vascular interventions, accelerating site-of-care migration to ambulatory surgical centers.
Market Restraints
- Paclitaxel supply concentration:Three contract manufacturers control the majority of pharmaceutical-grade coating supply, creating single-source vulnerability for device makers.
- EU MDR transition costs:Enhanced clinical follow-up mandates for peripheral indications are extending regulatory timelines and inflating post-market surveillance budgets.
- Bioresorbable scaffold competition:Fully absorbable stent platforms threaten to capture coronary cases where drug-coated balloons currently serve as bridge therapy.
Strategic Opportunities
- Pediatric vascular applications:B. Braun SE's specialized production lines demonstrate unmet need for size-appropriate devices in congenital heart defect repair.
- Value-based procurement expansion:Hospital purchasing coalitions in the Netherlands and Sweden are displacing traditional tenders with outcomes-linked contracts.
- Sirolimus coating formulations:Alternative antiproliferative agents offer differentiation where paclitaxel safety debates have created physician hesitation.
Industry Challenges
- Polymer coating uniformity:Achieving consistent 2–3 μg/mm² drug density across semi-compliant balloon surfaces demands specialized thin-film deposition expertise that remains scarce.
- Health technology assessment navigation:National payers in France, England, and Germany apply divergent cost-effectiveness thresholds, fragmenting market access strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug-Coated Balloon Catheter Market |
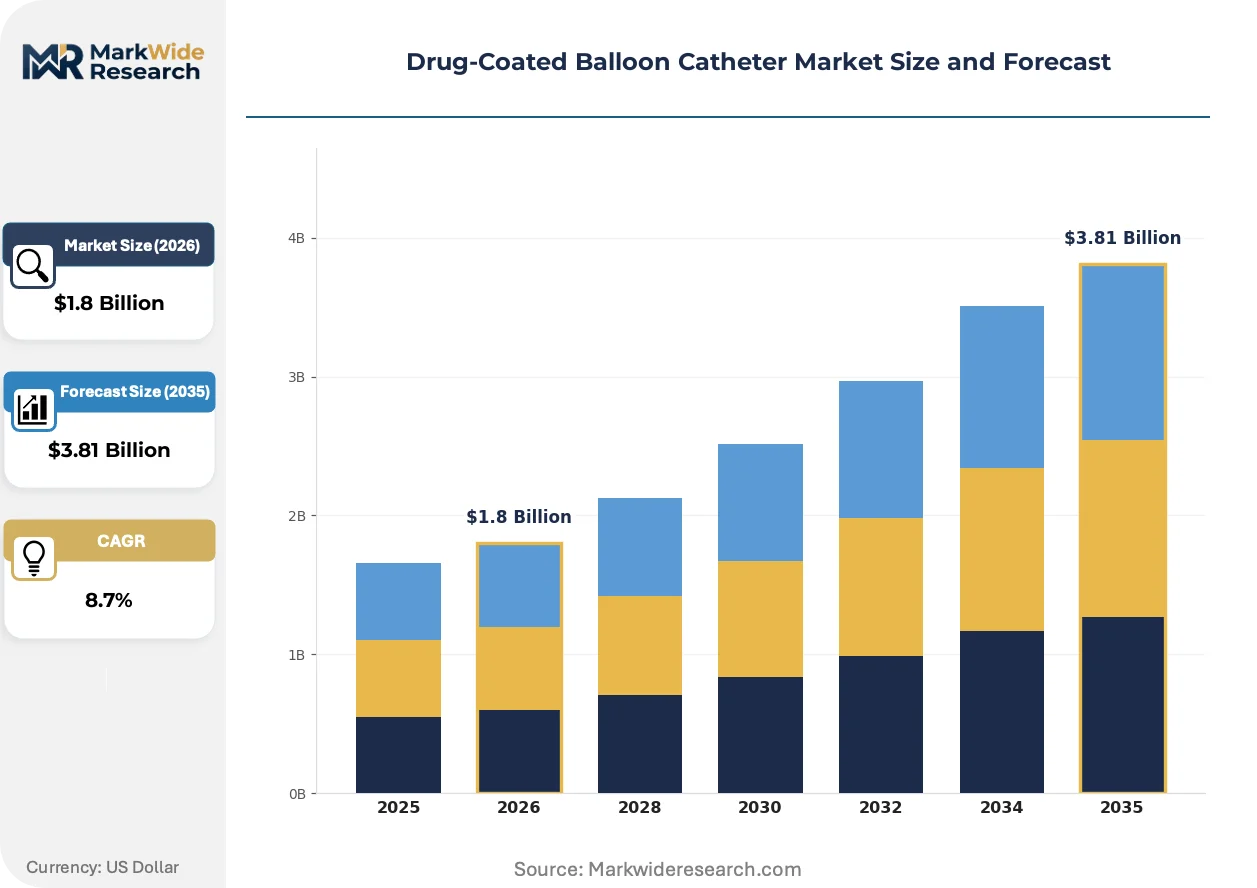
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pediatric, Adult, Coronary, Peripheral Technology: Bioresorbable, Non-bioresorbable, Drug-eluting, Coating Type End User: Hospitals, Clinics, Ambulatory Surgical Centers, Cardiac Centers Application: Coronary Artery Disease, Peripheral Arterial Disease, Vascular Procedures, Stenting |
| Companies Covered | Boston Scientific Corporation, B. Braun SE, Medtronic, BD, BIOTRONIK, Koninklijke Philips, Terumo Corporation, Cordis, iVascular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug-Coated Balloon Catheter Market Evolving Landscape
Coating chemistry and regulatory science are converging to redefine competitive advantage, with manufacturers racing to secure pharmacokinetic profiles that satisfy divergent national exposure thresholds.
Bioresorbable polymer matrices are integrating with paclitaxel and sirolimus payloads to enable controlled release kinetics that match vessel healing timelines. Academic medical centers in Switzerland and the Netherlands are piloting these platforms for below-the-knee interventions. This integration is compressing the window for first-generation durable-coating devices by establishing new efficacy benchmarks for tissue retention.
The EU MDR's enhanced post-market clinical follow-up requirements are extending surveillance obligations to five years for peripheral vascular indications. Manufacturers must now maintain active registries or face certificate suspension. Small-cap device firms without dedicated pharmacovigilance infrastructure are most affected, with several withdrawing femoropopliteal indications rather than absorbing compliance costs.
Hospital purchasing groups are consolidating vendor panels to three preferred suppliers per category, bundling drug-coated balloons with guidewire and sheath contracts. Integrated delivery networks in the US Southeast and hospital alliances in Germany's North Rhine-Westphalia region are leading this concentration. France remains an exception, where public hospital procurement maintains separate tender lots for interventional devices.
Drug-Coated Balloon Catheter Market Segmentation
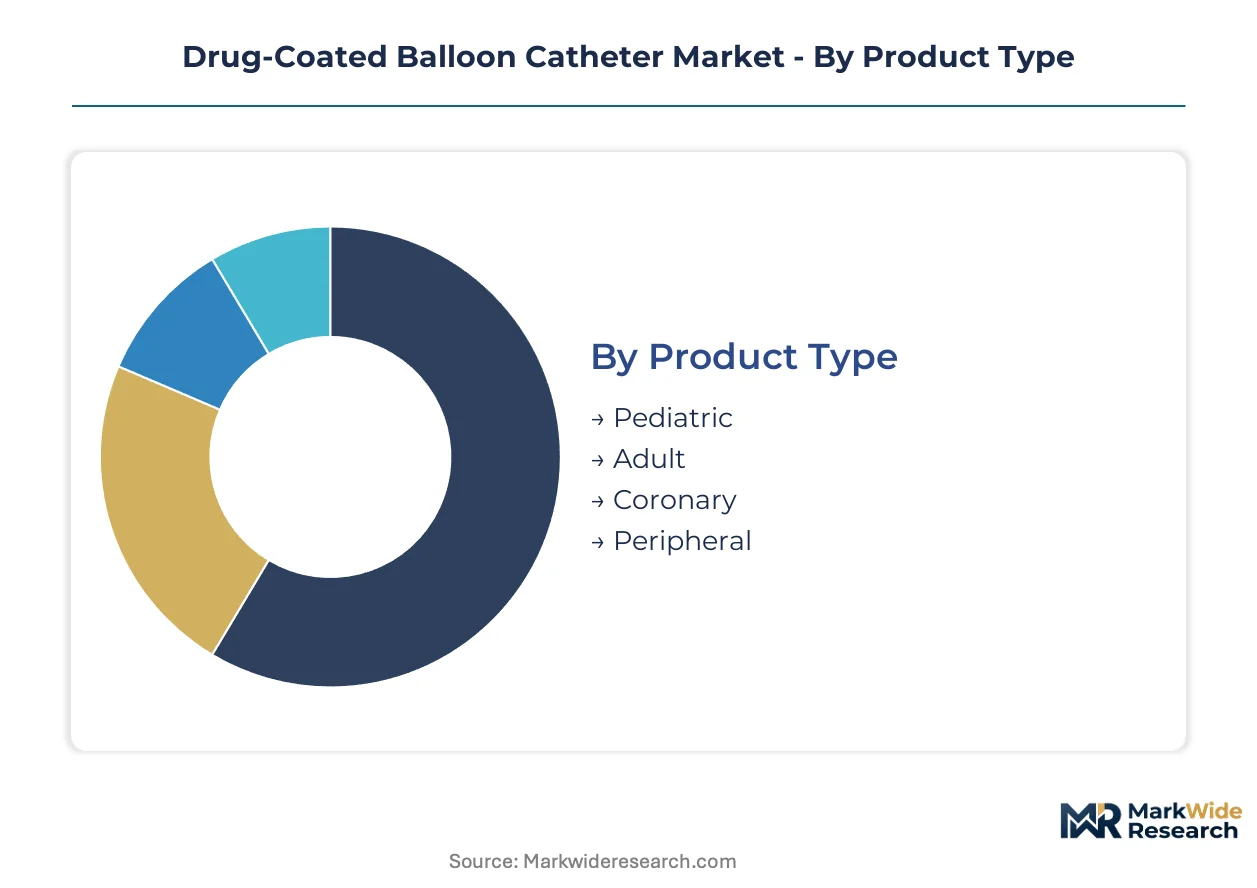
Drug-coated balloon catheter procurement patterns diverge sharply across clinical settings and anatomical targets. Buyers prioritize coating durability for coronary workflows versus flexibility for tortuous peripheral anatomy. Understanding these segment-specific demand drivers enables targeted product positioning and regulatory investment.
Product Type:
End-use scale and reimbursement intensity separate buyers in this category.
- Peripheral:Semi-compliant balloons with 2–3 μg/mm² paclitaxel density dominate femoropopliteal revascularization. German cardiac centers are expanding adoption for below-the-knee lesions where stent fracture risks are elevated.
- Coronary:Low-profile balloons with rapid drug transfer kinetics serve in-stent restenosis cases. Interventional cardiologists in US academic medical centers favor these for stent-free strategies in diffuse disease.
- Adult:Standard 5–7 French compatible platforms address the bulk of procedural volume across general hospital catheterization labs.
- Pediatric:Specialized low-diameter configurations from B. Braun SE demonstrate unmet need in congenital heart defect repair.
Peripheral leads volumes today; coronary is gaining share fastest.
Technology:
Coating persistence duration determines reimbursement coding and clinical indication breadth.
- Non-bioresorbable:Durable polymer matrices with controlled paclitaxel release dominate current procedural economics. These platforms anchor Medicare outpatient reimbursement for peripheral interventions.
- Bioresorbable:Absorbable matrices integrating sirolimus or paclitaxel enable tissue-matched release kinetics. Swiss and Dutch academic centers pilot these for below-the-knee cases to establish new efficacy benchmarks.
- Drug-eluting:Mechanisms emphasizing active pharmaceutical ingredient transfer efficiency rather than polymer architecture.
- Coating Type:Formulation selection directly influences Japan PMDA pharmacokinetic exposure threshold compliance.
Non-bioresorbable coatings dominate procedure counts; bioresorbable platforms show steepest expansion trajectory.
End User:
Site-of-care economics and case complexity stratify purchasing authority.
- Cardiac Centers:High-volume interventional hubs with dedicated vascular teams drive technology adoption. Germany's expanding cardiac center networks are accelerating peripheral drug-coated balloon uptake.
- Ambulatory Surgical Centers:US Medicare reimbursement favoring same-day discharge concentrates femoropopliteal cases in these settings.
- Hospitals:General acute care facilities with mixed procedural portfolios.
- Clinics:Outpatient diagnostic and follow-up settings with limited interventional capability.
Cardiac centers lead technology adoption; ambulatory surgical centers are expanding volume fastest.
Application:
Anatomical target and prior intervention history dictate device specification requirements.
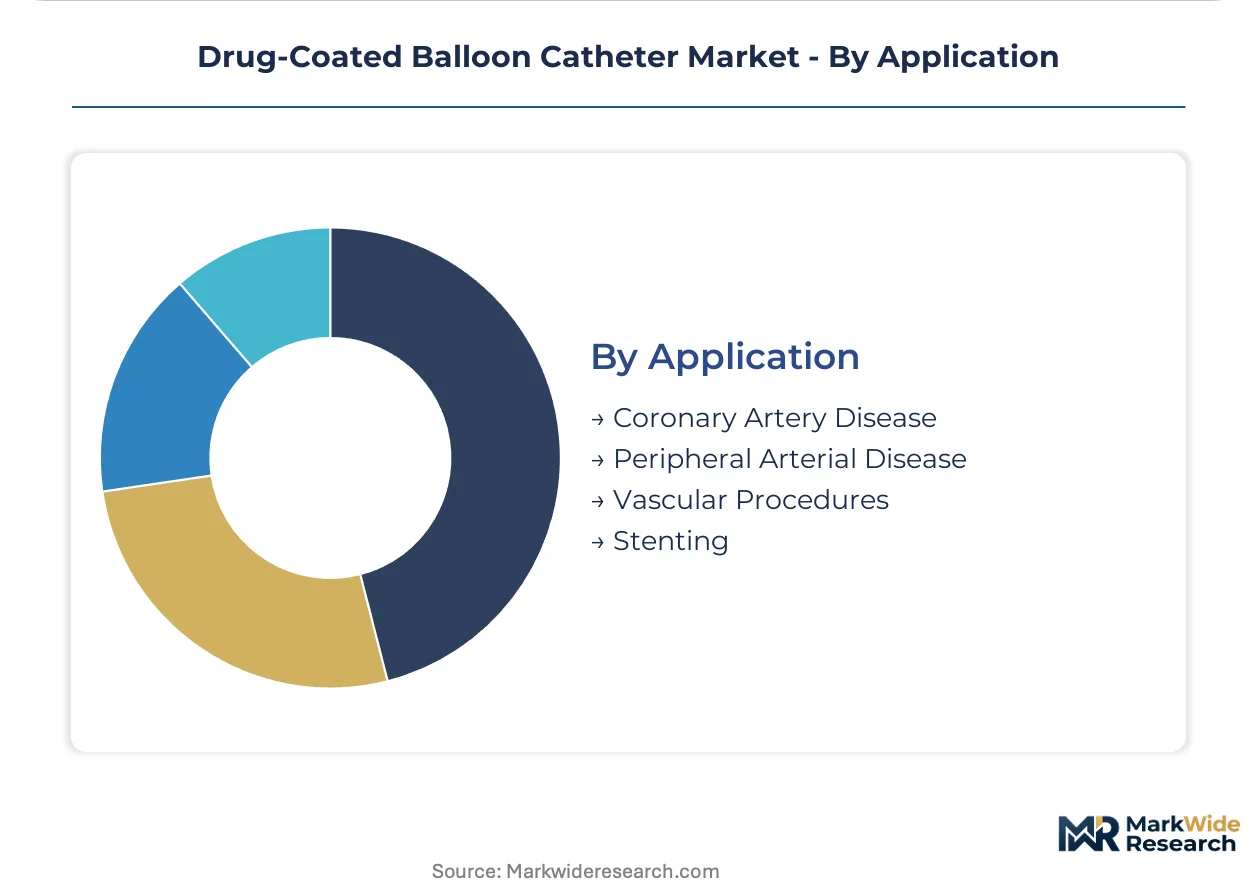
- Peripheral Arterial Disease:Femoropopliteal and infrapopliteal revascularization represents the primary volume pool. Aging demographics in Italy and Japan expand the addressable patient base for endovascular approaches.
- Coronary Artery Disease:In-stent restenosis and small vessel disease applications command premium pricing. Stent-free strategies in diffuse coronary disease are shifting cardiologist preference toward drug-coated balloons.
- Vascular Procedures:Broad category encompassing diagnostic and therapeutic endovascular workflows.
- Stenting:Adjunctive and bail-out applications where balloon angioplasty precedes or follows metallic scaffold placement.
Peripheral arterial disease leads procedure volumes; coronary artery disease applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drug-coated balloon catheter technology first achieved commercial scale in Germany during the early 2000s, with Berlin and Munich cardiac centers pioneering femoropopliteal applications. This German foundation established the clinical evidence base that subsequently diffused across European and North American markets.
United States
Medicare reimbursement policies favoring same-day discharge concentrate femoropopliteal procedures in ambulatory surgical centers across Florida and Texas. The FDA maintains stringent premarket approval pathways for drug-device combination catheters, extending regulatory timelines for peripheral vascular indications. Boston Scientific Corporation anchors its manufacturing presence in Massachusetts, supplying coronary applications to academic medical centers in the Northeast.
Germany
Cardiac centers in North Rhine-Westphalia and Bavaria are expanding adoption for below-the-knee lesions where stent fracture risks complicate traditional interventions. The EU MDR framework tightens clinical evidence requirements for Class III vascular devices, forcing manufacturers to consolidate trial data or exit peripheral indications. B. Braun SE operates specialized production lines in Melsungen, addressing unmet pediatric sizing needs for congenital heart defect repair.
Japan
Aging demographics in Osaka and Nagoya metropolitan areas expand the addressable patient pool for endovascular revascularization procedures. The PMDA applies distinct pharmacokinetic exposure thresholds that shape coating formulation choices for manufacturers seeking market entry. Terumo Corporation leverages its Tokyo-based research infrastructure to navigate these regulatory requirements for coronary drug-coated balloon submissions.
Switzerland
Academic medical centers in Zurich and Geneva pilot bioresorbable polymer matrices for below-the-knee interventions, establishing new efficacy benchmarks for tissue retention. Swissmedic coordinates with EU MDR transitional provisions for device certification. BIOTRONIK maintains its headquarters in Bülach, anchoring European research coordination for alternative antiproliferative coating formulations.
Netherlands
Hospital purchasing coalitions in the Randstad region displace traditional tenders with outcomes-linked contracts for vascular devices. The Dutch national health technology assessment institute applies specific cost-effectiveness thresholds that fragment market access strategy across European borders. Philips leverages its Eindhoven manufacturing base to supply integrated imaging and interventional platforms to cardiac centers in Amsterdam and Rotterdam.
Drug-Coated Balloon Catheter Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology sophistication and regulatory certification depth. The competitive set compresses under EU MDR transition costs, with small-cap firms withdrawing femoropopliteal indications rather than absorbing enhanced post-market surveillance budgets. Three strategic archetypes dominate: diversified medtech conglomerates with captive pharmaceutical supply chains, mid-cap vascular specialists with modular catheter platforms, and regional fabricators with pediatric or niche anatomical focus. Consolidation through M&A and strategic partnerships for coating technology licensing represent the dominant competitive moves.
Among diversified medtech conglomerates, Boston Scientific Corporation and Medtronic exemplify archetypes built on upstream control over critical supply chain segments. B. Braun SE occupies a distinct position as a European-based specialist with dedicated production infrastructure for size-appropriate pediatric configurations. These three entities represent contrasting strategic postures: one leveraging in-house balloon manufacturing, one anchoring position through pharmaceutical-grade coating supply chains, and one differentiating via specialized production lines for underserved anatomical segments.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| B. Braun SE |
| Medtronic |
| BD |
| BIOTRONIK |
| Koninklijke Philips |
| Terumo Corporation |
| Cordis |
| iVascular |
| Others |
Value Network & Pricing Analysis
Captive pharmaceutical-grade coating supply chains anchor pricing power for diversified medtech conglomerates while forcing mid-cap competitors toward outsourced manufacturing arrangements. This upstream control dynamic concentrates margin capture among three contract manufacturers that dominate paclitaxel supply, creating tiered cost structures across the competitive set.
Pricing Analysis
Premium-mid-economy pricing differentiation separates coronary applications with rapid drug-transfer kinetics from standard peripheral platforms. Certification grade under EU MDR and FDA premarket approval pathways command substantial premiums over CE-marked peripheral devices. Cost compression in standard peripheral tiers is intensifying because hospital purchasing coalitions consolidate vendor panels to three preferred suppliers per category. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while German cardiac centers prioritize coating durability over unit cost.
Supply Chain Analysis
Pharmaceutical-grade paclitaxel supply rests on German, Swiss, and US specialty chemical producers with dedicated GMP certification for medical device coatings. Semi-compliant balloon substrates and thin-film deposition equipment constitute critical component dependencies alongside antiproliferative active pharmaceutical ingredients. Single-source vulnerability concentrates in coating formulation expertise, where specialized thin-film deposition knowledge remains scarce. Distribution runs through hospital purchasing groups and integrated delivery networks that bundle drug-coated balloons with guidewire and sheath contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR transition costs for Class III vascular devices are compressing the competitive set and elevating compliance investment as a demand driver.
For Market Incumbents: Lock in coating supply chain exclusivity through long-term pharmaceutical-grade paclitaxel contracts before contract manufacturers consolidate further. Defend against bioresorbable scaffold substitution threats by accelerating pediatric and below-the-knee indication expansions where stent alternatives face anatomical constraints. Prioritize pharmacovigilance infrastructure investment to absorb EU MDR five-year post-market surveillance obligations without margin erosion. For New Entrants and Emerging Players: Capture value-based procurement entry points in Dutch and Swedish hospital purchasing coalitions where outcomes-linked contracts displace traditional tender mechanisms. Pediatric vascular applications present the most penetrable white space, with B. Braun SE's specialized production lines demonstrating unmet sizing needs in congenital heart defect repair. Lead with sirolimus coating formulations to differentiate where paclitaxel safety debates have created physician hesitation. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed pharmacovigilance infrastructure capacity for small-cap device firms. Long-term viability favors acquisition targets with captive coating technology or modular catheter platforms that enable rapid indication expansion. Watch bioresorbable polymer matrix pilot outcomes in Swiss and Dutch academic centers as inflection indicators for next-generation coating technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Five-year post-market surveillance infrastructure secures Class III vascular device certification continuity. |
| Coating Technology Licensing | Bioresorbable polymer matrix partnerships accelerate below-the-knee indication entry for mid-cap specialists. |
| Hospital System Partnership | Integrated delivery network contracts in US Southeast bundle drug-coated balloons with sheath and guidewire procurement. |
| Pediatric Production Line Expansion | Size-appropriate device configurations address unmet congenital heart defect repair demand in German cardiac centers. |
| Reimbursement Strategy | Medicare outpatient procedure coding alignment concentrates femoropopliteal volume in ambulatory surgical centers. |
Research Methodology
Bottom-up cardiac center and ambulatory surgical center modeling reconciled against top-down coating supply chain tracking forms the analytical core. Primary interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA premarket approval filings, EU MDR notified body certifications, CMS Medicare reimbursement databases, and hospital procurement contract registries. Triangulation across these sources ensures segment-level volume and value estimates reflect actual procedural economics and site-of-care migration patterns.
Historical trendline analysis of femoropopliteal and coronary procedure volumes across the analysis window informs the projection framework. Segmentation dimensions modeled include anatomical target, coating technology persistence, end-user site-of-care category, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to procedure volume baselines, adjusted for EU MDR transition timelines and Medicare reimbursement policy trajectories. Forecast inputs incorporate aging demographic projections for Germany, Italy, and Japan alongside stent-free coronary strategy adoption rates in US academic medical centers.
EU MDR implementation delays, paclitaxel supply chain disruption, and bioresorbable scaffold clinical trial outcomes are the dominant revision risks to modeled projections. Forecasts reflect assumptions regarding regulatory timeline adherence and coating technology substitution elasticities. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Abdominal Stent Graft System Market
Cardiovascular Devices
Aortic Stents Grafts Market