
 Pressure Infusion Bags Market | 2026-2036
Pressure Infusion Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Infusion Bags Market Outlook
Skilled biomedical engineering talent is reorganizing manufacturing capacity across the pressure infusion bags sector as cleanroom operators and polymer specialists migrate toward higher-margin device categories. B. Braun sustains European production scale through captive PVC compounding and automated welding lines. Smiths Medical dominates North American hospital contracting through integrated fluid management portfolios. Merit Medical Systems differentiates via angiography-adjacent pressure delivery platforms that share core inflation technology with infusion bags.
Pressure infusion bags are pneumatic or mechanical compression devices, typically fabricated from PVC, polyethylene, or silicone sheeting with welded seams and pressure-rated inflation chambers, designed to accelerate fluid or blood product delivery into a patient's vascular system under controlled pressure. Disposable single-use configurations command the largest volume share as infection control protocols harden against reusable alternatives, while multi-lumen designs for simultaneous medication and fluid delivery represent the fastest-growing product subset. Emergency care applications anchor demand due to protocolized fluid resuscitation in trauma bays, though surgical procedure usage generates superior per-unit margins through kit bundling with higher-value disposable sets.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for bag manufacturers seeking dual-territory commercialization. ISO 13485 quality management certification operates as a baseline procurement filter for hospital group purchasing organizations across North America and Western Europe. Stakeholders must monitor evolving EPA and REACH restrictions on phthalate plasticizers in PVC formulations, as material substitution decisions will cascade through supply contracts and unit economics within the next product refresh cycle.
Market Dynamics
Cleanroom-grade polymer welding automation is compressing production economics for pressure infusion bags, forcing mid-scale manufacturers to consolidate or exit as B. Braun and Smiths Medical extend their captive supply advantages through in-house compounding and vertically integrated assembly lines.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter conformity assessment requirements are filtering out marginal suppliers and concentrating procurement among ISO 13485-certified vendors with established notified body relationships.
- Emergency department trauma protocol standardization:Hospital systems in the United States, Germany, and Japan are hardening disposable-only policies for fluid resuscitation equipment.
- Silicone sheeting material substitution:Phthalate-free polymer formulations are capturing preference share among pediatric and neonatal intensive care units seeking REACH-compliant alternatives.
Market Restraints
- PVC resin price volatility:Feedstock cost swings tied to ethylene and chlorine markets compress margin predictability for non-integrated bag producers lacking captive polymer supply.
- FDA 510(k) clearance timelines:Extended review cycles for novel pressure-delivery mechanisms delay product launches and freeze R&D amortization schedules.
- Mechanical pump substitution:Electronic infusion systems with closed-loop pressure control are capturing share in high-acuity surgical suites where precision overrides cost considerations.
Strategic Opportunities
- India hospital infrastructure expansion:Government-funded trauma center construction under the National Health Mission is creating first-time demand for standardized emergency fluid delivery equipment.
- Pre-hospital EMS modernization:Ambulance fleet upgrades in Japan and South Korea are extending pressure infusion bag utilization beyond traditional hospital boundaries.
- RFID-enabled inventory tracking:Convergence of polymer manufacturing with embedded sensor technology is opening subscription-based fleet management contracts for disposable bag systems.
Industry Challenges
- Polymer welding technician scarcity:Cleanroom operator certification requirements are constraining production scale-up for manufacturers expanding beyond single-facility footprints.
- Dual-territory compliance synchronization:Reconciling FDA 510(k) and EU MDR documentation demands is extending product development cycles and diluting engineering bandwidth.
- Legacy sterilization validation:Ethylene oxide residue testing protocols are requiring process requalification for manufacturers transitioning to gamma irradiation methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Infusion Bags Market |
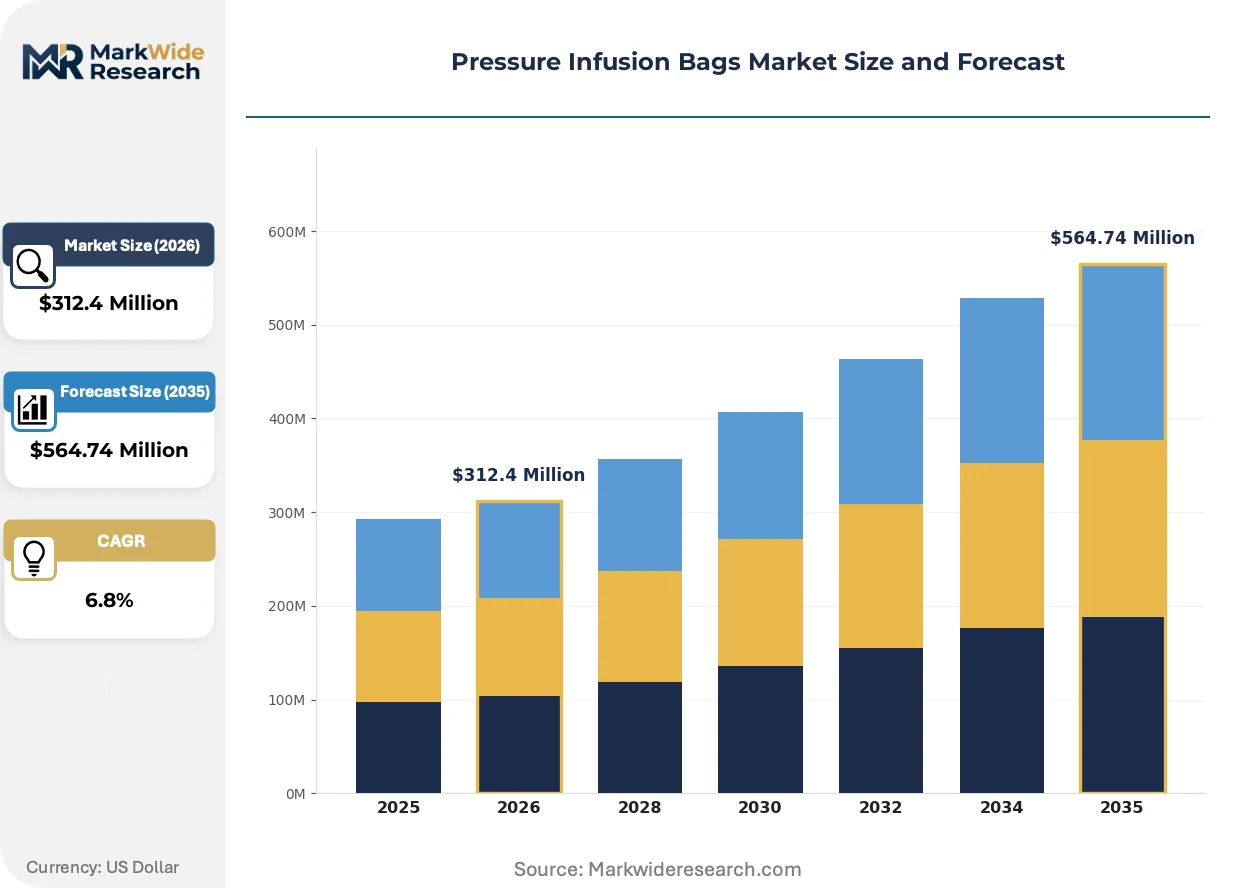
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Disposable, Multi-Lumen Application: Emergency Care, Surgical Procedures, Blood Transfusion, Fluid Resuscitation Material: PVC, Polyethylene, Silicone, Neoprene End User: Hospitals, Clinics, Ambulance Services, Home Care |
| Companies Covered | Tapmedic LLC, B. Braun, Merit Medical Systems, Biegler GmbH, Smiths Medical, ICU Medical Inc., SunMed, Fresenius Kabi, VBM Medizintechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Infusion Bags Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape competitive positioning across pressure infusion bag manufacturing, with automation and compliance capabilities emerging as the primary axes of differentiation.
Multi-lumen silicone sheeting with integrated pressure relief valves is displacing single-chamber PVC configurations in neonatal and pediatric critical care segments. University hospital systems in Germany and Japan are specifying these designs in procurement tenders despite 40-60% unit cost premiums. The technology is displacing conventional welded-seam construction by enabling simultaneous medication and fluid delivery without cross-contamination risk.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC formulation overhauls across European supply chains. ECHA substance evaluation timelines are compressing material qualification windows and accelerating supplier consolidation. German and Swiss medical device manufacturers are responding by diversifying into TPU and silicone alternatives ahead of anticipated 2027 enforcement milestones.
Hospital group purchasing organizations are consolidating vendor panels around integrated fluid management portfolios rather than standalone bag procurement. North American IDNs are awarding multi-year contracts to suppliers offering pressure infusion bags bundled with warming devices and transducer systems. This concentration is most visible in the United States, where three GPOs control access to over 60% of acute care bed capacity.
Pressure Infusion Bags Market Segmentation
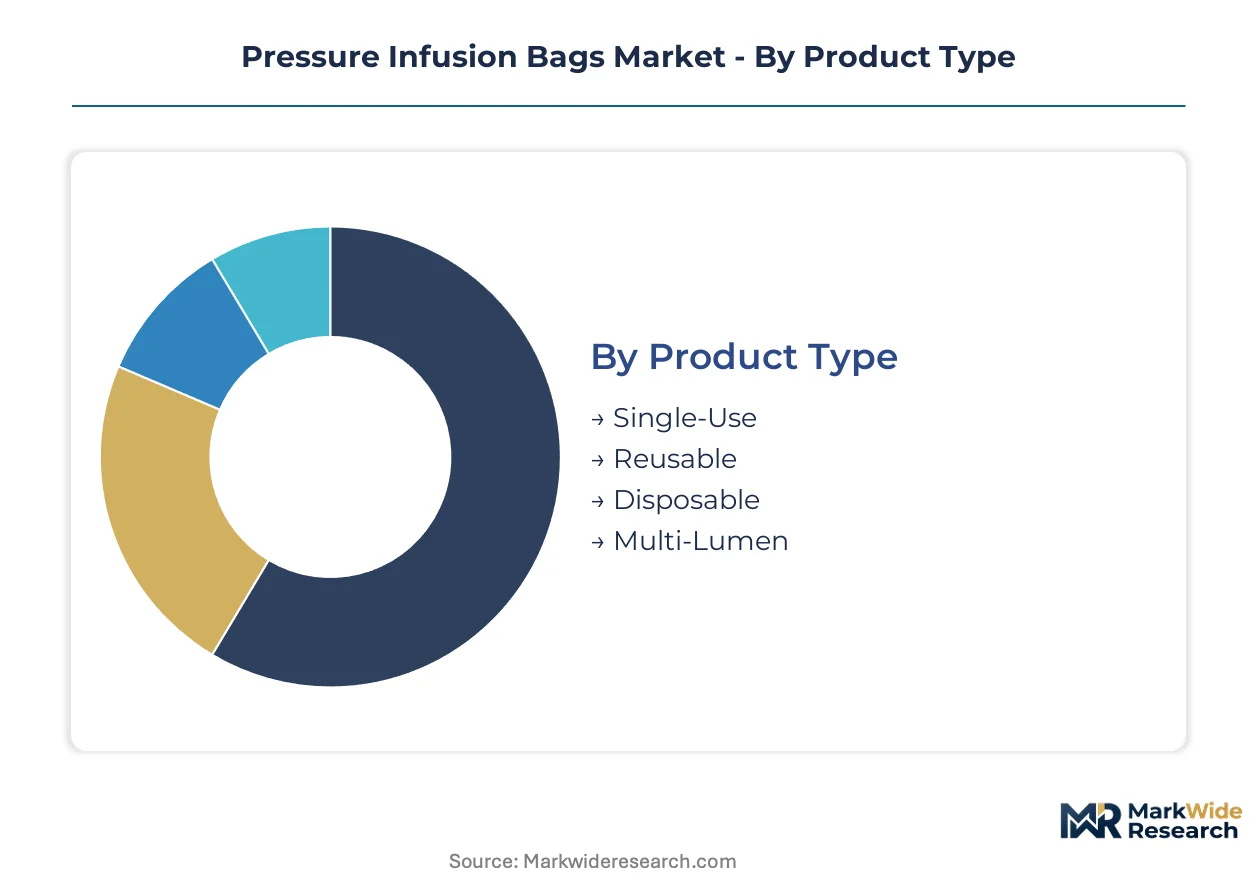
Pressure infusion bags fragment across four distinct taxonomies that govern procurement logic and margin structure. Material composition determines regulatory pathway complexity, while product type dictates sterilization economics and end-user preference for disposability.
Product Type:
FDA 510(k) clearance requirements and EU MDR technical documentation obligations split this category by infection control liability and reprocessing validation burden.
- Single-Use:PVC or polyethylene configurations with welded seams and pre-attached pressure gauges eliminate cross-contamination risk in trauma bays. Hospital emergency departments in the United States and Germany mandate these for protocolized fluid resuscitation, with procurement concentrated among ISO 13485-certified vendors.
- Disposable:Gamma-sterilized polymer chambers with integrated inflation valves serve high-throughput surgical suites where reprocessing infrastructure is absent. Japanese hospital systems specify these in bundled contracts with fluid warming devices.
- Reusable:Silicone sheeting with detachable pressure chambers requires ethylene oxide revalidation cycles that extend turnaround time.
- Multi-Lumen:Parallel inflation chambers enable simultaneous medication and fluid delivery without line crossover.
Single-Use handles the majority of throughput; Multi-Lumen is climbing the fastest on share.
Application:
Per-unit margin structure varies sharply by clinical setting, with surgical kit bundling generating superior economics versus standalone emergency deployment.
- Emergency Care:Protocolized trauma bay resuscitation in United States academic medical centers drives volume concentration. Disposable-only policies harden as Joint Commission surveyors scrutinize reusable alternatives.
- Surgical Procedures:Operating room integration with transducer systems and warming platforms commands premium positioning. German university hospitals bundle these with higher-value disposable sets.
- Blood Transfusion:Pressure-rated chambers for rapid hemoglobin restoration in hemorrhagic shock protocols.
- Fluid Resuscitation:Standardized crystalloid delivery in sepsis and dehydration management.
Emergency Care captures the highest absolute volume; Surgical Procedures delivers the steepest margin expansion.
Material:
REACH Annex XVII phthalate restrictions and EPA residue thresholds are forcing substitution decisions that cascade through supply contracts.
- PVC:Plasticized formulations with welded seam construction dominate legacy installed base. ECHA substance evaluation timelines compress qualification windows for European manufacturers.
- Silicone:Phthalate-free sheeting with integrated pressure relief valves captures preference in pediatric and neonatal intensive care units. Swiss and German manufacturers diversify into these alternatives ahead of anticipated enforcement milestones.
- Polyethylene:Lower-cost alternative for standard-pressure applications with reduced elasticity requirements.
- Neoprene:Elastomeric compression chambers for reusable configurations requiring extended cycle life.
PVC retains the dominant share position; Silicone is gaining share fastest on regulatory preference.
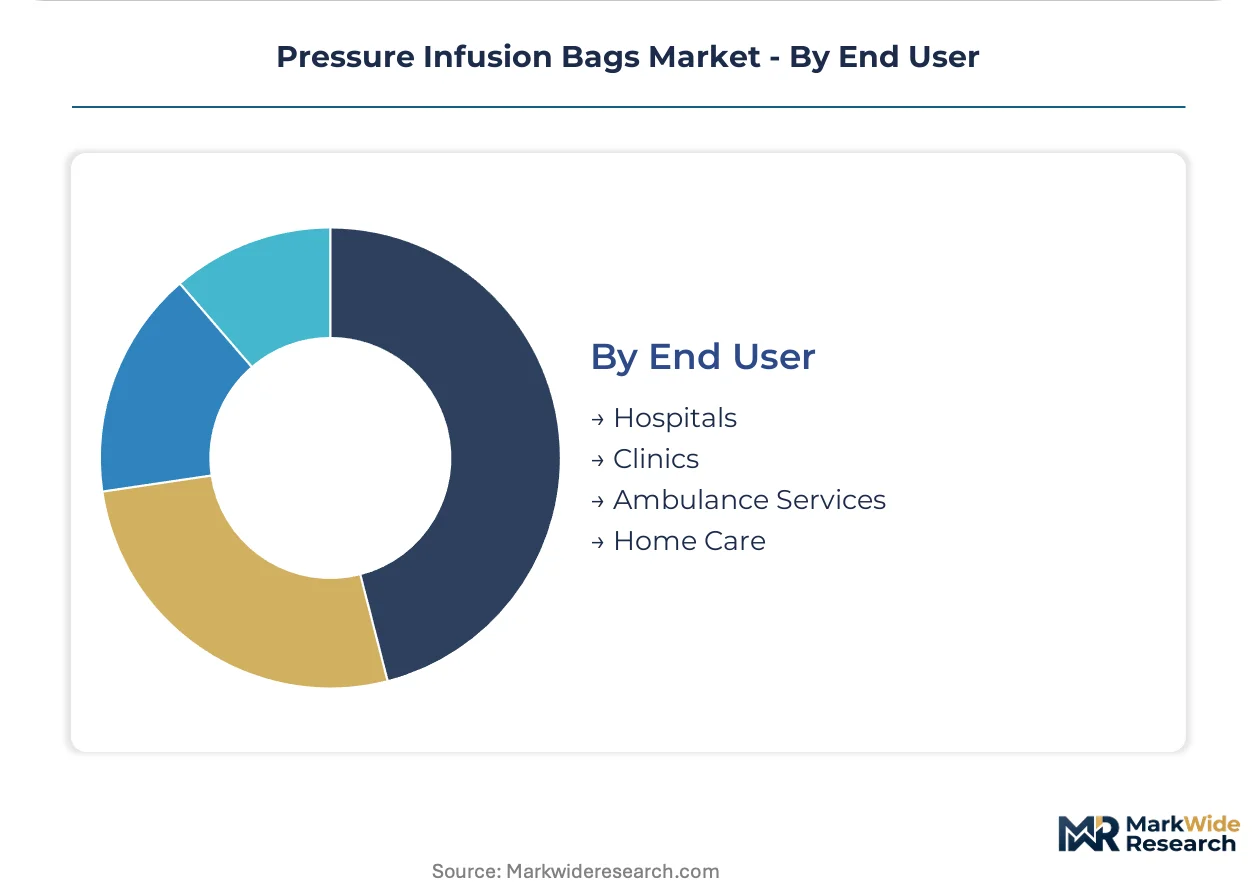
End User:
Procurement authority concentrates differently across settings, with group purchasing organizations controlling hospital access while ambulance fleets negotiate direct manufacturer contracts.
- Hospitals:Integrated delivery networks in the United States award multi-year contracts to suppliers offering pressure infusion bags within fluid management portfolios. Three GPOs control access to over sixty percent of acute care bed capacity.
- Ambulance Services:Pre-hospital EMS modernization in Japan and South Korea extends utilization beyond traditional boundaries. Fleet standardization programs create first-time demand for ruggedized disposable configurations.
- Clinics:Outpatient surgical centers with limited sterilization infrastructure favor single-use procurement.
- Home Care:Palliative hydration therapy and immunoglobulin delivery in residential settings.
Hospitals command the dominant procurement volume; Ambulance Services is expanding most quickly on fleet upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States emergency departments deploy disposable pressure infusion bags at triple the per-capita rate of Japanese surgical suites, where reusable configurations retain preference in cost-constrained procurement. German university hospitals anchor European silicone adoption, while Indian trauma center construction drives first-time demand for standardized fluid delivery equipment.
United States
Academic medical centers in Boston and Baltimore mandate single-use configurations for Joint Commission-compliant trauma protocols. FDA 510(k) clearance timelines extend product development cycles for domestic manufacturers seeking novel pressure-delivery mechanisms. Three group purchasing organizations headquartered in Chicago and Nashville control procurement access to over sixty percent of acute care bed capacity.
Germany
REACH Annex XVII phthalate restrictions accelerate silicone sheeting substitution in pediatric and neonatal intensive care units. EU MDR technical documentation obligations filter procurement toward ISO 13485-certified vendors with established notified body relationships. Medical device clusters in Baden-Württemberg and Bavaria diversify into TPU alternatives ahead of anticipated enforcement milestones.
Japan
Pre-hospital EMS modernization extends pressure infusion bag utilization beyond traditional hospital boundaries through ambulance fleet upgrades. METI-funded trauma center construction under regional emergency care networks sustains replacement cycles. Osaka and Nagoya medical device distributors negotiate direct manufacturer contracts for ruggedized disposable configurations.
India
Government-funded trauma center construction under the National Health Mission creates first-time demand for standardized emergency fluid delivery equipment. CDSCO medical device rules elevate registration barriers for imported bag configurations. Hospital infrastructure expansion concentrates in Maharashtra and Karnataka where state health missions prioritize emergency care equipment procurement.
Switzerland
Swissmedic certification requirements for phthalate-free polymer formulations capture preference share among pediatric specialists seeking REACH-compliant alternatives. Precision manufacturing clusters in Basel and Zurich advance multi-lumen designs with integrated pressure relief valves. Cantonal hospital procurement federations consolidate vendor panels around integrated fluid management portfolios.
Pressure Infusion Bags Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive polymer supply and automated welding lines separating scale-driven manufacturers from assembly-dependent competitors. The market structure concentrates procurement authority among ISO 13485-certified vendors with established FDA and EU MDR compliance capabilities. Two strategic archetypes dominate: diversified medical device conglomerates with fluid management portfolios, and angiography-adjacent specialists leveraging shared inflation technology. Competitive moves center on backward integration into polymer compounding and multi-year hospital group purchasing organization contract capture.
Among diversified medical device conglomerates, B. Braun and Smiths Medical exemplify the integrated archetype through European and North American manufacturing footprints respectively. Merit Medical Systems occupies a position within the angiography-adjacent specialist tier, leveraging core inflation technology across pressure delivery platforms. German fabricator Biegler GmbH represents the mid-scale specialist segment serving regional hospital procurement federations with differentiated silicone configurations.
| Leading Market Players |
|---|
| Tapmedic LLC |
| B. Braun |
| Merit Medical Systems |
| Biegler GmbH |
| Smiths Medical |
| ICU Medical Inc. |
| SunMed |
| Fresenius Kabi |
| VBM Medizintechnik GmbH |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price stratification in pressure infusion bags, concentrating procurement among notified body-backed vendors while compressing margins for uncertified competitors unable to access hospital group purchasing organization panels. Buyers with captive polymer compounding command 15-25% cost advantages over assembly-dependent rivals, translating directly into pricing power across multi-year contracts.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement, with United States group purchasing organizations locking in three-to-five year contracts for bundled fluid management portfolios that embed pressure infusion bags alongside warming devices and transducer systems. Three-tier pricing structure across premium silicone multi-lumen, standard PVC single-use, and economy polyethylene configurations reflects material grade and certification burden differentiation. Pricing pressure stems from mechanical pump substitution in high-acuity surgical suites where electronic closed-loop systems capture preference despite higher capital outlay. Ambulance services and Indian trauma centers exhibit highest price sensitivity, while German university hospitals prioritize REACH-compliant silicone sheeting with limited elasticity to cost premiums.
Supply Chain Analysis
Inventory buffers and six-to-eight week lead times for cleanroom-grade polymer sheeting constrain rapid demand response, particularly for silicone formulations facing ECHA substance evaluation bottlenecks. Manufacturing concentrates in Germany, the United States, and Switzerland, with Baden-Württemberg and Bavarian clusters anchoring European supply through automated welding lines. Feedstock draws from ethylene and chlorine markets for PVC, plus specialized silicone monomer streams subject to pharmaceutical-grade purity requirements. Single-source vulnerability runs through notified body relationships for EU MDR technical documentation, where limited certification capacity extends qualification timelines. Distribution runs through hospital group purchasing organization contracts in North America and direct manufacturer negotiations with cantonal procurement federations in Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID-enabled inventory tracking and subscription-based fleet management contracts for disposable bag systems are expanding faster than hardware unit growth, creating recurring revenue layers that improve customer lifetime value metrics. Service-attach opportunities concentrate in pre-hospital EMS modernization programs requiring real-time utilization monitoring.
For Market Incumbents: Consolidate backward integration into polymer compounding to defend margin position against feedstock volatility, while capturing multi-year hospital system contracts through integrated fluid management portfolios that bundle pressure infusion bags with warming platforms. Capacity expansion in Switzerland and Germany secures REACH-compliant silicone supply ahead of enforcement milestones. Certification investment in dual-territory FDA 510(k) and EU MDR pathways preserves access to highest-value procurement panels. For New Entrants and Emerging Players: Lead with silicone sheeting configurations targeting pediatric and neonatal intensive care units in German and Swiss university hospitals, where phthalate-free formulations command 40-60% unit premiums and procurement specifications favor specialized suppliers over diversified conglomerates. India's government-funded trauma center construction under the National Health Mission offers white-space penetration with standardized emergency fluid delivery equipment. Direct manufacturer contracting with Osaka and Nagoya distributors bypasses established GPO-controlled channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core inflation technology assets, particularly angiography-adjacent pressure delivery platforms with transferable core competencies. Five-to-ten year viability hinges on automation capabilities and notified body relationship depth rather than brand equity alone. Watch for CDSCO registration acceleration in India as inflection signal for emerging market infrastructure plays.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body relationships in Germany and Switzerland filter procurement toward certified vendors. |
| Silicone Material Substitution Program | REACH Annex XVII compliance captures preference share in pediatric intensive care segments. |
| RFID-Enabled Inventory Tracking Integration | Embedded sensor technology opens subscription-based fleet management contracts for disposable systems. |
| Hospital System Partnership Expansion | United States GPO multi-year awards bundle pressure infusion bags with higher-margin warming devices. |
| Pre-Hospital EMS Fleet Standardization | Japan and South Korea ambulance upgrades extend utilization beyond traditional hospital boundaries. |
Study Parameters
Operator-level perspectives from biomedical engineers, cleanroom production managers, hospital purchasing committee members, and group purchasing organization contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and REACH Annex XVII substance evaluation timelines. Bottom-up demand modeling across material type, product configuration, and end-user segment triangulated against top-down market sizing from polymer welding equipment shipments and notified body certification records.
Sensitivity analysis tested forecast robustness across alternative scenarios for PVC resin price volatility, EU MDR enforcement timing, and mechanical pump substitution rates in high-acuity surgical suites. The analytical framework modeled volume and value outputs across material composition, product type, application setting, and end-user procurement authority throughout the projection horizon. CAGRs derived from segment-level growth drivers including trauma protocol standardization, EMS modernization cycles, and silicone substitution timelines. Industry-specific inputs incorporated ethylene feedstock futures curves and ECHA substance evaluation pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EU MDR compliance investment, stable polymer welding technician availability, and continued hospital disposable-only policy hardening would require recalibration. Forecasts reflect documented assumptions regarding REACH enforcement milestones and trauma center construction funding continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Cerebral Vascular Stent Market