
 Resuscitation Bags Market | 2026-2036
Resuscitation Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Resuscitation Bags Market Analytics
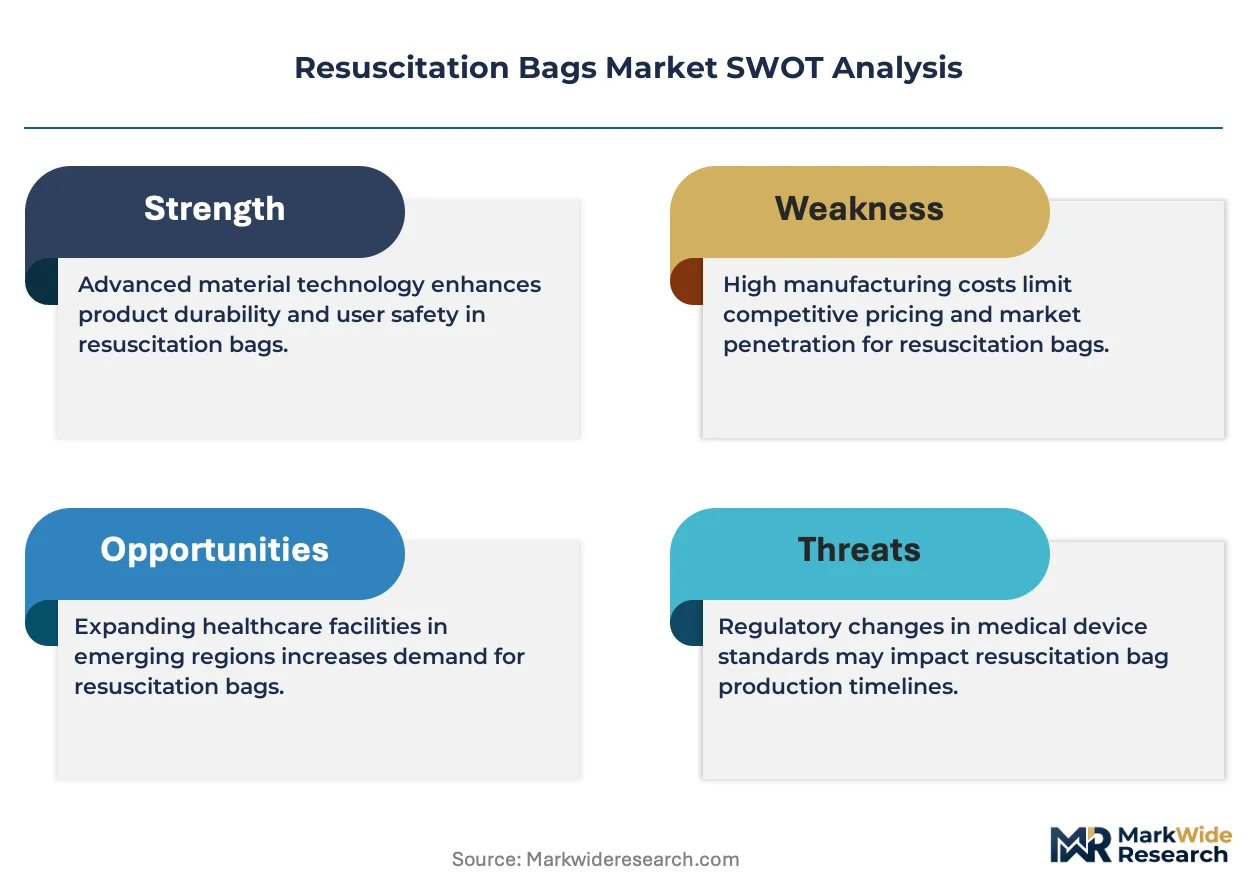
The EU Medical Device Regulation is restructuring procurement criteria across European healthcare systems, forcing manufacturers to revalidate biocompatibility documentation for latex and silicone components. Ambu A/S leverages its Nordic manufacturing base to sustain CE-marked product lines with streamlined regulatory dossiers. Smiths Medical anchors its position through specialized distribution partnerships with national hospital purchasing consortia. Teleflex Incorporated competes on scale, operating high-volume PVC resuscitation bag production for cost-sensitive emergency responder segments.
A resuscitation bag is a handheld, self-inflating device comprising a flexible reservoir bag, one-way valve assembly, and patient connector, typically constructed from medical-grade silicone or polyvinyl chloride with latex-free alternatives for allergy-sensitive populations; it delivers positive-pressure ventilation to patients with inadequate spontaneous respiration across pre-hospital and clinical settings. Disposable product types command the dominant volume share as infection control protocols harden against cross-contamination risks in hospital care and ambulance services. Silicone material segments attract premium positioning due to superior autoclavability and extended service life in reusable configurations, while PVC formulations occupy the high-volume, price-elastic tier for single-use emergency applications.
The FDA's 510(k) clearance framework governs market entry for U.S.-distributed resuscitation bags, with particular scrutiny of valve reliability testing under emergency-use conditions. ISO 10651 standards define performance benchmarks for manual resuscitators across European and Asia-Pacific jurisdictions, creating harmonized technical barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving material restrictions under REACH and state-level environmental mandates, as these will progressively disqualify certain PVC plasticizer chemistries and reshape supplier qualification requirements.
Market Dynamics
The EU Medical Device Regulation is compressing supplier qualification timelines while ambulance service modernization programs across Germany, France, and Italy accelerate replacement cycles for manual resuscitators.
Growth Catalysts
- Emergency department volume expansion:Hospital systems in Germany and the United States are expanding dedicated resuscitation bays, driving disposable bag procurement through centralized purchasing consortia.
- REACH material compliance deadlines:The European Chemicals Agency is phasing out specific phthalate plasticizers in PVC formulations, forcing manufacturers to reformulate and revalidate biocompatibility dossiers ahead of enforcement windows.
- Silicone autoclavability:Reusable silicone resuscitation bags deliver extended service life in hospital anesthesia departments, reducing total cost of ownership despite premium upfront pricing.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone elastomer production concentrates among a limited set of European and Asian chemical suppliers, exposing device manufacturers to input cost volatility and allocation constraints.
- FDA 510(k) pathway complexity:The FDA requires extensive valve reliability testing documentation for emergency-use conditions, extending regulatory timelines for new market entrants without predicate device strategies.
- Manual resuscitator substitution:Mechanical ventilators and automated resuscitation systems are displacing handheld bags in tertiary hospital intensive care units where staff-to-patient ratios permit capital equipment deployment.
Strategic Opportunities
- India ambulance fleet expansion:The country's national health mission is procuring emergency medical equipment for district-level ambulance services, creating volume demand for cost-optimized PVC resuscitation bags.
- Telemedicine-integrated emergency response:Convergence of manual resuscitation with real-time video telemetry enables remote physician guidance during pre-hospital cardiac arrest interventions.
- Japan's PMDA streamlined review:Japan's Pharmaceuticals and Medical Devices Agency has implemented priority review pathways for disaster-response medical equipment, accelerating market access for resuscitation devices designated for national stockpile programs.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face capacity constraints at accredited laboratories, delaying product launches for manufacturers with reformulated material platforms.
- Latex-free validation complexity:Eliminating natural rubber latex from valve assemblies and patient connectors requires extensive alternative elastomer qualification, complicating supply chain transitions for legacy product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resuscitation Bags Market |
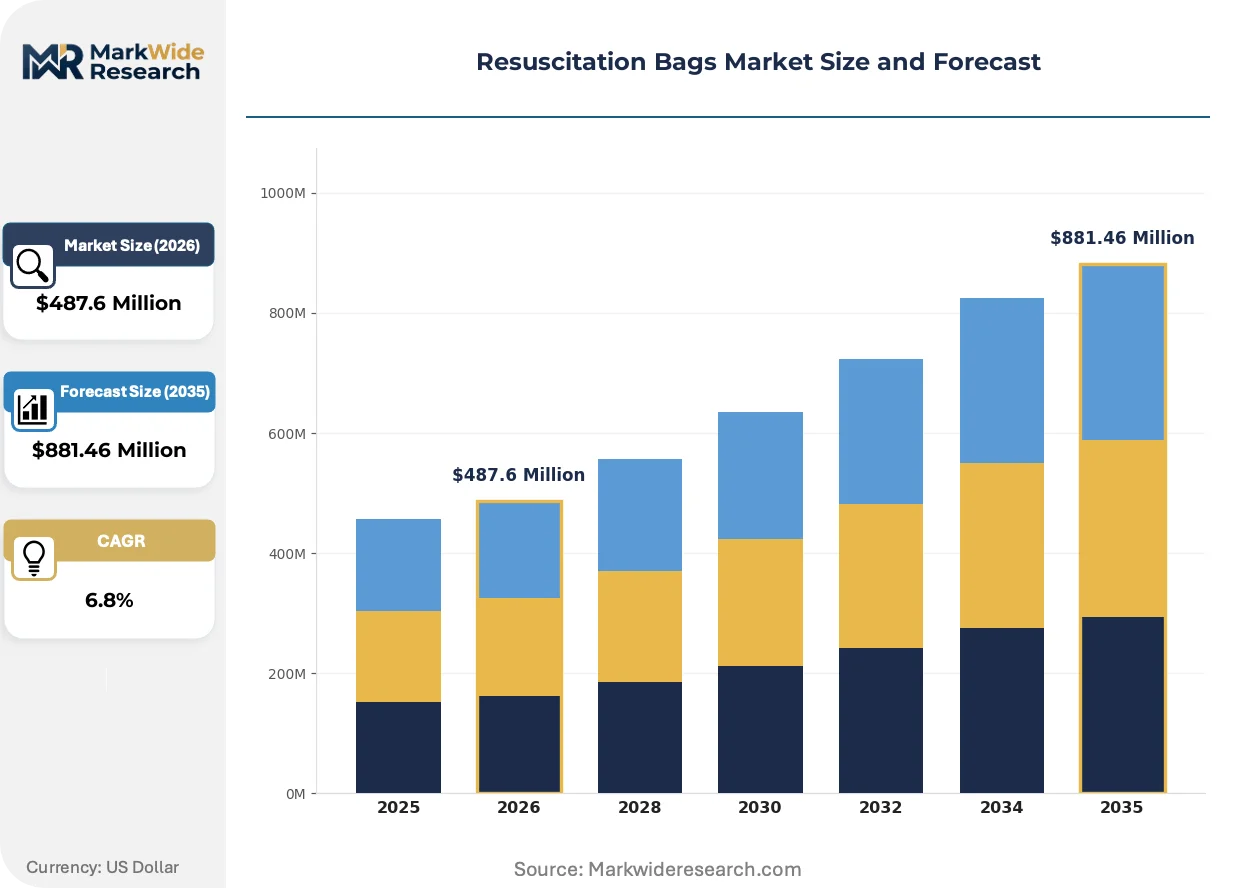
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Disposable, Reusable Application: Emergency Medicine, Home Care, Ambulance Services, Hospital Care Material: Latex, Silicone, PVC, Rubber End User: Hospitals, Clinics, Emergency Responders, Nursing Homes |
| Companies Covered | Teleflex Incorporated, Smiths Medical, Ambu A/S, WEINMANN Emergency Medical Technology, Koninklijke Philips N.V., Medtronic plc, Laerdal Medical, ResMed Inc., Vyaire Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resuscitation Bags Market Evolving Landscape
Material science advances and regulatory harmonization pressures are restructuring competitive positioning in manual resuscitation equipment, with sustainability mandates and connectivity integration emerging as decisive design parameters.
Single-use silicone resuscitation bags are electrifying product development roadmaps at major device manufacturers. These hybrid formulations combine the autoclavability of traditional silicone with disposability economics, targeting hospital infection control committees in Germany and the Netherlands. Emergency medicine departments are electrifying their procurement specifications to favor this material class, compressing PVC volume share in premium acute care segments.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC reformulation across European supply chains. The European Chemicals Agency's sunset dates for DEHP and DINP chemistries are triggering requalification waves that favor manufacturers with dedicated regulatory affairs infrastructure. German hospital purchasing consortia are responding by consolidating supplier relationships around CE-marked product lines with validated alternative plasticizer documentation.
Ambulance service operators are compressing equipment replacement cycles from seven-year to four-year intervals, unbundling resuscitation bags from comprehensive vehicle outfitting contracts. National procurement frameworks in France and Italy are displacing fragmented municipal purchasing, concentrating volume among distributors with dedicated emergency responder service networks. This consolidation is most visible in Spain's regionalized emergency medical systems, where autonomous communities are standardizing on single-source agreements for respiratory equipment.
Resuscitation Bags Market Segmentation
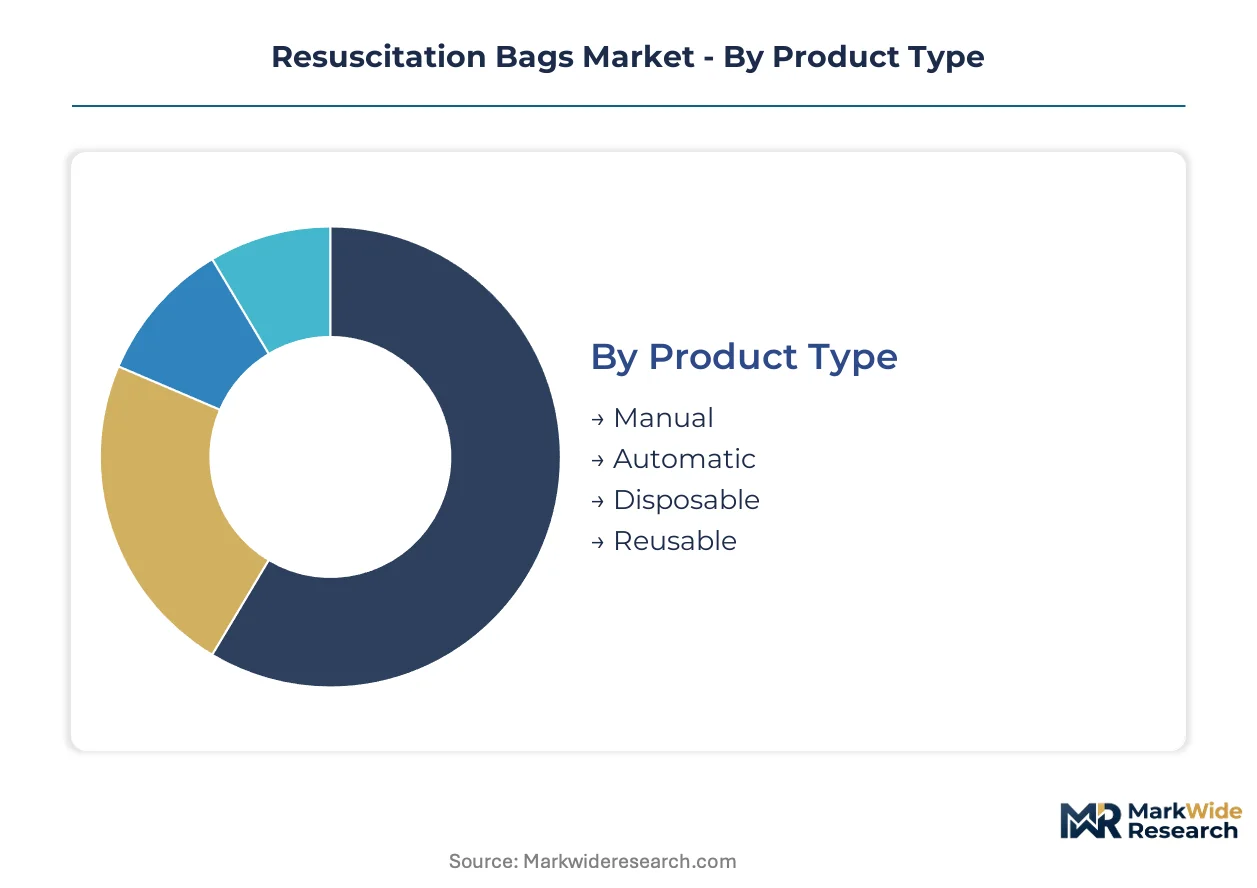
Resuscitation bag procurement diverges sharply across clinical settings, with infection control protocols, sterilization infrastructure, and emergency response workflows dicting material and product type selection. Segmentation reveals how regulatory compliance burdens and total cost-of-ownership calculations fragment purchasing authority between hospital central supply departments and decentralized ambulance fleet operators.
Product Type:
CE marking under EU MDR and FDA 510(k) clearance impose divergent validation requirements: disposable lines demand biocompatibility dossiers per ISO 10993, while reusable configurations require sterilization efficacy documentation under ISO 17665.
- Disposable:Single-use PVC or silicone constructions eliminate cross-contamination risk in high-turnover emergency departments. German hospital purchasing consortia are consolidating volume around CE-marked disposable lines with validated DEHP-free plasticizer formulations ahead of REACH enforcement windows.
- Manual:Handheld self-inflating bags with mechanical valve assemblies dominate pre-hospital settings where power independence is mandatory. Ambulance services in France and Italy specify manual units for basic life support tiers, with procurement shifting from municipal fragmentation to national framework agreements.
- Reusable:Medical-grade silicone constructions withstand repeated steam sterilization cycles in hospital anesthesia departments. Premium upfront pricing is offset by extended service life in facilities with centralized sterilization infrastructure.
- Automatic:Pressure-cycled or flow-triggered devices reduce operator fatigue during prolonged resuscitation. Demand concentrates in tertiary hospital intensive care units with mechanical ventilator substitution occurring where capital budgets permit.
Leading the category by volume: Disposable. Growing fastest: Automatic.
Application:
End-use setting determines performance specifications, with pre-hospital durability requirements contrasting against hospital precision demands.
- Emergency Medicine:Hospital emergency departments require rapid-deployment bags with standardized connector interfaces for seamless ventilator handoff. Volume concentrates in Germany and the United States as dedicated resuscitation bay expansion drives procurement through centralized purchasing.
- Ambulance Services:Field-use devices must withstand temperature extremes and mechanical shock without valve degradation. Fleet modernization programs across Germany, France, and Italy are compressing replacement cycles from seven-year to four-year intervals.
- Hospital Care:Inpatient wards and perioperative suites favor reusable silicone configurations with autoclavability. Infection control committees in the Netherlands specify hybrid single-use silicone for premium acute care segments.
- Home Care:Lightweight, compact designs serve palliative respiratory support and neonatal transition care. Demand remains fragmented across durable medical equipment suppliers with limited standardization.
Maximum procurement standardization: Emergency Medicine. Steepest expansion trajectory: Ambulance Services.
Material:
Raw material selection locks manufacturers into distinct regulatory pathways, with silicone requiring specialized elastomer supply agreements and PVC exposed to REACH plasticizer phaseouts.
- Silicone:Platinum-cured medical-grade elastomers deliver superior tensile strength and thermal stability for reusable applications. Supply concentrates among European and Asian chemical suppliers, exposing device manufacturers to allocation constraints.
- PVC:Cost-optimized formulations dominate high-volume disposable emergency applications. ECHA sunset dates for DEHP and DINP are forcing reformulation and revalidation waves across European supply chains.
- Latex:Natural rubber constructions persist in legacy valve components despite allergy sensitization risks. Elimination requires extensive alternative elastomer qualification, complicating supply chain transitions.
- Rubber:Synthetic elastomer alternatives to latex serve allergy-sensitive populations with modified compression set characteristics. Niche positioning limits volume scale.
Highest margin capture: Silicone. Fastest regulatory displacement: PVC.
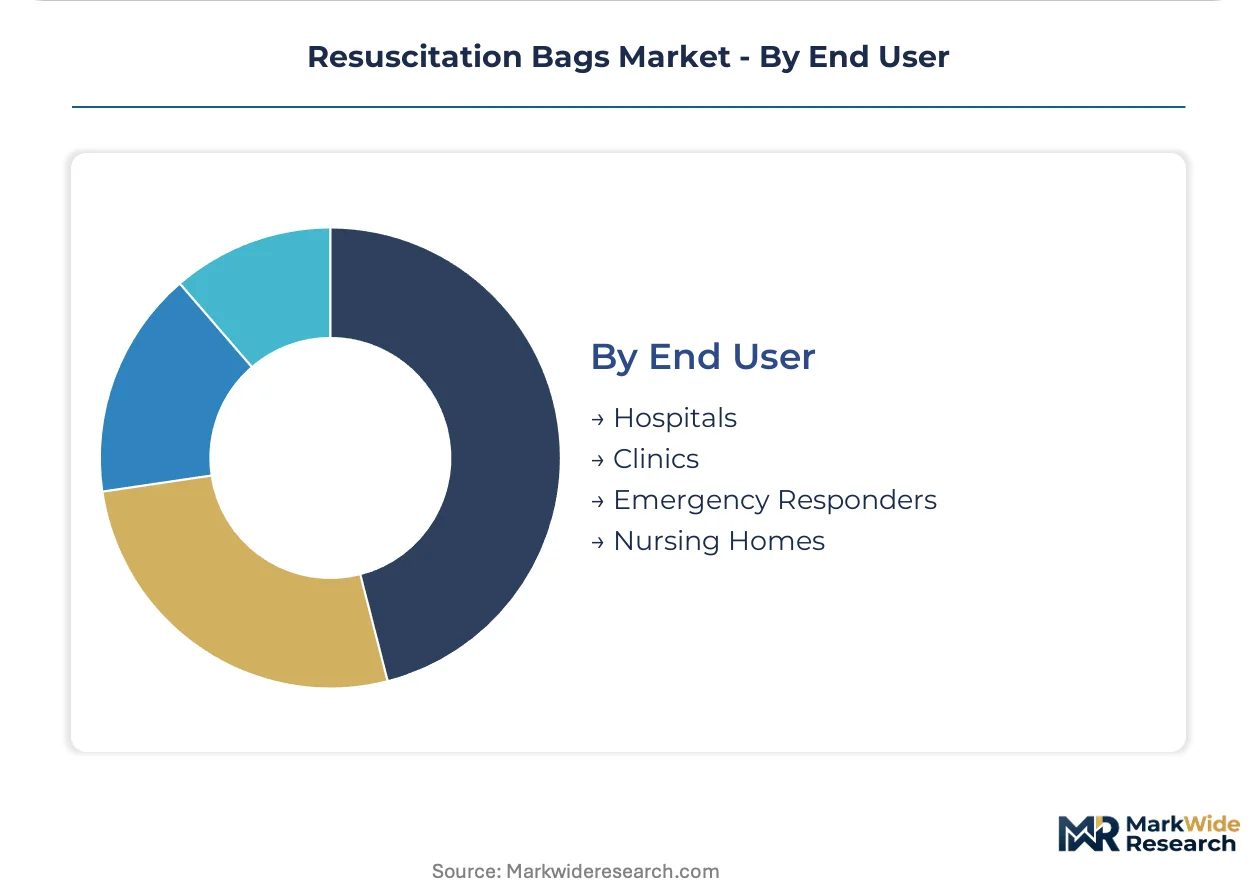
End User:
Purchasing authority fragmentation mirrors care delivery structure, with hospitals exercising centralized procurement and emergency responders operating through distributor service networks.
- Hospitals:Integrated delivery networks leverage volume concentration for price negotiation on disposable lines. German hospital purchasing consortia are consolidating supplier relationships around validated alternative plasticizer documentation.
- Emergency Responders:Fire departments and municipal ambulance authorities prioritize equipment durability and rapid field replacement. Spain's regionalized emergency medical systems are standardizing on single-source agreements for respiratory equipment.
- Clinics:Outpatient surgical centers and urgent care facilities balance cost constraints with infection control requirements. Procurement typically follows hospital system affiliate agreements.
- Nursing Homes:Long-term care facilities deploy resuscitation bags for respiratory emergency backup with limited sterilization infrastructure. Demand correlates with skilled nursing bed capacity expansion.
Volume concentration: Hospitals. Procurement consolidation momentum: Emergency Responders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European manufacturers dominate resuscitation bag production capacity, while demand concentrates in German emergency medicine systems and North American hospital networks. Regulatory divergence between FDA 510(k) pathways and EU MDR compliance timelines fragments market entry strategies. Procurement consolidation across German, French, and Italian ambulance services is reshaping distributor relationships.
Germany
Emergency department volume expansion and ambulance fleet modernization drive procurement concentration. The EU Medical Device Regulation forces revalidation of biocompatibility documentation for latex and silicone components. Bavaria's hospital purchasing consortia consolidate supplier relationships around CE-marked product lines with validated alternative plasticizer formulations.
United States
Hospital systems expand dedicated resuscitation bays through centralized purchasing networks. The FDA's 510(k) clearance framework requires extensive valve reliability testing documentation, extending regulatory timelines. Greater Boston and Pacific Northwest medical device clusters anchor domestic distribution infrastructure for emergency responder segments.
France
Ambulance service modernization compresses equipment replacement cycles from seven-year to four-year intervals. National procurement frameworks displace fragmented municipal purchasing for respiratory equipment. The Île-de-France region standardizes on single-source agreements for manual resuscitators across regional emergency medical systems.
India
The national health mission procures emergency medical equipment for district-level ambulance services, creating volume demand for cost-optimized PVC configurations. CDSCO medical device regulations tighten import compliance requirements. Maharashtra and Gujarat manufacturing clusters supply domestic hospital networks with disposable resuscitation bags.
Japan
PMDA priority review pathways accelerate market access for disaster-response medical equipment designated for national stockpile programs. Aging demographics expand hospital care segments requiring reusable silicone configurations. The Kanto region concentrates procurement authority for tertiary hospital intensive care units.
Resuscitation Bags Market Competitive Landscape
The competitive structure tilts toward diversified medical device conglomerates with dedicated regulatory affairs infrastructure. Market entry barriers concentrate among manufacturers with established CE-marked product lines and FDA-cleared predicate devices. Three archetypes dominate: integrated respiratory device specialists, emergency medical equipment generalists, and disposable consumables scale operators. Capacity expansion and strategic distribution partnerships represent the dominant competitive moves, with manufacturers prioritizing consolidation of national hospital purchasing consortia relationships.
Within the integrated respiratory device tier, Teleflex Incorporated and Smiths Medical exemplify scale-driven positioning across cost-sensitive emergency responder segments. Ambu A/S occupies a position anchored in Nordic manufacturing bases with streamlined regulatory dossiers for CE-marked product lines. These three entities represent the archetype of manufacturers leveraging dedicated regulatory infrastructure to navigate divergent FDA and EU MDR compliance timelines.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Smiths Medical |
| Ambu A/S |
| WEINMANN Emergency Medical Technology |
| Koninklijke Philips N.V. |
| Medtronic plc |
| Laerdal Medical |
| ResMed Inc. |
| Vyaire Medical Inc. |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII sunset dates for DEHP and DINP phthalate plasticizers gate qualified PVC supply to European device manufacturers while simultaneously segmenting pricing tiers between compliant and non-compliant product lines. German hospital purchasing consortia now demand validated alternative plasticizer documentation as a prerequisite for contract eligibility, compressing margins for reformulation-lagged competitors and concentrating premium-tier pricing power among early-validated suppliers.
Pricing Analysis
Value-based pricing anchored to sterilization cycle throughput and infection control outcomes dominates hospital procurement specifications for reusable silicone configurations. Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured silicone autoclavable units from DEHP-free PVC disposables and conventional PVC emergency responder bags. Cost compression in economy-tier PVC runs through REACH compliance deadlines as manufacturers absorb revalidation expenses without full price pass-through. Emergency responder segments exhibit highest price sensitivity due to municipal budget fragmentation, while tertiary hospital anesthesia departments accept premium positioning for extended service life metrics.
Supply Chain Analysis
Direct-to-hospital-GPO channels handle high-volume disposable demand from integrated delivery networks in Germany and the United States, while distributor service networks manage fragmented emergency responder procurement across France and Italy. Medical-grade silicone elastomer production concentrates in Germany, Japan, and South Korea, exposing device manufacturers to allocation constraints during supply shocks. Raw material platforms rest on platinum-cured silicone compounds, DEHP-free PVC formulations, and synthetic latex alternatives for allergy-sensitive valve assemblies. Single-source vulnerability concentrates in European specialty chemical suppliers qualified for ISO 10993 biocompatibility dossiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation has erected a cost-of-compliance barrier that rewards manufacturers with dedicated regulatory affairs infrastructure and CE-marked product lines, effectively moating incumbents against undercapitalized entrants.
For Market Incumbents: Extend sterilization validation capabilities into single-use silicone hybrid formulations to capture infection control committee specifications in Dutch and German acute care segments. Deepen backward integration into medical-grade silicone elastomer supply through captive agreements with German and Japanese chemical suppliers, insulating against allocation constraints that threaten production continuity for reusable product lines. For New Entrants and Emerging Players: Japan's PMDA priority review pathway for disaster-response medical equipment opens a window for stockpile-designated resuscitation devices with accelerated market access timelines. Target India's district-level ambulance fleet expansion under the national health mission with cost-optimized PVC configurations qualified under CDSCO import compliance frameworks. Pursue telemedicine-integrated emergency response partnerships as a differentiated go-to-market angle for pre-hospital cardiac arrest interventions. For Investors and Strategic Acquirers: Consolidation of France's Île-de-France regional emergency medical systems onto single-source agreements is the leading indicator that distributor service network scale will determine downstream pricing power in European ambulance markets. Position acquisition screening around mid-cap device manufacturers with validated EU MDR technical documentation and established GPO contracts manager relationships. Monitor CDSCO enforcement intensity against import non-compliance as a signal for domestic Indian manufacturing consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation revalidation secures German hospital purchasing consortia contract eligibility. |
| Hospital System Partnership | GPO contracts manager relationships concentrate volume across integrated delivery networks in the United States. |
| Backward Integration | Captive supply agreements with German silicone elastomer suppliers reduce input cost volatility exposure. |
| Software Companion Development | Telemedicine-integrated emergency response enables remote physician guidance during pre-hospital interventions. |
| Reimbursement Strategy | Japan's PMDA priority review accelerates national stockpile designation for disaster-response equipment. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EUDAMED CE marking registrations, and ISO 10651 standard harmonization records, complemented by interviews with hospital purchasing committee chairs, ambulance fleet procurement officers, biomedical engineers specializing in respiratory devices, and GPO contracts managers. Secondary validation drew from ECHA REACH enforcement timelines, CDSCO medical device import compliance bulletins, and PMDA priority review pathway designations. Bottom-up demand modeling from end-use procurement volumes was triangulated against top-down manufacturer capacity assessments.
Segment-level outputs across the analysis window reflect disaggregation by product type, application setting, material platform, and end-user purchasing authority. The analytical framework modeled emergency department volume expansion, ambulance fleet modernization replacement cycles, and REACH plasticizer phaseout enforcement windows as demand drivers. CAGRs were derived from regression analysis of historical procurement data against regulatory compliance deadline impacts.
The model assumes a particular technology adoption path for single-use silicone hybrid formulations; alternative pathways favoring extended PVC service life through alternative plasticizer innovation would alter the material segment outlook. Forecasts reflect assumptions regarding ECHA enforcement intensity, PMDA review pathway throughput, and CDSCO import compliance tightening. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market