
 North America Industrial Duct for Dust Collection Market | 2026-2036
North America Industrial Duct for Dust Collection Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Duct for Dust Collection Market Analytics
Mexico's industrial corridor expansion is reconfiguring supply chain flows for fabricated duct systems. Donaldson Company, Inc. leverages its filtration technology heritage to anchor premium system integration. Nordfab sustains market presence through modular quick-fit duct architecture that reduces installation labor. Imperial Systems, Inc. specializes in heavy-gauge welded configurations for abrasive dust environments.
Industrial duct for dust collection comprises rigid or flexible conduit systems engineered from galvanized steel, stainless steel, aluminum, or coated fabrics, typically fabricated in diameters ranging from 3 to 48 inches with sealed longitudinal seams to maintain negative pressure integrity. These systems transport particulate-laden air streams from capture points to filtration or exhaust equipment, protecting worker respiratory health and preventing combustible dust accumulation. Metal ducts occupy the dominant value share given durability demands in high-temperature and abrasive applications, while flexible duct variants capture growth in retrofit installations where routing constraints limit rigid system feasibility. Pharmaceutical cleanroom applications command premium pricing due to electropolished stainless steel requirements and documentation protocols.
OSHA combustible dust standards and EPA National Emission Standards for Hazardous Air Pollutants shape product specifications and inspection frequencies across United States facilities. Canadian Centre for Occupational Health and Safety guidelines and Mexico's STPS workplace safety regulations create comparable compliance obligations that sustain replacement demand. Stakeholders must monitor evolving MSHA mining dust rules and state-level air quality implementation plans that could tighten particulate thresholds beyond federal baselines.
Market Dynamics
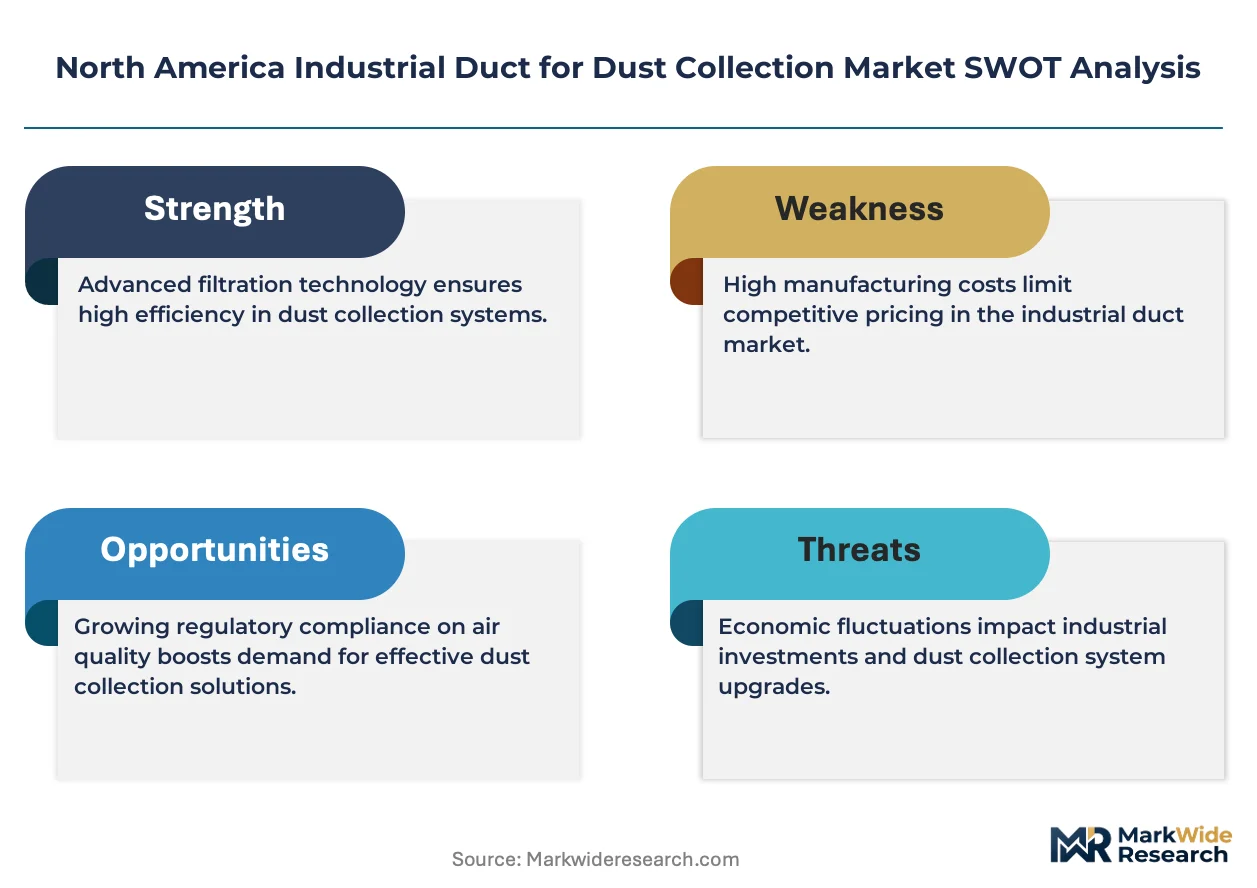
OSHA combustible dust enforcement is compressing replacement cycles across Great Lakes manufacturing corridors, forcing facilities to accelerate duct infrastructure upgrades beyond historical depreciation schedules.
Growth Catalysts
- OSHA Combustible Dust National Emphasis Program:Inspection frequency increases in woodworking and metalworking facilities drive mandatory system overhauls. Facilities face citation exposure exceeding $150,000 per violation, accelerating capital deployment.
- Stainless steel electropolishing:Pharmaceutical cleanroom specifications now require documentation protocols that metal fabricators must embed into production workflows, creating premium tier demand.
- Mexico industrial corridor expansion:Automotive and aerospace manufacturing clusters in Querétaro and Nuevo León are constructing greenfield facilities with integrated dust collection infrastructure.
Market Restraints
- Galvanized steel price volatility:Zinc input costs fluctuate with commodity markets, compressing fabrication margins and destabilizing project quoting.
- Regional supplier concentration:Heavy-gauge welded duct capacity clusters in Ohio and Pennsylvania, creating geographic supply risk for western Canadian and Mexican projects.
- Welding labor scarcity:Certified pressure-vessel welders command premium wages, extending lead times for custom industrial configurations.
Strategic Opportunities
- Modular quick-fit retrofit penetration:Aging facilities in Michigan and Ontario seek slide-together duct systems that minimize production downtime during installation.
- Canadian carbon pricing alignment:Federal output-based pricing system creates incentive structures for energy-efficient fan and blower integration with duct networks.
- Smart sensor convergence:Pressure differential monitoring and IoT-enabled clog detection are merging with traditional duct architecture, enabling predictive maintenance service models.
Industry Challenges
- NFPA 654 compliance documentation:Facilities struggle to maintain dust hazard analysis records across multi-site operations, exposing operators to liability.
- Legacy mechanical integration:New duct specifications must interface with decades-old collector units lacking standardized connection geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Duct for Dust Collection Market |
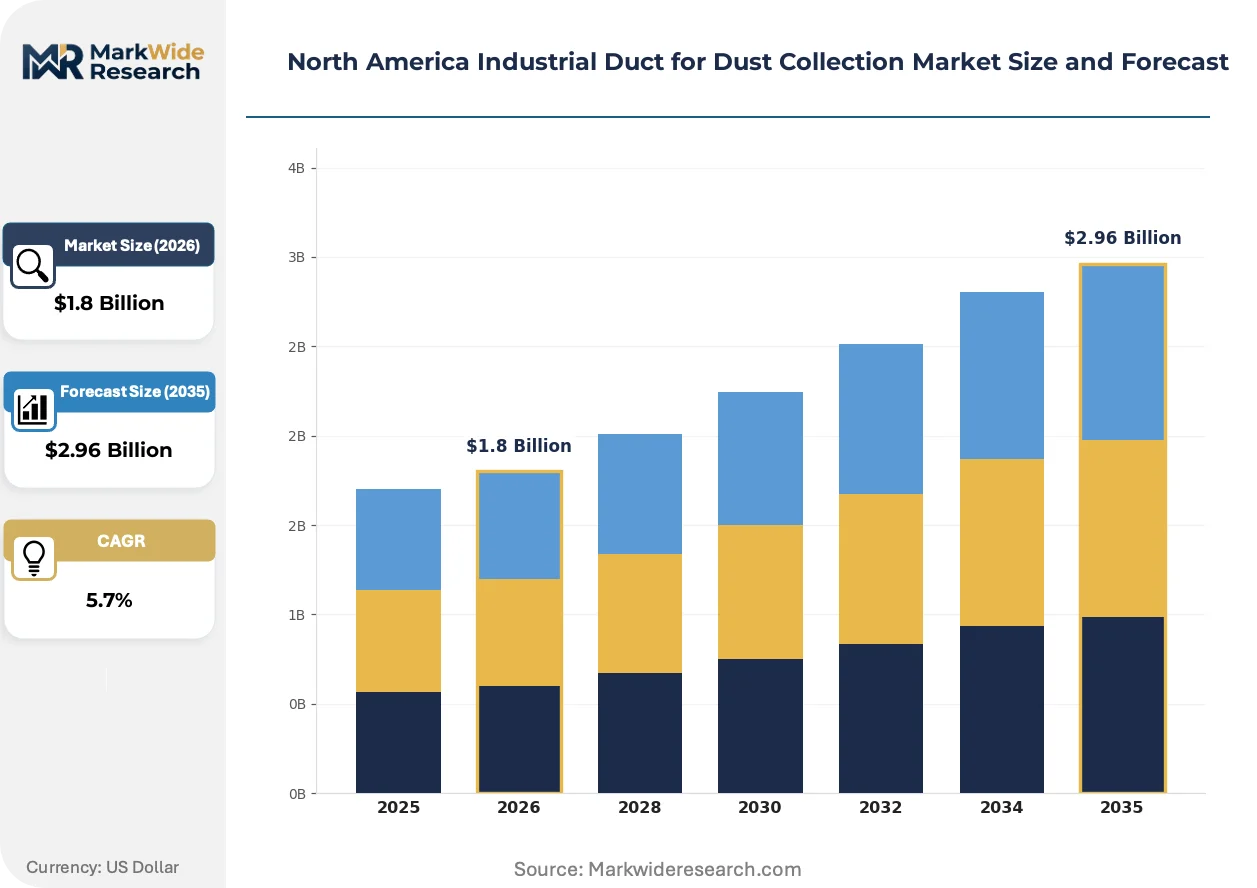
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Ducts, Flexible Ducts, Fabric Ducts, PVC Ducts Application: Manufacturing, Woodworking, Pharmaceuticals, Food Processing End User: Manufacturers, Contractors, Facility Managers, Distributors Installation Type: Indoor, Outdoor, Retrofit, New Construction |
| Companies Covered | Spiral MFG, US Duct, Nordfab, Carolina Air Systems, Donaldson Company, Inc., Penn American Inc., Oneida Air Systems, Inc., Imperial Systems, Inc., Fab-Tech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Duct for Dust Collection Market Evolving Landscape
Fabrication methods and material specifications are diverging across end-use verticals, with customization depth becoming the primary competitive axis rather than unit economics alone.
Spiral-lock seam duct technology is hybridizing with traditional welded construction in abrasive dust environments. Mining operations in Arizona and Nevada now specify hybrid configurations that combine spiral-forming speed with reinforced wear plates at high-velocity elbows. This convergence is compressing the price gap between commodity spiral duct and engineered welded systems, forcing mid-tier fabricators to specialize or exit.
EPA National Emission Standards for Hazardous Air Pollutants maximum achievable control technology reviews are tightening particulate thresholds for chemical processing facilities. The industrial consequence is mandatory downstream duct insulation and condensation control in corrosive gas streams. Pharmaceutical manufacturers in New Jersey and North Carolina face the steepest compliance timelines, accelerating specification of fluoropolymer-coated stainless interiors.
Buyer concentration among national facility management contractors is consolidating procurement authority previously held by plant engineers. Third-party maintenance providers now specify duct configurations across multi-site industrial portfolios, displacing original equipment manufacturer influence. This pattern is most visible in food processing networks spanning the US Midwest, where standardized duct geometries reduce spare parts inventory complexity.
North America Industrial Duct for Dust Collection Market Segmentation
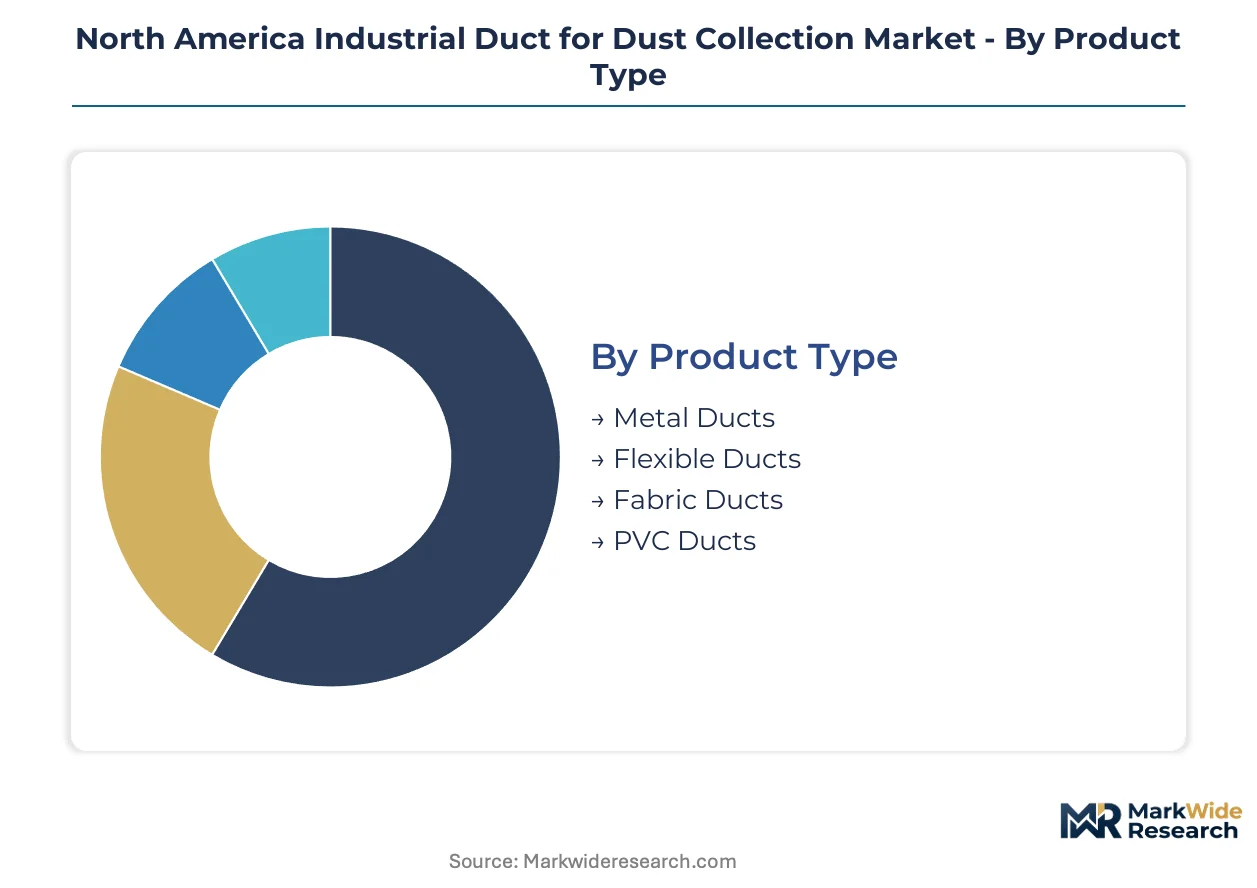
Industrial duct specifications diverge sharply across material tolerances, installation constraints, and regulatory exposure levels. Each segmentation axis reveals distinct procurement patterns that shape vendor positioning and margin structures.
Product Type:
Use-case spectrum spans permanent infrastructure investments to temporary routing solutions, with material durability dictating replacement cycles and total cost of ownership calculations.
- Metal Ducts:Fabricated from galvanized steel, stainless steel, or aluminum with sealed longitudinal seams to maintain negative pressure integrity in high-temperature and abrasive environments. Great Lakes manufacturing corridors drive replacement demand as OSHA combustible dust enforcement compresses infrastructure upgrade timelines beyond historical depreciation schedules.
- Flexible Ducts:Constructed from coated fabrics or reinforced polymers enabling routing around structural obstacles in constrained mechanical spaces. Woodworking facilities across Michigan and Ontario specify these for retrofit installations where production downtime minimization outweighs long-term durability trade-offs.
- Fabric Ducts:Porous textile distribution systems for low-velocity air dispersion in cleanroom and climate-controlled environments.
- PVC Ducts:Corrosion-resistant thermoplastic configurations for chemical fume and acid gas handling in specialized process applications.
The dominant share belongs to Metal Ducts, while Flexible Ducts is closing the gap fastest as aging industrial infrastructure drives retrofit demand.
Application:
Compliance intensity varies dramatically across verticals, with pharmaceutical and food processing commanding premium specifications due to contamination liability exposure.
- Manufacturing:Heavy-gauge welded systems for metalworking, automotive, and general industrial particulate capture. Ohio and Pennsylvania fabrication clusters supply Great Lakes corridor demand where EPA National Emission Standards for Hazardous Air Pollutants enforcement drives system overhauls.
- Woodworking:Combustible dust collection infrastructure sized for high-volume chip and fine particle transport. OSHA National Emphasis Program inspection frequency increases accelerate capital deployment across sawmills and millwork facilities facing citation exposure exceeding $150,000 per violation.
- Pharmaceuticals:Electropolished stainless steel with documentation protocols for cleanroom particulate control.
- Food Processing:Sanitary-grade configurations meeting USDA and FDA sanitary design requirements for edible product handling.
Manufacturing captures the largest procurement volume, though Pharmaceuticals exhibits the steepest expansion trajectory as electropolishing documentation requirements deepen vendor specialization.
End User:
Procurement authority is consolidating toward third-party maintenance providers with multi-site standardization mandates.
- Manufacturers:Direct capital expenditure by industrial facility owners with in-house engineering specifications. Automotive and aerospace clusters in Querétaro and Nuevo León integrate dust collection infrastructure into greenfield construction with long-term operational ownership models.
- Contractors:Installation and integration specialists specifying duct configurations as part of bundled mechanical system delivery.
- Facility Managers:Third-party maintenance providers consolidating procurement across distributed industrial portfolios, displacing original equipment manufacturer influence through standardized geometries that reduce spare parts inventory complexity.
- Distributors:Inventory-holding intermediaries serving fragmented regional fabrication demand with quick-turn replacement components.
Manufacturers retain direct procurement leadership, yet Facility Managers are gaining share fastest as outsourced maintenance models penetrate food processing networks spanning the US Midwest.
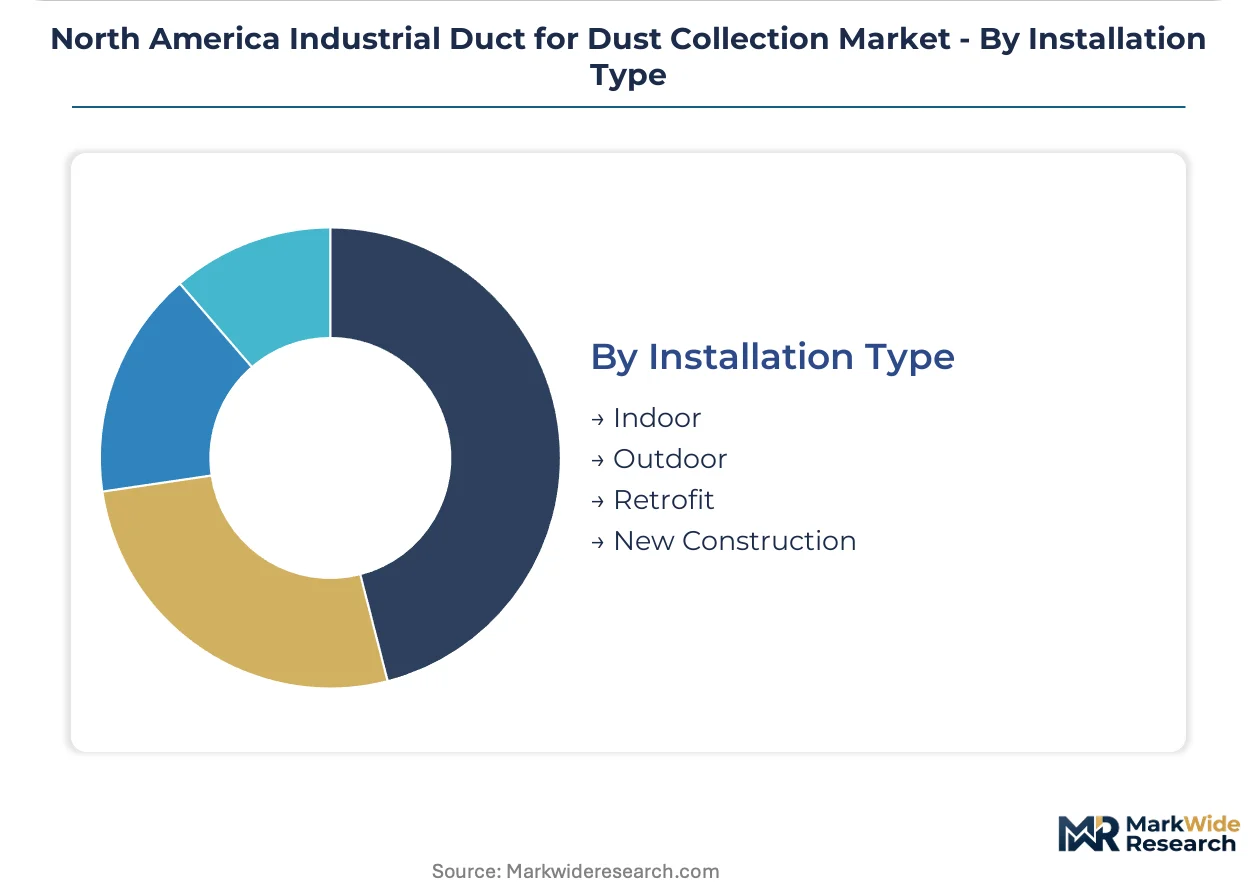
Installation Type:
Project timing relative to facility lifecycle determines labor cost structures and system integration complexity.
- Indoor:Climate-protected routing through mechanical rooms and process areas with standardized connection geometries. New Jersey and North Carolina pharmaceutical manufacturers face compressed EPA compliance timelines that accelerate specification of fluoropolymer-coated stainless interiors for corrosive gas streams.
- Outdoor:Weather-resistant configurations with insulation and condensation control for external collector placement.
- Retrofit:Slide-together modular systems minimizing production downtime in aging Michigan and Ontario facilities where routing constraints limit rigid duct feasibility.
- New Construction:Integrated design-build specifications with optimized routing and fan-blower integration under Canadian federal output-based pricing system incentives.
Indoor installations command the dominant project share, while Retrofit is climbing the fastest as legacy mechanical infrastructure reaches replacement age across North American industrial corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply by industrial base age and regulatory enforcement intensity. The United States prioritizes replacement cycles in legacy manufacturing corridors, while Mexico and Canada emphasize greenfield integration and carbon-aligned efficiency standards respectively.
United States
OSHA combustible dust enforcement compresses infrastructure upgrade timelines in aging Great Lakes manufacturing facilities. EPA National Emission Standards for Hazardous Air Pollutants maximum achievable control technology reviews tighten particulate thresholds for chemical processors. Ohio and Pennsylvania fabrication clusters supply heavy-gauge welded duct demand from automotive and metalworking operations facing citation exposure exceeding $150,000 per violation.
Canada
Federal output-based pricing system creates incentive structures for energy-efficient fan and blower integration with duct networks. Canadian Centre for Occupational Health and Safety guidelines sustain replacement demand comparable to US compliance obligations. Ontario woodworking and automotive facilities in the Windsor-Toronto corridor drive modular quick-fit retrofit specifications that minimize production downtime.
Mexico
STPS workplace safety regulations create compliance frameworks accelerating capital deployment in expanding industrial zones. Automotive and aerospace manufacturing clusters in Querétaro and Nuevo León construct greenfield facilities with integrated dust collection infrastructure. Northern border states concentrate maquiladora operations specifying standardized duct geometries to reduce cross-border spare parts inventory complexity.
Southwest United States
Mining operations in Arizona and Nevada specify hybrid spiral-lock seam configurations combining forming speed with reinforced wear plates at high-velocity elbows. MSHA mining dust rules evolution pressures sub-surface and surface extraction facilities toward predictive maintenance sensor integration. Phoenix and Tucson fabrication capacity serves regional mineral processing demand with compressed lead times versus Great Lakes suppliers.
Southeast United States
Food processing networks spanning Georgia and the Carolinas consolidate procurement authority toward third-party facility managers with multi-site standardization mandates. USDA and FDA sanitary design requirements for edible product handling command premium specifications in poultry and processed food operations. Atlanta and Charlotte distribution hubs channel quick-turn replacement components to fragmented regional fabrication demand.
North America Industrial Duct for Dust Collection Market Competitive Landscape
Capability concentration sits with specialized fabricators holding certified pressure-vessel welding credentials; scale advantage sits with diversified filtration technology providers with integrated system portfolios. The vendor base organizes into three strategic archetypes: premium system integrators leveraging filtration heritage, modular quick-fit specialists optimizing installation labor reduction, and regional heavy-gauge fabricators serving abrasive dust environments. Dominant competitive moves include backward integration into galvanized and stainless steel coil sourcing, and geographic expansion through distributor network consolidation in underserved western Canadian and Mexican markets.
Among premium-tier system integrators, Donaldson Company, Inc. anchors integrated filtration-duct positioning through technology heritage spanning capture-to-exhaust equipment lines. Nordfab occupies the modular architecture vector with quick-fit slide-together systems that reduce field installation labor in retrofit-constrained facilities. Imperial Systems, Inc. represents the heavy-gauge welded specialization archetype, serving mining and metalworking operations with abrasive dust handling requirements. These three anchors illustrate the competitive divergence between integrated technology platforms, installation-efficiency optimization, and durability-focused custom fabrication.
| Leading Market Players |
|---|
| Spiral MFG |
| US Duct |
| Nordfab |
| Carolina Air Systems |
| Donaldson Company, Inc. |
| Penn American Inc. |
| Oneida Air Systems, Inc. |
| Imperial Systems, Inc. |
| Fab-Tech Inc. |
| Others |
Value Network & Pricing Analysis
Ohio and Pennsylvania fabrication clusters concentrate heavy-gauge welded duct capacity, concentrating pricing power among certified pressure-vessel welders who command premium wages. This geographic supply concentration feeds downstream into project quoting volatility, as western Canadian and Mexican buyers face extended lead times that compress margin buffers for distant contractors.
Pricing Analysis
Long-term offtake contracts dominate procurement for automotive and aerospace greenfield facilities in Querétaro and Nuevo León, while spot purchasing persists for emergency replacement components. Three-tier pricing structure across premium, standard, and economy levels separates electropolished stainless pharmaceutical specifications from galvanized woodworking infrastructure and flexible retrofit variants. Cost compression in standard-grade galvanized configurations is intensifying because zinc input commodity volatility destabilizes fabrication margins. Third-party facility managers exhibit highest price sensitivity through multi-site standardization mandates, whereas pharmaceutical cleanroom operators accept premium tiers for documentation protocol compliance.
Supply Chain Analysis
Extended payment terms from national facility management contractors are reshaping supplier financing structures, forcing regional fabricators toward supply-chain finance facilities. Raw material sourcing draws from domestic steel coil producers, Canadian aluminum smelters, and specialized fluoropolymer coating suppliers. Single-source vulnerability concentrates in certified pressure-vessel welding labor pools clustered around Great Lakes manufacturing corridors. Distribution runs through distributor networks consolidating inventory positions in Atlanta and Charlotte hubs to serve fragmented Southeast food processing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across material grades, compliance intensities, and installation constraints creates specialized niche opportunities. Outsourced maintenance model penetration is splintering procurement authority away from plant engineers toward third-party standardizers.
For Market Incumbents: Build regulatory compliance documentation moats around electropolished stainless steel workflows for pharmaceutical cleanroom specifications. Deepen backward integration into galvanized and stainless steel coil sourcing to buffer zinc commodity volatility. Expand certified welding capacity in Phoenix and Tucson to capture Southwest mining demand with compressed lead times versus Great Lakes competitors. For New Entrants and Emerging Players: Establish a beachhead in modular quick-fit retrofit systems for aging Michigan and Ontario woodworking facilities facing OSHA National Emphasis Program citation exposure. Target western Canadian carbon pricing incentive structures with energy-efficient fan-blower integration offerings. Lead with installation labor reduction value propositions that minimize production downtime during mechanical room upgrades. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-integrated duct fabricators with predictive maintenance service model potential over pure commodity spiral-forming operations. Long-term viability hinges on IoT-enabled pressure differential monitoring convergence with traditional metal architecture. Acquisition focus should center on regional heavy-gauge specialists holding MSHA mining certifications. The signal to watch is EPA maximum achievable control technology review acceleration for chemical processing particulate thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Sourcing | Captive supply of galvanized and stainless inputs buffers zinc commodity price volatility for fabrication margins. |
| Geographic Expansion through Distributor Consolidation | Channel control in underserved western Canadian and Mexican markets reduces lead time disadvantages versus Great Lakes clusters. |
| Smart Sensor Convergence with Duct Architecture | Pressure differential monitoring and IoT-enabled clog detection enable predictive maintenance service revenue streams. |
| Certified Welding Capacity Addition in Southwest | Phoenix and Tucson proximity to Arizona and Nevada mining operations captures hybrid spiral-lock seam demand with faster fulfillment. |
| Pharmaceutical Documentation Protocol Investment | Electropolished stainless steel workflow certification secures premium tier positioning in New Jersey and North Carolina cleanroom markets. |
Research Methodology
Cross-validation between primary interviews with plant engineers, maintenance directors, and OEM procurement teams and secondary validation through OSHA enforcement databases, EPA National Emission Standards for Hazardous Air Pollutants filings, and customs trade data anchors the qualitative findings. Bottom-up triangulation across fabrication facility capacity assessments and top-down demand modeling from end-use vertical capital expenditure patterns ensures analytical robustness.
Calibration against historical replacement cycle data and regulatory enforcement intensity indices shapes the projection framework across the analysis window. Segmentation dimensions modeled include material grade tier, application vertical, installation type, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating OSHA citation frequency trends, greenfield construction permits in Mexican industrial corridors, and Canadian carbon pricing incentive adoption rates.
Stress conditions across zinc commodity price bands, certified welder availability constraints, and EPA particulate threshold tightening scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and industrial capital expenditure patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Tipper Pads Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Automated Material Handling Systems Market