
 Slimline Aluminum Window System Market | 2026-2036
Slimline Aluminum Window System Market Size, Share, and Industry Trends Forecast 2026-2036
Slimline Aluminum Window System Market Insights
Multi-source procurement for extrusion and thermal break components is broadening as fabricators reduce dependency on integrated aluminum mills. SCHÜCO leverages its captive R&D network to control thermal barrier innovation across European projects. YKK AP anchors North American supply through vertically integrated extrusion and finishing operations. Reynaers Aluminium competes on specification depth, sustaining architect relationships through dedicated facade engineering support.
Slimline aluminum window systems integrate narrow-profile extruded aluminum frames with polyamide thermal breaks, achieving sightlines below 30 millimeters while maintaining structural load capacity and U-value performance. These systems serve high-end commercial and residential facades where maximum glazing area and minimal frame visibility are specified. Sliding configurations dominate volume in high-rise residential towers across Asia-Pacific, while fixed frames command premium positioning in museum and gallery projects where uninterrupted views are prioritized. Powder-coated finishes lead specification rates in coastal markets due to salt-spray resistance, though anodized treatments retain share in interior commercial applications where metallic aesthetics are specified.
F-Gas Regulation and REACH compliance in Europe mandate low-global-warming-potential thermal break materials and restrict certain surface treatment chemistries, directly shaping product development pipelines. The EU Green Deal's building performance standards and CE marking requirements for construction products create tiered market access where certified systems capture institutional and public-sector tenders. Stakeholders must monitor evolving national building codes and thermal performance thresholds as specification gatekeepers tighten compliance verification across project financing and insurance underwriting.
Market Dynamics
The F-Gas Regulation and EU Green Deal are compressing thermal performance thresholds across European construction, forcing fabricators to redesign polyamide thermal break chemistry and surface treatment processes ahead of enforcement deadlines.
Growth Catalysts
- EU Green Deal building mandates:Institutional tenders in Germany and the United Kingdom now require certified U-value performance, locking out uncertified suppliers and consolidating specification share among pre-qualified system houses.
- Luxury residential tower construction:Dubai and Singapore developers specify sub-30-millimeter sightlines for panoramic glazing, creating specification pull for structurally rated slimline frames in high-rise residential.
- Powder-coating chemistry advances:Salt-spray-resistant finishes now exceed 1,000-hour ASTM B117 exposure, opening coastal commercial markets previously closed to aluminum framing due to corrosion risk.
Market Restraints
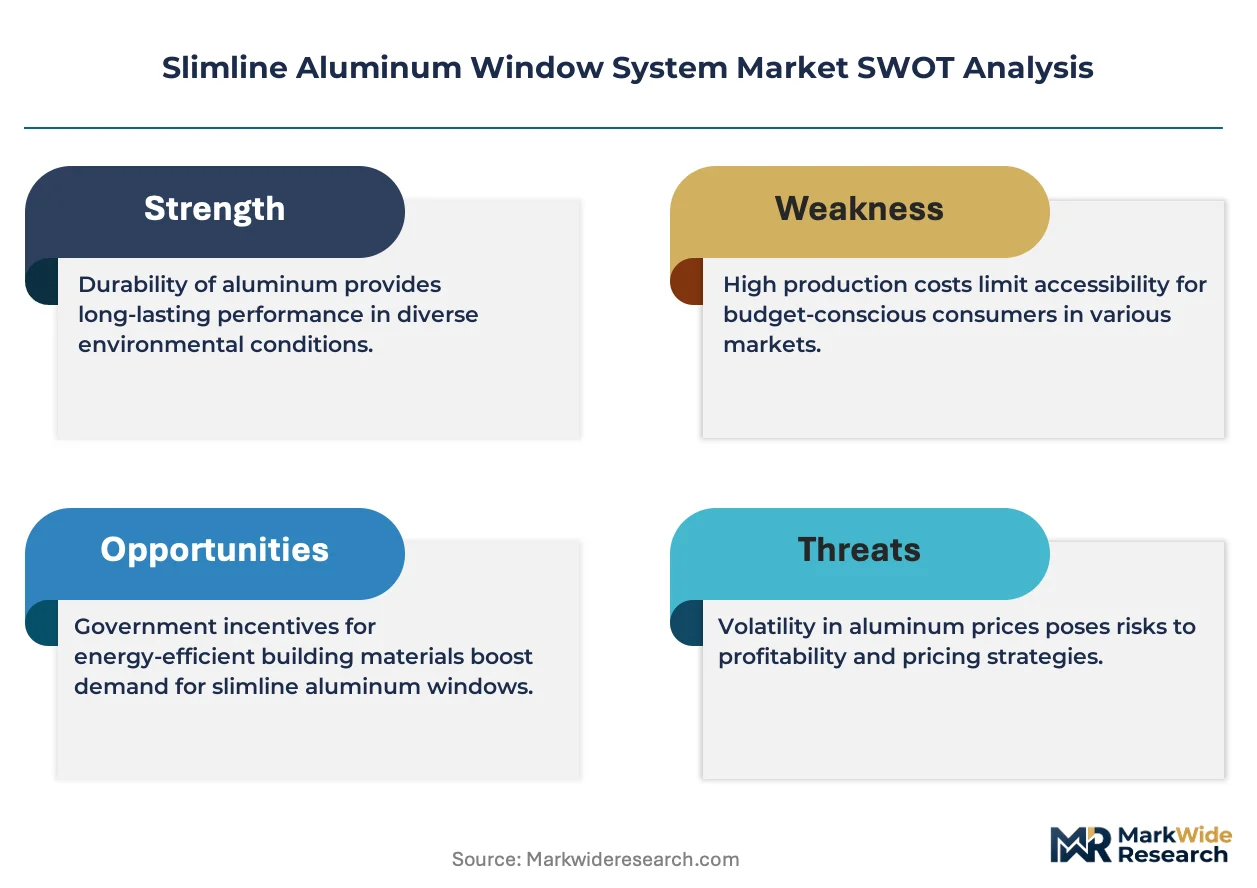
- Primary aluminum ingot volatility:London Metal Exchange pricing swings directly compress fabricator margins, with no viable material substitution for load-bearing extrusions.
- Polyamide thermal break supply concentration:European compounders control specialized glass-filled nylon formulations, creating single-source risk for high-performance frame assembly.
- REACH surface treatment restrictions:Hexavalent chromium conversion coatings face phase-out timelines, forcing capital-intensive process retooling for anodizing and pretreatment lines.
Strategic Opportunities
- United States commercial retrofit pipeline:Aging curtain wall stock in Chicago, New York, and Los Angeles creates replacement demand for thermally broken slimline systems meeting ASHRAE 90.1 standards.
- CE marking as competitive moat:Certified fabricators capture public-sector tenders across EU member states where compliance verification gates project financing.
- Smart facade integration:Embedded electrochromic glazing and sensor networks converge with slimline framing, enabling premium positioning in net-zero building certifications.
Industry Challenges
- Thermal modeling expertise scarcity:Finite element analysis for thermal bridge calculation requires specialized engineering talent that fabricators struggle to recruit at scale.
- Multi-certification timeline compression:Simultaneous CE marking, NFRC ratings, and local code approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slimline Aluminum Window System Market |
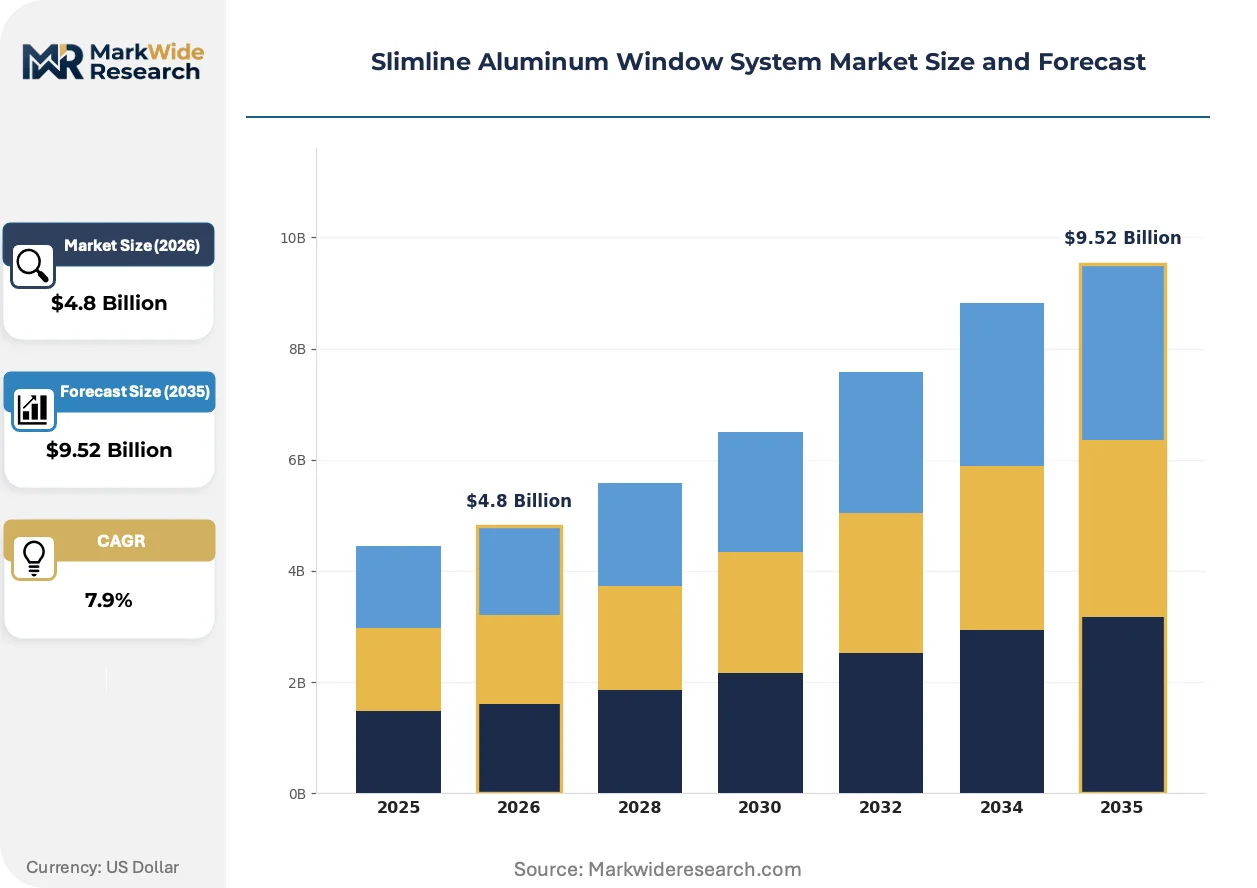
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casement, Sliding, Fixed, Awning, Hopper Material Finish: Anodized, Powder Coated, Mill Finish, Wood Grain, Painted Application: Commercial Buildings, High-Rise Structures, Institutional Facilities, Hospitality Establishments, Recreational Venues End User: Property Developers, Construction Contractors, Architectural Firms, Facility Managers, Renovation Specialists |
| Companies Covered | Solarlux GmbH, Panoramah!, heroal, Sky-Frame, Reynaers Aluminium, SCHÜCO, VITROCSA, Western Window Systems, YKK AP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slimline Aluminum Window System Market Trends and Innovations
Thermal barrier engineering and facade digitization are converging to redefine system performance boundaries, with chemistry and software displacing conventional mechanical differentiation.
Polyamide thermal break technology is consolidating specification authority among integrated system houses. High-performance polyamide strips with 25% glass fiber content now enable U-values below 1.0 W/m²K in 70-millimeter frame depths. Museum and gallery architects in Basel, Copenhagen, and Melbourne specify these systems for uninterrupted sightlines where structural thermal breaks were previously unavailable.
REACH and F-Gas Regulation in Europe mandate low-global-warming-potential blowing agents in thermal break manufacturing. ECHA restrictions on per- and polyfluoroalkyl substances further constrain surface treatment chemistries. German and Dutch fabricators are accelerating water-based anodizing and powder-coating line conversions to maintain market access ahead of 2025-2027 enforcement windows.
Architect specification behavior is fragmenting across performance-tier preferences. Institutional buyers in London and Frankfurt now unbundle facade engineering from window supply, engaging independent thermal consultants before system selection. This disintermediation compresses traditional fabricator-architect relationships and rewards specification depth over historical account presence.
Slimline Aluminum Window System Market Segmentation
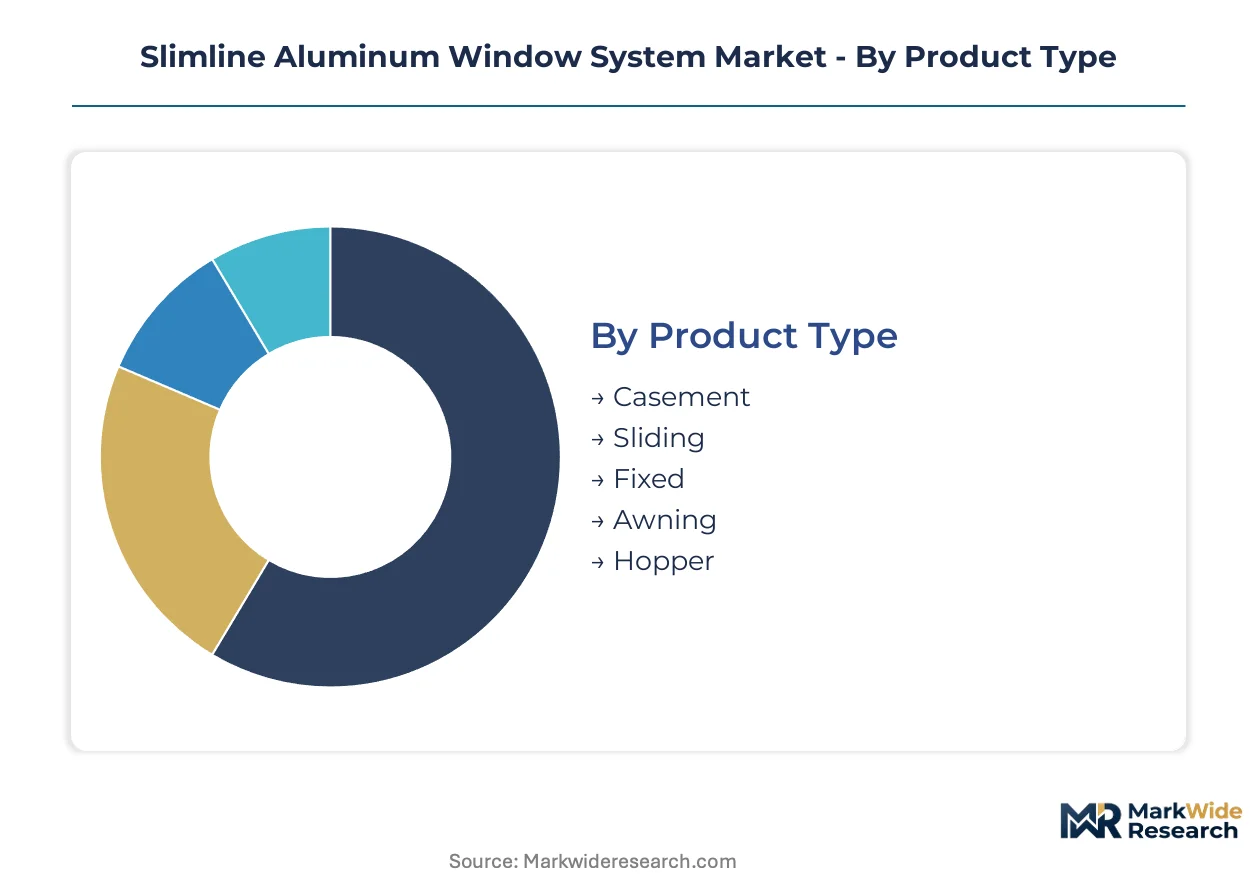
Slimline aluminum window systems fragment across product architecture, surface chemistry, project scale, and procurement channel. Specification behavior varies sharply by segment, with thermal performance thresholds and sightline requirements driving divergent sourcing strategies.
Product Type:
Sliding configurations dominate volume in Asia-Pacific residential towers, while fixed frames command premium positioning in cultural institutions where uninterrupted sightlines justify structural thermal break investment.
- Sliding:Horizontal track systems with multi-point locking hardware achieve sub-30-millimeter sightlines in 120-millimeter interlock depths. Dubai and Singapore luxury residential towers specify these for panoramic glazing where floor-to-ceiling transparency drives unit premiums.
- Fixed:Non-operable frames eliminate sash hardware for maximum glass area and thermal continuity. Museum and gallery projects in Basel, Copenhagen, and Melbourne prioritize these systems where structural thermal breaks enable U-values below 1.0 W/m²K in minimal frame depths.
- Casement:Side-hinged sashes with compression seals deliver superior air infiltration ratings for mid-rise commercial retrofits in Germany and the United Kingdom.
- Awning:Top-hinged projection windows shed precipitation while enabling secure ventilation in coastal hospitality projects across Florida and California.
- Hopper:Bottom-hinged in-swing configurations serve basement and mechanical room applications where egress requirements conflict with exterior space constraints.
Mature deployment sits with casement systems in European commercial retrofits. Newer deployment is concentrated in sliding configurations for Asia-Pacific high-rise residential.
Material Finish:
Powder coating has displaced anodizing in coastal markets due to salt-spray resistance advances, while metallic interior aesthetics sustain anodized share in commercial lobbies and retail facades.
- Powder Coated:Electrostatically applied thermoset polyester achieves 1,000-hour ASTM B117 salt-spray resistance, opening marine environment specifications previously closed to aluminum framing. German fabricators have accelerated water-based line conversions ahead of REACH enforcement windows.
- Anodized:Electrochemical oxide layers yield metallic aesthetics without organic coatings. Interior commercial applications in Frankfurt and London specify these for elevator lobbies and flagship retail where raw aluminum appearance carries brand equity.
- Mill Finish:Unprocessed extrusion surfaces serve concealed structural applications and temporary construction enclosures where appearance is non-critical.
- Wood Grain:Sublimation-printed polyester films simulate timber aesthetics for residential projects where homeowner association covenants restrict visible metal.
- Painted:Liquid coating systems retain niche positioning for custom color matching in heritage restoration and corporate identity programs.
Volume concentration rests with powder-coated finishes in coastal commercial markets. Premium positioning clusters with anodized treatments in interior architectural specifications.
Application:
Commercial building retrofits in the United States and Europe drive replacement demand, while new high-rise construction in Asia-Pacific pulls structurally rated systems for wind load resistance.
- Commercial Buildings:Office and retail retrofits across Chicago, New York, and Los Angeles create replacement demand for thermally broken systems meeting ASHRAE 90.1 standards. Curtain wall stock installed in the 1970s-1980s reaches end-of-service life.
- High-Rise Structures:Residential towers above 30 stories require engineered frames for interstory drift and wind load. Singapore and Dubai developers specify these for sub-30-millimeter sightlines where glazing ratios exceed 70% of facade area.
- Institutional Facilities:Schools, hospitals, and government buildings in Germany and the United Kingdom now require certified U-value performance for public-sector tender eligibility under EU Green Deal mandates.
- Hospitality Establishments:Hotel guest room windows balance acoustic performance with operability for guest comfort in urban infill projects.
- Recreational Venues:Sports facilities and convention centers demand large-format fixed glazing for daylight harvesting and spectator sightlines.
Replacement volume concentrates in commercial building retrofits. Steepest expansion trajectory appears in high-rise structures across Asia-Pacific luxury residential.
End User:
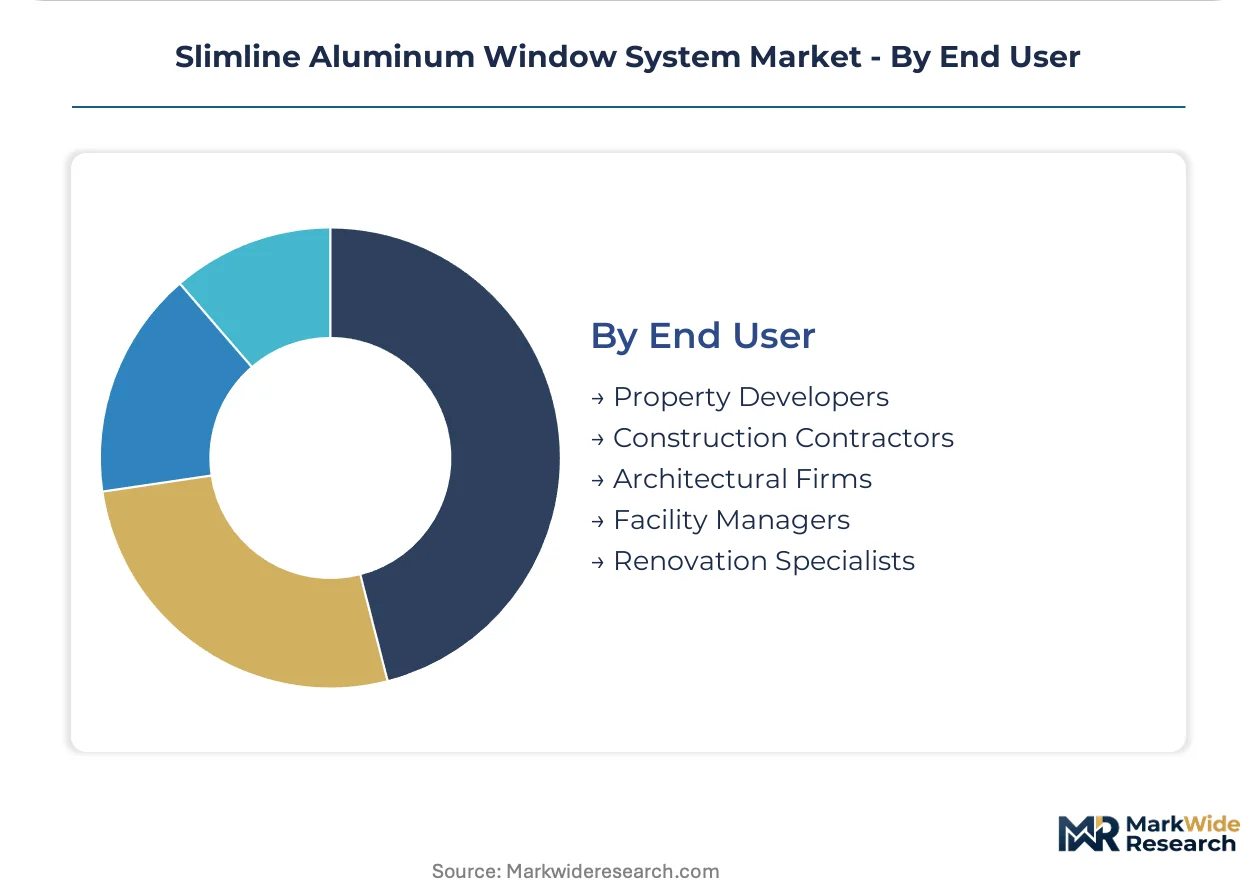
Procurement authority is fragmenting as institutional buyers unbundle facade engineering from window supply, engaging independent thermal consultants before system selection.
- Property Developers:Dubai and Singapore luxury residential developers specify sub-30-millimeter sightlines as unit differentiators, driving direct relationships with system houses for thermal performance guarantees.
- Architectural Firms:Basel, Copenhagen, and Melbourne museum architects now engage independent thermal consultants before system selection, compressing traditional fabricator relationships.
- Construction Contractors:German and UK contractors face compressed certification timelines for CE marking and local code approvals, extending procurement cycles.
- Facility Managers:US commercial portfolio operators prioritize ASHRAE 90.1-compliant replacements for energy cost reduction and green building certification maintenance.
- Renovation Specialists:Heritage restoration contractors in London and Paris navigate custom color matching and sightline compatibility with existing masonry openings.
Established procurement channels run through construction contractors in European commercial markets. Emerging influence concentrates with architectural firms specifying thermal performance ahead of fabricator engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary aluminum smelting capacity in Canada and Norway anchors raw material supply chains for European and North American fabricators, while bauxite processing clusters in Australia and Guinea feed Asian extrusion mills.
Germany
Commercial retrofit demand in Frankfurt and Berlin drives specification volume for thermally broken systems. The EU Green Deal and F-Gas Regulation enforce U-value thresholds that disqualify uncertified suppliers from public tenders. Fabrication clusters in North Rhine-Westphalia and Bavaria consolidate around captive R&D networks for thermal barrier chemistry.
United States
Aging curtain wall stock in Chicago, New York, and Los Angeles creates replacement demand exceeding new construction volume. ASHRAE 90.1 standards govern energy code compliance for commercial retrofits. Gulf Coast fabricators in Texas and Florida prioritize salt-spray-resistant powder coatings for coastal hospitality projects.
Singapore
Luxury residential towers above 40 stories specify sub-30-millimeter sightlines as unit differentiators in the Core Central Region. The Building and Construction Authority mandates Green Mark certification for new developments. Marina Bay and Orchard Road clusters attract direct relationships between developers and European system houses.
United Arab Emirates
Dubai's Downtown and Business Bay districts anchor high-rise residential construction with glazing ratios exceeding 70% of facade area. Dubai Municipality's Al Sa'fat green building regulations tighten thermal performance requirements. Local fabricators in Jebel Ali Free Zone assemble imported European profiles for wind-load-rated installations.
United Kingdom
London's commercial retrofit pipeline concentrates specification authority among institutional portfolio operators. Building Regulations Part L updates compress thermal performance thresholds for replacement windows. Manchester and Birmingham clusters develop regional fabrication capacity to reduce lead times from continental suppliers.
Slimline Aluminum Window System Market Competitive Landscape
Strategic partnerships dominate the current landscape as fabricators secure captive supply of polyamide thermal breaks and certified extrusion capacity. The vendor base stratifies across integrated system houses, regional fabricators, and specialist consultants. Three archetypes anchor positioning: vertically integrated multinationals controlling thermal barrier R&D, specification-focused houses sustaining architect relationships through facade engineering support, and regional assemblers competing on lead time and customization. Geographic expansion and technology licensing represent the dominant competitive moves, with European houses extending Middle Eastern and Asian project offices.
Among German-integrated system houses, SCHÜCO and heroal exemplify the R&D-controlled archetype through captive innovation networks. Reynaers Aluminium represents the specification-depth model, sustaining market position through dedicated technical support rather than manufacturing scale. Western Window Systems anchors North American positioning through vertically organized extrusion and finishing operations. These three patterns illustrate how competitive advantage concentrates differently across thermal barrier chemistry, architect engagement intensity, and supply chain configuration.
| Leading Market Players |
|---|
| Solarlux GmbH |
| Panoramah! |
| heroal |
| Sky-Frame |
| Reynaers Aluminium |
| SCHÜCO |
| VITROCSA |
| Western Window Systems |
| YKK AP |
| Others |
Pricing and Supply Chain Analysis
Primary aluminum ingot volatility cascades through extrusion pricing tiers, with London Metal Exchange swings compressing fabricator margins before reaching project-based quotes for high-rise developers in Dubai and Singapore. Thermal break compounders in Germany and the Netherlands anchor premium tier positioning through captive polyamide formulations, while regional assemblers in Jebel Ali compete on stripped-down specifications for cost-sensitive hospitality projects.
Pricing Analysis
Warranty-backed thermal performance guarantees separate premium system houses from unbundled regional fabricators, with SCHÜCO and Reynaers Aluminium including 10-year U-value certification in project pricing while Middle Eastern assemblers quote frame-only supply. Price differentiation rests on CE marking status and facade engineering support depth, with certified fabricators commanding 15-20% premiums for public-sector tender eligibility. Pricing pressure stems from REACH compliance capital requirements forcing process retooling costs onto mid-tier players. Property developers in Singapore exhibit lowest price sensitivity, prioritizing sightline performance and Green Mark certification over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from European institutional buyers now require qualified polyamide thermal break suppliers from both Germany and Belgium, reducing single-compounder dependency for high-performance frame assembly. Raw material flows draw from Norwegian and Canadian primary smelting, German glass-filled nylon compounding, and Chinese hardware machining. Supply chain risk concentrates in tariff exposure on Chinese aluminum extrusions entering North American markets. Distribution runs through system house direct sales for premium specifications and regional fabricator networks for retrofit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable fabricators, with REACH and F-Gas Regulation enforcement timelines forcing capital-constrained regional players toward acquisition or exit.
For Market Incumbents: Extend thermal barrier R&D partnerships into Middle Eastern project offices before European compounders establish direct Dubai relationships. Deepen captive extrusion capacity in Texas and Florida to capture coastal hospitality retrofit demand. CE marking investment creates defensive moats against uncertified Asian imports targeting German public tenders. For New Entrants and Emerging Players: The mid-market gap between premium European system houses and Gulf Coast commodity fabricators offers white-space entry through ASHRAE 90.1-compliant thermal break assembly. Target Chicago and Los Angeles commercial retrofit specifications where independent thermal consultant engagement now precedes fabricator selection. Lead with finite element analysis capabilities as a service-layer differentiator. For Investors and Strategic Acquirers: Accelerated water-based anodizing line conversions among German fabricators is the leading indicator that REACH enforcement is compressing margins for non-compliant players. Five-to-ten-year viability favors vertically integrated system houses with captive thermal barrier chemistry. Monitor polyamide compounder acquisition activity as the signal for consolidation phase entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Barrier Chemistry | Captive polyamide formulation control locks out specification competitors in EU Green Deal tenders. |
| Middle East Project Office Expansion | Dubai and Singapore developer direct relationships bypass architect-specification bottlenecks. |
| Water-Based Coating Line Conversion | REACH-compliant surface treatment maintains German and Dutch market access ahead of enforcement. |
| Independent Thermal Consulting Partnership | Pre-fabricator engagement with Basel and Copenhagen architects compresses traditional account relationships. |
| Smart Facade Sensor Integration | Embedded electrochromic glazing compatibility enables net-zero building certification premium positioning. |
Research Methodology
Independent corroboration across fabricator technical directors, facade engineering consultants, and institutional procurement managers underwrites the qualitative findings in this study. Primary fieldwork engaged thermal break compounders in North Rhine-Westphalia, aluminum extrusion plant managers in Bavaria, and specification architects in Singapore and Dubai. Secondary validation drew from Building and Construction Authority Green Mark databases, Dubai Municipality Al Sa'fat compliance filings, and German federal building energy code documentation. Bottom-up project pipeline analysis triangulates against top-down construction spending forecasts across the analysis window.
Comparable-period anchoring to historical retrofit cycles and high-rise residential completion rates structured the projection horizon. Segmentation modeling spanned product architecture, surface chemistry, application scale, and procurement channel authority. CAGRs were derived from installed base replacement velocity and new construction specification pull. Forecast inputs incorporated London Metal Exchange aluminum price band sensitivity and REACH enforcement timeline probability weighting.
Inputs from European fabricator associations and Middle Eastern developer disclosures were available through the study window; gaps in proprietary thermal break formulation cost structures introduce uncertainty bands around margin compression estimates. Deviation in F-Gas Regulation enforcement timing or aluminum tariff policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Spray Foam Market