
 Global Warehouse Racking Market | 2026-2036
Global Warehouse Racking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Warehouse Racking Market Intelligence
The proliferation of equipment-as-a-service and leasing models is rewriting the competitive landscape for warehouse racking suppliers. This capital-light approach allows smaller logistics operators to adopt advanced systems previously accessible only to large enterprises. SSI SCHAEFER leverages its broad portfolio to provide integrated, software-driven solutions for complex fulfillment operations. In contrast, Interlake Mecalux focuses on manufacturing scale and a wide distribution network to serve high-volume demand for standard pallet racks.
Warehouse racking comprises engineered steel structures designed to store materials in horizontal levels with multiple tiers. These systems are specified by their load-bearing capacity, often measured in pounds per beam level, and their seismic performance rating. The primary function is to maximize vertical storage density and streamline inventory management within a facility. While conventional pallet racks remain the dominant product type for general distribution centers, demand for mobile racks and mezzanine racks is accelerating, driven by the specialized needs of e-commerce fulfillment and cold storage facilities.
Structural integrity and worker safety standards, including OSHA regulations in the United States and the EN 15512 standard associated with CE marking in Europe, govern racking design. These frameworks mandate specific steel grades, load testing protocols, and installation requirements. The central strategic decision for end-users is balancing the upfront cost of high-density, automated systems against the long-term operational flexibility of more conventional racking configurations.
Market Dynamics
The integration of automated storage and retrieval systems (AS/RS) with traditional steel structures is the central force defining the market. This convergence dictates new design requirements for load capacity, structural tolerance, and software compatibility, pushing the industry beyond simple static storage solutions.
Growth Catalysts
- Third-Party Logistics (3PL) Expansion:The rapid growth of the 3PL sector, especially in emerging logistics hubs across Vietnam and Indonesia, creates sustained demand for highly efficient, dense, and scalable racking solutions to manage diverse client inventories.
- AS/RS Integration:The technological push to combine automated systems with racking structures drives investment in specialized, high-tolerance racks. These systems are essential for improving fulfillment speed and accuracy in e-commerce distribution centers.
- Cold Chain Requirements:Demand for specialized mobile and high-density racking is accelerating within the food and beverage industry to maximize cubic space utilization in temperature-controlled cold storage and freezer environments.
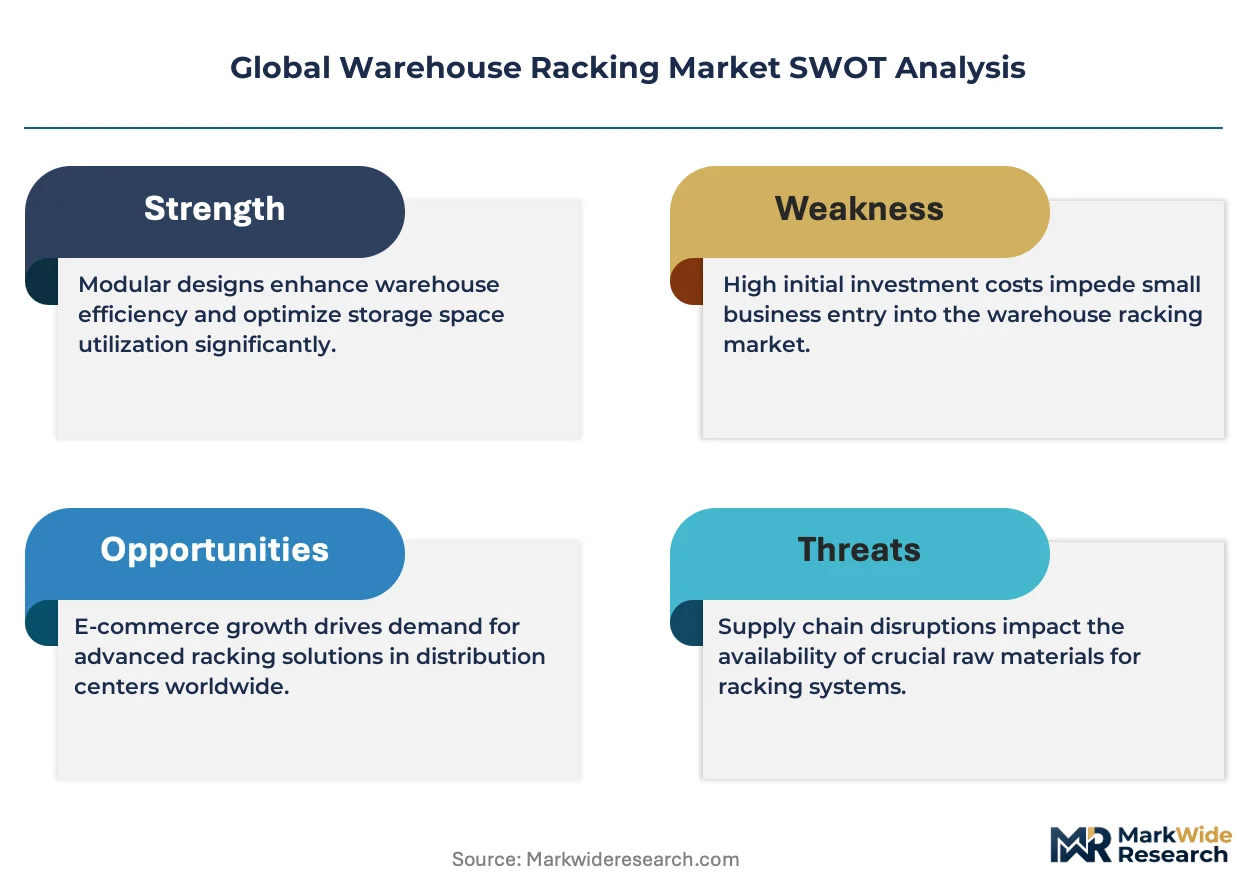
Market Restraints
- High Capital Expenditure:The significant upfront investment required for high-density and automated racking systems, including AS/RS, presents a major barrier for small and medium-sized enterprises (SMEs) without access to flexible financing.
- Steel Price Volatility:As the primary raw material, fluctuations in global steel prices directly impact manufacturing costs and project pricing. This volatility complicates long-term financial planning for both suppliers and end-users.
- Seismic Code Complexity:Designing and installing racking to comply with varying and stringent seismic performance requirements in regions like California or Japan adds significant engineering complexity, cost, and lead time to projects.
Strategic Opportunities
- Equipment-as-a-Service (EaaS) Models:The development of leasing and subscription-based service models provides a capital-light pathway for smaller operators to access advanced racking and automation, opening a new customer segment.
- Software and Controls Integration:There is a significant opportunity in offering integrated software layers, like Warehouse Execution Systems (WES), that optimize the performance of racking hardware, turning a static asset into an intelligent one.
- Retrofit and Modernization Projects:A large installed base of aging warehouses in North America and Europe creates a substantial market for retrofitting existing facilities with modern, denser, and safer racking systems to improve efficiency.
Industry Challenges
- Legacy System Integration:Operators face significant technical hurdles and operational disruption when attempting to integrate modern, automated racking systems with pre-existing warehouse management software (WMS) and facility layouts.
- Skilled Labor Scarcity:A shortage of certified installers and maintenance technicians capable of managing the complexities of automated and high-tolerance racking systems can lead to project delays and increased operational risks.
- Compliance and Certification Timelines:Navigating the certification process to meet safety standards like the European EN 15512 or OSHA regulations can be time-consuming, delaying project commissioning and revenue generation for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Warehouse Racking Market |
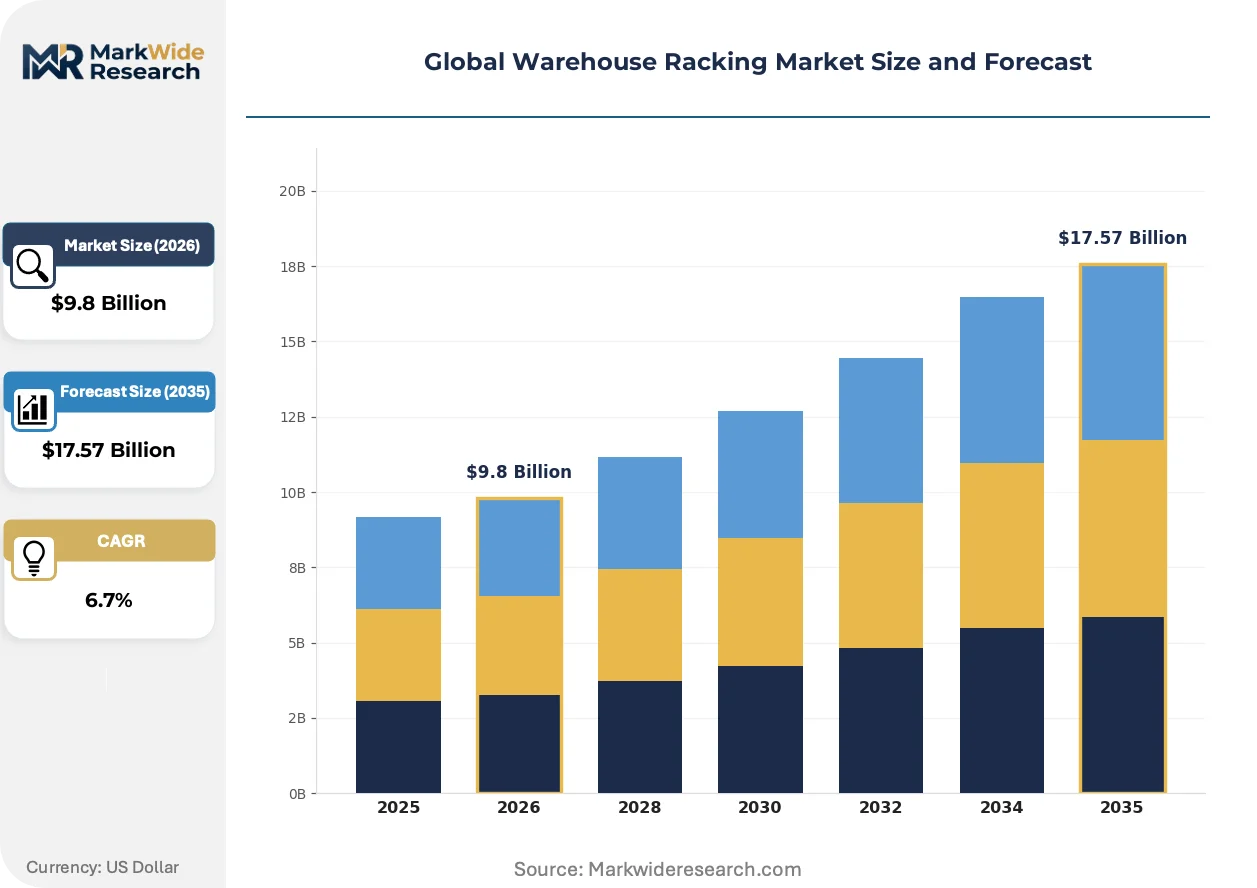
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pallet Racks, Cantilever Racks, Mezzanine Racks, Drive-In Racks, Mobile Racks Material: Steel, Aluminum, Wire Mesh, Plastic-Coated Steel, Galvanized Steel Application: Third-Party Logistics, Cold Storage Facilities, E-commerce Fulfillment, Automotive Parts Storage, Electronics Warehousing End User: Distribution Centers, Retail Warehouses, Manufacturing Plants, Food & Beverage Storage, Pharmaceutical Storage |
| Companies Covered | Steel King Industries, Frazier Industrial Company, Interlake Mecalux, Jiangsu EBIL Intelligent Storage Technology, Hannibal Industries, SSI SCHAEFER, UNARCO Material Handling, MEX Storage Systems, Ridg-U-Rak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Warehouse Racking Market Strategic Shifts & Innovations
The evolution from static storage assets to dynamic, intelligent infrastructure defines the market's trajectory. This shift is driven by the need for greater inventory velocity and accuracy, compelling a re-evaluation of how racking systems interact with software and automation.
Digital twin technology creates a virtual replica of the physical warehouse, including racking, for advanced simulation. Large-scale logistics operators and e-commerce companies are the primary adopters, using it for layout planning and workflow optimization. This technology is virtualizing the entire system design and commissioning process, allowing for stress testing and throughput analysis before any steel is installed.
Europe's EN 15512 standard, a requirement for CE marking, is setting a high bar for the design of steel static storage systems. The regulation mandates specific protocols for load testing, material specifications, and manufacturing quality control. Consequently, manufacturers targeting the European market must invest in higher-grade materials and more rigorous engineering verification, impacting global supply chain strategies.
A fundamental change in order profiles from bulk pallet shipments to individual item or case picks is reshaping system design. This trend, a direct result of e-commerce growth, is reducing the dominance of standard pallet racks in favor of carton flow racks, shelving, and mezzanine structures. The shift is most pronounced within fulfillment centers for apparel and consumer electronics across North America.
Global Warehouse Racking Market Segmentation
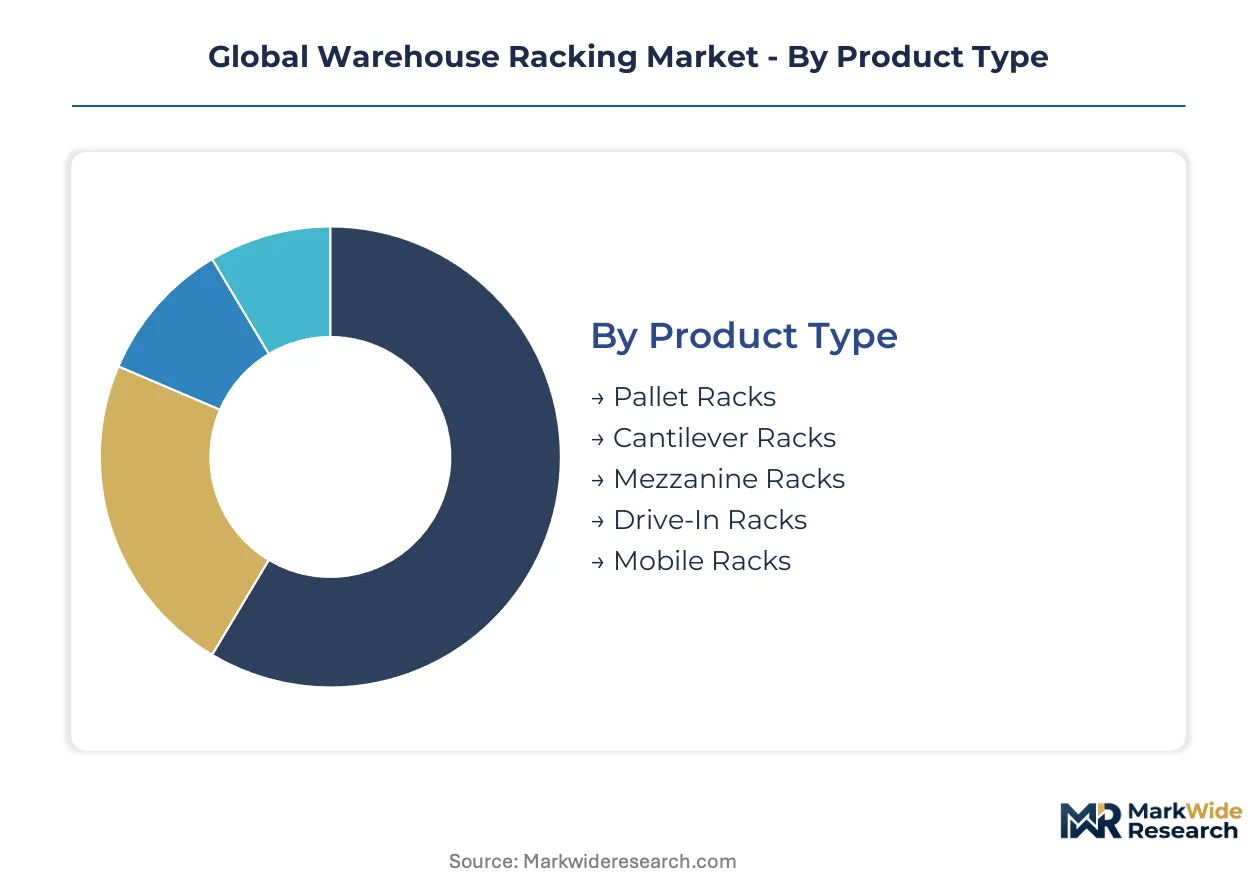
Segmentation within the global warehouse racking market is essential for understanding diverse operational demands and technological preferences. It highlights the specialized requirements across various storage environments and user types, influencing design, material selection, and automation integration for optimal efficiency.
Product Type:
The product type segment spans mature conventional systems and emerging specialized solutions.
- Pallet Racks:These engineered steel structures provide foundational storage for palletized goods in horizontal levels. Demand remains strong in general distribution centers worldwide, driven by their cost-effectiveness and versatility for bulk inventory management.
- Mobile Racks:These high-density systems are mounted on movable bases, allowing aisles to be opened only when needed. Demand is accelerating in cold storage facilities and e-commerce fulfillment centers, where maximizing cubic space utilization is critical for operational efficiency.
- Cantilever Racks:Designed for storing long, bulky items such as timber, pipes, or sheet metal.
- Mezzanine Racks:Multi-level storage platforms that create additional floor space within existing facilities.
- Drive-In Racks:Provide high-density storage for homogeneous products with first-in, last-out (FILO) inventory control.
Pallet Racks retain volume leadership; Mobile Racks hold the steepest expansion curve.
Material:
Material segmentation highlights the supply concentration of core structural elements.
- Steel:This is the primary construction material for most load-bearing racking structures due to its high strength-to-weight ratio and durability. Demand spans across all racking types and applications, forming the backbone of warehouse storage infrastructure globally.
- Galvanized Steel:Steel coated with a protective layer of zinc, offering enhanced corrosion resistance. Demand concentrates in harsh environments such as cold storage facilities and outdoor yards, protecting against moisture and temperature fluctuations.
- Aluminum:A lightweight alternative used in specialized applications where weight reduction or specific corrosion resistance is required.
- Wire Mesh:Primarily utilized for decking, safety barriers, and shelving, providing visibility and improved sprinkler penetration.
- Plastic-Coated Steel:Offers additional protection against scratches and impacts, often used in retail or specialized handling areas.
Steel remains the dominant material, while specialized variants like galvanized steel cater to specific environmental needs.
Application:
Application segments reflect the distinct operational requirements of various customer types.
- Third-Party Logistics:This sector requires highly flexible, scalable, and dense racking solutions to manage diverse client inventories efficiently. Demand is particularly high in emerging logistics hubs across Vietnam and Indonesia, driven by sustained growth in outsourced supply chain operations.
- E-commerce Fulfillment:This application demands high-speed, automated, and dense storage systems for rapid order processing and shipping. It drives investment in AS/RS-compatible racking and specialized carton flow and shelving solutions to meet fast delivery expectations.
- Cold Storage Facilities:Requires specialized mobile and drive-in racking to maximize cubic space utilization in temperature-controlled environments for perishable goods.
- Automotive Parts Storage:Often utilizes a mix of cantilever and selective racking to accommodate a wide range of part sizes and shapes.
- Electronics Warehousing:Focuses on secure, often anti-static, and organized storage solutions for sensitive components and finished products.
Third-Party Logistics and E-commerce Fulfillment are significant growth drivers for advanced racking solutions.
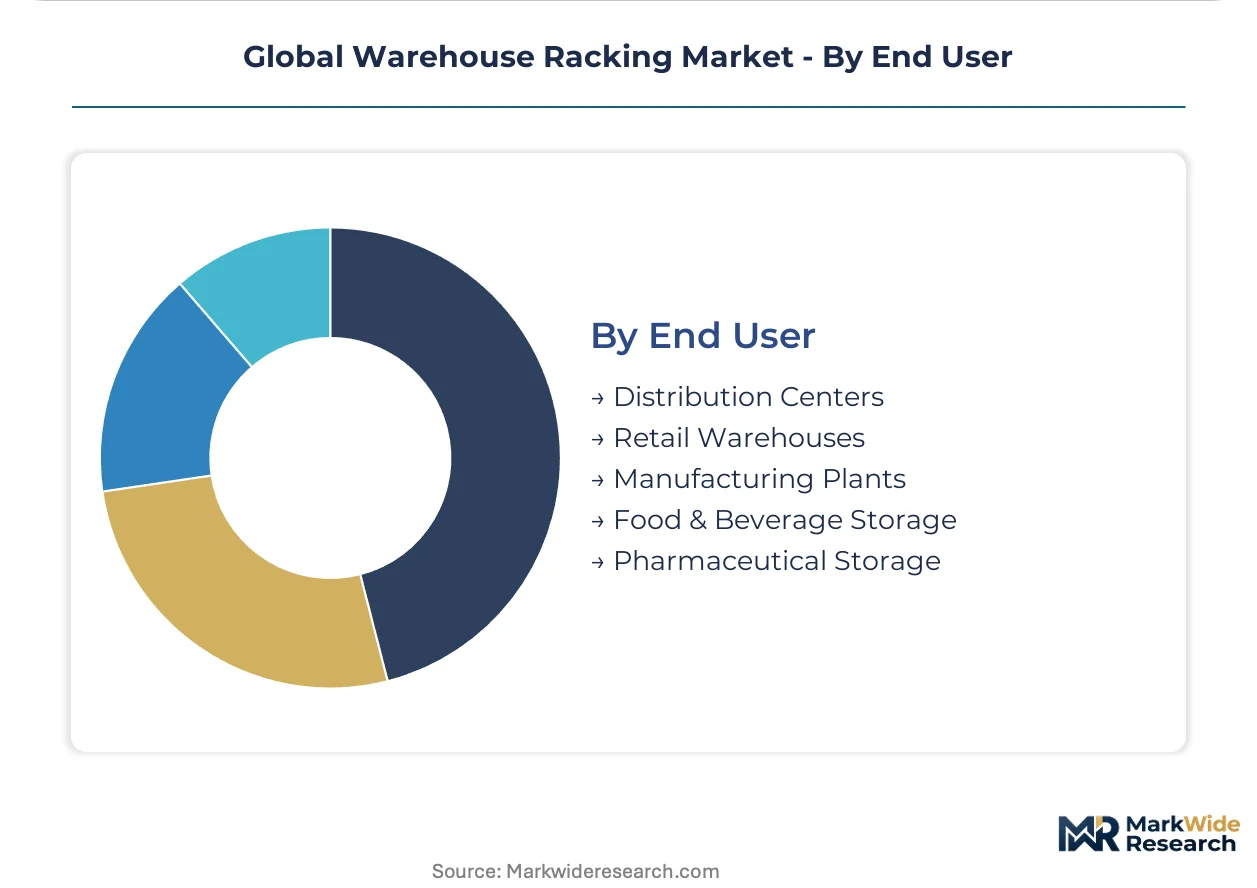
End User:
End-user categories differentiate demand based on operational scale and inventory volume.
- Distribution Centers:These large-scale facilities handle immense volumes of goods for onward shipment to retailers or end-consumers. They require robust, often highly automated, racking systems to manage complex inventory flows and optimize throughput.
- Food & Beverage Storage:This segment has specific requirements for hygiene, temperature control, and efficient inventory rotation (FIFO). It drives demand for specialized mobile, drive-in, and pallet flow racks suitable for cold and freezer environments.
- Retail Warehouses:Support store replenishment and direct-to-consumer operations, often requiring flexible and accessible racking for diverse product lines.
- Manufacturing Plants:Integrate racking solutions for raw materials, work-in-progress (WIP), and finished goods storage within production facilities.
- Pharmaceutical Storage:Requires stringent environmental control, security, and often specialized racking for sensitive and high-value products, adhering to regulatory standards.
Distribution Centers represent a primary demand source, while Food & Beverage Storage drives innovation in specialized systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for logistics infrastructure development across emerging economies are shaping regional demand for warehouse racking systems. These policies often include tax breaks and land subsidies, stimulating investment in modern storage facilities. The global market exhibits varied growth trajectories, influenced by localized e-commerce penetration and industrial expansion.
United States
Rapid expansion of e-commerce fulfillment centers drives demand for high-density and automated racking solutions in the United States. OSHA regulations mandate specific safety standards for racking installation and maintenance, ensuring worker protection. Major logistics hubs, such as those around Chicago and Los Angeles, see continuous investment in advanced warehouse automation technologies.
Germany
Compliance with the EN 15512 standard, a requirement for CE marking, elevates the design and material quality for warehouse racking in Germany. The country's strong manufacturing sector creates consistent demand for robust storage systems for raw materials and finished goods. Industrial regions like Bavaria and North Rhine-Westphalia are modernizing existing facilities with automated storage solutions.
Vietnam
The Vietnamese government's focus on improving trade infrastructure and attracting foreign direct investment fuels demand for scalable racking solutions. Growth in the third-party logistics sector, particularly in industrial zones near Ho Chi Minh City and Hanoi, creates sustained need for efficient storage. These emerging logistics hubs are developing rapidly to support regional supply chains.
Japan
Stringent seismic performance requirements for racking design and installation are a primary driver in Japan, ensuring structural integrity during natural disasters. High land costs necessitate maximizing vertical storage density, leading to demand for mobile and automated systems. Major urban centers like Tokyo and Osaka are adopting advanced AS/RS integrated racking to optimize space utilization.
India
The Goods and Services Tax (GST) implementation has streamlined logistics operations, encouraging investment in larger, more efficient distribution centers across India. Demand for warehouse racking is accelerating due to the expanding e-commerce market and organized retail sector. Industrial corridors, including those in Maharashtra and Gujarat, are witnessing significant development of modern warehousing infrastructure.
Global Warehouse Racking Market Key Industry Players
On the supply side, the industry is tiered, with global conglomerates offering comprehensive solutions alongside regional specialists. This structure supports both large-scale, complex projects and localized, standard requirements. Strategic archetypes include integrated solution providers, mass manufacturers, and niche specialists. Dominant competitive moves involve portfolio diversification and geographic expansion.
Integrated solution providers, such as SSI SCHAEFER, exemplify this approach by offering software-driven systems alongside hardware for complex fulfillment operations. Manufacturing scale and wide distribution networks are the focus for companies like Interlake Mecalux, serving high-volume demand for standard pallet racks. Jiangsu EBIL Intelligent Storage Technology Co., Ltd. represents the growing presence of Asia-based manufacturers specializing in smart storage and automation integration.
| Leading Market Players |
|---|
| Steel King Industries |
| Frazier Industrial Company |
| Interlake Mecalux |
| Jiangsu EBIL Intelligent Storage Technology |
| Hannibal Industries |
| SSI SCHAEFER |
| UNARCO Material Handling |
| MEX Storage Systems |
| Ridg-U-Rak |
| Others |
Cost & Logistics Intelligence
Underutilization in older warehouse facilities across North America drives down average racking prices for retrofit projects, forcing suppliers to differentiate on service and integration. This dynamic influences both manufacturing efficiency and distribution strategies.
Pricing Analysis
Certification level, specifically adherence to EN 15512 and OSHA standards, creates the primary spread in warehouse racking pricing. The dominant pricing model remains project-based, incorporating value-based components for automated and integrated solutions. Price differentiation stems from seismic performance ratings, customization for AS/RS integration, and comprehensive installation services. Pricing pressure stems from global steel price volatility, impacting manufacturing costs, making small and medium-sized enterprises more price-sensitive than large 3PLs investing in advanced automation.
Supply Chain Analysis
Steel price volatility represents a significant structural risk across the warehouse racking supply chain. Geographic supply concentration for core steel production centers on China, India, and Germany, influencing global material costs. Key raw material dependencies include various steel grades and specialized components for automated systems. Distribution runs through a mix of direct sales from large manufacturers and regional distributor networks, particularly for standard pallet racks, while AS/RS components introduce new single-source vulnerabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The warehouse racking market is experiencing a platform-economics inflection, driven by the imperative for seamless interoperability between physical racking structures and advanced Warehouse Execution Systems. This shift transforms static assets into intelligent, integrated logistics platforms.
For Market Incumbents: Entrench market position by deepening vertical integration into software and automation solutions, offering comprehensive, integrated systems beyond just steel structures. Diversify geographic reach into emerging logistics hubs like Vietnam and Indonesia to counter regional specialized manufacturers. Invest in advanced material science R&D to meet evolving seismic and load-bearing standards, mitigating the threat from highly specialized AS/RS providers.
For New Entrants and Emerging Players: Establish a beachhead in specialized segments such as cold storage or e-commerce fulfillment, where demand for mobile and carton flow racks is accelerating. Target small and medium-sized enterprises in emerging logistics hubs by offering capital-light Equipment-as-a-Service (EaaS) models. Focus on rapid deployment and modular, scalable solutions to gain market share against entrenched players.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the automated warehouse solutions segment, reflecting significant investment in technology and infrastructure. The market presents long-term viability as essential logistics infrastructure. Seek acquisition targets that are specialized automation integrators or software firms with strong Warehouse Execution System capabilities. The signal to watch is the sustained acceleration of AS/RS adoption rates in large distribution centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated WES Solutions | Enhances operational efficiency for 3PLs by optimizing inventory flow and order fulfillment. |
| Expand Galvanized Steel Production | Meets rising demand for corrosion-resistant racking in cold storage facilities and outdoor yards. |
| Offer Equipment-as-a-Service Models | Lowers capital expenditure barriers for small logistics operators adopting advanced systems. |
| Invest in Digital Twin Technology | Allows e-commerce companies to simulate warehouse layouts and stress-test throughput virtually. |
| Acquire Specialized Automation Integrator | Strengthens capabilities in AS/RS integration, crucial for high-speed e-commerce fulfillment centers. |
Research Approach
Initial hypotheses were tested against primary input from warehouse managers, logistics executives, racking manufacturers, and material handling consultants and refined through iterative discussions. This study integrated findings from over 50 in-depth interviews with extensive secondary validation from industry reports, company financial filings, and government trade data. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy across all market segments.
Demand-supply balance and market saturation dynamics formed the core of the analytical framework over the projection horizon. The modeling incorporated segmentation across product type, material, application, and end-user, alongside regional economic growth. Compound annual growth rates were derived from historical trends and projected technological adoption rates. Key forecast inputs included projected e-commerce penetration and 3PL expansion in emerging markets.
Stress conditions across steel price fluctuations and AS/RS investment levels were modeled; outcomes outside those bands fall beyond the analytical envelope. The forecasts reflect a defined set of market assumptions regarding logistics infrastructure development and trade policies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Low-Level Order Picker Pallet Truck Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Pipe Wrapping Machines Market