
 Facade Anchor Systems Market | 2026-2036
Facade Anchor Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Facade Anchor Systems Market Foresight
EN 1090-1 certification for structural steel and aluminum component fabrication is rotating the competitive landscape toward manufacturers with certified execution-class production lines. Halfen GmbH leverages its European fabrication network to sustain premium positioning in engineered cast-in channels. Hilti Aktiengesellschaft anchors its market presence through direct technical sales coverage and specification-grade adhesive anchor portfolios. Simpson Strong-Tie Company Inc. competes on building-code familiarity and contractor-channel density across North American jurisdictions.
Facade anchor systems comprise mechanical, adhesive, hybrid, and cast-in-place devices engineered to transfer dead loads, wind loads, and seismic forces from exterior cladding assemblies to primary structural frames, typically fabricated from stainless steel or carbon steel with specified yield strengths exceeding 50 ksi. Their primary purpose is to ensure structural integrity and life-safety performance of non-load-bearing curtain walls and rainscreen systems across commercial, institutional, and high-rise residential construction. Mechanical anchors retain the largest installed base due to decades of code precedent and installer familiarity, while adhesive anchors command margin premiums in post-installed rehabilitation and seismic-upgrade applications where substrate conditions vary. Stainless steel material specifications are gaining specification share in coastal and chemically exposed environments where carbon steel corrosion resistance falls short of warranty requirements.
ASTM E330 wind-load testing protocols and AAMA 501 structural performance standards govern product qualification in the United States, while EN 1990 and EN 1991 Eurocode bases shape European design methodology and national annex implementation. These frameworks elevate engineering liability and documentation burdens, which favors suppliers with in-house testing laboratories and PE-stamped submittal packages. Stakeholders must monitor evolving energy-code thermal bridging thresholds and seismic design category expansions that will redefine minimum performance tiers and recertification cycles for established product lines.
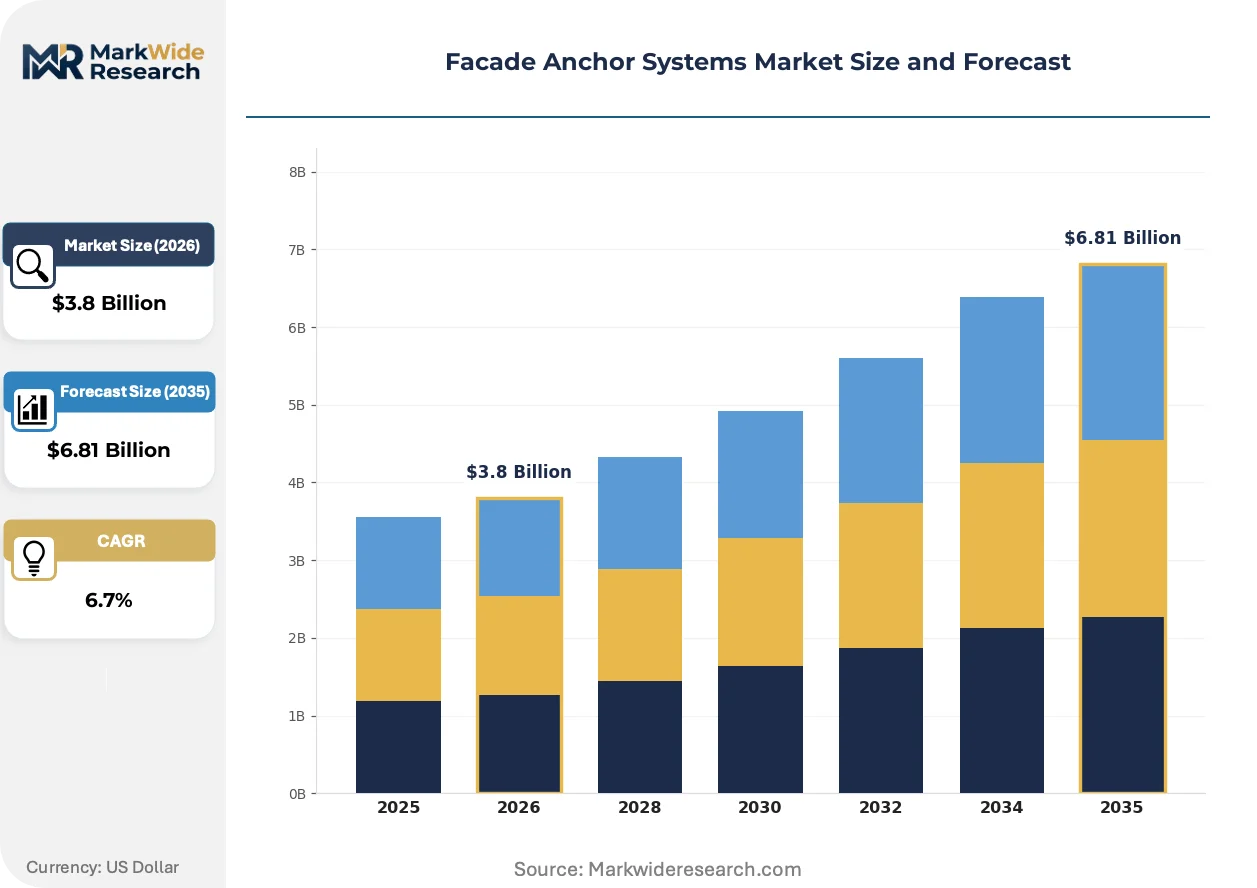
Market Dynamics
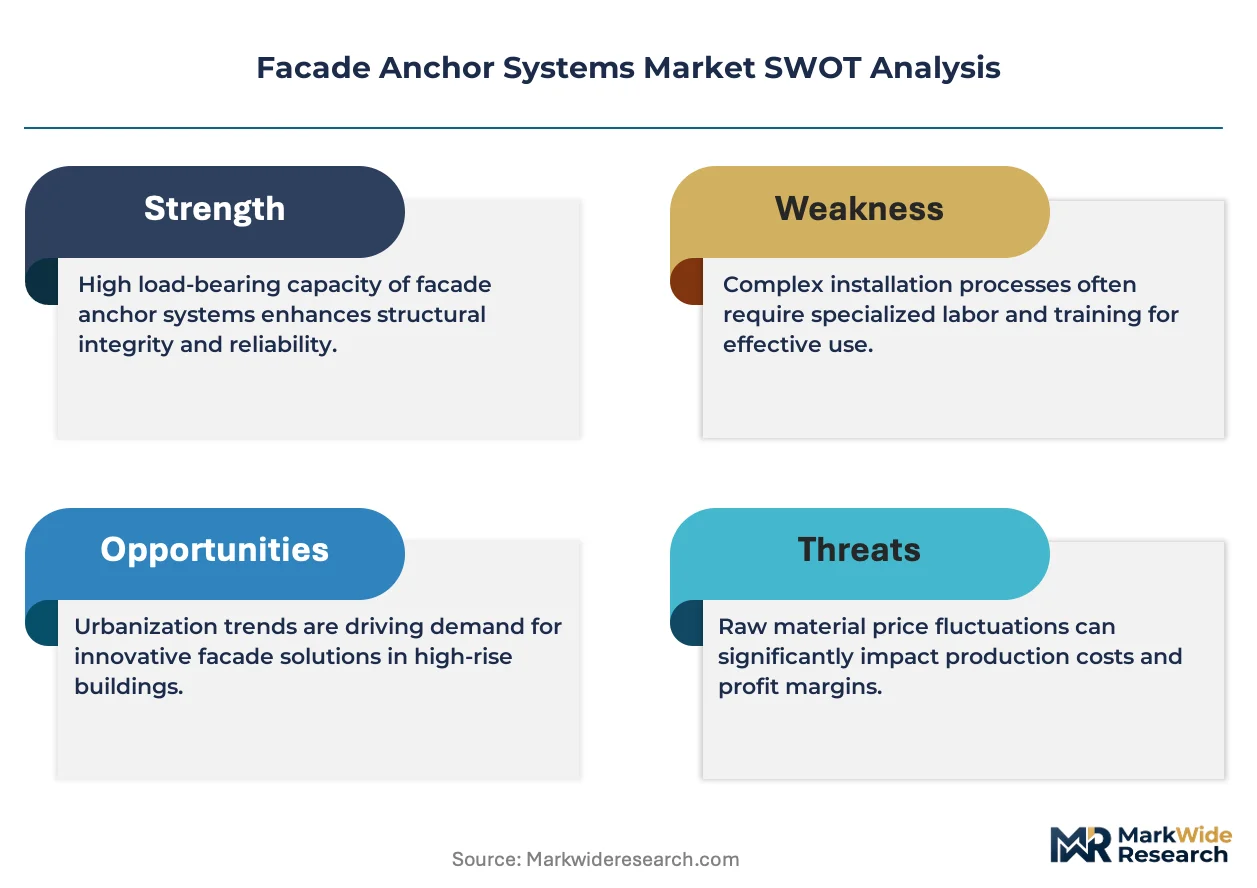
Curtain wall thermal performance mandates are compressing anchor specification cycles as jurisdictions tighten energy-code enforcement, forcing manufacturers to recertify product lines against evolving thermal bridging thresholds.
Growth Catalysts
- UAE Commercial High-Rise Construction:Developers in Dubai and Abu Dhabi are specifying engineered cast-in channels for glass-clad supertalls, creating specification pull for thermally broken assemblies.
- Germany's EPBD Implementation:Updated Energy Performance of Buildings Directive enforcement is mandating reduced thermal bridging coefficients, elevating demand for stainless steel thermally isolated anchor systems.
- Saudi Giga-Project Pipeline:Neom and Riyadh developments are sourcing structural anchorage at scale, concentrating procurement volume with certified execution-class fabricators.
Market Restraints
- Stainless Steel Input Volatility:Nickel and molybdenum price swings compress margin stability for corrosion-resistant anchor specifications.
- European Fabrication Concentration:EN 1090-1 certified production lines cluster in Germany, Austria, and Italy, creating supply bottleneck risk for non-European projects.
- Adhesive Anchor Curing Limitations:Substrate temperature and moisture constraints restrict post-installed rehabilitation applications in cold-climate construction windows.
Strategic Opportunities
- Seismic Upgrade Retrofit:Japan's METI building resilience programs are expanding structural reinforcement mandates for existing curtain wall stock.
- Digital Specification Platforms:BIM-integrated anchor selection tools are displacing traditional catalog-based submittal workflows among North American design firms.
- India Smart City Infrastructure:BIS adoption of Eurocode-aligned structural standards is opening specification pathways for certified European anchor systems.
Industry Challenges
- PE-Stamped Submittal Capacity:Engineering liability documentation requirements exceed in-house technical staffing at mid-tier distributors.
- Multi-Jurisdiction Code Harmonization:ASTM E330, AAMA 501, and EN 1990 testing protocol divergence forces redundant qualification expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facade Anchor Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Anchors, Adhesive Anchors, Hybrid Anchors, Cast-in-Place Anchors Material: Stainless Steel, Carbon Steel, Aluminum, Composite Materials Installation Method: Drilled, Welded, Bolt-On, Pre-Installed End User: Construction Contractors, Building Owners, Architects, Structural Engineers |
| Companies Covered | Simpson Strong-Tie Company Inc., Halfen GmbH, Heckmann Building Products Inc., Knight Wall Systems Inc., CRH plc, Hilti Aktiengesellschaft, EJOT Group, WIRE-BOND Inc., Fischer Group of Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facade Anchor Systems Market Shifts & Advancements
Thermal bridging engineering is displacing pure load-capacity as the primary anchor selection criterion, with specification authority migrating from structural engineers to envelope consultants.
Embedded fiber-optic strain sensing is miniaturizing within cast-in channel profiles, enabling real-time load monitoring for high-rise curtain wall systems. Building operators in Singapore and Hong Kong are piloting these smart anchors for predictive maintenance scheduling. The technology is compressing warranty negotiation timelines by providing empirical performance data.
REACH Annex XVII restrictions on chromium(VI) compounds are forcing conversion to trivalent passivation finishes for carbon steel anchors. German and French fabricators are absorbing retooling costs to maintain CE marking compliance. Coastal specification segments are accelerating stainless steel substitution where trivalent treatments fail salt-spray warranty thresholds.
Consolidated procurement by multinational facade contractors is compressing distributor margins and unbundling after-sales technical support. Tier-one envelope specialists in the United Arab Emirates and Saudi Arabia are demanding direct manufacturer relationships with bonded inventory commitments. This disintermediation is visible across Gulf Cooperation Council megaproject clusters where single-source accountability reduces interface risk.
Facade Anchor Systems Market Segmentation
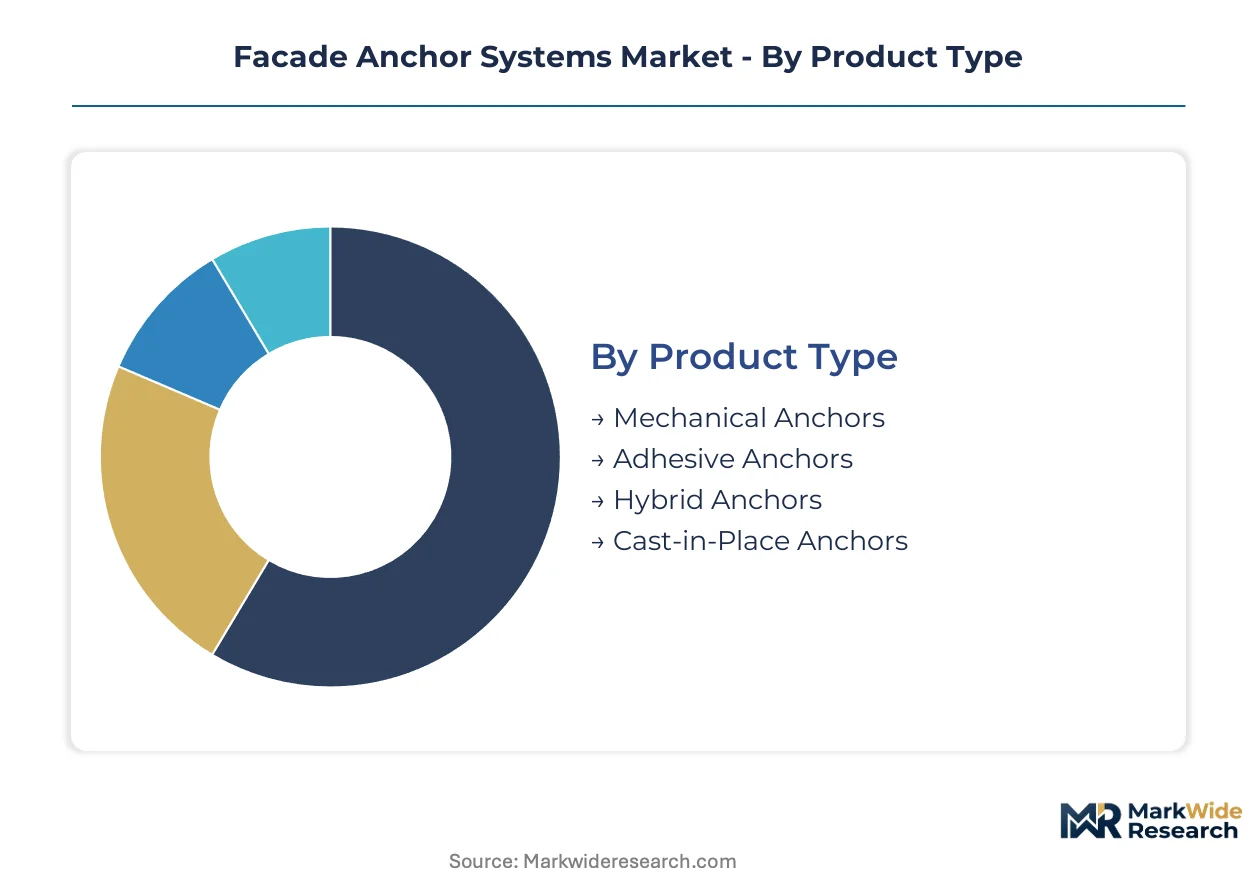
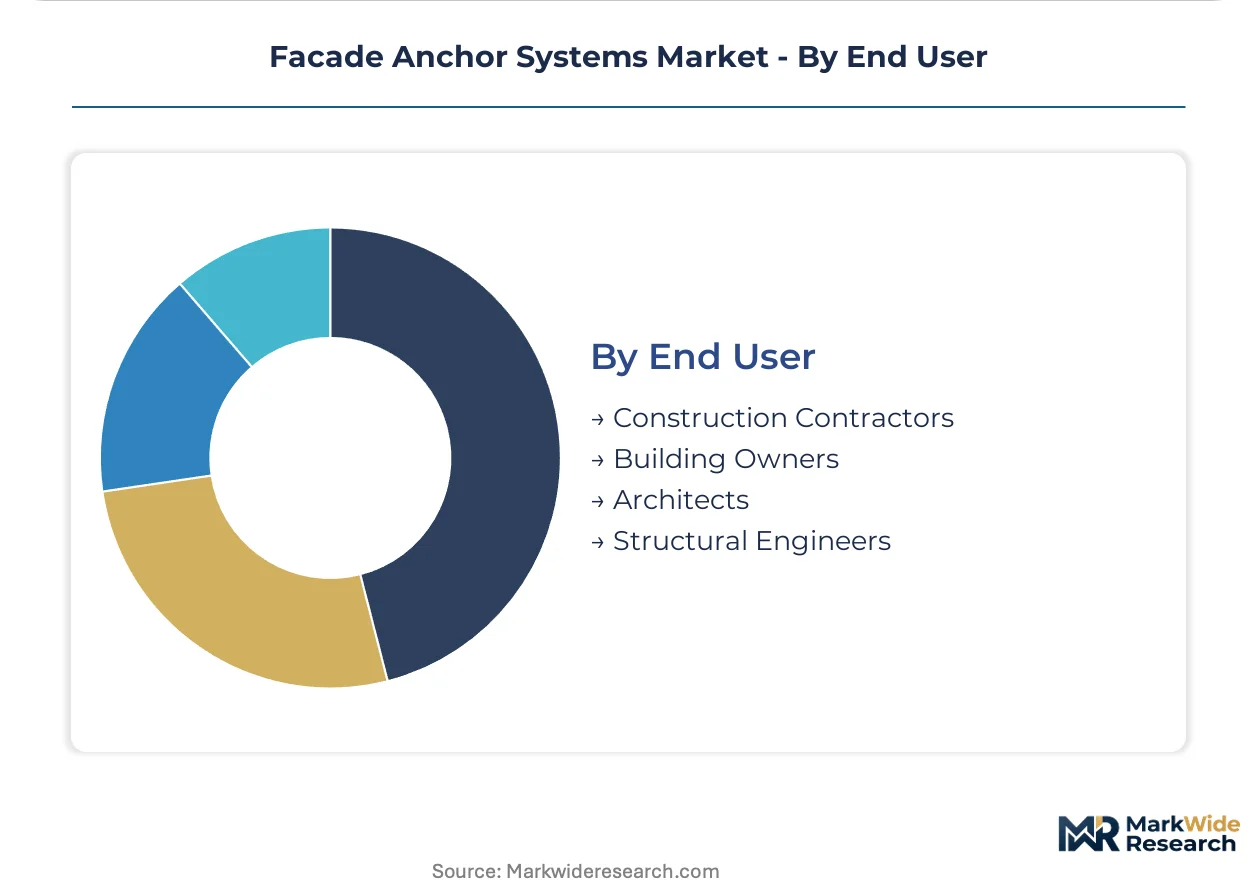
Facade anchor specification authority migrates across stakeholder groups depending on project phase and risk profile. Segmentation reveals where procurement decisions concentrate and which technical attributes command premium positioning.
Product Type:
Margin pools concentrate in thermally engineered and code-certified anchor families where specification inertia protects pricing power.
- Mechanical Anchors:Expansion and undercut devices fabricated from carbon or stainless steel deliver immediate load transfer without curing delays. Decades of International Building Code precedent and installer familiarity sustain specification dominance across North American commercial construction, though thermal bridging limitations pressure share in energy-code jurisdictions.
- Adhesive Anchors:Epoxy, vinylester, and hybrid polymer systems bond threaded rod or rebar into drilled substrates, enabling post-installed rehabilitation where mechanical expansion risks substrate fracture. Seismic-upgrade mandates in Japan's METI programs and California's Tier 1 cities are concentrating demand for qualified adhesive systems with ETAG 001 approval documentation.
- Hybrid Anchors:Combined mechanical-adhesive bonding mechanisms address variable substrate conditions in renovation applications.
- Cast-in-Place Anchors:Channels and plates embedded during concrete pour eliminate drilling and provide adjustable positioning for curtain wall erection.
The dominant share belongs to Mechanical Anchors, while Adhesive Anchors is closing the gap fastest.
Material:
Specification decisions increasingly pivot on corrosion resistance warranties and thermal conductivity coefficients rather than raw material cost.
- Stainless Steel:Austenitic grades 304 and 316 deliver salt-spray resistance exceeding 1,000 hours per ASTM B117, satisfying coastal and chemically exposed applications where carbon steel warranty claims accumulate. Dubai's supertall pipeline and Singapore's maritime towers are specifying duplex 2205 for chloride-heavy environments.
- Carbon Steel:Zinc-electroplated and hot-dip galvanized finishes serve budget-constrained commercial projects with moderate exposure, though REACH Annex XVII chromium(VI) restrictions force trivalent passivation conversion in European supply chains.
- Aluminum:Lightweight extrusions serve secondary framing connections where magnetic interference or weight reduction matters.
- Composite Materials:Glass-fiber-reinforced polymers address electromagnetic transparency requirements in specialized institutional buildings.
Stainless Steel commands the specification premium, yet Carbon Steel retains volume leadership in cost-sensitive segments.
Installation Method:
Project delivery schedules and substrate access constraints determine method selection, with pre-installed systems capturing early-design influence.
- Pre-Installed:Cast-in channels and plates embedded during concrete pour enable adjustable curtain wall attachment without field drilling, compressing high-rise erection schedules. Gulf Cooperation Council megaprojects are mandating pre-installed systems to reduce interface risk between concrete contractors and envelope specialists.
- Drilled:Post-installed mechanical and adhesive anchors dominate renovation and seismic-retrofit applications where existing structure access is the only option.
- Welded:Field-welded connections persist in heavy industrial cladding where dynamic loads exceed mechanical anchor ratings.
- Bolt-On:Through-bolted assemblies serve temporary or demountable facade systems in exhibition and retail fit-outs.
Pre-Installed methods are expanding share fastest in new construction, while Drilled retains retrofit dominance.
End User:
Procurement authority fragments across project phases, with early-stage influencers wielding disproportionate specification lock-in.
- Structural Engineers:PE-stamped submittal review and load-path verification grant decisive influence over anchor selection in jurisdictions with rigorous enforcement. German and Austrian engineers are elevating thermally broken anchor specifications under EPBD thermal bridging calculations.
- Architects:Envelope consultants increasingly specify anchor thermal performance criteria as energy modeling integrates facade attachment details. BIM-integrated specification tools are compressing traditional catalog-based selection workflows among North American design firms.
- Construction Contractors:Value engineering pressure and installer familiarity drive substitution toward proven mechanical systems during procurement phase.
- Building Owners:Warranty duration and predictive maintenance capabilities influence selection in institutional and owner-occupied developments.
Structural Engineers retain technical authority, though Architects are gaining ground fastest as envelope performance modeling advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's updated Energy Performance of Buildings Directive is tightening facade thermal bridging requirements, elevating specification standards for thermally broken anchor assemblies across multiple jurisdictions. Saudi Arabia's giga-project developments in Riyadh and Neom are sourcing engineered anchorage systems at scale, while the United Arab Emirates expands commercial high-rise construction with glass-clad supertalls demanding curtain wall anchorage.
United Arab Emirates
Developers in Dubai and Abu Dhabi are specifying engineered cast-in channels for glass-clad supertalls, creating specification pull for thermally broken assemblies. MOHAP building safety regulations mandate structural certification for high-rise envelope attachments. The Dubai Design District and Business Bay clusters concentrate procurement volume with facade contractors demanding direct manufacturer relationships.
Germany
EPBD enforcement is mandating reduced thermal bridging coefficients, elevating demand for stainless steel thermally isolated anchor systems. ECHA REACH Annex XVII restrictions on chromium(VI) compounds force trivalent passivation conversion in domestic fabrication. EN 1090-1 certified production lines cluster in Baden-Württemberg and Bavaria, creating supply concentration for European projects.
Saudi Arabia
Neom and Riyadh developments are sourcing structural anchorage at scale, concentrating procurement volume with certified execution-class fabricators. SFDA building material standards align with Eurocode structural performance requirements. The Riyadh Metro and Qiddiya entertainment clusters drive specification demand for pre-installed cast-in systems.
Japan
METI building resilience programs are expanding structural reinforcement mandates for existing curtain wall stock, accelerating seismic-upgrade retrofit demand. JIS standards govern anchor qualification for post-installed applications in high-seismic zones. Tokyo and Osaka commercial districts concentrate renovation activity where adhesive anchors address substrate access constraints.
United States
ASTM E330 wind-load testing protocols and AAMA 501 standards govern product qualification across commercial high-rise construction. California seismic design categories and energy-code thermal bridging thresholds elevate specification documentation burdens. New York and Chicago supertall clusters concentrate demand for PE-stamped submittal packages from suppliers with in-house testing laboratories.
Facade Anchor Systems Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with public companies leveraging capital markets for EN 1090-1 execution-class capacity expansion while family-owned fabricators defend regional specification relationships. The market structures around three archetypes: premium-tier European certified fabricators, mid-market regional distributors with technical sales coverage, and commodity carbon steel suppliers competing on contractor-channel density. Consolidation pressures concentrate among adhesive anchor specialists seeking ETAG 001 approval documentation, while vertical integration moves appear in cast-in channel production.
Among German-based fabricators, Halfen GmbH exemplifies the premium-tier certified archetype, while Hilti Aktiengesellschaft anchors the technical sales coverage model across multiple jurisdictions. Simpson Strong-Tie Company Inc. occupies a position within the North American code-familiarity segment, competing on building-code documentation and contractor-channel presence.
| Leading Market Players |
|---|
| Simpson Strong-Tie Company Inc. |
| Halfen GmbH |
| Heckmann Building Products Inc. |
| Knight Wall Systems Inc. |
| CRH plc |
| Hilti Aktiengesellschaft |
| EJOT Group |
| WIRE-BOND Inc. |
| Fischer Group of Companies |
| Others |
Supply & Pricing Matrix
EN 1090-1 execution-class certification gates both supply qualification and price differentiation simultaneously, concentrating fabrication capacity in Germany, Austria, and Italy while elevating specification premiums for certified anchor assemblies. Buyers without direct manufacturer relationships absorb distributor markups that compress margin pools for mid-tier procurement channels.
Pricing Analysis
Certification level (EN 1090-1 execution class) creates the primary spread between premium thermally broken assemblies and commodity mechanical anchors. Three-tier pricing structure across premium certified, standard commercial, and economy-grade carbon steel anchors reflects thermal performance coefficients and corrosion resistance warranties. Pricing pressure stems from consolidated procurement by Gulf Cooperation Council facade contractors demanding bonded inventory commitments and direct technical support. Construction contractors exhibit highest price sensitivity during value-engineering phases, while structural engineers prioritize load-capacity documentation over unit cost.
Supply Chain Analysis
Inventory lead times for cast-in channels stretch longest during Gulf megaproject construction windows, forcing just-in-sequence delivery commitments from certified fabricators. Production concentrates in Germany, Austria, and Italy for EN 1090-1 certified lines, with secondary carbon steel stamping in China and Turkey. Raw material draws from nickel and molybdenum suppliers for stainless steel grades, zinc for galvanizing finishes, and epoxy resin systems for adhesive formulations. Single-source vulnerability concentrates in European execution-class fabrication capacity for thermally broken specifications. Distribution runs through specification-grade distributors with PE-stamped submittal capabilities in North America and direct manufacturer relationships in the Middle East.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIM-integrated specification platforms are reconfiguring this market toward platform-economics dynamics, where anchor selection tools embedded in design software create interoperability lock-in and displace traditional catalog-based procurement workflows.
For Market Incumbents: Consolidate specification relationships with envelope consultants migrating authority from structural engineers to thermal-performance modelers. Deepen backward integration into stainless steel forging capacity to offset nickel price volatility and defend margin pools in coastal specification segments. Prioritize in-house testing laboratory accreditation to compress PE-stamped submittal turnaround times against mid-tier distributor competition. For New Entrants and Emerging Players: Lead with digital specification tools targeting North American design firms adopting BIM-integrated anchor selection workflows. Penetrate India's smart city infrastructure segment where BIS adoption of Eurocode-aligned standards opens specification pathways for certified European systems. Pursue seismic-upgrade retrofit opportunities in Japan's METI-mandated building resilience programs as the most accessible entry point for adhesive anchor qualification. For Investors and Strategic Acquirers: EPBD thermal bridging enforcement reshapes the acquisition landscape toward thermally engineered anchor specialists with existing EN 1090-1 certification and European fabrication footprints. Long-term viability centers on suppliers with specification authority migration capabilities and predictive maintenance technology integration. Target acquisition archetypes combine certified execution-class production with smart anchor fiber-optic sensing development. Watch for BIM platform partnership announcements as inflection indicators for specification workflow control.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Forging | Captures margin from nickel price volatility for 316-grade coastal specifications. |
| BIM Platform Partnership | Locks specification authority with envelope consultants adopting digital selection tools. |
| Smart Anchor Fiber-Optic Development | Enables predictive maintenance contracts with Singapore and Hong Kong building operators. |
| EN 1090-1 Execution-Class Capacity Expansion | Qualifies supply for Saudi giga-project procurement concentrating with certified fabricators. |
| Seismic Upgrade Retrofit Specialization | Captures METI-mandated demand in Tokyo and Osaka commercial districts. |
Research Methodology
Desk research of building code documentation, EN 1090-1 certification registries, and facade engineering standards preceded structured interviews with structural engineers, envelope consultants, facade contractors, and anchor system procurement managers. Primary fieldwork combined with secondary validation against ASTM E330 test reports, AAMA 501 structural performance databases, and Eurocode national annex implementations. Bottom-up project pipeline analysis across UAE, Saudi Arabia, Germany, and Japan triangulated with top-down construction spend forecasts.
Variance decomposition across product type, material specification, installation method, and end-user influence dimensions shaped the analytical framework. Modeled segmentation captured mechanical versus adhesive versus cast-in-place anchor families, stainless steel versus carbon steel versus aluminum material grades, pre-installed versus drilled versus welded methods, and structural engineer versus architect versus contractor procurement authority. CAGRs derived from project-level installation forecasts and specification mix shifts throughout the projection horizon. Industry-specific inputs incorporated thermal bridging coefficient thresholds, seismic design category expansions, and smart anchor pilot deployment timelines.
Underlying assumptions cover continued EPBD enforcement trajectory, sustained Gulf Cooperation Council megaproject commitment, and stable EN 1090-1 certification requirements, with deviation risk concentrated in nickel price volatility, adhesive anchor ETAG 001 approval delays, and BIM platform market consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Europe Construction Chemicals Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Soil Stabilization Market