
 Middle-East and Africa Gypsum Board Market | 2026-2036
Middle-East and Africa Gypsum Board Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Gypsum Board Market Foresight
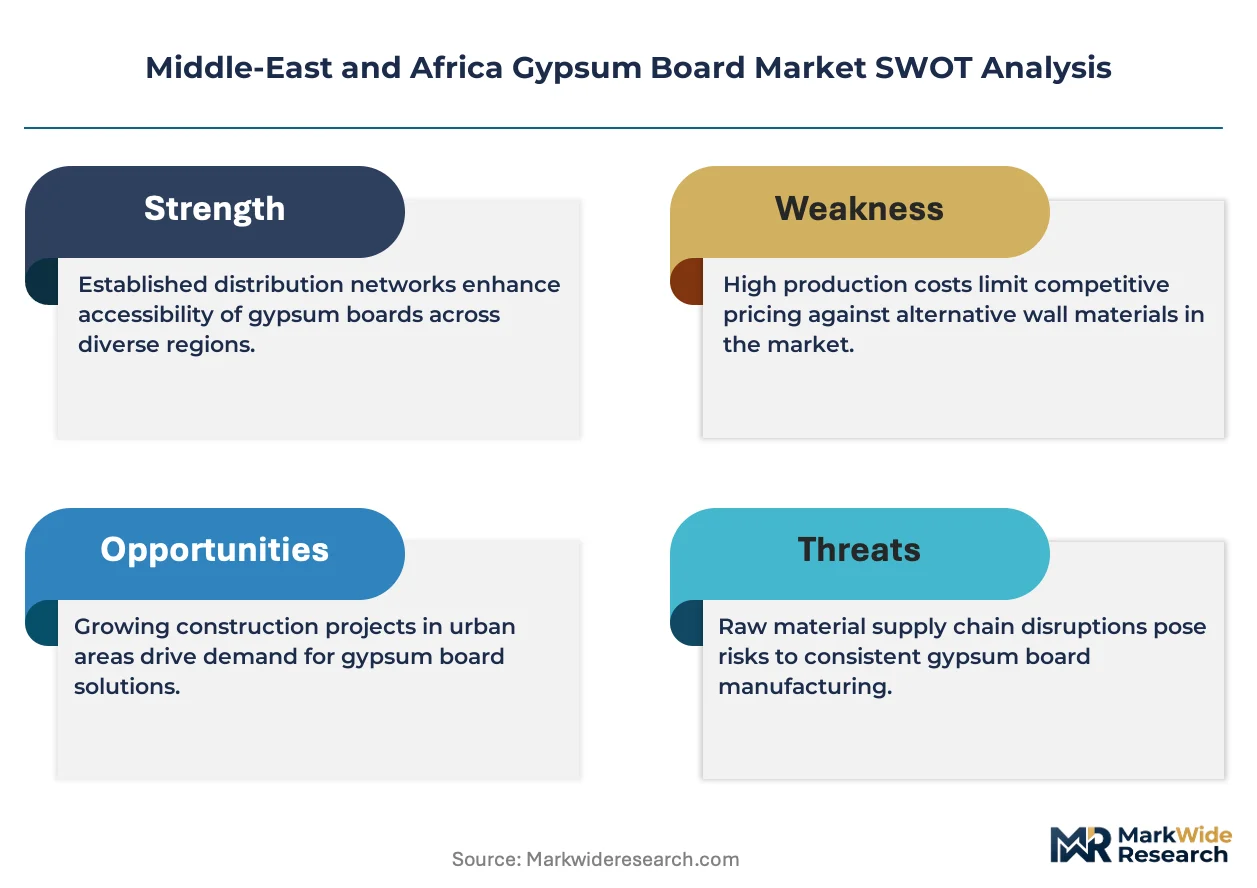
Saudi Arabia's industrial city expansions and dedicated gypsum manufacturing zones are reshaping regional supply geography. Saint-Gobain leverages its integrated plasterboard operations across North African production hubs to serve Mediterranean-facing projects. Knauf Group anchors its competitive stance through deep distribution partnerships with Saudi and Emirati construction conglomerates. Mada Gypsum Company specializes in high-volume standard board output tailored to Gulf residential contracting cycles.
Gypsum board consists of a calcium sulfate dihydrate core pressed between thick paper facings, manufactured through continuous calcination and slurry mixing processes to produce lightweight interior wall and ceiling panels. The product type dimension shows fire-resistant grades commanding premium positioning as Gulf building codes tighten safety mandates, while moisture-resistant variants gain share in coastal UAE and Qatar developments. Application segmentation reveals commercial construction as the dominant volume channel, though educational infrastructure across Egypt and Nigeria represents an emerging specification frontier. Thickness preferences cluster at 12mm for standard partition walls, with 15mm boards penetrating high-traffic commercial corridors.
Saudi Arabia's national building code authority and the UAE's civil defense fire safety directorate enforce gypsum board performance standards that determine product approval and project eligibility. Egypt's housing ministry specifications and South Africa's SABS quality marks create additional compliance layers for cross-border suppliers. Stakeholders must track regulatory divergence between Gulf standardization initiatives and sub-Saharan African adoption timelines to optimize certification investments and manufacturing footprint decisions.
Market Dynamics
Gulf Cooperation Council mega-commercial construction is compressing project timelines and forcing specification standardization across Saudi Arabia, the United Arab Emirates, and Qatar. This demand concentration is reshaping manufacturing footprints and certification requirements throughout the Middle-East and Africa region.
Growth Catalysts
- Saudi Green Building Codes:The national sustainability framework mandates fire-resistant and moisture-resistant gypsum board grades for public infrastructure, redirecting procurement toward certified products.
- UAE Hospitality Pipeline:Dubai and Abu Dhabi mixed-use developments sustain heavy drywall consumption for luxury hotel and residential towers, anchoring regional volume.
- Continuous Calcination Technology:Advanced manufacturing processes reduce core density while maintaining structural integrity, enabling lighter panels that cut logistics costs.
Market Restraints
- Natural Gypsum Import Dependence:High-purity gypsum rock concentrates in select North African and Middle Eastern deposits, exposing manufacturers to extraction quota volatility and transport cost spikes.
- Fire Safety Compliance Divergence:Saudi Arabia's national building code authority and the UAE's civil defense fire safety directorate maintain non-harmonized testing protocols, forcing duplicate certification investments.
- Cement Board Substitution:Fiber-cement panels penetrate exterior cladding and wet-area applications where gypsum board faces moisture-resistance limitations.
Strategic Opportunities
- Nigerian Educational Infrastructure:Federal and state-level school construction programs represent an emerging specification frontier with limited established supplier relationships.
- Egyptian Housing Ministry Specifications:New mass housing initiatives create volume opportunities for manufacturers achieving local quality mark approvals.
- Digital Specification Platforms:Construction procurement digitization enables direct architect-contractor-manufacturer connectivity, compressing traditional distribution layers.
Industry Challenges
- Fire-Resistance Certification Timelines:Gulf standardization initiatives and sub-Saharan African adoption timelines create asynchronous approval windows that complicate cross-border manufacturing decisions.
- Skilled Installation Labor Scarcity:Proper board handling, joint finishing, and moisture-protection detailing require trained crews that remain concentrated in established construction hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Gypsum Board Market |
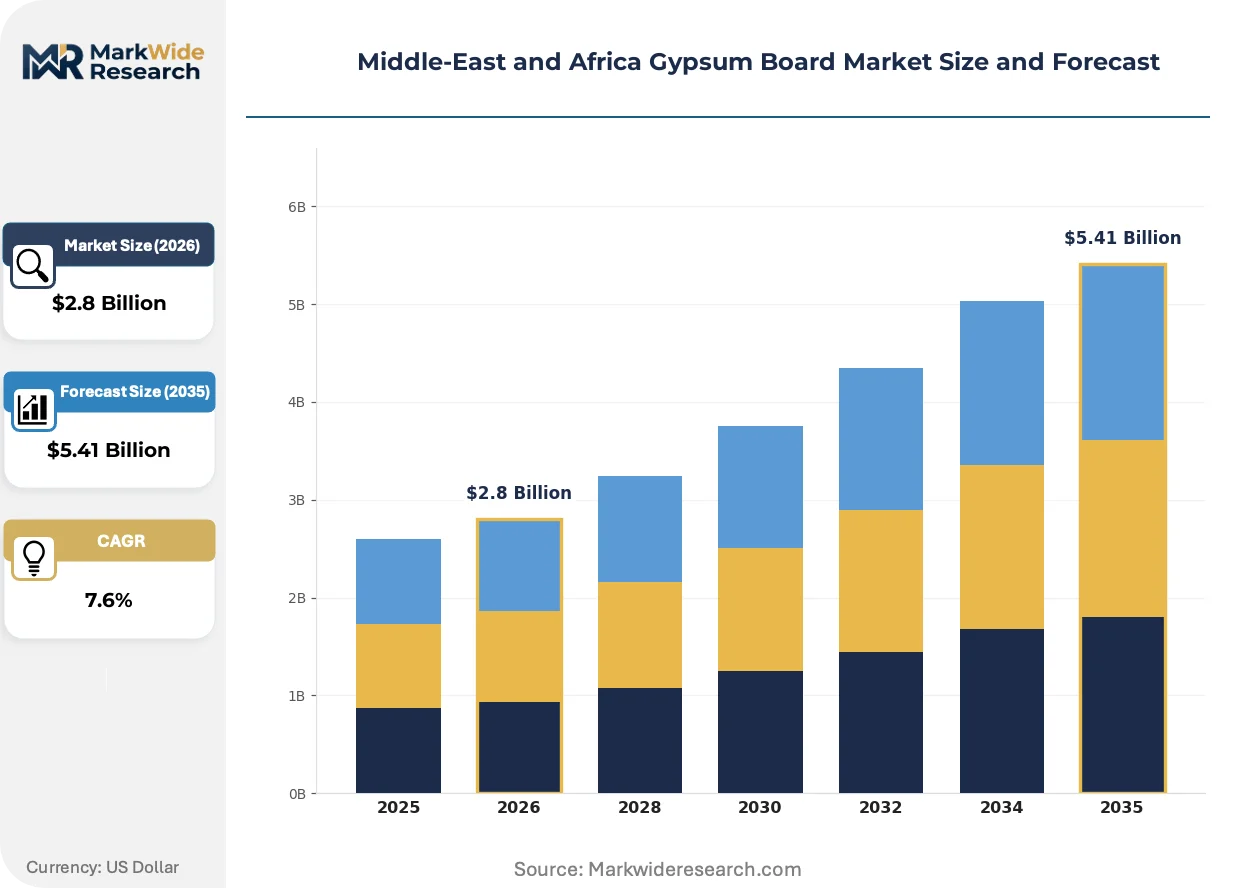
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Fire-Resistant, Moisture-Resistant, Soundproof Application: Residential, Commercial, Industrial, Educational Thickness: 9mm, 12mm, 15mm, 18mm End User: Contractors, Builders, Architects, Designers |
| Companies Covered | Saint-Gobain, Knauf Group, Mada Gypsum Company, National Gypsum Company, Gypsemna, KCC Corporation, AYHACO Gypsum Products Manufacturing, Global Gypsum Co Ltd, Etex Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Gypsum Board Market Shifts & Advancements
Manufacturing process digitization and specification platform evolution are compressing traditional supply chain layers across the Middle-East and Africa gypsum board market. These shifts are altering how products reach end-users and how performance is validated.
Building information modeling integration is digitizing gypsum board specification workflows. Saudi and Emirati architectural firms now embed fire-resistance and acoustic performance data directly into digital construction documents. This technology is digitizing the traditional manufacturer-representative specification channel, reducing reliance on field sales teams for technical compliance verification.
The UAE's civil defense fire safety directorate and Saudi Arabia's national building code authority are tightening performance testing mandates for commercial high-rises. These regulations force manufacturers to maintain dual certification portfolios. Fire-resistant grades face the steepest compliance burden, with testing cycle extensions affecting product launch timing.
Contractor procurement consolidation is reshaping distribution economics. Large Saudi and Emirati construction conglomerates now negotiate direct supply agreements with manufacturers, bypassing traditional wholesale channels. This concentration is most visible in Dubai's hospitality sector, where single-source procurement covers entire tower developments.
Middle-East and Africa Gypsum Board Market Segmentation
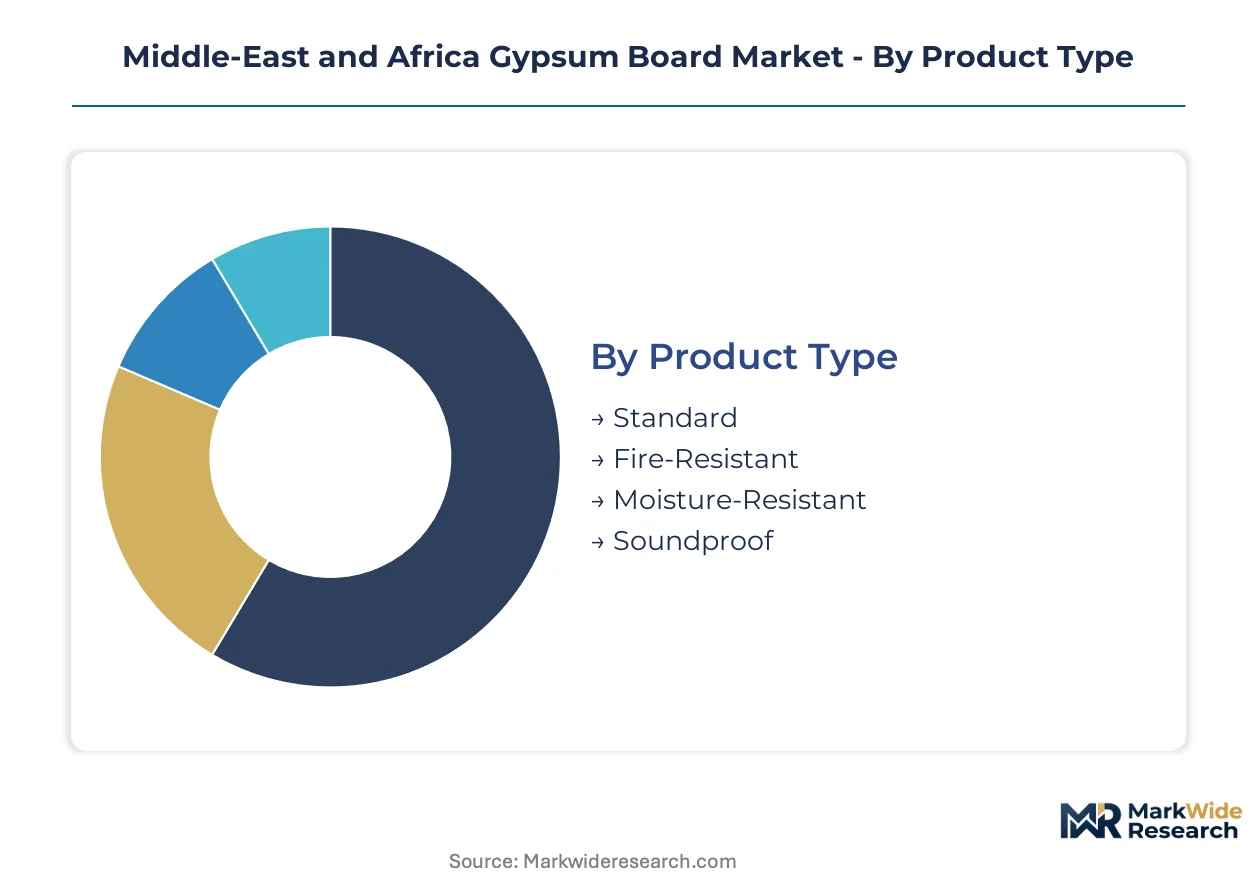
Gypsum board procurement cycles vary dramatically across specification tiers, with standard grades turning inventory monthly while certified fire-resistant products face extended approval timelines. Understanding these velocity differentials helps manufacturers align production scheduling with regional construction cadences.
Product Type:
Fire-resistant grades command the longest specification cycles due to mandatory testing protocols, while standard boards rotate through inventory fastest.
- Standard:Calcium sulfate dihydrate core with paper facings serves partition walls and ceiling systems. Saudi residential contracting cycles absorb the highest volumes, though margin compression limits supplier investment in capacity expansion.
- Fire-Resistant:Reinforced core with glass fiber additives achieves extended fire ratings required by Saudi national building codes and UAE civil defense mandates. Dubai commercial high-rises and Riyadh government complexes drive specification, with testing cycle extensions affecting product launch timing.
- Moisture-Resistant:Silicone-treated core and green-tinted paper facing resist humidity degradation in coastal UAE and Qatar developments.
- Soundproof:Denser core formulation with laminated construction attenuates acoustic transmission in hospitality and cinema applications.
Standard boards anchor the volume base while fire-resistant grades gain share at the steepest rate.
Application:
Commercial construction concentrates procurement volumes through consolidated contractor relationships, whereas educational infrastructure fragments across dispersed public tender processes.
- Commercial:Mixed-use towers, retail complexes, and office developments in Dubai and Abu Dhabi sustain heavy drywall consumption. Saudi giga-project pipelines compress timelines and force specification standardization across hospitality and retail segments.
- Residential:Villa compounds and apartment blocks across Riyadh and Jeddah generate recurring demand for standard-grade partition systems. Egyptian mass housing initiatives under the housing ministry specifications create emerging volume opportunities.
- Industrial:Manufacturing facilities and logistics warehouses require impact-resistant board grades with enhanced durability profiles.
- Educational:Federal and state-level school construction programs in Nigeria represent a specification frontier with limited established supplier relationships.
Commercial applications concentrate procurement scale while educational infrastructure expands most quickly as public investment accelerates.
Thickness:
Material cost tiers stratify by panel density, with thinner specifications dominating residential economics and thicker grades penetrating premium commercial corridors.
- 12mm:Mid-weight panels balance structural performance with handling efficiency for standard partition walls across Gulf residential developments.
- 15mm:Enhanced rigidity supports high-traffic commercial corridors in Dubai hospitality towers and Riyadh office complexes. Premium positioning reflects higher gypsum content and improved impact resistance.
- 9mm:Lightweight ceiling applications and curved architectural features reduce structural load and simplify installation.
- 18mm:Maximum density boards serve specialized fire-rated assemblies and acoustic isolation systems in cinema and performance venues.
12mm specifications dominate unit volumes while 15mm boards climb the fastest as commercial code requirements tighten.
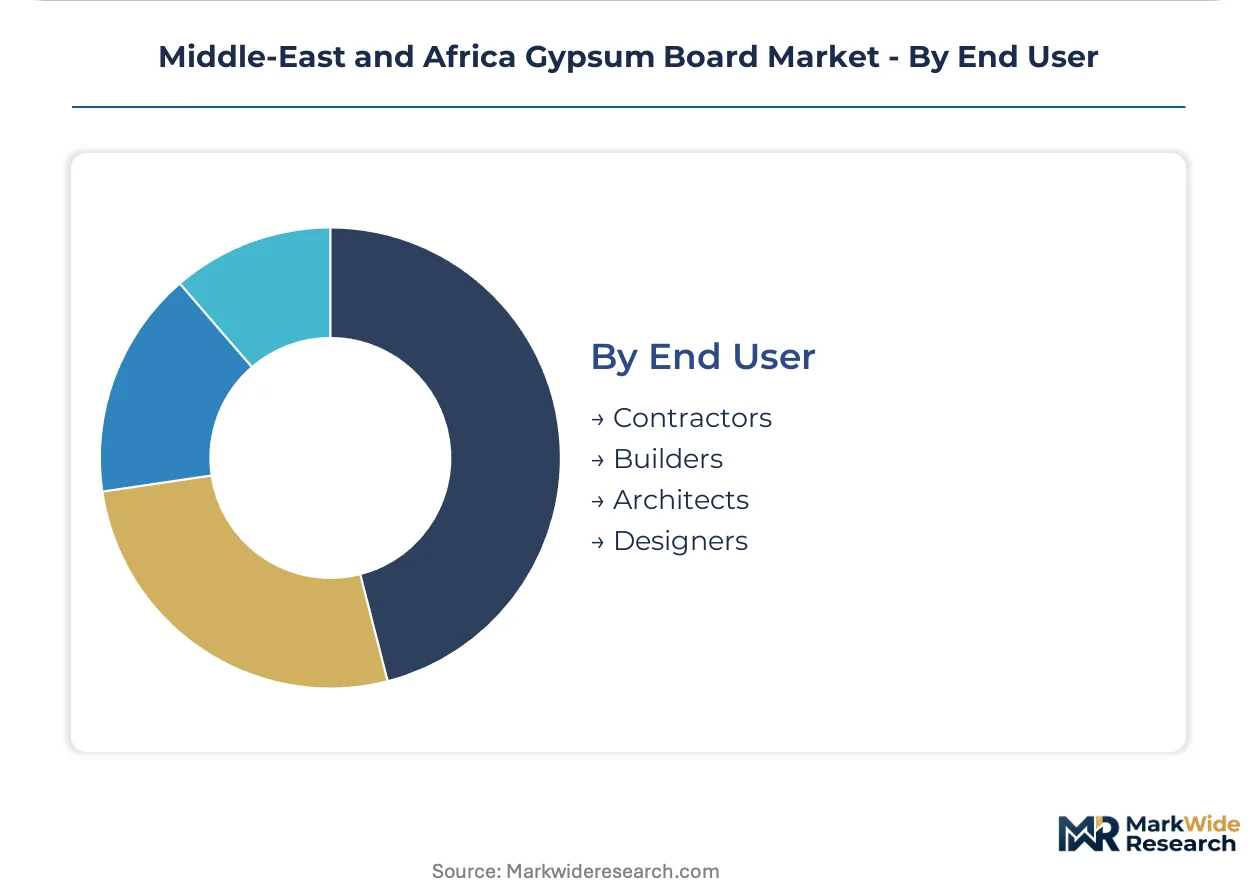
End User:
Procurement authority concentrates with contractors executing consolidated supply agreements, while architects influence specification through digital platform integration.
- Contractors:Large Saudi and Emirati construction conglomerates negotiate direct manufacturer agreements, bypassing wholesale channels. Single-source procurement covers entire Dubai tower developments.
- Builders:Mid-scale residential developers across Egypt and Nigeria source through regional distributors with limited technical specification involvement.
- Architects:Saudi and Emirati firms embed fire-resistance data directly into building information models, digitizing traditional manufacturer-representative channels.
- Designers:Interior specialists specify aesthetic finishes and acoustic treatments for luxury hospitality and retail environments.
Contractors control procurement scale while architects reshape specification workflows through technology integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity gypsum deposits concentrate in select North African and Middle Eastern extraction zones, exposing manufacturers to quota volatility and transport cost spikes. Manufacturing capacity clusters around Gulf industrial cities where mega-commercial construction compresses project timelines. Regulatory divergence between Gulf standardization initiatives and sub-Saharan African adoption timelines complicates cross-border certification investments.
Saudi Arabia
Giga-project pipelines and industrial city expansions drive specification volumes for fire-resistant and moisture-resistant grades. The national building code authority mandates certified products for public infrastructure under the national sustainability framework. Riyadh and Jeddah residential contracting cycles absorb substantial standard board volumes, while NEOM Northwest anchors next-generation construction demand.
United Arab Emirates
Dubai and Abu Dhabi mixed-use developments sustain heavy drywall consumption for luxury hospitality towers. The civil defense fire safety directorate enforces performance testing mandates for commercial high-rises that force dual certification portfolios. Dubai's hospitality sector concentrates procurement through single-source agreements covering entire tower developments.
Egypt
Mass housing initiatives under housing ministry specifications create emerging volume opportunities for manufacturers achieving local quality mark approvals. Educational infrastructure across Cairo and Alexandria represents a specification frontier with expanding public investment. The Nile Delta construction corridor concentrates mid-scale residential development demand.
Nigeria
Federal and state-level school construction programs represent an emerging specification frontier with limited established supplier relationships. Lagos and Abuja commercial development drives initial premium-grade penetration. The national building regulator maintains adoption timelines that lag Gulf standardization initiatives by several years.
South Africa
SABS quality marks create compliance layers for cross-border suppliers targeting industrial and commercial applications. Johannesburg and Cape Town construction hubs concentrate skilled installation labor that remains scarce elsewhere in sub-Saharan Africa. Mining sector facility maintenance generates recurring demand for impact-resistant board grades.
Middle-East and Africa Gypsum Board Market Competitive Landscape
Integrated multinationals and regional specialists split the market between premium certified grades and high-volume standard output. Manufacturing footprints align with gypsum deposit proximity and Gulf demand concentration. Three archetypes dominate: European-headquartered building materials conglomerates with integrated plasterboard operations, Gulf-based manufacturers serving residential contracting cycles, and Asian industrial groups leveraging continuous calcination technology. Competitive moves center on distribution partnerships with construction conglomerates and certification portfolio expansion across divergent national building codes.
Among European-headquartered building materials groups, Saint-Gobain and Knauf Group exemplify the integrated multinational archetype through established regional production hubs. Mada Gypsum Company occupies a position within the Gulf-based specialist tier, representing manufacturers tailored to local residential contracting cycles. These three anchors illustrate the geographic and strategic segmentation that defines competitive positioning across the Middle-East and Africa region.
| Leading Market Players |
|---|
| Saint-Gobain |
| Knauf Group |
| Mada Gypsum Company |
| National Gypsum Company |
| Gypsemna |
| KCC Corporation |
| AYHACO Gypsum Products Manufacturing |
| Global Gypsum Co Ltd |
| Etex Group |
| Others |
Supply & Pricing Matrix
High-purity gypsum rock deposits in Egypt and Oman anchor upstream material flows, concentrating margin capture with extractors while manufacturers downstream absorb transport cost volatility and quota allocation risk. This concentration pattern forces board producers to index pricing tiers against raw material security rather than finished product differentiation alone.
Pricing Analysis
Saudi Arabia's national building code authority dictates the pricing tier structure through mandatory fire-resistance certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates fire-resistant grades with glass fiber reinforcement from moisture-resistant silicone-treated cores and basic calcium sulfate dihydrate panels. Cost compression in standard-grade residential boards is intensifying because Egyptian and Nigerian contractors prioritize volume procurement over performance specifications. Large Saudi and Emirati construction conglomerates exhibit the lowest price sensitivity due to consolidated single-source agreements, while mid-scale residential developers across North Africa remain most responsive to per-unit cost fluctuations.
Supply Chain Analysis
Export control regimes on continuous calcination technology limit manufacturing equipment flows to Gulf industrial zones, constraining capacity expansion outside established production hubs. Geographic supply concentration centers on Saudi Arabia's Jubail and Yanbu industrial cities, the UAE's Jebel Ali corridor, and Egypt's Suez Canal development zone. Raw material dependencies rest on high-purity natural gypsum rock, recycled gypsum from flue gas desulfurization, and silicone additives for moisture-resistant grades. Single-source vulnerability runs through Egyptian quarry extraction quotas controlled by state mining authorities. Distribution runs through direct manufacturer-contractor agreements in Dubai and Riyadh, with regional distributors serving fragmented Nigerian and Egyptian residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa gypsum board market sits in early-cycle expansion as Nigerian educational infrastructure and Egyptian mass housing programs accelerate specification penetration beyond traditional Gulf commercial corridors.
For Market Incumbents: Build certification moats around dual-approval portfolios spanning Saudi Arabia's national building code authority and the UAE's civil defense fire safety directorate to neutralize cement board substitution threats in wet-area applications. Deepen backward integration into captive gypsum quarry access in Egypt and Oman to secure raw material cost stability against extraction quota volatility. Expand fire-resistance testing laboratory partnerships to compress product launch timelines as commercial high-rise mandates tighten. For New Entrants and Emerging Players: Mid-market commercial buildings in Lagos and Abuja represent the most penetrable entry point given limited established supplier relationships and lagging national building regulator adoption timelines behind Gulf standardization. Federal and state-level school construction programs across Nigeria offer tender fragmentation that favors agile regional manufacturers over integrated multinationals with rigid contract terms. Pursue architect-direct digital specification platform partnerships to bypass entrenched wholesale distribution layers concentrated in established construction hubs. For Investors and Strategic Acquirers: Capital is best deployed toward Gulf-based specialists with existing Saudi and Emirati construction conglomerate relationships and untapped capacity for fire-resistant grade conversion. Long-term viability hinges on certification portfolio breadth across divergent national building codes rather than single-market dominance. Monitor Egyptian housing ministry specification updates as the inflection signal for North African volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Egyptian and Omani gypsum deposit control secures raw material cost stability against state extraction quota volatility. |
| Fire-Resistance Certification Expansion | Dual-approval portfolios across Saudi and UAE regulators unlock specification eligibility for commercial high-rise projects. |
| Digital Specification Platform Partnerships | Building information modeling integration with Riyadh and Dubai architectural firms compresses traditional manufacturer-representative channels. |
| Regional Distribution Network Buildout | Lagos and Abuja logistics hubs penetrate Nigerian educational infrastructure with limited incumbent supplier relationships. |
| Moisture-Resistant Grade Capacity Addition | Silicone-treated core production serves coastal UAE and Qatar developments facing humidity degradation risks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, national building code authority filings, construction project development databases, and industrial mineral extraction records. Primary interviews engaged plant managers at integrated plasterboard operations, procurement leads at Saudi and Emirati construction conglomerates, distribution channel partners across North Africa, and technical R&D directors specializing in continuous calcination processes. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Gulf industrial cities and North African production zones.
Forecast inputs include product type segmentation by fire-resistant, moisture-resistant, standard, and soundproof grades; application channels spanning commercial, residential, industrial, and educational infrastructure; thickness specifications at 9mm, 12mm, 15mm, and 18mm tiers; and end-user procurement authority concentration among contractors, builders, architects, and designers. CAGRs derive from construction pipeline velocity analysis across Saudi giga-projects, UAE hospitality developments, Egyptian mass housing initiatives, and Nigerian federal school programs. Industry-specific inputs incorporate regulatory adoption timeline divergence between Gulf standardization initiatives and sub-Saharan African implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in construction credit availability, currency volatility affecting import-dependent raw material flows, or state budget reallocations impacting public infrastructure procurement would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline stability and quarry extraction quota continuity. Material shifts in Saudi national sustainability framework enforcement intensity or UAE civil defense mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
North America Prefab Wood Building Market