
 Slab Repair Products Market | 2026-2036
Slab Repair Products Market Size, Share, and Industry Trends Forecast 2026-2036
Slab Repair Products Market Analytics
Project finance for municipal infrastructure rehabilitation is tilting competitive dynamics toward suppliers with asset-light distribution networks. Sika AG leverages its direct-sales footprint to secure specification-driven contracts with state DOTs. Mapei S.p.A. anchors its position through specialized polymer formulations for high-traffic commercial slabs. GCP Applied Technologies competes on technology leadership in cementitious repair systems for industrial floor restoration.
Slab repair products encompass engineered materials—epoxy resins, polyurethane foams, polymer-modified cementitious compounds, and specialized mortars—formulated to restore structural integrity, seal cracks, and level deteriorated concrete surfaces in buildings, bridges, and pavements. These systems typically achieve compressive strengths exceeding 4,000 psi and bond to substrates through mechanical interlock and chemical adhesion, enabling load-bearing rehabilitation without full replacement. Cementitious formulations dominate volume due to lower material cost and compatibility with existing concrete chemistry, while polyurethane injection systems command premium positioning for dynamic crack sealing in infrastructure subjected to thermal cycling. Epoxy-based products sustain above-average margins in industrial applications where chemical resistance and rapid return-to-service justify higher expenditure.
ASTM International governs material performance through C881 specifications for epoxy-resin bonding systems, while ACI 318 and ACI 562 frame structural repair design and evaluation protocols for concrete buildings. The US Federal Highway Administration and state DOTs enforce National Bridge Inspection Standards that mandate timely remediation of deficient structural elements, directly generating procurement cycles for repair materials. Stakeholders must monitor evolving EPA VOC emissions limits for coating and sealant categories, as regulatory compression on solvent content is forcing reformulation investments across polyurethane and epoxy product lines.
Market Dynamics
Deferred maintenance backlogs across US transportation infrastructure are compressing procurement cycles and forcing state DOTs toward specification-driven material selection rather than lowest-bid procurement.
Growth Catalysts
- National Bridge Inspection Standards:Federal mandates for timely remediation of deficient structural elements generate recurring procurement cycles for epoxy injection systems and cementitious repair compounds.
- Polyurethane foam injection:Dynamic crack-sealing capabilities in thermal-cycling environments are displacing rigid repair methods for bridge decks and airport pavements.
- Industrial floor restoration:Chemical-resistant epoxy formulations sustain premium positioning as manufacturing facilities prioritize rapid return-to-service over material cost minimization.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and polyurethane precursor costs fluctuate with crude oil derivatives, compressing margins for formulated product manufacturers.
- VOC emissions limits:EPA regulatory compression on solvent content in coating categories is forcing costly reformulation investments across solventborne epoxy and polyurethane product lines.
- Cementitious compatibility requirements:Polymer-modified cementitious systems face technical limitations in high-moisture substrate applications where epoxy bonding systems achieve superior adhesion.
Strategic Opportunities
- Smart infrastructure monitoring:Convergence of wireless sensor networks with self-healing concrete formulations creates white space for repair products with embedded diagnostic capabilities.
- Asset-light distribution networks:Direct-to-contractor digital platforms are opening channel innovation opportunities bypassing traditional distributor markups in municipal procurement.
- State DOT specification capture:Tightening FHWA performance standards create regulatory tailwinds for suppliers with documented compressive strength and bond durability testing.
Industry Challenges
- ACI 562 certification timelines:Evaluation and repair protocol compliance requires extended third-party testing cycles that delay product commercialization.
- Application technician skill gaps:Proper installation of high-performance injection systems demands trained crews, creating execution bottlenecks in fragmented contractor markets.
- Legacy substrate variability:Deteriorated concrete surface conditions vary unpredictably, complicating standardized repair system performance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slab Repair Products Market |
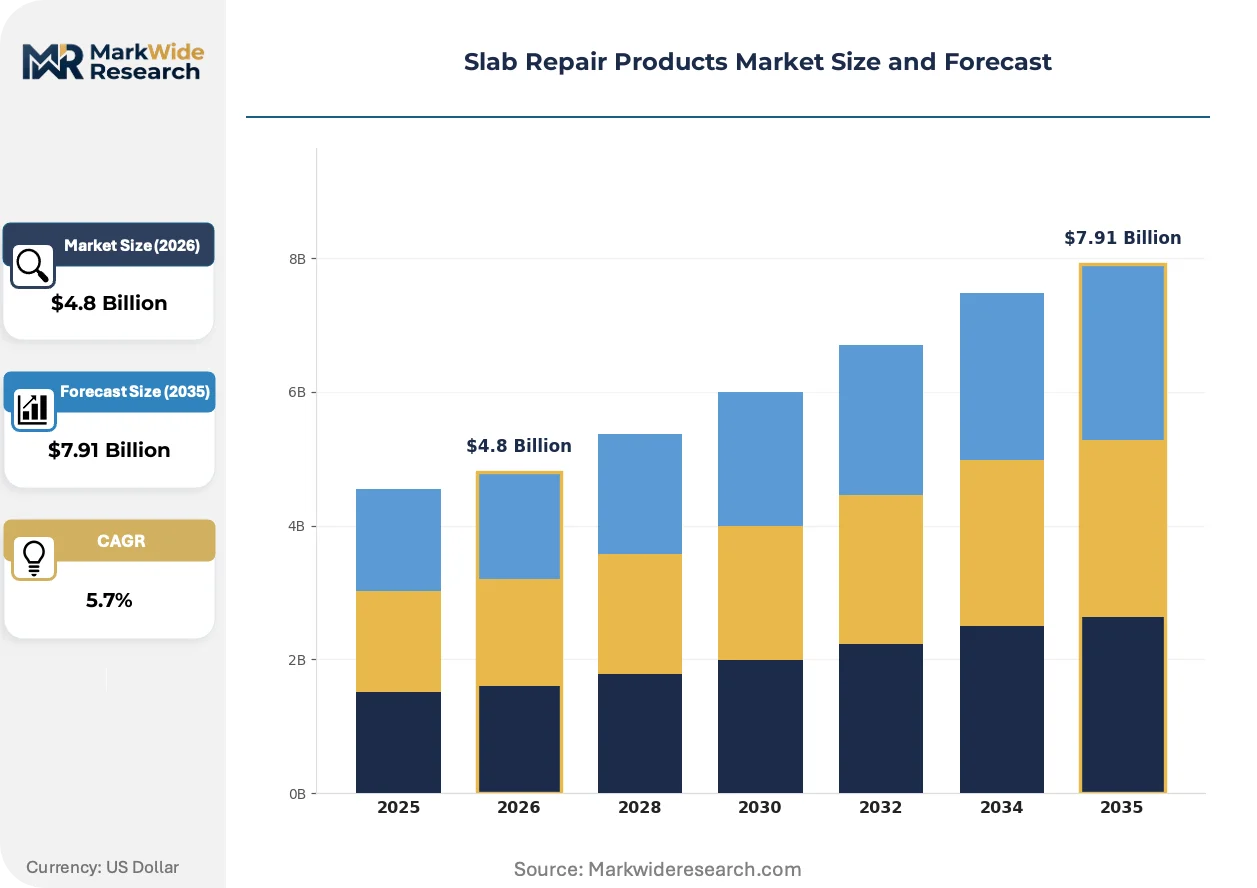
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Polymer, Cementitious Application: Residential, Commercial, Industrial, Infrastructure Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers End User: Contractors, Homeowners, Engineers, Architects |
| Companies Covered | BASF SE, Sika AG, Sherwin-Williams Company, SABIC, SILPRO, Mapei S.p.A., Fosroc International Ltd, GCP Applied Technologies, LafargeHolcim Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slab Repair Products Market Evolving Landscape
Material science advances and regulatory pressure on emissions are simultaneously reshaping formulation strategies and installation methodologies across the repair products value chain.
Ultrasonic pulse-echo testing equipment is digitizing quality assurance workflows for bonded repair systems. State DOT inspection crews and commercial contractors are adopting handheld diagnostic devices at accelerating rates. Real-time bond integrity verification is compressing warranty dispute resolution and enabling performance-based contractor compensation models.
REACH restrictions on isocyanate-containing formulations are forcing European manufacturers toward waterborne polyurethane alternatives. Industrial consequence includes reformulation R&D prioritization and supply chain requalification for raw material inputs. High-traffic commercial slab applications in Germany and France are most affected, with contractors accepting longer cure times in exchange for regulatory compliance.
Specification-driven procurement is consolidating buyer decision-making around certified performance metrics rather than unit pricing. Municipal engineering departments and facility managers are displacing traditional low-bid awards with life-cycle cost analysis frameworks. California and Texas DOT pilot programs demonstrate this shift most visibly, with multi-year material supply agreements replacing spot purchasing.
Slab Repair Products Market Segmentation
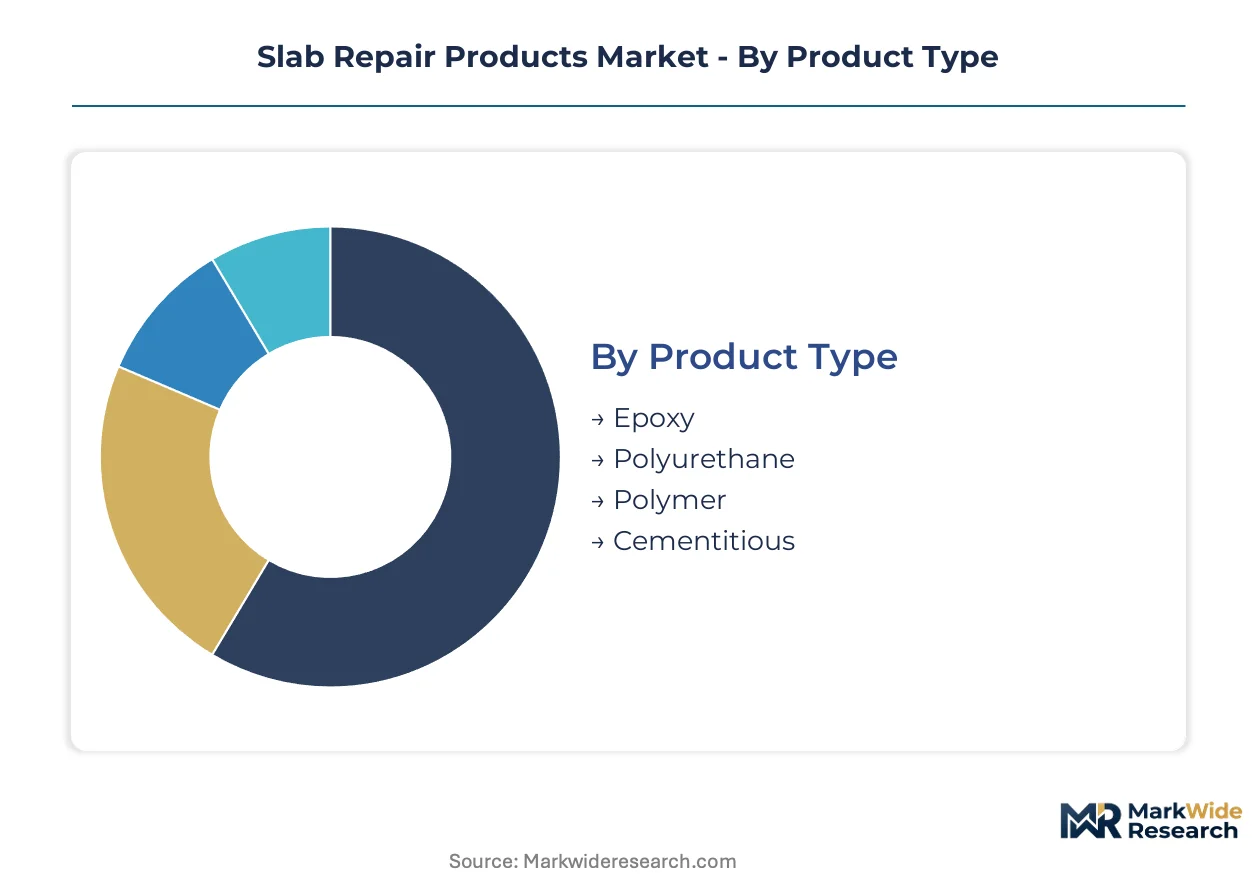
Segmentation in slab repair products reveals distinct performance requirements across substrate conditions, load-bearing demands, and installation expertise. Material selection varies sharply between structural rehabilitation and cosmetic surface restoration. Channel strategy must align with specification complexity and project scale.
Product Type:
Mature formulations dominate volume while emerging chemistries capture specification-driven premiums.
- Epoxy:Rigid thermosetting polymers achieve compressive strengths exceeding 10,000 psi with exceptional chemical resistance. Demand concentrates in US industrial floor restoration where rapid return-to-service justifies material cost premiums above cementitious alternatives. FHWA bridge deck specifications increasingly mandate epoxy bonding systems for load-transfer rehabilitation.
- Polyurethane:Flexible foaming systems accommodate dynamic crack movement through thermal cycling ranges. Airport pavement and bridge expansion joint applications in Texas and California drive procurement as state DOTs prioritize durability over rigid repair methods. EPA VOC regulatory compression is forcing waterborne formulation transitions.
- Polymer:Synthetic latex and acrylic modifiers enhance cementitious matrix flexibility and adhesion. Residential basement waterproofing and commercial slab resurfacing represent core demand channels.
- Cementitious:Portland cement-based compounds with polymer additives dominate material volume due to substrate compatibility and lower unit cost. Municipal infrastructure rehabilitation programs specify these systems for budget-constrained projects.
Cementitious systems handle the majority of throughput; polyurethane is expanding most quickly on specification capture in transportation infrastructure.
Application:
Cost tier segmentation separates commodity repair from engineered structural intervention.
- Infrastructure:Bridge decks, airport pavements, and highway slabs require materials meeting ASTM C881 and ACI 562 certification protocols. US Federal Highway Administration procurement cycles generate recurring demand for injection systems and bonded overlays. Deferred maintenance backlogs across state DOTs compress installation timelines.
- Industrial:Manufacturing floors, warehouses, and processing facilities demand chemical-resistant formulations with rapid cure profiles. Food and beverage plants specify USDA-compliant epoxy systems for sanitation compliance. Premium pricing sustains above-average margins despite smaller project volumes.
- Commercial:Retail floors, office buildings, and hospitality spaces prioritize aesthetic restoration with minimal downtime. High-traffic environments in urban cores drive polymer-modified cementitious overlay demand.
- Residential:Basement slabs, driveways, and garage floors represent price-sensitive demand concentrated in suburban renovation markets. DIY channel penetration varies by product complexity.
Infrastructure commands the steepest pricing tier; industrial applications are climbing fastest on specification stringency.
Distribution Channel:
Customer type dictates channel configuration and service intensity requirements.
- Direct Sales:Manufacturer-to-contractor relationships dominate specification-driven municipal and industrial procurement. State DOT prequalification programs favor suppliers with documented technical support capabilities.
- Distributors:Regional building material distributors serve fragmented commercial contractor markets with inventory proximity and credit terms. Branch network density correlates with construction activity concentration.
- Wholesalers:Volume aggregation for commodity cementitious products serves multi-location contractor operations and retail channel supply.
- Online Retail:E-commerce penetration remains limited to standard-grade residential repair kits with established performance reputations.
Distributors anchor commercial volume; direct sales is gaining share fastest on DOT specification capture.
End User:
Technical expertise stratification determines product complexity and support service bundling.
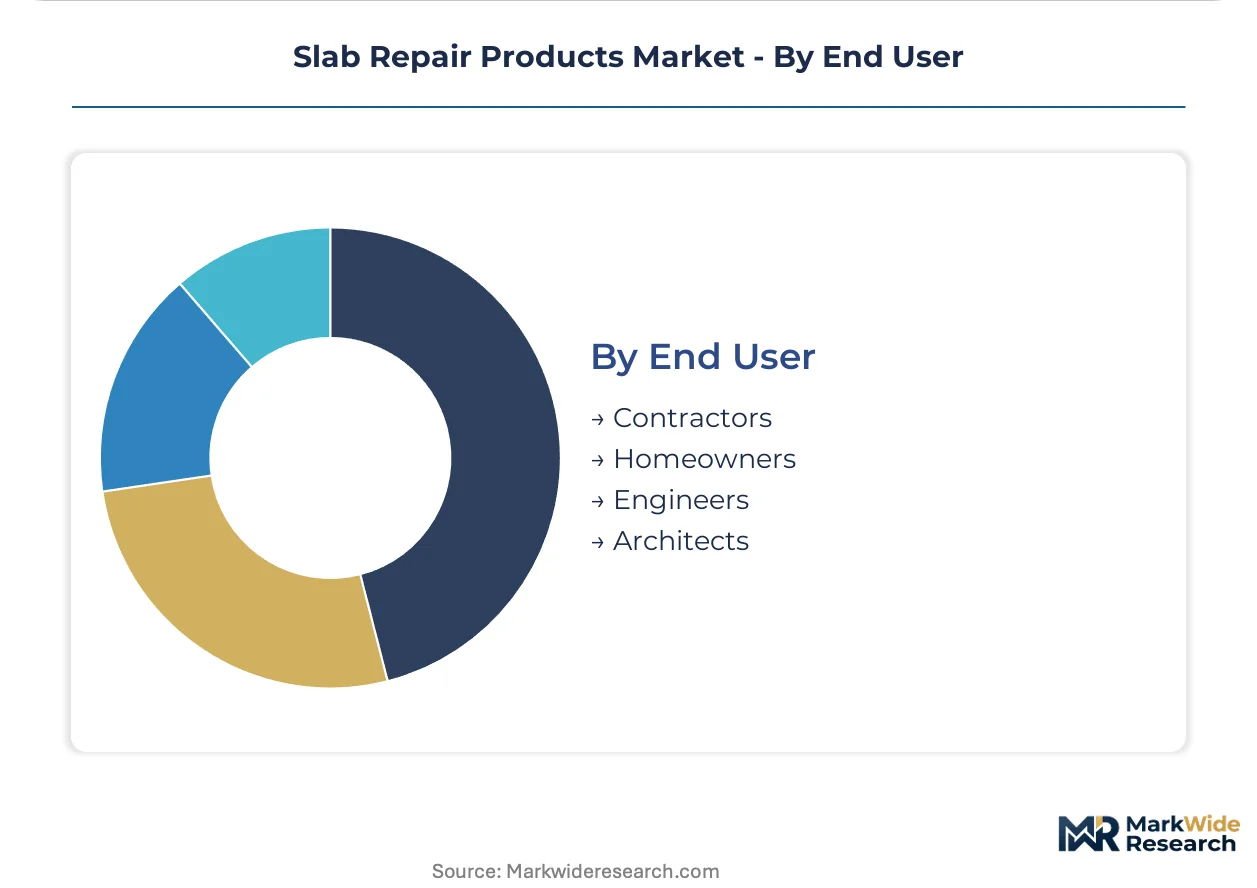
- Contractors:Licensed concrete repair specialists specify performance-grade systems with warranty documentation requirements. Application technician certification programs from material suppliers create switching costs.
- Engineers:Structural and civil engineering firms drive specification writing for infrastructure rehabilitation projects. ACI 562 evaluation protocol compliance influences material selection authority.
- Architects:Design professionals influence commercial and institutional project material selection through aesthetic and sustainability criteria.
- Homeowners:Retail channel consumers prioritize ease of application and cost minimization over long-term performance metrics.
Contractors handle the majority of product volume; engineers are the fastest mover on specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State DOT procurement offices and industrial facility managers concentrate buying power across mature infrastructure markets. Specification-driven material selection tilts procurement toward suppliers with documented compressive strength testing and bond durability certifications. Regional demand patterns track deferred maintenance backlogs and tightening FHWA performance standards.
United States
Federal Highway Administration bridge inspection mandates generate recurring procurement cycles for epoxy injection systems and cementitious repair compounds. State DOTs in California and Texas pilot multi-year material supply agreements displacing spot purchasing. The I-95 corridor from Boston through Washington DC concentrates commercial slab resurfacing demand in high-traffic urban cores.
Germany
REACH restrictions on isocyanate-containing formulations force waterborne polyurethane transitions in high-traffic commercial applications. Contractors accept extended cure times to maintain regulatory compliance. The Rhine-Ruhr industrial belt anchors demand for chemical-resistant epoxy systems in manufacturing floor restoration.
China
GB standards for structural concrete rehabilitation tighten material performance requirements in transportation infrastructure. Provincial transportation bureaus accelerate bridge deck repair programs under national infrastructure renewal directives. The Yangtze River Delta corridor concentrates polymer-modified cementitious overlay demand in Shanghai's commercial redevelopment zones.
India
BIS certification requirements for construction chemicals create specification barriers for imported repair formulations. State public works departments in Maharashtra and Gujarat prioritize cost-competitive cementitious systems for municipal bridge rehabilitation. The Delhi-Mumbai Industrial Corridor drives industrial floor restoration demand in manufacturing clusters.
Canada
Health Canada environmental assessments influence provincial transportation agency material specifications for infrastructure projects. Ontario and Quebec DOTs specify low-VOC epoxy systems for bridge deck rehabilitation in urban airsheds. The Greater Toronto Area concentrates commercial slab repair demand from aging institutional building portfolios.
Slab Repair Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented contractor markets. The vendor base spans multinational chemical conglomerates with direct-sales infrastructure and regional formulators serving price-sensitive municipal segments. Three archetypes dominate: specification-capturing multinationals, polymer-chemistry specialists, and volume-oriented cementitious suppliers. Competitive moves center on state DOT prequalification capture and waterborne formulation transitions under tightening emissions limits.
Among specification-capturing multinationals, Sika AG and Mapei S.p.A. exemplify the polymer-formulation specialist archetype with documented technical support capabilities. BASF SE anchors the diversified chemical conglomerate tier with cross-selling leverage across construction chemical portfolios. These three entities occupy positions where regulatory compliance documentation and compressive strength certification create switching costs for procurement officers.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| Sherwin-Williams Company |
| SABIC |
| SILPRO |
| Mapei S.p.A. |
| Fosroc International Ltd |
| GCP Applied Technologies |
| LafargeHolcim Ltd |
| Others |
Value Network & Pricing Analysis
The Houston-Gulf Coast petrochemical corridor anchors North American epoxy resin and polyurethane precursor capacity, and its operating rate fluctuations transmit directly into formulated product pricing power for slab repair manufacturers serving state DOT procurement offices.
Pricing Analysis
Cost-plus contracts with crude oil derivative indexation dominate procurement agreements between formulators and municipal buyers. Three-tier pricing structure across premium, standard, and economy levels separates DOT-specified epoxy injection systems from commercial polymer-modified cementitious overlays and residential-grade repair kits. Pricing pressure stems from EPA-mandated VOC reformulation investments that compress margins on solventborne product lines. Residential homeowners exhibit highest price sensitivity, while industrial facility managers prioritize rapid return-to-service over material cost minimization.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become a competitive differentiator for distributors serving fragmented commercial contractor markets. Raw material production concentrates in the United States, Germany, and China, with bisphenol-A epichlorohydrin resins and aromatic isocyanates feeding formulation plants. Supply chain risk centers on single-source vulnerability for specialty amine hardeners used in rapid-cure industrial applications. Distribution runs through regional building material distributors with branch network density correlating to construction activity concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
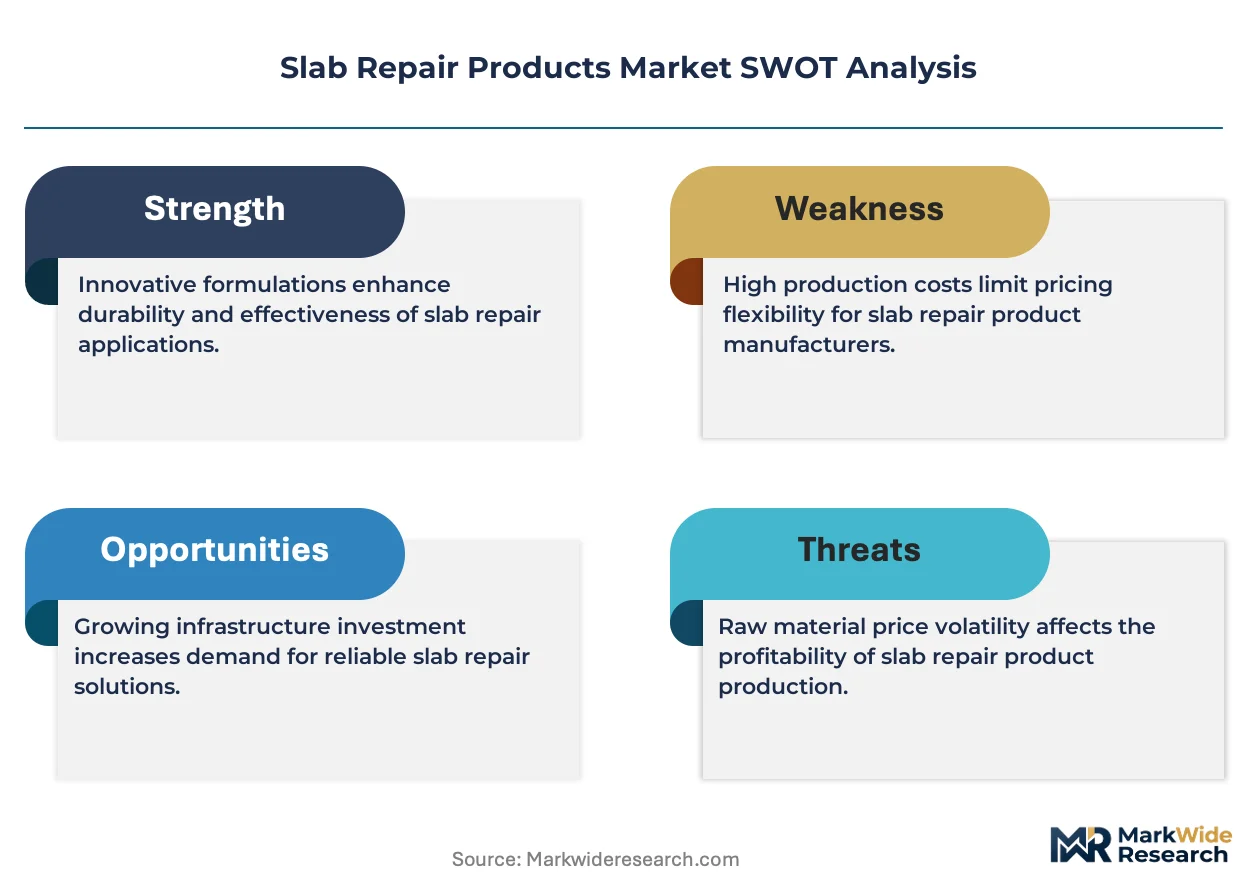
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. State DOT prequalification programs and ACI 562 certification requirements generate switching costs that protect incumbent specification share.
For Market Incumbents: Build specification moats through accelerated ACI 562 certification investments and state DOT prequalification capture. Cementitious formulators face margin compression from petrochemical feedstock volatility. Backward integration into polymer-modified cementitious raw materials secures cost position against commodity epoxy resin price swings. For New Entrants and Emerging Players: India's state public works departments represent the most penetrable geographic underpenetration for cost-competitive cementitious systems. BIS certification barriers favor domestic manufacturing partnerships over direct import strategies. Digital direct-to-contractor platforms bypass traditional distributor markups in fragmented municipal procurement channels. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because tightening FHWA bridge inspection standards and REACH-compliant formulation transitions favor suppliers with documented compliance infrastructure. Acquisition targets should display vertical integration into waterborne polyurethane chemistry and established state DOT technical support capabilities. Monitor EPA VOC rulemaking timelines as inflection indicators for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation Transition | EPA VOC compliance investments reposition solventborne epoxy suppliers for municipal specification retention. |
| State DOT Prequalification Capture | Documented compressive strength testing secures multi-year material supply agreements displacing spot purchasing. |
| Direct-to-Contractor Digital Platform | Asset-light distribution bypasses traditional distributor markups in fragmented commercial procurement channels. |
| Self-Healing Concrete R&D Partnership | Convergence with wireless sensor networks creates white space for embedded diagnostic repair products. |
| Application Technician Certification Program | Trained crew pipelines address execution bottlenecks and create switching costs for specification-driven contractors. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary validation anchors the qualitative findings. Concrete repair contractors, state DOT materials engineers, polymer formulation chemists, and commercial facility maintenance directors provided operational perspectives. Trade data from USITC, ACI technical committee publications, EPA regulatory dockets, and FHWA bridge inventory databases supplied quantitative anchors. Bottom-up project pipeline analysis and top-down construction spending allocation triangulate market sizing.
Calibration against historical specification adoption curves and raw material price elasticity informs the projection framework. Segmentation dimensions span product chemistry, application severity, distribution channel, and end-user technical sophistication. CAGRs derive from regression analysis of infrastructure investment cycles and regulatory compliance timelines. Modeled inputs include state DOT deferred maintenance backlog data and REACH restriction implementation schedules.
Practitioners should monitor petrochemical feedstock volatility, EPA VOC rulemaking acceleration, and state DOT procurement method shifts for early signals. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure appropriation levels. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Global Fencing Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Composite Repair Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Fire Hydrants Market