
 Timber Floor Joist Market | 2026-2036
Timber Floor Joist Market Size, Share, and Industry Trends Forecast 2026-2036
Timber Floor Joist Market Analytics
Cross-laminated timber is rebalancing traditional sawn-lumber economics in floor systems as architects specify taller mass-timber structures. West Fraser leverages vertical integration from British Columbia timberlands to engineered-joist mills, sustaining cost advantages across the Pacific Northwest. Boise Cascade anchors its position through proprietary software that optimizes I-joist layouts for multifamily developers. Roseburg Forest Products competes on the strength of its Southern Pine resource base, controlling fiber supply through company-owned forests in the US Southeast.
Timber floor joists are structural horizontal members, typically spanning 2.4 to 6.0 meters, that support floor loads and transfer them to beams, walls, or foundations; engineered variants combine oriented strand board webs with laminated veneer lumber flanges to achieve superior strength-to-weight ratios and dimensional stability. I-Joists dominate new residential construction in North America due to their predictable performance and reduced callback rates from floor squeak complaints. LVL Joists capture premium share in commercial mid-rise applications where longer spans and heavier loads demand enhanced structural capacity. Solid Timber Joists retain cost-sensitive renovation work where existing structures constrain dimensional tolerances.
US building codes adopted through the International Code Council shape product acceptance criteria for prescriptive span tables, while the EPA's formaldehyde emission standards under TSCA Title VI govern adhesive systems in engineered joist manufacturing. The EU Construction Products Regulation mandates CE marking and harmonized EN standards for structural timber members sold in member states. Stakeholders must monitor evolving carbon-accounting frameworks that credit biogenic carbon storage, as these rules will determine whether timber joists command green premiums or face competition from lower-embodied-carbon alternatives.
Market Dynamics
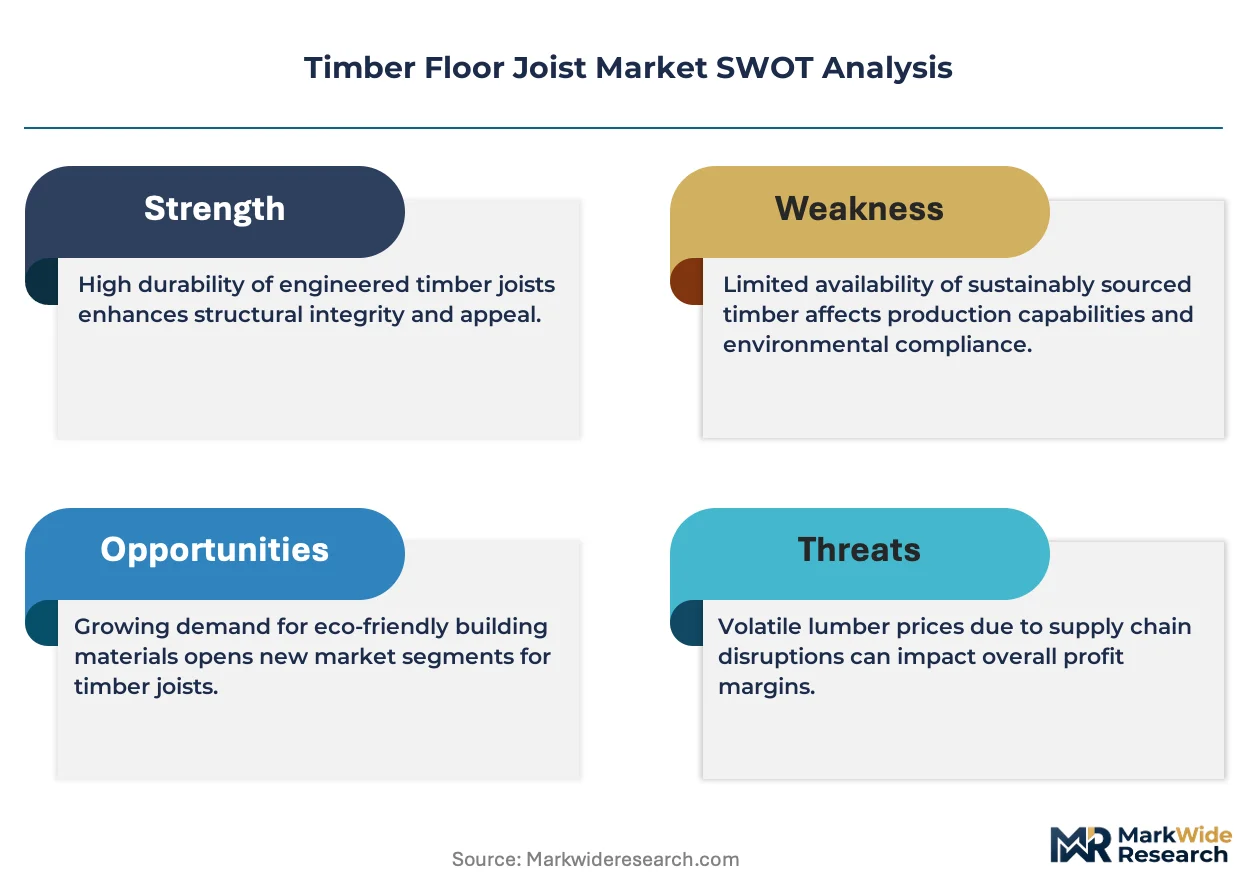
Mass-timber building codes are compressing traditional sawn-lumber demand as architects specify taller hybrid structures requiring engineered joist systems with verified fire ratings and carbon credentials.
Growth Catalysts
- US EPA TSCA Title VI formaldehyde standards:These emission limits accelerate substitution of solid timber with low-VOC engineered I-joists in multifamily housing.
- Mid-rise residential construction:Five-over-one podium buildings in Seattle and Portland specify LVL joists for longer spans and reduced floor vibration.
- Carbon-accounting frameworks:Biogenic carbon storage credits in EU member states and British Columbia green building programs reward timber joist specification over steel and concrete alternatives.
Market Restraints
- Oriented strand board web supply concentration:North American OSB mill capacity limits I-joist production scaling during demand surges.
- Adhesive chemistry costs:Phenol-formaldehyde and polyurethane resin prices track volatile petrochemical feedstock indices.
- Steel and concrete substitution:Hybrid construction in seismic zones and commercial high-rises favors non-combustible structural systems despite timber's carbon advantages.
Strategic Opportunities
- Australian multi-story timber framing:Building code amendments in Victoria and New South Wales permit eight-story timber structures, opening engineered joist demand.
- Prefabricated floor cassettes:Offsite manufacturing integrates I-joist, sheathing, and MEP rough-in, compressing on-site labor hours.
- German KfW climate construction incentives:Low-interest loans for carbon-efficient buildings steer developers toward certified timber systems.
Industry Challenges
- Structural engineer capacity:Mass-timber design expertise concentrates in Vancouver, London, and Vienna, creating project bottlenecks elsewhere.
- CE marking harmonization delays:EN 1995 timber design standard updates lag behind product innovation, slowing cross-border specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Timber Floor Joist Market |
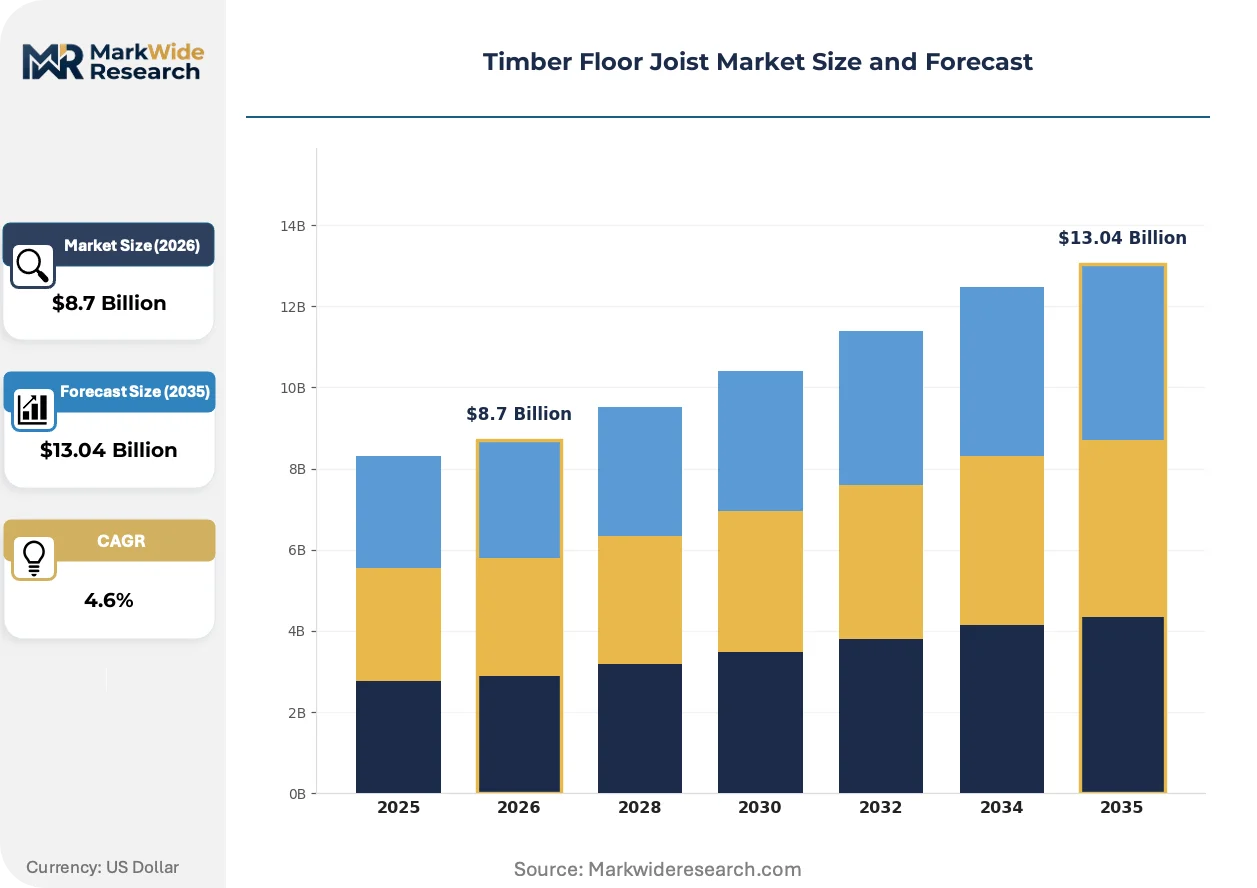
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineered Joists, Solid Timber Joists, LVL Joists, I-Joists Material: Pine, Spruce, Hardwood, Plywood End User: Residential Construction, Commercial Buildings, Industrial Facilities, Renovation Projects Installation Method: Pre-fabricated, Site-built, Modular, Traditional |
| Companies Covered | West Fraser, Boise Cascade, Roseburg Forest Products, Louisiana-Pacific Corporation, Weyerhaeuser Company, RedBuilt, Pacific Woodtech Corporation, Stark Truss Company, EACOM Timber Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Timber Floor Joist Market Evolving Landscape
Digital fabrication and bio-based adhesives are compressing the performance gap between commodity lumber and precision-engineered floor systems. Specification software now automates span optimization.
Cross-laminated timber floor plates is absorbing secondary load-bearing functions from traditional joist systems in commercial mid-rise construction. German and Austrian developers specify CLT for its two-way spanning capacity and exposed ceiling aesthetics. This hybrid approach is absorbing market share from pure I-joist solutions in buildings over six stories.
EU Construction Products Regulation harmonized standards are mandating Environmental Product Declarations for all structural timber members sold in member states. Manufacturers must document cradle-to-gate carbon footprints and end-of-life scenarios. Nordic producers with certified supply chains capture specification preference in Netherlands and France public procurement.
Developer procurement teams now bundle structural timber with carbon offset verification services. Large multifamily builders in Portland and Vancouver contract directly with engineered wood mills for project-specific EPDs. This service-layer unbundling shifts margin from commodity distribution to technical consulting.
Timber Floor Joist Market Segmentation
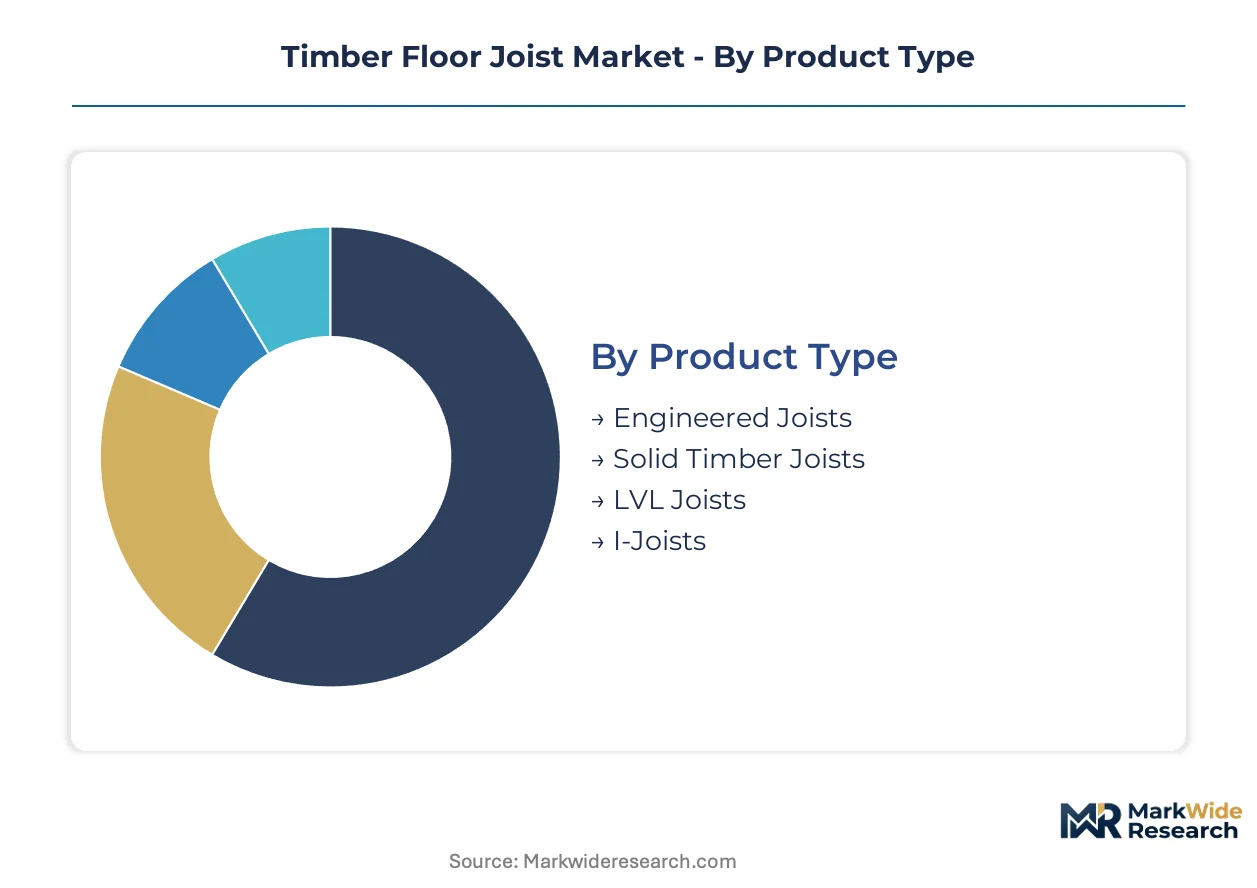
Timber floor joist procurement patterns diverge sharply across product categories, with engineered systems commanding premium specification in code-driven markets while solid timber retains renovation economics. Understanding these segment boundaries clarifies where margin pools concentrate and which material-grade combinations unlock carbon-credit eligibility.
Product Type:
Supply concentration in OSB web manufacturing and LVL flange production tilts competitive advantage toward vertically integrated producers with captive fiber supply.
- I-Joists:Composite members pair oriented strand board webs with laminated veneer lumber flanges, delivering predictable stiffness and reduced floor vibration. Demand concentrates in United States multifamily podiums where prescriptive span tables favor their strength-to-weight ratio and builders value reduced callback rates from squeak complaints.
- LVL Joists:Continuous veneers bonded under heat and pressure create uniform structural members capable of spanning 7.5 meters without intermediate support. Commercial mid-rise applications in Germany and Australia specify these for longer clear spans where floor loading exceeds residential thresholds.
- Engineered Joists:Broad category capturing proprietary composite systems outside standard I-joist geometries, including rim boards and specialty headers.
- Solid Timber Joists:Traditional dimensional lumber retains cost-sensitive renovation work where existing structures constrain dimensional tolerances and engineered product lead times prove prohibitive.
Today's leader: I-Joists. Tomorrow's challenger: LVL Joists.
Material:
Cost tier differentiation separates plantation-softwood feedstocks from certified temperate hardwoods, with plywood laminates occupying a mid-tier specification niche.
- Pine:Southern Yellow Pine and Radiata Pine dominate North American and Australasian engineered joist production respectively, with fast growth cycles supporting fiber cost discipline.
- Spruce:Nordic Spruce from Scandinavian and Baltic supply basins feeds European LVL mills, with cold-climate density delivering favorable mechanical properties for long-span applications.
- Hardwood:Dense temperate species command specialty specification in acoustic-rated floor systems where mass damping reduces impact sound transmission.
- Plywood:Cross-banded veneer construction provides dimensional stability in rim boards and header applications where edge-loading resistance matters.
Volume concentrates in Pine. Margin expansion potential sits with certified Spruce supply chains.
End User:
Application-driven specification splits between prescriptive-code residential tract housing and performance-specified commercial structures requiring engineer-stamped calculations.
- Residential Construction:Single-family and low-rise multifamily builders in the United States specify I-joists for predictable installation speed and reduced jobsite waste. Five-over-one podium typologies in Seattle and Portland drive LVL demand for transfer slabs.
- Commercial Buildings:Mid-rise office and retail structures in Germany and Australia specify engineered joists with verified fire ratings, with CLT floor plates absorbing secondary functions in taller mass-timber buildings.
- Industrial Facilities:Warehouse and light manufacturing floors prioritize solid timber for point-load tolerance and repairability.
- Renovation Projects:Existing structure constraints favor dimensional lumber matching legacy framing, particularly in heritage-designated buildings where material substitution triggers regulatory review.
Residential Construction anchors volume. Commercial Buildings deliver the steepest expansion trajectory as mass-timber codes mature.
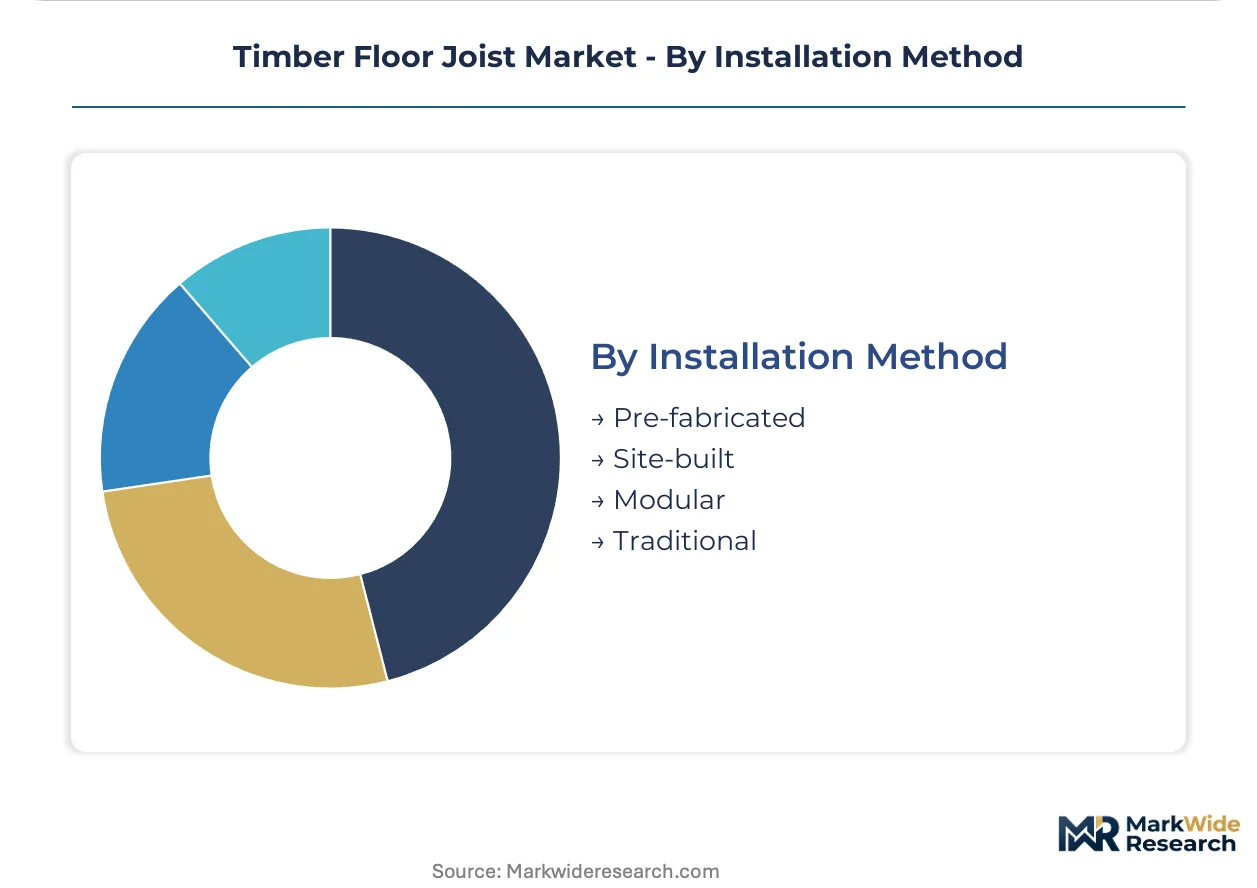
Installation Method:
Customer type stratification separates offsite manufacturers integrating floor cassettes from stick-build contractors purchasing commodity joists.
- Pre-fabricated:Factory-built floor cassettes combine I-joists, sheathing, and MEP rough-in, compressing on-site labor hours for United Kingdom and Netherlands developers facing skilled-trades shortages.
- Modular:Volumetric construction units integrate complete floor assemblies, with joist specification determined by transport-load constraints and crane-lift limitations.
- Site-built:Traditional stick-framing persists in United States custom home markets where builders value just-in-time delivery flexibility.
- Traditional:Solid timber joists cut to length on site dominate renovation work and markets with limited engineered product distribution infrastructure.
Pre-fabricated methods gain fastest. Site-built retains largest installed-base inertia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Northwest industrial cluster anchors engineered wood manufacturing, with British Columbia and Washington State mills feeding cross-border supply chains for mass-timber construction.
United States
Five-over-one podium typologies in Seattle and Portland drive LVL specification for transfer slabs, while EPA TSCA Title VI formaldehyde standards accelerate engineered I-joist substitution in multifamily housing. The Southeast cluster around Georgia and Alabama leverages Southern Yellow Pine fiber supply for cost-competitive production.
Germany
KfW climate construction incentives steer developers toward certified timber systems, with mid-rise commercial buildings in Munich and Hamburg specifying engineered joists with verified fire ratings. The EU Construction Products Regulation mandates CE marking and harmonized EN standards for structural timber members.
Australia
Building code amendments in Victoria and New South Wales permit eight-story timber structures, opening engineered joist demand for multi-story residential framing. Melbourne and Sydney architects specify LVL products for longer clear spans in commercial mid-rise applications.
Canada
British Columbia green building programs reward timber joist specification over steel and concrete alternatives, with Vancouver emerging as a mass-timber design expertise hub. Provincial carbon-accounting frameworks credit biogenic carbon storage in public procurement decisions.
United Kingdom
Factory-built floor cassettes gain traction among developers facing skilled-trades shortages, with offsite manufacturers in the Midlands and North England integrating I-joists with sheathing and MEP rough-in. The Net Zero Strategy drives specification toward low-embodied-carbon structural systems.
Timber Floor Joist Market Competitive Landscape
Global majors compete with regional champions across fiber supply and specification software capabilities. The vendor base stratifies between vertically integrated timberland owners and specialized engineered-joist fabricators. Three archetypes dominate: captive-fiber producers controlling upstream timber supply, technology-anchored specialists offering layout optimization software, and regional truss manufacturers serving renovation contractors. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure OSB web supply and distribution relationships.
Among North American timberland-anchored producers, West Fraser and Boise Cascade occupy positions reflecting British Columbia and Pacific Northwest fiber access respectively. Roseburg Forest Products exemplifies the Southern Pine resource base archetype. These three represent distinct supply-chain configurations: northern temperate, technology-integrated, and southeastern plantation-softwood.
| Leading Market Players |
|---|
| West Fraser |
| Boise Cascade |
| Roseburg Forest Products |
| Louisiana-Pacific Corporation |
| Weyerhaeuser Company |
| RedBuilt |
| Pacific Woodtech Corporation |
| Stark Truss Company |
| EACOM Timber Corporation |
| Others |
Value Network & Pricing Analysis
Multifamily developers in Seattle and Portland anchor pricing power for engineered I-joists and LVL systems, with procurement concentrated among podium-building specialists who negotiate project-based long-term offtake contracts tied to green building certification tiers.
Pricing Analysis
Phenol-formaldehyde and polyurethane resin costs pass through directly to engineered joist pricing, with petrochemical feedstock volatility compressing margins for non-integrated producers. Pricing stratifies across premium certified-spruce supply chains, standard plantation-pine grades, and economy solid-timber renovation tiers. Cost compression in the economy tier is intensifying because OSB web supply concentration limits production scaling during demand surges. Residential tract builders exhibit highest price sensitivity, while commercial mid-rise developers prioritize fire-rated performance over unit economics.
Supply Chain Analysis
End-of-life timber recovery flows remain underdeveloped, with demolition waste streams currently diverted to biomass rather than remanufacturing into engineered fiber feedstocks. Manufacturing concentrates in the United States, Canada, and Germany, with British Columbia and Pacific Northwest mills anchoring North American engineered wood capacity. Production draws from Southern Yellow Pine, Nordic Spruce, and Radiata Pine resource bases. Single-source vulnerability in OSB web supply creates bottleneck risk during construction seasonality peaks. Distribution runs through regional building-material distributors and direct mill relationships with offsite manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The timber floor joist market functions as a stable compounder, with residential construction code adoption providing steady specification pull for engineered systems across successive building cycles.
For Market Incumbents: Deploy captive fiber supply as the primary defensive lever. Secure long-term timberland leases in the US Southeast and Pacific Northwest to hedge against raw material cost volatility. Invest in proprietary span-optimization software to lock in multifamily developer relationships before CLT floor plates displace pure I-joist solutions in mid-rise applications. For New Entrants and Emerging Players: Begin with prefabricated floor cassette manufacturing for UK and Netherlands developers facing skilled-trades shortages. Target Australian multi-story timber framing as the most penetrable geography following eight-story code amendments in Victoria and New South Wales. Pursue direct contracting relationships with carbon-conscious municipal procurement programs as the entry wedge. For Investors and Strategic Acquirers: Building products conglomerates with existing distribution networks are the most active acquirer in this space, seeking engineered wood capabilities to complement legacy lumber portfolios. The five-to-ten year viability window favors targets with certified supply chains and EPD documentation capabilities. Monitor mass-timber building code adoption velocity in Germany and Australia as the inflection signal for LVL demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberland | West Fraser and Roseburg Forest Products secure Southern Pine fiber cost discipline through company-owned forests. |
| Specification Software Development | Boise Cascade's proprietary I-joist layout optimization locks in multifamily developer loyalty and reduces engineering costs. |
| Environmental Product Declaration Investment | Nordic producers capture Netherlands and France public procurement preference through certified cradle-to-gate carbon documentation. |
| Prefabricated Floor Cassette Manufacturing | UK and Netherlands offsite manufacturers compress on-site labor hours by integrating I-joists with sheathing and MEP rough-in. |
| Carbon Offset Verification Services | Portland and Vancouver developers unbundle margin from commodity distribution to technical consulting through project-specific EPD contracting. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with engineered wood mill operations managers, multifamily developer procurement directors, structural engineering consultants, and building code officials informed demand-side assumptions. Secondary sources include International Code Council prescriptive span tables, EPA TSCA Title VI formaldehyde emission filings, EU Construction Products Regulation harmonized standards documentation, and national timber trade association production statistics. Bottom-up volume modeling triangulates against top-down construction spending allocation.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, material grade, end-use application, and installation method. CAGRs derive from regression analysis against housing starts, commercial construction permits, and mass-timber building code adoption curves. Industry-specific inputs incorporate OSB mill capacity utilization rates and biogenic carbon credit eligibility frameworks.
Several conditions sit outside the modeled scope, including seismic zone construction restrictions favoring steel and concrete, adhesive chemistry substitution timelines, and trade policy shifts affecting cross-border timber flows. Forecasts reflect documented assumptions about code adoption velocity and fiber supply continuity. Practitioners should monitor EN 1995 standard update delays and CLT floor plate specification rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Europe Construction Chemicals Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
China UPVC Doors and Windows Market