
 North America Sodium Chlorate Market | 2026-2036
North America Sodium Chlorate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sodium Chlorate Market Intelligence
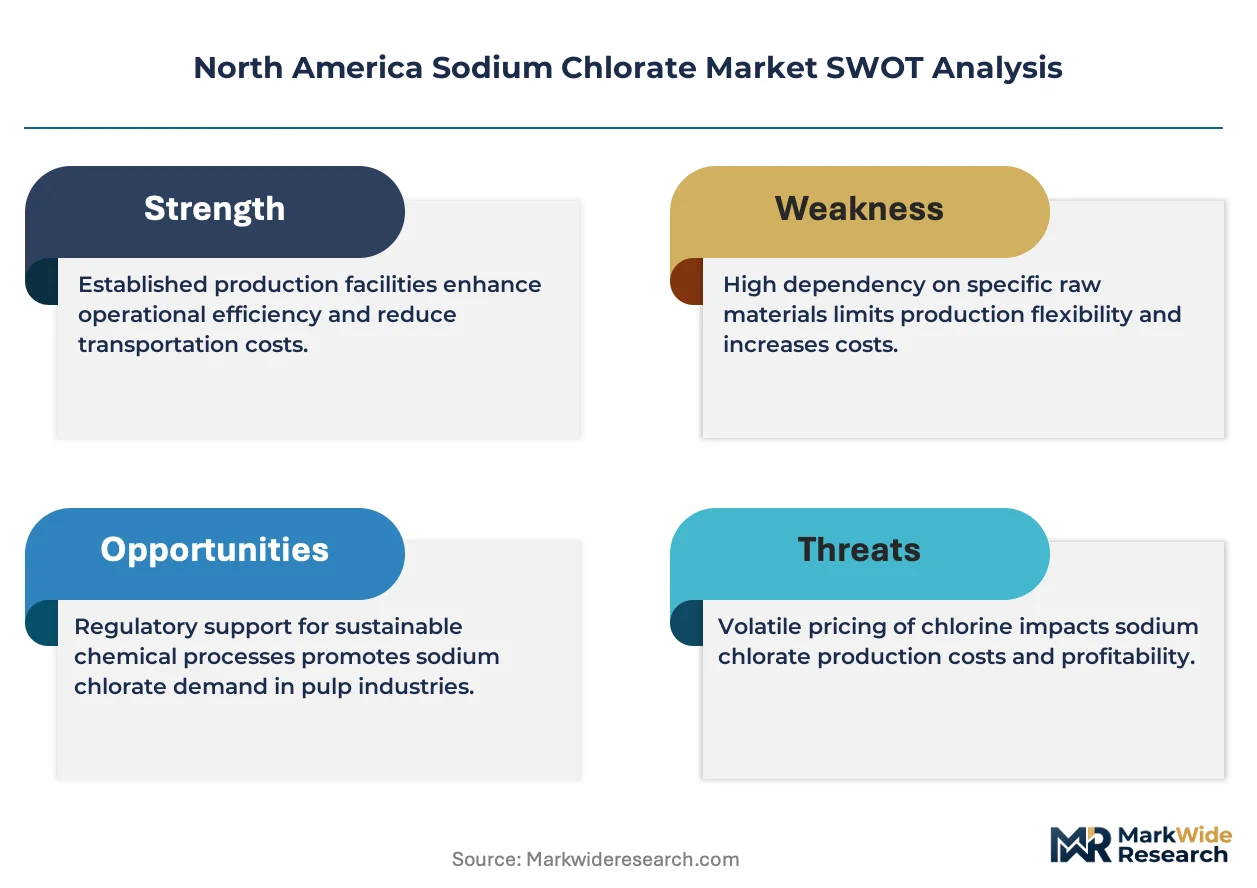
Chlorine dioxide is pivoting away from elemental chlorine in pulp bleaching, altering sodium chlorate consumption economics across North America. Nouryon leverages its integrated chlor-alkali network to sustain cost-advantaged supply to Canadian kraft mills. ERCO Worldwide anchors its position through captive sodium chlorate production tied to Great Lakes shipping corridors. Kemira competes via specialized peroxygens co-marketing with chlorate-derived bleaching chemicals.
Sodium chlorate is an inorganic salt with the chemical formula NaClO3, produced industrially through electrolysis of sodium chloride brine in undivided cells, yielding a white crystalline solid with high oxidative stability. Its primary commercial purpose centers on on-site generation of chlorine dioxide for elemental-chlorine-free pulp bleaching and selective herbicide formulations. Technical grade sodium chlorate dominates volume flows into pulp and paper applications where bleach plant throughput dictates offtake scale. Water treatment applications represent the fastest-expanding demand pool as municipalities adopt advanced oxidation processes for emerging contaminant removal. Industrial grade supply channels into herbicide blending operations where perchlorate impurity thresholds determine product acceptance.
The EPA regulates chlorate discharge limits under Clean Water Act effluent guidelines, while OSHA mandates permissible exposure limits for dust handling in production facilities. Health Canada and PMRA coordinate cross-border standards for herbicide residues and drinking water chlorate thresholds. Transport Canada and the US DOT enforce stringent classification rules for oxidizer shipments across the Great Lakes and Mississippi basin corridors. Stakeholders must monitor regulatory divergence between US and Canadian perchlorate screening levels as this tension reshapes purification investment decisions and cross-border product qualification requirements.
Market Dynamics
The EPA's tightening effluent guidelines for chlorate discharge are forcing bleach plant operators to recalibrate chemical dosing protocols and wastewater treatment investments, compressing operational margins while elevating specification requirements for sodium chlorate purity grades.
Growth Catalysts
- Elemental-Chlorine-Free Bleaching Mandates:Pulp and paper mills across the southeastern United States are accelerating chlorine dioxide adoption to meet EPA Cluster Rule compliance deadlines.
- Great Lakes Shipping Corridors:Captive sodium chlorate production tied to integrated chlor-alkali facilities reduces delivered cost to Canadian kraft mills.
- Advanced Oxidation Process Adoption:Municipal water treatment facilities are deploying chlorate-derived oxidation for emerging contaminant removal under Safe Drinking Water Act mandates.
Market Restraints
- Electrolytic Energy Intensity:Sodium chloride brine electrolysis consumes substantial electricity, exposing producers to volatile power pricing in deregulated US and Canadian markets.
- Perchlorate Impurity Thresholds:Health Canada and PMRA screening levels for herbicide-grade sodium chlorate are diverging from US EPA guidance, fragmenting cross-border product qualification.
- Membrane Cell Technology Substitution:Chlor-alkali producers are shifting membrane cell investments away from undivided cell configurations, constraining dedicated sodium chlorate capacity expansion.
Strategic Opportunities
- Municipal Water Treatment Underpenetration:Advanced oxidation process adoption in mid-sized US municipalities remains below saturation, creating greenfield installation demand.
- Peroxygens Co-Marketing Convergence:Bleaching chemical suppliers are bundling sodium chlorate with hydrogen peroxide formulations to capture integrated pulp mill procurement consolidation.
- Cross-Border Rail Distribution Innovation:Dedicated oxidizer railcar fleets are expanding direct-to-mill delivery networks across the Mississippi basin, bypassing traditional distributor markups.
Industry Challenges
- Electrochemical Process Control Expertise Gap:Undivided cell electrolysis optimization requires specialized engineering talent that has concentrated at legacy production sites.
- Multi-Jurisdictional Certification Complexity:Simultaneous EPA, OSHA, Transport Canada, and US DOT compliance for chlorate shipments creates documentation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sodium Chlorate Market |
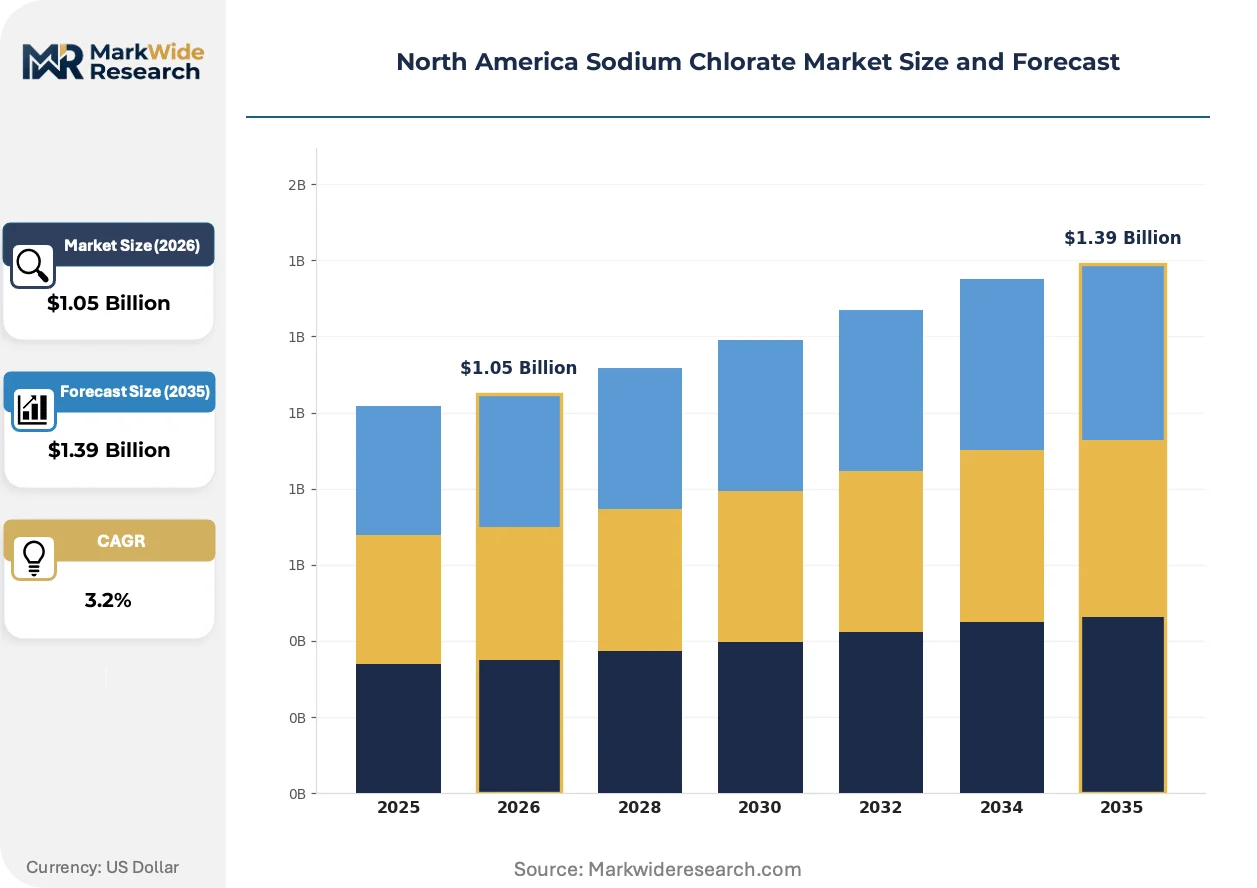
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Food Grade, Pharmaceutical Grade, Industrial Grade Application: Pulp & Paper, Water Treatment, Herbicides, Bleaching Agents End User: Paper Manufacturers, Chemical Producers, Agricultural Sector, Municipalities Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Nouryon, AkzoNobel, ERCO Worldwide, DuPont de Nemours Inc, Occidental Petroleum Corp, Chemtrade, Kemira, Arkema, Olin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sodium Chlorate Market Strategic Shifts & Innovations
Electrochemical process intensification and regulatory chemistry standardization are converging to reshape how sodium chlorate is produced, specified, and delivered across North American supply chains.
Membrane electrolysis retrofits are integrating into existing undivided cell infrastructure to reduce specific energy consumption per metric ton of sodium chlorate output. Pulp and paper producers with captive bleach plants are piloting these hybrid configurations to hedge against carbon pricing exposure. The technology is integrating production economics with emissions compliance, compressing the cost gap between merchant and captive supply.
EPA effluent limitation guidelines for pulp and paper mills are tightening chlorate discharge thresholds under revised Clean Water Act frameworks. This regulatory pressure is forcing bleach plant operators to install secondary treatment systems or switch to lower-impurity sodium chlorate grades. Southeastern US integrated mills are most affected, accelerating qualification programs for technical-grade material with enhanced purity specifications.
Direct mill procurement contracts are displacing traditional distributor-mediated supply arrangements for high-volume bleach plant operators. Pulp producers with chlorine dioxide generators are negotiating long-term offtake agreements with integrated chlor-alkali suppliers, extracting volume-based pricing concessions. This concentration is most visible across Canadian kraft mill networks where captive production economics favor dedicated supply relationships over spot market participation.
North America Sodium Chlorate Market Segmentation
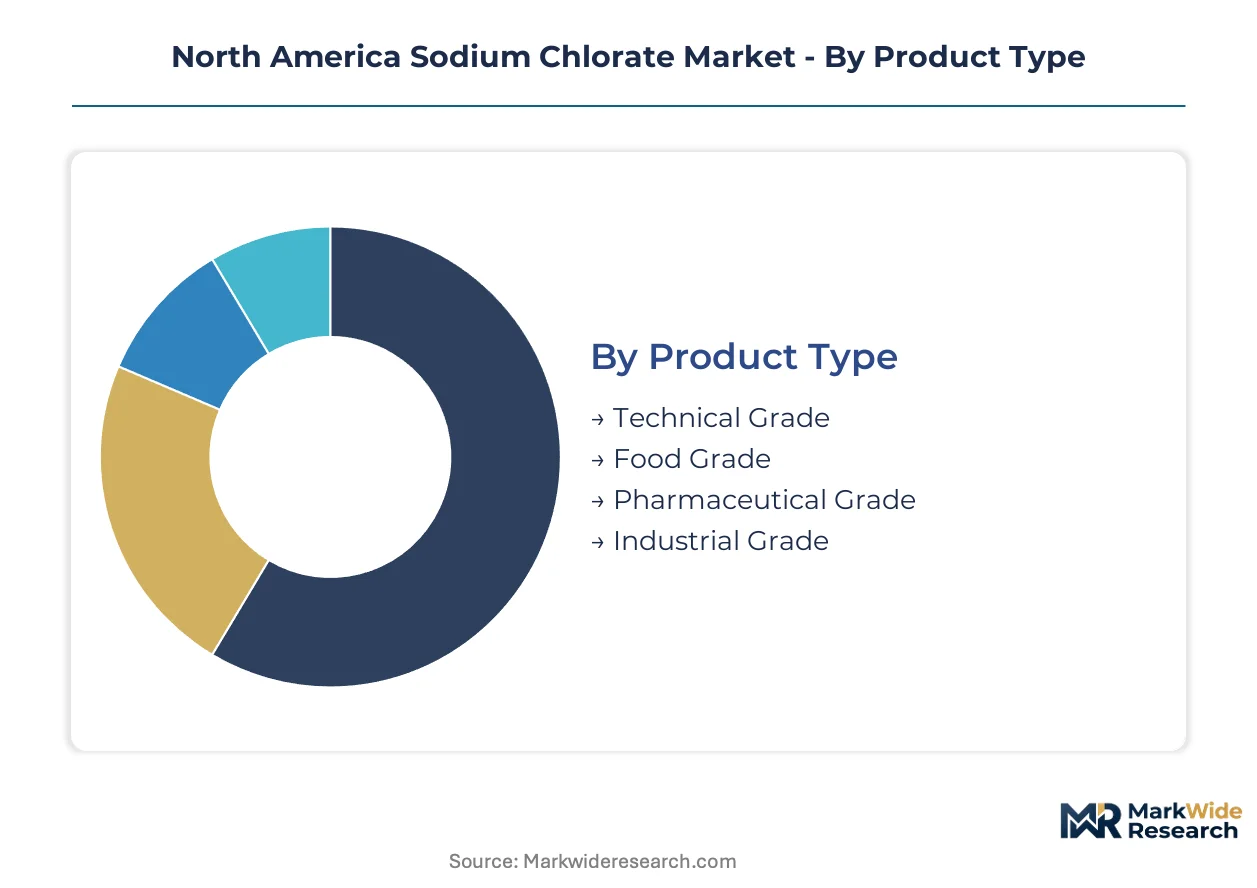
Sodium chlorate specification tiers align directly with downstream oxidative chemistry requirements. Pulp bleaching, herbicide formulation, and water treatment each impose distinct purity thresholds that fragment procurement patterns across North American supply chains.
Product Type:
Volume flows concentrate in industrial and technical grades where specification tolerance permits higher throughput economics, while food and pharmaceutical segments command premium purification investments.
- Technical Grade:Crystalline sodium chlorate with controlled moisture content and minimal insoluble residue, formulated for chlorine dioxide generation in bleach plant operations. Demand clusters at southeastern US kraft mills where EPA Cluster Rule compliance drives consistent offtake. Pulp and paper procurement teams specify this grade for on-site ClO₂ reactor feedstock.
- Industrial Grade:Standard-purity salt with broader impurity bandwidth, serving herbicide blending operations and non-critical oxidation processes. Agricultural sector buyers across the Mississippi basin absorb volume here, with perchlorate content thresholds varying by state regulatory interpretation. This grade trades at cost-advantaged positions against technical material.
- Food Grade:Refined product meeting FDA direct food additive specifications for antimicrobial surface treatments. Poultry and produce processing facilities in California and Texas represent concentrated uptake.
- Pharmaceutical Grade:Highest-purity material compliant with USP monograph requirements for active pharmaceutical ingredient synthesis. Limited demand concentrates at contract manufacturing organizations in Puerto Rico and Massachusetts.
Mature deployment sits with Technical Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
End-use concentration follows bleach chemistry adoption curves and regulatory enforcement timelines rather than pure manufacturing scale.
- Pulp & Paper:Elemental-chlorine-free bleaching via chlorine dioxide generation consumes the majority of North American sodium chlorate volume. Southeastern integrated mills anchor demand, with Canadian kraft producers running captive chlorate operations through Great Lakes shipping corridors. EPA effluent guideline tightening is forcing secondary treatment investments that preserve chlorate throughput.
- Water Treatment:Advanced oxidation process deployment for emerging contaminant removal under Safe Drinking Water Act mandates. Mid-sized municipalities across the Ohio River valley are expanding installation, with chlorate-derived oxidation gaining share against permanganate alternatives.
- Herbicides:Defoliant and desiccant formulations for cotton and potato cultivation. Agricultural chemical blenders in the Texas Panhandle and Central Valley of California drive seasonal procurement patterns.
- Bleaching Agents:Textile and specialized industrial oxidation applications outside pulp processing. Niche demand concentrates at denim finishing facilities in North Carolina and Mexico border maquiladoras.
Pulp & Paper commands established volume. Water Treatment is climbing the fastest.
End User:
Procurement sophistication diverges sharply between integrated chemical producers and municipal buyers navigating federal compliance frameworks.
- Paper Manufacturers:Bleach plant operators with chlorine dioxide generators negotiate long-term offtake agreements directly with chlor-alkali suppliers. Direct mill procurement is displacing distributor intermediation across Canadian and US southeastern networks.
- Chemical Producers:Formulators of herbicide and specialty oxidation products requiring consistent chlorate specification. Multi-jurisdictional certification complexity creates documentation bottlenecks for cross-border shipments.
- Agricultural Sector:Seasonal buyers with price-sensitive procurement patterns and limited storage infrastructure. Distributor-mediated supply dominates due to fragmented farm-scale demand.
- Municipalities:Water treatment authorities adopting advanced oxidation under EPA mandate pressure. Technical expertise gaps slow deployment outside major metropolitan utilities.
Paper Manufacturers represent entrenched demand. Municipalities are gaining share fastest.
Distribution Channel:
Channel selection reflects shipment hazard classification constraints and customer scale rather than convenience preferences.
- Direct Sales:Long-term contracts between integrated chlor-alkali producers and high-volume bleach plant operators. Dedicated oxidizer railcar fleets are expanding across the Mississippi basin to serve this channel.
- Distributors:Regional chemical handlers managing smaller lot sizes and seasonal agricultural demand. Inventory positioning near herbicide blending facilities in the Central Valley and Texas Panhandle.
- Online Sales:Limited to laboratory-scale quantities and reagent-grade material. Regulatory documentation requirements constrain expansion.
- Retail:Minimal presence restricted to consumer herbicide products with diluted chlorate content. Big-box agricultural supply in rural markets.
Direct Sales anchors volume flows. Online Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp and paper concentration along the southeastern United States and Great Lakes corridors anchors sodium chlorate demand across North America. EPA effluent guidelines and Health Canada perchlorate thresholds reshape cross-border procurement patterns. Transport corridors and captive chlor-alkali integration determine delivered cost economics.
United States
Southeastern integrated kraft mills in Georgia and Alabama drive chlorine dioxide consumption for EPA Cluster Rule compliance. The EPA's revised effluent limitation guidelines tighten chlorate discharge thresholds, forcing bleach plant operators toward higher-purity technical grades. Dedicated oxidizer railcar fleets now bypass traditional distributor markups across the Mississippi basin.
Canada
Great Lakes shipping corridors enable captive sodium chlorate production tied to integrated chlor-alkali facilities serving Ontario and Quebec kraft mills. Health Canada and PMRA coordinate cross-border standards for herbicide residues and drinking water chlorate thresholds. Nouryon leverages its integrated network to sustain cost-advantaged supply to Canadian pulp producers.
Mexico
Border maquiladoras in Tamaulipas and Coahuila absorb niche textile bleaching demand outside pulp applications. Mexico's national water authority enforces emerging contaminant standards that parallel Safe Drinking Water Act frameworks. Chemical distributors in Monterrey manage cross-border oxidizer shipments under US DOT and Mexican transport classification rules.
North America Sodium Chlorate Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated chlor-alkali producers commanding direct mill relationships while regional distributors handle fragmented agricultural demand. The vendor base concentrates around three strategic archetypes: captive producers with backward integration into brine electrolysis, merchant suppliers with dedicated oxidizer logistics networks, and diversified chemical conglomerates with peroxygens co-marketing capabilities. Dominant competitive moves include long-term offtake contracting with high-volume bleach plant operators and rail distribution investments across the Mississippi basin.
Among integrated chlor-alkali specialists, Nouryon and ERCO Worldwide occupy positions exemplifying captive production economics tied to Great Lakes shipping corridors. Kemira represents the peroxygens co-marketing archetype, bundling sodium chlorate with hydrogen peroxide formulations to capture integrated pulp mill procurement consolidation. These three anchors illustrate how supply chain configuration and regulatory chemistry expertise determine competitive positioning.
| Leading Market Players |
|---|
| Nouryon |
| AkzoNobel |
| ERCO Worldwide |
| DuPont de Nemours Inc |
| Occidental Petroleum Corp |
| Chemtrade |
| Kemira |
| Arkema |
| Olin Corporation |
| Others |
Cost & Logistics Intelligence
Membrane electrolysis retrofits across existing undivided cell infrastructure simultaneously compress specific energy consumption per metric ton and concentrate production economics at integrated chlor-alkali sites with captive brine access. This dual effect reshapes how technical-grade sodium chlorate is priced against merchant supply in the southeastern United States and Great Lakes corridors.
Pricing Analysis
The volume-versus-margin split separates high-tonnage pulp mill offtake from specialty-grade premiums. Contract-based long-term offtake agreements dominate direct mill procurement, with price differentiation resting on chlorate purity grade and volume scale. Cost compression in technical-grade material is intensifying because EPA effluent guidelines force secondary treatment investments. Agricultural blenders exhibit highest price sensitivity due to seasonal demand patterns, while pharmaceutical-grade buyers show lowest sensitivity given USP monograph compliance requirements.
Supply Chain Analysis
Regional distribution centers near herbicide blending facilities in the Texas Panhandle and Central Valley of California manage seasonal inventory positioning for industrial-grade material. Supply concentrates in the United States and Canada, with captive production drawing from sodium chloride brine, electricity, and membrane cell technology inputs. Single-source vulnerability runs through Great Lakes shipping corridors where winter ice conditions constrain logistics. Distribution runs through dedicated oxidizer railcar fleets serving direct mill contracts across the Mississippi basin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over chlor-alkali feedstock and captive bleach plant economics determines competitive survival. Players are pursuing upstream brine electrolysis capacity as the decisive lever.
For Market Incumbents: Cement long-term offtake agreements with southeastern US kraft mills before EPA Cluster Rule compliance deadlines harden procurement consolidation. Lock in membrane cell technology upgrades to defend against carbon pricing exposure and peroxygens substitution threats.
For New Entrants and Emerging Players: Regional chemical distributors represent the most accessible channel partner type for penetrating fragmented agricultural demand in the Mississippi basin. Target mid-sized municipalities adopting advanced oxidation processes under Safe Drinking Water Act mandates, leveraging technical expertise partnerships with municipal engineering consultants as the go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated chlor-alkali conglomerates seeking captive sodium chlorate capacity. Long-term viability favors producers with backward integration into brine electrolysis and Great Lakes logistics access. Watch for divergence between EPA and Health Canada perchlorate screening levels as the inflection signal reshaping purification investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Electrolysis | Captive sodium chloride supply insulates Nouryon and ERCO from merchant brine price volatility. |
| Membrane Cell Technology Upgrade | Specific energy reduction per metric ton hedges carbon pricing exposure for Great Lakes producers. |
| Long-term Supply Agreement with Pulp Mills | Direct mill contracts across Georgia and Alabama bypass distributor markups and secure volume. |
| Peroxygens Co-Marketing Partnership | Bundling sodium chlorate with hydrogen peroxide captures procurement consolidation at integrated kraft mills. |
| Dedicated Oxidizer Railcar Fleet Expansion | Rail distribution innovation across the Mississippi basin reduces delivered cost to bleach plant operators. |
Research Approach
Trade databases, SEC 10-K filings, and American Chemistry Council reports formed the secondary backbone, cross-referenced against primary interviews with chlor-alkali plant managers, pulp mill procurement leads, herbicide formulators, and municipal water treatment engineers. Bottom-up and top-down triangulation validated volume estimates across technical and industrial grade segments.
Analytical lenses alternated between bottom-up electrolysis capacity modeling and top-down pulp industry chlorine dioxide consumption patterns across the projection horizon. Segmentation dimensions included grade tier, end-use industry, and regional production hub. CAGRs derived from electrolytic energy cost trajectories and EPA regulatory enforcement timelines.
Caveats apply where EPA effluent guideline revisions or Health Canada perchlorate threshold adjustments could materially shift the outlook for technical-grade demand. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Methyl Cyclohexane Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market