
 2-Nitrothiophene Market | 2026-2036
2-Nitrothiophene Market Size, Share, and Industry Trends Forecast 2026-2036
2-Nitrothiophene Market Outlook
Pharmaceutical-grade specification is rotating toward higher-purity thresholds as downstream API manufacturers tighten incoming raw material qualification. TCI Chemicals leverages its Japan-based synthesis infrastructure to dominate high-lot-consistency supply for Asian pharmaceutical contract manufacturers. Merck KGaA sustains European demand through its integrated quality management and REACH-compliant documentation systems. Thermo Fisher Scientific anchors North American distribution through channel control over research-grade volumes.
2-Nitrothiophene is a nitro-substituted heterocyclic compound with the molecular formula C4H3NO2S, synthesized primarily through electrophilic aromatic substitution of thiophene using mixed acid nitration; it serves as a versatile building block for thiophene-derived pharmaceuticals, dyes, and organic semiconductors. The reagent segment leads value contribution due to precision requirements in pharmaceutical route scouting, while the catalyst segment registers the fastest structural expansion as agrochemical formulators adopt thiophene-based coupling chemistry. Crystalline form commands margin concentration because purification and polymorph control differentiate suppliers for GMP-regulated buyers.
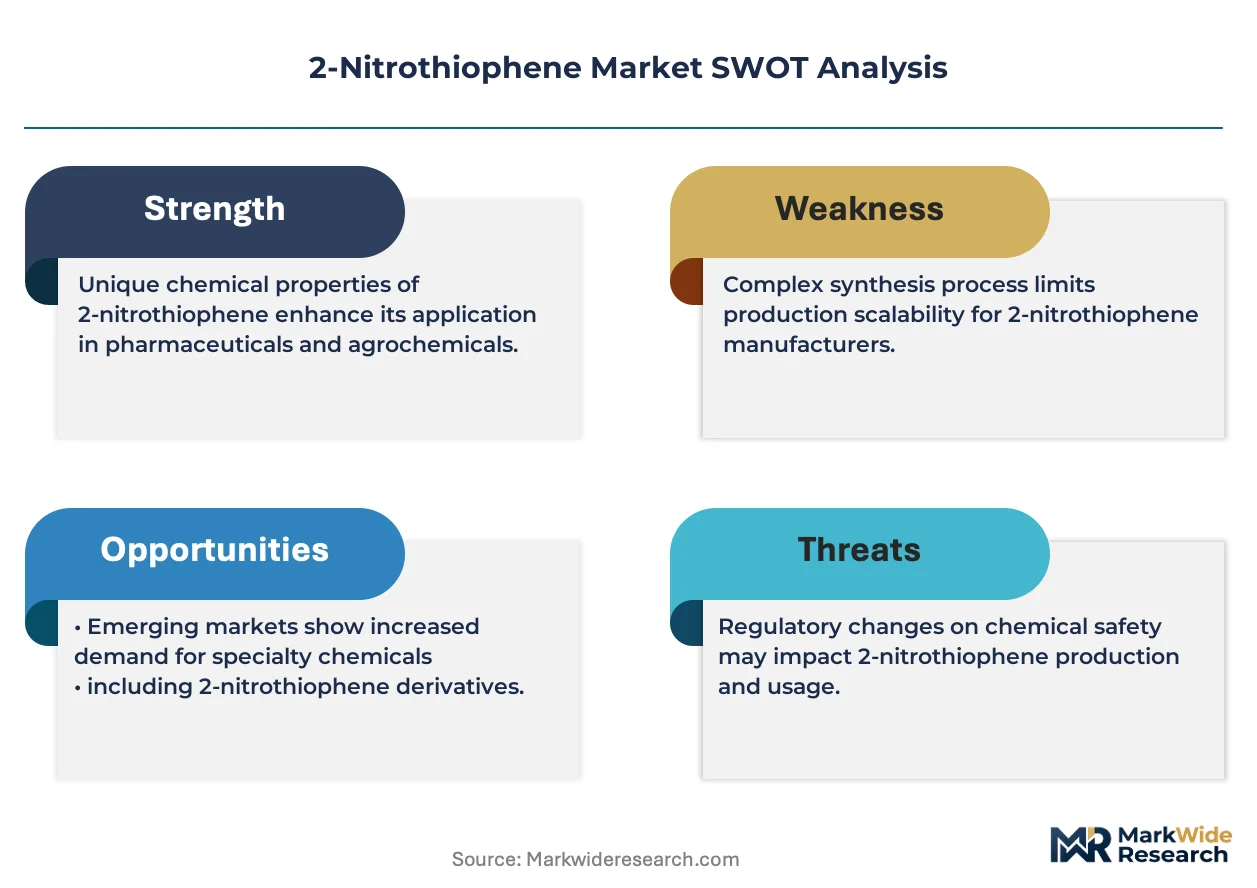
REACH registration obligations in Europe, EPA Toxic Substances Control Act reporting in the United States, and Japan's Chemical Substances Control Law collectively elevate compliance costs and favor incumbent suppliers with established dossier capabilities. ISO 17025 accreditation and ICH Q7 compliance now function as baseline market access filters rather than competitive differentiators. Stakeholders must monitor evolving PFAS-analog regulatory scrutiny, as thiophene ring structures face emerging classification reviews that could reshape raw material qualification protocols across pharmaceutical and agrochemical value chains.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing supplier margins while simultaneously elevating barriers to entry, as GMP certification and ICH Q7 compliance become non-negotiable baseline qualifications rather than competitive differentiators.
Growth Catalysts
- REACH dossier completion:European incumbent suppliers with pre-registered substances capture procurement from API manufacturers seeking compliant raw material streams without regulatory lag.
- Thiophene coupling chemistry:Agrochemical formulators adopt novel C-H activation protocols that expand 2-nitrothiophene utility beyond traditional nitration pathways.
- Japan:METI-supported specialty chemical clusters concentrate GMP-certified production capacity, anchoring regional pharmaceutical contract manufacturing demand.
Market Restraints
- Concentrated nitration feedstock supply:Thiophene precursor availability tightens around German and Chinese petrochemical corridors, exposing buyers to input volatility.
- PFAS-analog scrutiny:ECHA's emerging classification reviews of sulfur-heterocycle structures threaten raw material qualification protocols across pharmaceutical value chains.
- Electrophilic substitution yield ceilings:Mixed acid nitration chemistry faces inherent selectivity limits that constrain batch efficiency and waste reduction.
Strategic Opportunities
- India:CDSCO's accelerated API manufacturing incentives create procurement openings for REACH-compliant exporters serving domestic pharmaceutical expansion.
- Organic semiconductor deposition:Thiophene-derived small-molecule electronics integrate 2-nitrothiophene as functionalized building blocks for OFET and OPV applications.
- Direct-to-formulator digital channels:Specialty chemical platforms bypass traditional distributor markups for research-grade volumes in North American academic and CRO segments.
Industry Challenges
- ICH Q7 auditor scarcity:Qualified GMP inspection personnel concentrate at established certification bodies, extending qualification timelines for new production facilities.
- Polymorph control capex:Crystallization infrastructure investments for consistent polymorph delivery strain mid-cap supplier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Nitrothiophene Market |
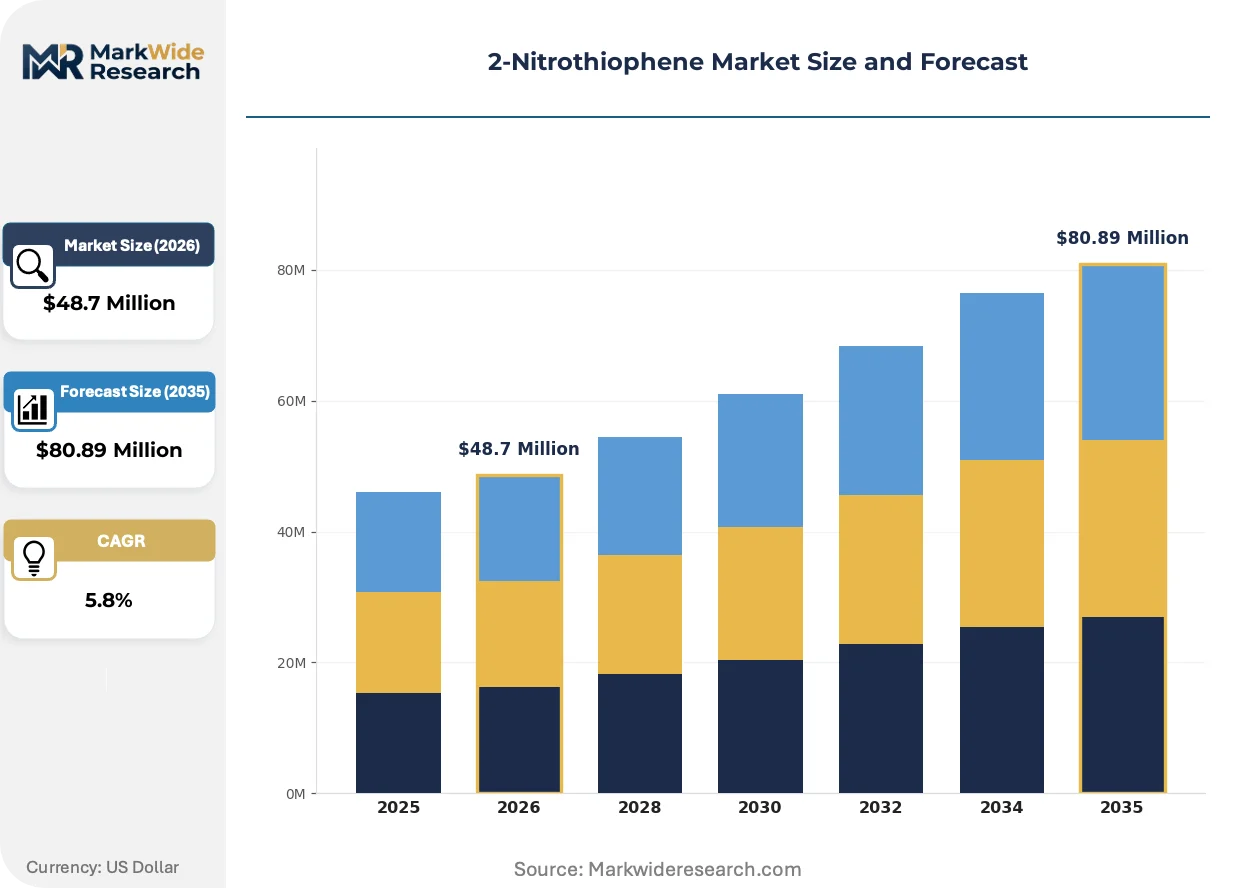
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $80.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Reagent, Stabilizer, Catalyst Application: Dyes, Pharmaceuticals, Agrochemicals, Material Science End User: Manufacturers, Lab Facilities, Research Institutions, Educational Institutions Form: Liquid, Powder, Crystalline, Granular |
| Companies Covered | TCI Chemicals, Spectrum Chemical Mfg. Corp., Merck KGaA, DOJINDO Laboratories, MedChemExpress, Thermo Fisher Scientific, Oakwood Chemical, Alfa Aesar, Toronto Research Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Nitrothiophene Market Strategic Shifts
Process intensification and regulatory data digitization are compressing development cycles while fragmenting traditional supply relationships across the 2-nitrothiophene value chain.
Continuous flow nitration reactors replace batch mixed-acid systems, enabling pharmaceutical manufacturers to tighten impurity profiles for high-potency API precursors. Specialty chemical engineering firms deploy skid-mounted units at customer sites, collapsing logistics exposure and qualification overhead. Modular synthesis hardware is miniaturizing production footprints while preserving GMP compliance for kilogram-scale pharmaceutical intermediate supply.
REACH Article 33 supply chain communication obligations now mandate granular substance disclosure down to 0.1% weight thresholds, forcing raw material suppliers to restructure documentation systems. ECHA's SCIP database requirements extend tracking obligations through article incorporation stages. European pharmaceutical formulators are consolidating qualified supplier lists to reduce compliance audit burden, privileging incumbent dossier holders.
Specification-driven procurement now dominates pharmaceutical raw material sourcing, with incoming material qualification protocols expanding from certificate-of-analysis review to full supply chain transparency. Large API manufacturers deploy dedicated supplier quality engineers at critical raw material sites, displacing arm's-length transactional relationships. Buyer engineering resource concentration is most pronounced in German and Japanese pharmaceutical manufacturing clusters where GMP enforcement remains stringent.
2-Nitrothiophene Market Segmentation
Channel configuration in 2-nitrothiophene distribution varies sharply by segment. Pharmaceutical intermediates flow through qualified supplier programs with full documentation chains, while research-grade volumes move through digital platforms and distributor networks.
Product Type:
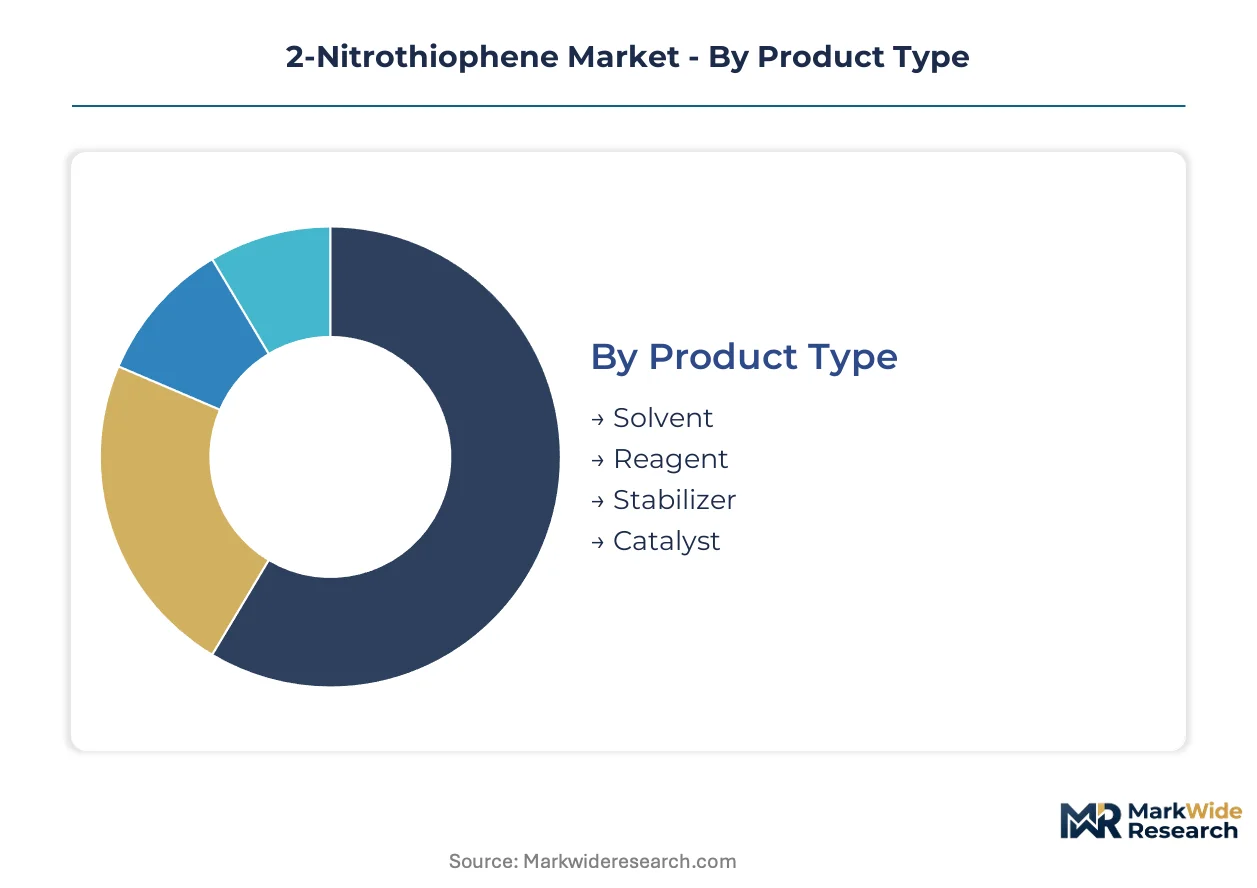
Reagent-grade volumes concentrate in direct manufacturer relationships, while catalyst and stabilizer grades route through specialty chemical distributors with technical support capabilities.
- Reagent:High-purity grade manufactured to ACS or comparable specifications for pharmaceutical route scouting and analytical method development. Demand concentrates at GMP-certified API manufacturers in Germany and Japan where incoming material qualification requires full regulatory dossiers. REACH-compliant documentation and ICH Q7 certificates function as baseline order qualifiers.
- Catalyst:Process-grade material enabling C-H activation and cross-coupling reactions in agrochemical synthesis. Expansion concentrates among formulators adopting thiophene-based coupling chemistry for novel fungicide and herbicide active ingredients, particularly where EPA registration timelines favor established synthetic pathways.
- Solvent:Technical-grade material used in extraction and reaction media for dye and pigment manufacturing.
- Stabilizer:Specialty additive grade employed in polymer and coating formulations requiring sulfur-heterocycle antioxidant properties.
Reagent dominates installed base. Catalyst is where expansion concentrates.
Application:
Cost tier stratification separates pharmaceutical-grade qualification requirements from technical-grade material specifications in dyes and agrochemicals.
- Pharmaceuticals:Intermediate for thiophene-derived APIs including antipsychotic and anti-inflammatory agents. Demand clusters at contract manufacturers serving innovator pharmaceutical companies with FDA and EMA filing obligations. Purity thresholds tighten continuously as ICH Q3D elemental impurity guidelines extend to raw material qualification.
- Agrochemicals:Building block for thiophene-based fungicides and plant growth regulators. Manufacturers in Japan leverage METI-supported specialty chemical infrastructure to supply domestic formulators with consistent lot-to-lot quality for field trial registration batches.
- Dyes:Precursor for sulfur-containing azo and anthraquinone colorants in textile and printing applications.
- Material Science:Functionalized building block for organic semiconductor small molecules in OFET and OPV device fabrication.
Pharmaceuticals commands premium pricing tiers. Material Science is climbing the fastest.
End User:
Customer type determines order minimums, documentation depth, and relationship structure across the value chain.
- Manufacturers:Industrial-scale consumers including API producers, agrochemical formulators, and dye manufacturers purchasing drum or tote quantities with established supply agreements. Procurement teams at German pharmaceutical manufacturers deploy dedicated supplier quality engineers at critical raw material sites.
- Lab Facilities:CROs and analytical service providers requiring gram to kilogram quantities with certificate-of-analysis documentation for method validation studies.
- Research Institutions:Academic chemistry departments and government laboratories sourcing through institutional purchasing contracts.
- Educational Institutions:Undergraduate teaching laboratories with basic purity requirements and minimal documentation needs.
Manufacturers anchor volume throughput. Lab Facilities is where specification-driven procurement is displacing transactional relationships.
Form:
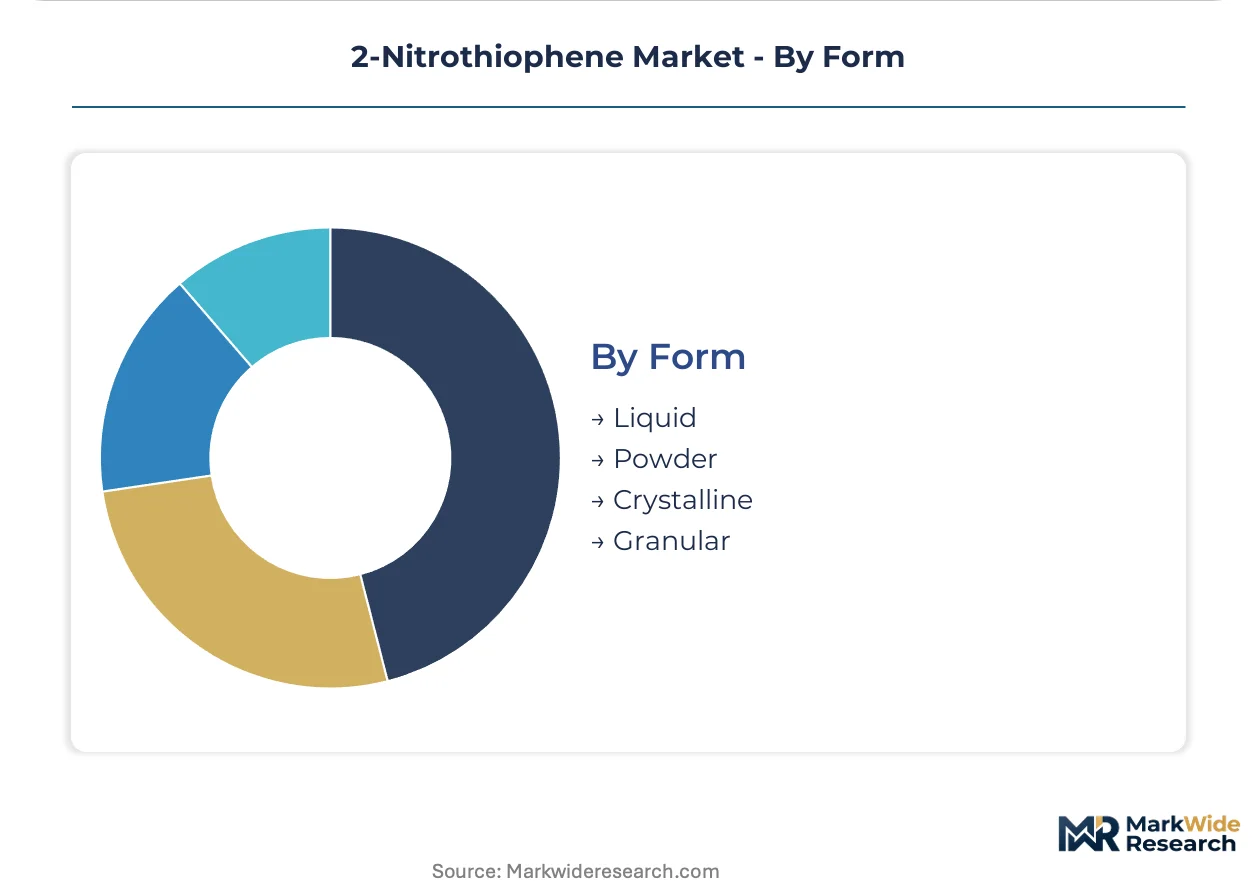
Margin concentration tracks purification intensity and polymorph control requirements, with crystalline forms commanding substantial premiums over bulk powder.
- Crystalline:High-purity solid with controlled polymorph and particle size distribution for pharmaceutical intermediate applications. Polymorph control capex requirements strain mid-cap supplier balance sheets, favoring incumbents with established crystallization infrastructure.
- Powder:Technical-grade solid for dye manufacturing and agrochemical synthesis where dissolution kinetics matter more than polymorph specificity.
- Liquid:Solution or melt form for direct feed into continuous flow reactors, gaining traction as pharmaceutical manufacturers adopt process intensification.
- Granular:Free-flowing solid form for automated handling in high-volume manufacturing environments.
Crystalline dominates margin capture. Liquid is gaining share fastest as continuous flow adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity, absorbing substantial premiums for GMP-certified material, whereas Indian and Chinese pharmaceutical manufacturers remain acutely sensitive to landed cost differentials despite tightening quality thresholds.
United States
API contract manufacturers in New Jersey and North Carolina drive reagent-grade procurement for antipsychotic intermediate synthesis. EPA Toxic Substances Control Act reporting obligations elevate compliance costs for non-domestic suppliers. The Research Triangle Park cluster anchors demand from CROs requiring certificate-of-analysis documentation for FDA filing support.
Germany
BASF and Merck KGaA's integrated supply chains consume crystalline-grade volumes for thiophene-derived active ingredient routes. REACH registration completion functions as a non-negotiable order qualifier, filtering out unprepared entrants. The Ludwigshafen chemical corridor concentrates GMP-audited production capacity serving EMA-regulated pharmaceutical formulators.
Japan
METI-supported specialty chemical infrastructure in Kanto and Osaka-Kobe sustains domestic agrochemical and pharmaceutical intermediate demand. PMDA filing requirements for novel drug substances propagate backward to raw material qualification protocols. The Kawasaki industrial zone hosts TCI Chemicals' synthesis facilities supplying Asian contract manufacturers with lot-consistent reagent grades.
India
CDSCO's accelerated API manufacturing incentives in Hyderabad and Ahmedabad create procurement openings for REACH-compliant exporters. Domestic formulators remain price-sensitive, compressing margins on technical-grade material while premium pharmaceutical grades command substantial markups. The Gujarat chemical belt concentrates import-dependent thiophene derivative processing capacity.
China
MIIT's dual carbon goals constrain nitration capacity expansion in Shandong and Jiangsu petrochemical corridors. NMPA's tightening pharmaceutical raw material documentation requirements are displacing non-compliant suppliers from innovator drug value chains. The Yangtze River Delta cluster anchors dye and agrochemical intermediate manufacturing with evolving environmental compliance burdens.
2-Nitrothiophene Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated multinationals commanding premium-tier pharmaceutical qualification while regional specialists capture technical-grade volume. The market structure fragments across three tiers: dossier-complete incumbents, GMP-certified mid-caps, and research-grade distributors. Japanese and German chemical conglomerates exemplify the integrated archetype, Indian and Chinese manufacturers occupy the scale-driven tier, and North American distributors anchor the research-grade channel. Dominant competitive moves include REACH dossier acquisition and crystallization infrastructure expansion.
Among Japan-based synthesis specialists, TCI Chemicals and DOJINDO Laboratories occupy positions within the high-lot-consistency tier serving Asian pharmaceutical contract manufacturers. Merck KGaA represents the integrated European archetype with REACH-compliant documentation systems. Thermo Fisher Scientific anchors North American distribution control over research-grade volumes. These three exemplify how geographic origin and corporate structure map to distinct competitive positioning within the qualification-stratified market.
| Leading Market Players |
|---|
| TCI Chemicals |
| Spectrum Chemical Mfg. Corp. |
| Merck KGaA |
| DOJINDO Laboratories |
| MedChemExpress |
| Thermo Fisher Scientific |
| Oakwood Chemical |
| Alfa Aesar |
| Toronto Research Chemicals |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory coverage at German pharmaceutical manufacturers anchors pricing power for crystalline-grade suppliers, compressing margins for spot-market sellers while rewarding REACH-compliant incumbents with long-term offtake premiums. Thiophene precursor availability concentrates around Ludwigshafen and Shandong corridors, translating feedstock volatility directly into reagent-grade price spreads.
Pricing Analysis
After-sales documentation revenue from ICH Q7 certificate renewals and REACH dossier updates drives lifetime value for incumbent suppliers. Three-tier pricing structure across GMP-certified, technical-grade, and research-grade levels stratifies the market, with certification tier and volume scale as primary differentiation levers. Cost compression in technical-grade material is intensifying because Indian formulators consolidate procurement around landed cost optimization. API manufacturers in Germany and Japan exhibit lowest price sensitivity, while Chinese dye producers remain most elastic.
Supply Chain Analysis
Strategic stockpile preferences dominate among Japanese pharmaceutical contract manufacturers, who maintain six-month crystalline-grade buffers against PMDA qualification delays. Supply concentrates in Germany, Japan, and China, with thiophene feedstock, mixed-acid nitration reagents, and GMP-audited crystallization capacity as critical inputs. Single-source vulnerability around TCI Chemicals' Kawasaki synthesis facilities threatens Asian reagent-grade availability. Distribution runs through qualified supplier programs for pharmaceutical volumes and digital platforms for research-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large API manufacturers as they consolidate qualified supplier lists to reduce compliance audit burden, privileging incumbent dossier holders with dedicated quality engineering relationships.
For Market Incumbents: Consolidate crystallization infrastructure investments and REACH dossier completeness to defend against emerging Indian CDSCO-compliant entrants. Backward integration into thiophene precursor supply secures margin control against German and Chinese petrochemical corridor volatility. Channel control over research-grade digital platforms preserves North American volume access. For New Entrants and Emerging Players: Lead with liquid-form continuous-flow compatibility to capture pharmaceutical process intensification demand in the United States and Germany. The most penetrable segment is research-grade CRO supply through direct-to-formulator digital channels. Technical support capabilities and rapid certificate-of-analysis turnaround function as the critical go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant REACH registrations and underutilized GMP crystallization assets. Long-term viability hinges on regulatory data digitization capabilities and SCIP database compliance infrastructure. Watch for ECHA PFAS-analog classification reviews as the inflection signal that would reshape raw material qualification protocols and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Acquisition | Captures procurement from API manufacturers seeking compliant raw material streams without regulatory lag. |
| Crystallization Infrastructure Expansion | Enables polymorph control for GMP-regulated buyers, differentiating suppliers in high-margin pharmaceutical tiers. |
| Continuous Flow Reactor Deployment | Supports pharmaceutical manufacturers adopting process intensification for high-potency API precursor synthesis. |
| Direct-to-Formulator Digital Channel | Bypasses distributor markups for research-grade volumes in North American academic and CRO segments. |
| Thiophene Precursor Backward Integration | Reduces exposure to German and Chinese petrochemical corridor volatility in concentrated nitration feedstock supply. |
Study Parameters
A standing panel of pharmaceutical procurement directors, agrochemical formulators, specialty chemical distributors, and GMP quality auditors provided ongoing calibration across primary interview rounds and secondary validation. Synthesis route chemists at contract manufacturing organizations and regulatory affairs specialists at REACH consultancy firms contributed technical perspective. Secondary sources included ECHA registration databases, CDSCO API manufacturing incentive filings, customs trade data for thiophene derivative flows, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled grade tier, end-use industry, form specification, and regional production hub as core segmentation dimensions. CAGRs were derived from segment-level growth rate reconciliation with aggregate market trajectory. Forecast inputs incorporated pharmaceutical pipeline progression for thiophene-derived APIs and agrochemical field trial registration timelines.
The analysis sits within stated boundaries; outcomes outside sustained REACH compliance cost structures or stable thiophene precursor availability would require recalibration. Forecasts reflect assumptions around regulatory enforcement intensity and GMP auditor capacity expansion. Revision becomes warranted when ECHA PFAS-analog classification reviews cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Europe Calcium Chloride Market