
 India Lime Market | 2026-2036
India Lime Market Size, Share, and Industry Trends Forecast 2026-2036
India Lime Market Foresight
Market Dynamics
Procurement from multiple regional quarries rather than single-source contracts is broadening supply resilience across northern and western India. Surya Corporation leverages captive limestone mines in Rajasthan to sustain cost-advantaged quicklime output. Shree Cement Ltd. anchors its lime position through backward integration into clinker-kiln operations. DCM Shriram Ltd. competes on hydrated lime purity grades for chemical manufacturing clients.
Product Landscape
Lime encompasses calcium oxide (quicklime) and calcium hydroxide (hydrated lime) produced by calcining limestone at temperatures exceeding 900 degrees Celsius, primarily serving as an alkalizing agent, flux, and binder across heavy industry. Quicklime dominates volume flows into steel desulfurization and construction mortar, while hydrated lime commands premium pricing in water treatment and environmental applications due to stricter effluent norms. Agricultural lime occupies a mature, price-sensitive niche tied to soil pH correction cycles in Punjab and Haryana.
Regulatory Environment
BIS certification requirements and CEA environmental clearances govern lime plant emissions and product quality for interstate commerce. The PLI scheme for critical minerals is channeling capital toward domestic calcination infrastructure, tightening compliance thresholds for particulate discharge and energy efficiency. Stakeholders must monitor state-level mining lease auctions and evolving MEE air quality mandates that could reshape cost structures for unintegrated producers.
Market Dynamics
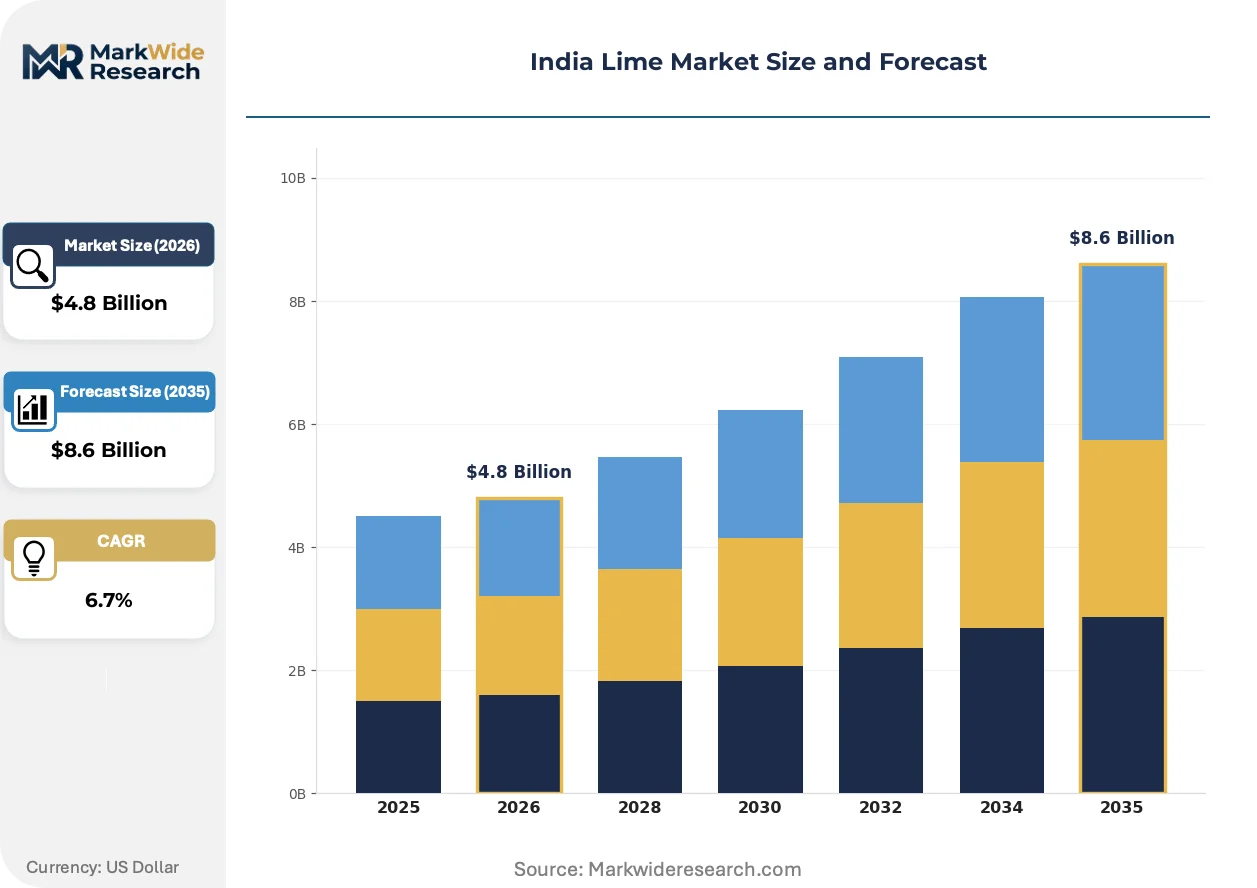
Construction material producers are scaling lime procurement for cement and steel applications, while BIS quality certification mandates and the PLI scheme for critical minerals tighten product standards and channel investment into domestic calcination capacity.
Growth Catalysts
- PLI Scheme for Critical Minerals:Production-linked incentives are accelerating capital deployment into domestic calcination infrastructure, reducing import dependency for high-purity quicklime used in steel desulfurization.
- Rajasthan Limestone Cluster:Concentrated high-grade reserves near the Delhi-Mumbai Industrial Corridor are shortening logistics loops for construction material producers.
- Steel Sector Expansion:Secondary steel producers are absorbing record volumes of metallurgical-grade quicklime as induction furnace capacity scales across western India.
Market Restraints
- Petcoke Price Volatility:Calcination energy costs swing with petroleum coke import tariffs, compressing margins for unintegrated producers lacking captive fuel supply.
- MEE Air Quality Mandates:Ministry of Environment and Forest particulate discharge thresholds are forcing kiln upgrades that strain working capital for mid-scale operators.
- Dolomitic Lime Substitution:Magnesium-bearing alternatives are displacing standard quicklime in select soil stabilization applications across Punjab's agricultural belt.
Strategic Opportunities
- Gujarat Chemical Corridor:Specialty hydrated lime grades for water treatment and effluent neutralization remain underpenetrated versus construction-grade volumes.
- CEA Environmental Clearances:Streamlined approval pathways for captive power integration are enabling energy-cost arbitrage for integrated cement-lime complexes.
- Digital Procurement Platforms:Aggregator marketplaces are disintermediating traditional mandi-based lime trading, compressing price discovery cycles for bulk industrial buyers.
Industry Challenges
- Kiln Operator Skill Scarcity:Experienced calcination technicians are concentrated among legacy producers, constrating capacity expansion timelines for new entrants.
- BIS Certification Timelines:Interstate commerce approvals for hydrated lime purity grades face 8-12 month validation windows, delaying market entry for specialty product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Lime Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrated Lime, Quick Lime, Burnt Lime, Agricultural Lime Application: Construction, Agriculture, Water Treatment, Chemical Manufacturing End User: Construction Industry, Agriculture Sector, Mining Companies, Environmental Agencies Distribution Channel: Direct Sales, Retail, Wholesale, Online Platforms |
| Companies Covered | Surya Corporation, Ankur Minerals Pvt. Ltd., Shree Cement Ltd., Dehradun Lime Stones, Gangotri Inorganic Private Limited, Sigma Minerals Ltd., Hindustan Lime Corporation, Rajasthan Lime Udhyog, DCM Shriram Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Lime Market Shifts & Advancements
Technology convergence and regulatory tightening are compressing the cost-quality frontier across India's lime value chain, with digitization and environmental compliance emerging as the primary axes of competitive differentiation.
Advanced process control systems integrating real-time kiln temperature monitoring with automated fuel feed adjustment are unifying quality consistency across batch operations. Large cement producers with captive lime units are deploying these systems fastest, compressing the yield gap between integrated and standalone calcination facilities.
BIS certification requirements for quicklime reactivity and hydrated lime purity are hardening technical barriers to interstate commerce. The standards are forcing regional producers to upgrade laboratory infrastructure, with Rajasthan and Gujarat facilities investing in X-ray fluorescence analyzers to maintain compliance documentation.
Long-term offtake agreements are displacing spot-market purchasing for steel and construction sector buyers. This contract concentration is compressing working capital cycles for integrated producers while squeezing margin flexibility for traders dependent on mandi price arbitrage across northern India.
India Lime Market Segmentation
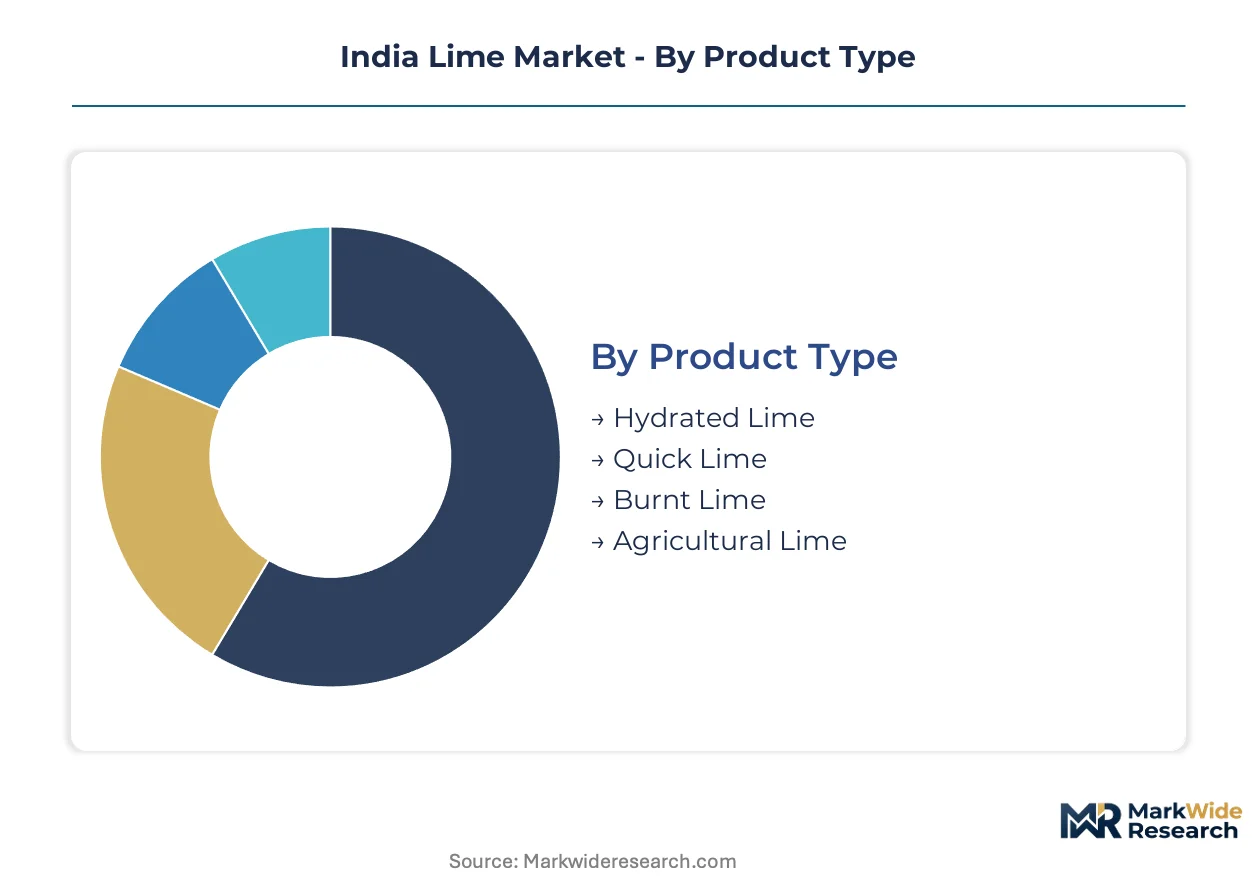
India's lime market fragments across product chemistry, application intensity, and procurement channel maturity. Understanding these splits reveals where margin pools concentrate versus where volume flows dominate.
Product Type:
Volume flows concentrate in basic calcination outputs, while premium pricing attaches to controlled reactivity and purity grades.
- Quick Lime:Calcium oxide produced through high-temperature limestone calcination above 900 degrees Celsius. Steel desulfurization operations across western India absorb the largest volumes as induction furnace capacity scales in Gujarat and Maharashtra.
- Hydrated Lime:Calcium hydroxide formed through controlled slaking of quicklime with precise water addition. Water treatment utilities in Rajasthan and Gujarat pay premium pricing for high-purity grades meeting BIS reactivity specifications under tightening MEE effluent mandates.
- Burnt Lime:Traditional kiln output with variable reactivity used in legacy construction mortar applications. Rural infrastructure projects in Madhya Pradesh and Uttar Pradesh maintain steady offtake despite quality inconsistency.
- Agricultural Lime:Finely ground limestone or dolomitic material for soil pH correction. Punjab and Haryana farming cooperatives purchase seasonally during pre-sowing windows, making this the most price-sensitive product tier.
Mature deployment sits with Quick Lime across established steel and cement corridors. Newer deployment is concentrated in Hydrated Lime as environmental compliance tightens effluent treatment standards.
Application:
Construction absorbs raw volume tonnage while chemical and environmental applications capture value-added pricing.
- Construction:Lime serves as a binder in masonry mortar, plaster, and soil stabilization for road projects. The Delhi-Mumbai Industrial Corridor infrastructure buildout sustains bulk procurement from Rajasthan quarry clusters.
- Water Treatment:Hydrated lime neutralizes acidic effluent and precipitates heavy metals in municipal and industrial wastewater systems. Gujarat's chemical corridor municipalities are upgrading treatment capacity fastest under state pollution control mandates.
- Agriculture:Soil amendment applications dominate in wheat-rice rotation belts where alkalinity correction improves fertilizer uptake efficiency. Cooperative procurement aggregates smallholder demand in Haryana's grain belt.
- Chemical Manufacturing:High-purity grades feed calcium carbide, bleaching powder, and citric acid production. Specialty chemical producers in Maharashtra and Gujarat specify low-magnesium content for process consistency.
Volume leadership rests with Construction. Steepest expansion trajectory belongs to Water Treatment as municipal infrastructure spending accelerates.
End User:
Procurement sophistication varies sharply between institutional buyers with laboratory specifications and fragmented agricultural demand.
- Construction Industry:Cement producers, ready-mix concrete operators, and road contractors purchase through annual contracts with integrated lime-cement complexes. Shree Cement and similar backward-integrated players dominate this channel.
- Mining Companies:Metallurgical quicklime for gold and copper ore flotation and pH control in heap leaching operations. Rajasthan's zinc and copper belt generates concentrated demand from Hindustan Zinc and Hindustan Copper operations.
- Environmental Agencies:Municipal corporations and state pollution control boards specify hydrated lime for sewage treatment and flue gas desulfurization. Gujarat Urban Development Mission projects represent emerging tender volumes.
- Agriculture Sector:Fragmented smallholder and cooperative demand with minimal quality differentiation. Mandi-based traders aggregate seasonal purchases across Punjab, Haryana, and western Uttar Pradesh.
Contract discipline is strongest with Construction Industry buyers. Spot-market volatility concentrates in Agriculture Sector procurement.
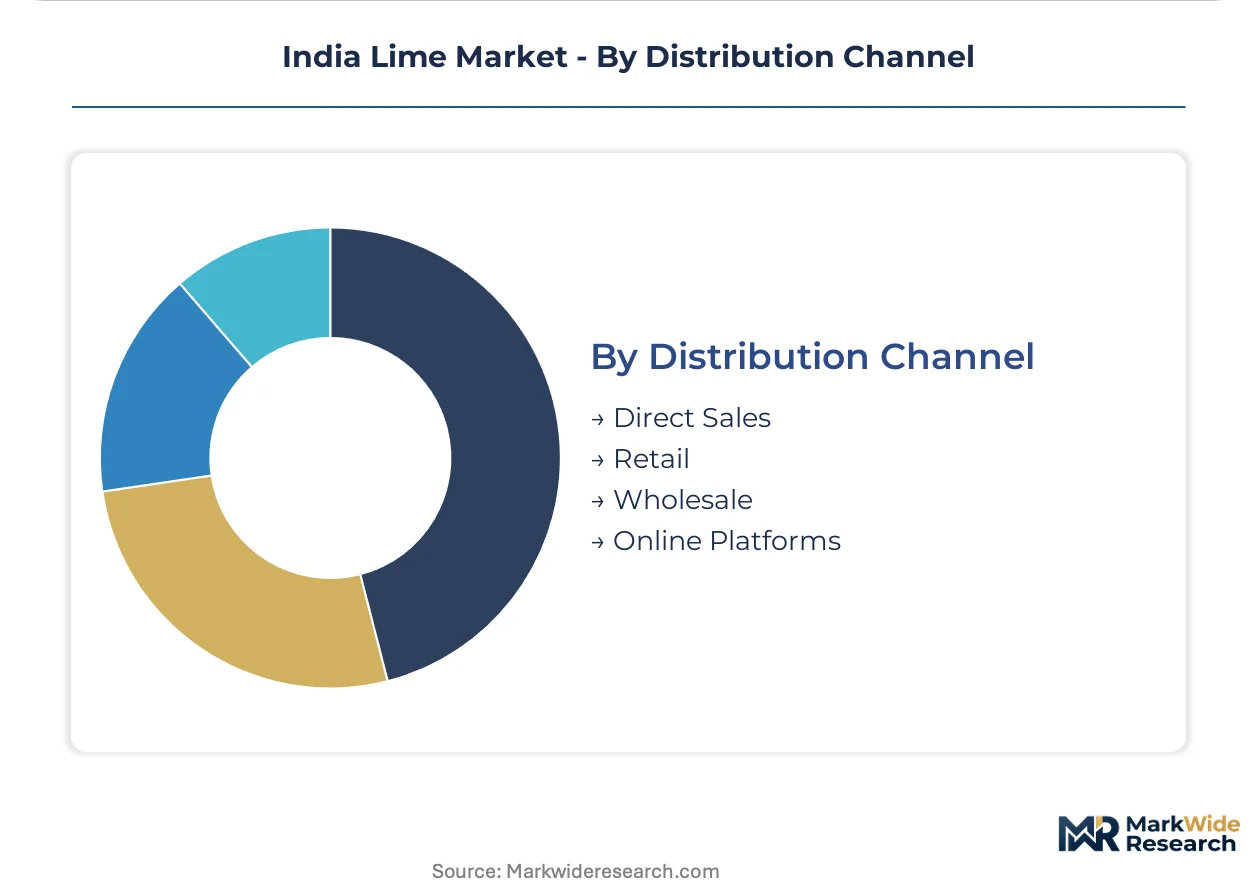
Distribution Channel:
Channel selection tracks buyer scale and specification complexity, with digital intermediaries compressing traditional trader margins.
- Direct Sales:Long-term offtake agreements between calcination plants and steel, cement, or chemical manufacturers. Surya Corporation and DCM Shriram leverage captive mine access to lock in annual volumes with price escalation clauses.
- Wholesale:Regional distributors aggregating construction-grade material for mid-scale contractors and agricultural cooperatives. Rajasthan and Gujarat wholesale hubs maintain inventory buffers against monsoon logistics disruptions.
- Retail:Small-lot sales through building material suppliers for rural construction and household agriculture. Price transparency remains lowest in this channel due to fragmented buyer power.
- Online Platforms:Emerging B2B aggregators connecting bulk buyers with multiple quarry sources. Digital procurement is gaining fastest among secondary steel producers seeking price discovery across Rajasthan supply bases.
Established volume flows through Direct Sales. Channel experimentation is most active in Online Platforms as industrial procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone reserves cluster in Rajasthan and Gujarat anchor India's lime production geography, with calcination capacity concentrating near the Delhi-Mumbai Industrial Corridor to minimize logistics friction for construction and steel buyers.
Rajasthan
Jodhpur and Jaisalmer districts host high-calcium limestone belts feeding steel desulfurization and cement clinker operations. BIS certification mandates for quicklime reactivity grades are forcing laboratory upgrades among mid-scale calciners. The Nagaur-Ajmer industrial corridor is attracting PLI-linked investment into captive calcination units serving secondary steel producers.
Gujarat
Surat and Vadodara chemical manufacturers absorb premium hydrated lime grades for effluent neutralization under tightening MEE discharge norms. The state's pollution control board is accelerating municipal sewage treatment tenders that specify BIS-compliant hydrated lime. Dahej and Hazira industrial zones are emerging as procurement hubs for water treatment utilities.
Maharashtra
Mumbai-Pune construction corridors sustain bulk quicklime offtake for ready-mix concrete and soil stabilization projects. The state's urban development department is mandating lime-based mortar specifications for heritage restoration contracts. Nagpur's mining belt generates metallurgical lime demand for manganese and iron ore processing operations.
Haryana
Hisar and Karnal agricultural cooperatives drive seasonal lime procurement for wheat-rice rotation soil amendment. The state agriculture department is subsidizing soil health card recommendations that specify calcium carbonate application rates. Panipat's textile cluster is absorbing hydrated lime for effluent treatment as zero-liquid-discharge mandates tighten.
Madhya Pradesh
Rewa and Satna limestone deposits supply variable-reactivity burnt lime for rural road construction and brick kiln operations. The state's public works department is consolidating lime procurement through centralized tenders for Pradhan Mantri Gram Sadak Yojana projects. Gwalior's emerging industrial area is testing quicklime for fly ash stabilization in pavement base courses.
India Lime Market Competitive Landscape
Global majors compete with regional champions across calcination technology and captive raw material access, producing a tiered structure where integrated cement-lime complexes hold cost advantages over standalone operators. The vendor base separates into three archetypes: backward-integrated cement producers with captive kilns, independent calciners controlling quarry leases, and trading houses aggregating mandi volumes. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, with digitization of procurement emerging as a secondary battleground.
Among integrated cement-lime operators, Shree Cement Ltd. and DCM Shriram Ltd. exemplify the backward-integrated archetype leveraging clinker-kiln synergies. Independent specialists including Surya Corporation and Sigma Minerals Ltd. occupy positions anchored by captive Rajasthan limestone access. These company patterns illustrate how quarry control and kiln scale separate margin tiers in a market where BIS certification timelines create sticky customer relationships.
| Leading Market Players |
|---|
| Surya Corporation |
| Ankur Minerals Pvt. Ltd. |
| Shree Cement Ltd. |
| Dehradun Lime Stones |
| Gangotri Inorganic Private Limited |
| Sigma Minerals Ltd. |
| Hindustan Lime Corporation |
| Rajasthan Lime Udhyog |
| DCM Shriram Ltd. |
| Others |
Supply & Pricing Matrix
Petcoke import tariffs transmit directly through calcination cost structures, splitting the market between integrated cement-lime complexes with captive fuel supply and standalone operators exposed to spot energy markets. This fuel-cost bifurcation separates pricing tiers: steel desulfurization buyers with annual offtake contracts lock in volume discounts, while agricultural cooperatives in Punjab face spot-price volatility during seasonal procurement windows.
Pricing Analysis
Technical service bundling distinguishes premium hydrated lime contracts from unbundled construction-grade transactions. Three-tier pricing structure across BIS-certified premium grades, standard industrial quicklime, and variable-reactivity burnt lime for rural infrastructure dominates the market. Price differentiation rests on laboratory certification investment and kiln automation levels. Cost compression in standard-grade quicklime is intensifying because petcoke tariff swings squeeze unintegrated producers. Agricultural cooperatives exhibit highest price sensitivity, while water treatment utilities under MEE mandates accept premium pricing for guaranteed reactivity specifications.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for critical minerals are redirecting capital toward Rajasthan and Gujarat calcination capacity, reducing import dependency for metallurgical-grade quicklime. Supply concentrates in India, with limestone reserves clustering in Jodhpur-Jaisalmer belts and Surat-Vadodara chemical corridors. Raw material dependencies center on high-calcium limestone, petroleum coke for kiln fuel, and dolomitic substitutes threatening standard lime in soil applications. Single-source vulnerability haunts secondary steel producers lacking long-term quarry leases. Distribution runs through direct sales contracts for institutional buyers, wholesale hubs buffering monsoon disruptions, and emerging B2B platforms disintermediating mandi traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India lime market functions as a cost-of-compliance arena where BIS certification timelines and MEE air quality mandates erect eight-to-twelve month barriers that filter out undercapitalized entrants and reward laboratory-equipped incumbents.
For Market Incumbents: Anchor market position by accelerating captive limestone lease consolidation in Nagaur-Ajmer corridors before state mining auctions intensify competition. Defend against digital procurement platforms by embedding technical service teams within steel desulfurization operations, converting specification compliance into switching-cost moats. Prioritize kiln automation investment to compress yield gaps with integrated cement-lime complexes.
For New Entrants and Emerging Players: Specialty chemical manufacturers in Gujarat's Dahej-Hazira belt represent the most penetrable buyer archetype, as effluent neutralization demand outpaces local hydrated lime purity supply. Target municipal sewage treatment tenders under Gujarat Urban Development Mission projects, where BIS-compliant specification requirements are newly mandatory and incumbent capacity is constrained. Pursue toll-manufacturing partnerships with Rajasthan quarry leaseholders to bypass capital-intensive kiln construction.
For Investors and Strategic Acquirers: Accelerated state pollution control board tender issuance for flue gas desulfurization is the leading indicator that environmental-grade hydrated lime demand is crossing into sustained contract volumes. Position for five-to-ten year infrastructure buildout exposure by acquiring mid-scale calciners with existing BIS certification infrastructure and unexpired mining leases in Jodhpur district. Monitor PLI scheme disbursement velocity as the signal for domestic capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Limestone | Surya Corporation's Rajasthan mine access demonstrates sustained margin protection against quarry lease auction volatility. |
| Kiln Automation and Process Control Deployment | Real-time temperature monitoring systems unify quality consistency, compressing yield gaps between integrated and standalone facilities. |
| Long-term Offtake Contracting with Steel Producers | Annual volume agreements with induction furnace operators in western India lock in working capital predictability. |
| BIS Certification Infrastructure Investment | X-ray fluorescence analyzer deployment accelerates interstate commerce approval timelines for hydrated lime purity grades. |
| Digital Procurement Platform Partnership | B2B aggregator integration exposes secondary steel buyers to price discovery across multiple Rajasthan supply bases. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving calcination plant managers, steel procurement leads at secondary producers, chemical manufacturing R&D directors, and state pollution control board officials. BIS certification databases, CEA environmental clearance records, PLI scheme disbursement filings, and limestone mining lease auction documents supplied quantitative foundations. Bottom-up quarry capacity assessments and top-down steel sector lime consumption estimates were triangulated against construction material flow data.
Segment-level modeling tracked quicklime, hydrated lime, burnt lime, and agricultural lime across construction, water treatment, chemical manufacturing, and agriculture applications. End-user archetypes—integrated cement complexes, municipal environmental agencies, mining operations, and agricultural cooperatives—were modeled separately. CAGRs were derived from production capacity expansion timelines, steel desulfurization intensity trends, and effluent treatment infrastructure deployment schedules. Petcoke price volatility scenarios and MEE compliance cost assumptions fed sensitivity analysis.
Revisions become necessary when PLI scheme disbursement velocity shifts, state mining lease auction terms alter quarry access economics, or MEE particulate discharge thresholds tighten beyond modeled kiln upgrade cost assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Methionine Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Saudi Arabia Sodium Thiosulphate Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Global Dicyandiamide Market