
 North America Dimethyl Phosphate Market | 2026-2036
North America Dimethyl Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dimethyl Phosphate Market Insights
The capital-intensity divergence between integrated producers and specialty distributors is redrawing competitive boundaries in the North America Dimethyl Phosphate Market. Lanxess AG leverages its backward integration into phosphorus chemistry to sustain margin stability across flame retardant grades. Merck KGaA anchors its position through R&D intensity in high-purity intermediates for pharmaceutical applications.
Dimethyl phosphate is an organophosphorus ester with the formula (CH3O)2P(O)OH, typically manufactured through the reaction of phosphorus pentoxide with methanol followed by controlled hydrolysis, and functions primarily as a chemical intermediate, flame retardant additive, and solvent in industrial formulations. The flame retardants segment dominates value capture due to stringent building codes in North American construction, while the intermediates category leads volume growth through pharmaceutical and agrochemical contract manufacturing demand. Agricultural applications maintain steady offtake through bulk delivery channels serving corn and soybean belt formulators, though pharmaceuticals is displacing traditional outlets as the fastest-growing application by end-user margin.
EPA oversight of phosphorus compound emissions and OSHA workplace exposure limits are tightening purity and handling specifications across the value chain, while Health Canada and PMRA coordinate parallel regulatory reviews that affect cross-border product registration timelines for pesticide-grade material. State-level environmental regulations in California and Texas add layered compliance requirements that favor producers with in-house analytical and regulatory affairs capabilities. Stakeholders must monitor evolving phosphorus load restrictions in watershed regulations and position supply agreements around certified low-impurity grades before compliance windows narrow.
Market Dynamics
EPA phosphorus compound emission limits are compressing the viable producer base in the United States Gulf Coast corridor, forcing capital upgrades among legacy manufacturers while creating entry barriers for new market participants.
Growth Catalysts
- Flame Retardant Mandates:Stringent building codes across Texas and California construction markets are pulling dimethyl phosphate into polyurethane foam and epoxy formulations for commercial insulation systems.
- Pharmaceutical Contract Manufacturing:CDMOs serving oncology and antiviral API production in the Boston-Cambridge corridor are expanding high-purity intermediate offtake through multi-year supply agreements.
- Agrochemical Formulation Demand:Corn and soybean belt distributors in Illinois and Iowa are consolidating procurement volumes for organophosphate pesticide precursors ahead of planting season cycles.
Market Restraints
- Methanol Feedstock Volatility:Natural gas price swings affecting methanol production economics in the US Gulf Coast directly transmit to dimethyl phosphate manufacturing cost structures.
- Phosphorus Pentoxide Supply Concentration:Domestic merchant supply concentrates among three integrated phosphorus chemical producers, creating single-source vulnerability for non-integrated compounders.
- Substitution Pressure from Halogenated Retardants:Brominated alternatives in electronics casing applications are regaining cost competitiveness in price-sensitive consumer goods segments.
Strategic Opportunities
- Mexico Nearshoring Expansion:Automotive and appliance manufacturers in Querétaro and Nuevo León are qualifying North American-sourced flame retardants to replace Asian imports under USMCA tariff preferences.
- Bio-based Phosphorus Chemistry:Emerging pyrolysis routes from agricultural waste streams are opening pathways to certified renewable content grades for brand-owner sustainability commitments.
- California Toxicity Reporting Exemptions:Proposition 65 safe harbor thresholds for phosphorus esters are creating first-mover advantage for producers achieving sub-detectable impurity profiles.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Specialized phosphorus speciation expertise required for EPA compliance testing is concentrating among a shrinking pool of credentialed laboratory professionals.
- Multi-Jurisdictional Registration Timelines:Synchronized EPA-PMRA reviews for pesticide-grade material are extending product launch cycles by 18-24 months versus historical baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dimethyl Phosphate Market |
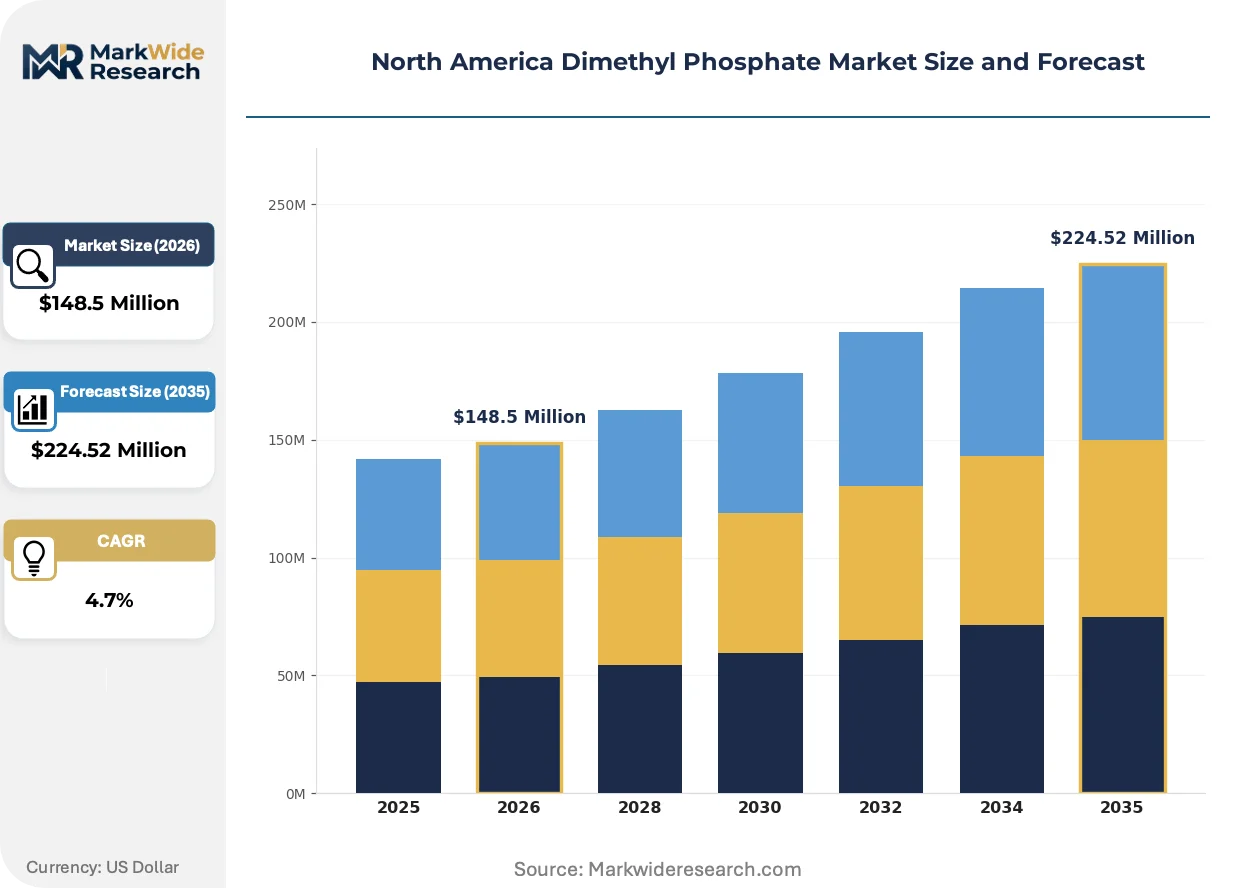
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $224.52 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Flame Retardants, Solvents, Intermediates Application: Agriculture, Pharmaceuticals, Chemical Manufacturing, Textiles End User: Farmers, Laboratories, Manufacturers, Distributors Delivery Mode: Bulk Delivery, Online Supply, Retail Distribution, Contract Services |
| Companies Covered | Fisher Scientific, AccuStandard, Inc., Merck KGaA, Lanxess AG, Toronto Research Chemicals, Alfa Chemistry, Biosynth, BLDpharm, Clearsynth, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dimethyl Phosphate Market Trends and Innovations
Process intensification and regulatory chemistry are reshaping how dimethyl phosphate is manufactured, tested, and specified across North American industrial value chains.
Continuous-flow microreactor technology for phosphorus ester synthesis is fragmenting the traditional batch-reactor economics that dominated Gulf Coast production. Pharmaceutical-grade manufacturers in New Jersey and Pennsylvania are piloting these systems to reduce solvent waste and thermal degradation byproducts. The shift is compressing minimum efficient scale thresholds and enabling distributed production closer to formulation sites.
EPA Tier III emission standards for phosphorus-containing compounds are tightening analytical detection limits from parts-per-million to parts-per-billion thresholds. Industrial buyers in construction materials are now requiring third-party certified low-emission grades ahead of formal compliance deadlines. Texas and California state environmental agencies are coordinating inspection protocols that favor producers with in-house ICP-MS capabilities.
Specification-driven procurement is consolidating buyer power among national distributors serving the agrochemical formulator base. Regional compounders in the Corn Belt are bypassing traditional merchant channels to negotiate direct toll-manufacturing arrangements with phosphorus chemical specialists. The pattern is most pronounced in Illinois and Ohio, where volume commitments now lock in three-year pricing with technical service bundling.
North America Dimethyl Phosphate Market Segmentation
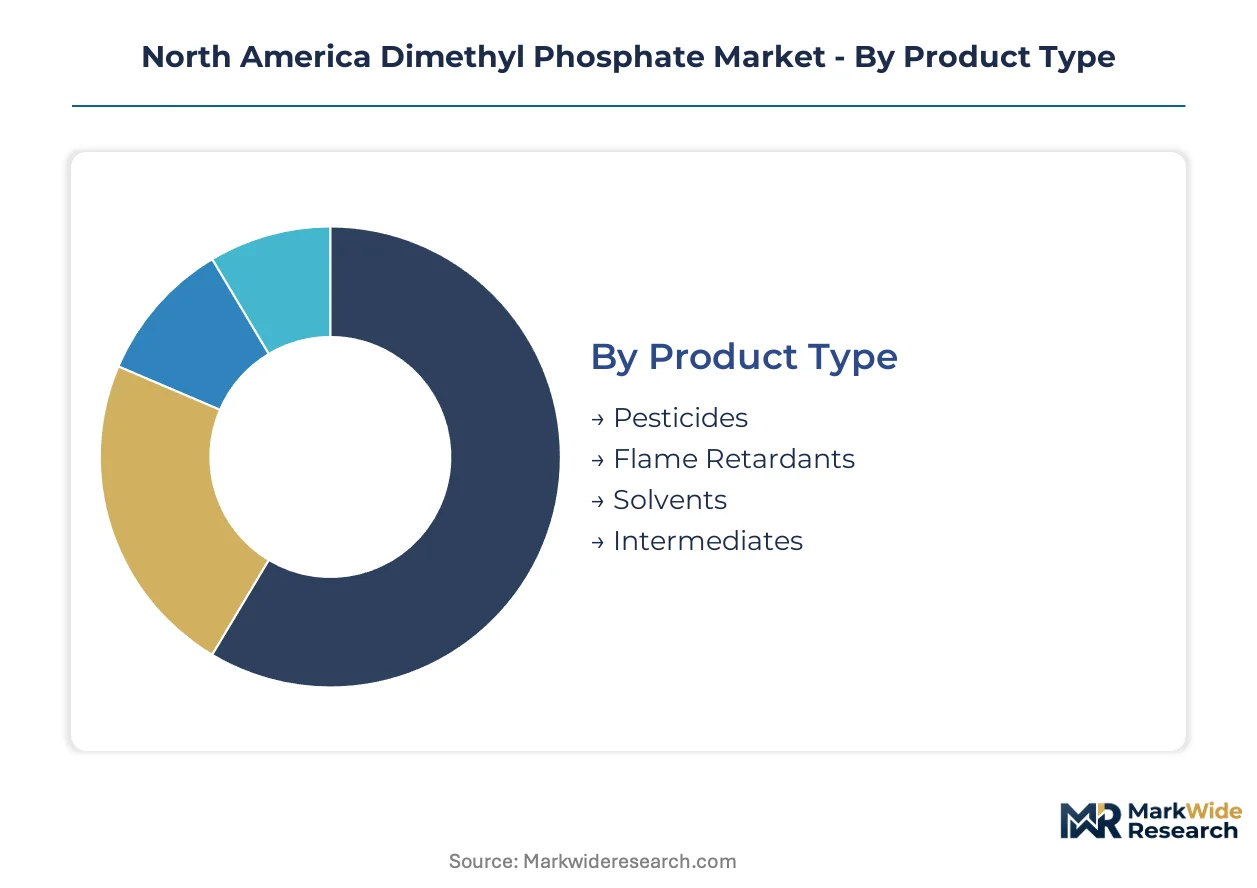
Dimethyl phosphate serves divergent performance requirements across North American industrial value chains. Specification purity, regulatory registration status, and delivery reliability separate premium-grade procurement from commodity offtake.
Product Type:
Flame retardant and intermediate grades dominate domestic manufacturing absorption, while pesticide and solvent categories concentrate in export-oriented production corridors.
- Flame Retardants:Halogen-free phosphorus ester formulations meeting NFPA 275 and California TB 117 standards for polyurethane foam and epoxy insulation systems. Demand concentrates in Texas and California construction markets where municipal building codes mandate phosphorus-based additives for commercial high-rise applications. EPA emission testing protocols are tightening purity specifications ahead of compliance windows.
- Intermediates:High-purity grades above 99.5% assay serving pharmaceutical API synthesis and agrochemical precursor manufacturing. CDMOs in the Boston-Cambridge corridor and Gulf Coast chemical clusters anchor procurement through multi-year supply agreements with technical service bundling.
- Pesticides:Organophosphate precursor compounds for corn and soybean belt formulators. Bulk delivery channels serve Illinois and Iowa distributors ahead of seasonal planting cycles.
- Solvents:Technical-grade material for industrial cleaning and extraction applications. Price-sensitive procurement patterns concentrate among regional compounders in Ohio and Pennsylvania.
Flame retardants command the established base. The steepest expansion runs through intermediates.
Application:
Margin structure varies sharply across end-use verticals, with pharmaceutical applications capturing premium pricing through certification requirements while agricultural offtake operates on volume-driven economics.
- Pharmaceuticals:Oncology and antiviral API manufacturing drives high-purity intermediate demand. FDA drug master file registration requirements and ICH Q3D elemental impurity guidelines enforce specification rigor that non-integrated producers cannot meet.
- Agriculture:Corn and soybean belt formulators in Illinois, Iowa, and Indiana consolidate procurement volumes for organophosphate pesticide precursors. PMRA-EPA synchronized registration timelines extend product launch cycles for new active ingredient introductions.
- Chemical Manufacturing:Toll manufacturing and custom synthesis operations across the Gulf Coast chemical corridor absorb technical-grade material for downstream phosphorus derivative production.
- Textiles:Flame retardant finishing for industrial fabrics and upholstery applications. California Proposition 65 safe harbor thresholds are displacing brominated alternatives in contract furniture specifications.
Agriculture anchors volume throughput. Pharmaceuticals delivers the strongest margin expansion trajectory.
End User:
Procurement sophistication separates institutional buyers with in-house analytical capabilities from price-sensitive intermediaries dependent on distributor technical support.
- Manufacturers:Integrated chemical producers and pharmaceutical CDMOs with captive phosphorus handling infrastructure. Direct toll-manufacturing arrangements bypass traditional merchant channels in Illinois and Ohio.
- Laboratories:R&D facilities and quality control operations requiring certified reference standards and small-batch high-purity grades. Procurement emphasizes lot traceability and certificate of analysis documentation.
- Farmers:End-use consumption through co-operative purchasing arrangements and regional distributor networks. Seasonal demand concentration creates working capital pressures for formulators.
- Distributors:National and regional chemical distributors consolidating volumes across agrochemical and specialty chemical portfolios. Specification-driven procurement is compressing supplier bases to producers with in-house regulatory affairs capabilities.
Manufacturers dominate value capture. Laboratories show the most rapid specification tightening.
Delivery Mode:
Supply chain configuration reflects hazard classification, volume scale, and customer technical service requirements across the value chain.
- Bulk Delivery:Railcar and tank truck shipments serving Gulf Coast chemical corridor manufacturers and Corn Belt agrochemical formulators. DOT hazardous materials regulations and EPA spill prevention requirements favor producers with dedicated logistics infrastructure.
- Contract Services:Toll manufacturing and dedicated supply agreements with technical service bundling. Three-year pricing locks are displacing spot market transactions in pharmaceutical and flame retardant procurement.
- Online Supply:E-commerce channels for laboratory-scale quantities and certified reference materials. Procurement emphasizes certificate of analysis availability and lot-specific documentation.
- Retail Distribution:Limited presence confined to agricultural co-operative channels and regional chemical supply houses serving small-scale formulators.
Bulk delivery commands the established base. Contract services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates along the United States Gulf Coast, where integrated phosphorus producers command premium positions, while Canadian and Mexican buyers absorb transport-cost penalties that compress margins for non-integrated distributors.
United States
Flame retardant procurement from Texas and California construction markets pulls dimethyl phosphate into polyurethane foam formulations. EPA Tier III emission standards tighten analytical detection limits for phosphorus compounds. Houston-Galveston chemical corridor manufacturers upgrade ICP-MS capabilities to meet compliance windows.
Canada
Pharmaceutical CDMOs in the Greater Toronto Area expand high-purity intermediate offtake for oncology API production. Health Canada coordinates PMRA-EPA synchronized reviews that extend pesticide-grade registration timelines. Montreal-based analytical laboratories face talent scarcity for phosphorus speciation expertise.
Mexico
Automotive and appliance manufacturers in Querétaro and Nuevo León qualify North American-sourced flame retardants under USMCA tariff preferences. Federal environmental regulations tighten wastewater phosphorus load restrictions. Monterrey industrial parks attract toll-manufacturing arrangements from Gulf Coast suppliers.
Gulf Coast Chemical Corridor
Downstream agrochemical and pharmaceutical manufacturing clusters anchor bulk delivery demand through railcar and tank truck channels. OSHA workplace exposure limits enforce handling specification upgrades. Louisiana and Texas state environmental agencies coordinate inspection protocols favoring producers with captive logistics infrastructure.
Corn Belt States
Illinois and Iowa agrochemical formulators consolidate procurement volumes for organophosphate pesticide precursors ahead of planting cycles. State-level nutrient management plans restrict phosphorus runoff into watersheds. Regional distributors in Ohio bypass merchant channels for direct toll-manufacturing contracts.
North America Dimethyl Phosphate Market Competitive Landscape
Concentration sits with integrated phosphorus chemical producers who control backward integration into phosphorus pentoxide and methanol feedstocks. The viable producer base compresses as EPA emission limits force capital upgrades among legacy manufacturers. Three strategic archetypes dominate: integrated multinational chemical conglomerates with captive phosphorus chemistry assets; specialty distributors with regulatory affairs capabilities; and pharmaceutical-grade manufacturers with FDA drug master file registrations. Competitive moves center on capacity expansion in low-emission production configurations and strategic partnerships with CDMOs for multi-year supply agreements.
Within the integrated chemical tier, Lanxess AG and Merck KGaA exemplify divergent positioning strategies. Lanxess AG represents the backward-integrated archetype with phosphorus chemistry assets sustaining margin stability across flame retardant grades. Merck KGaA occupies a position in high-purity pharmaceutical intermediates where R&D intensity and ICH Q3D compliance capabilities create specification barriers. Fisher Scientific anchors the distribution-focused segment with laboratory-scale channels and certificate-of-analysis documentation systems serving analytical chemistry procurement.
| Leading Market Players |
|---|
| Fisher Scientific |
| AccuStandard, Inc. |
| Merck KGaA |
| Lanxess AG |
| Toronto Research Chemicals |
| Alfa Chemistry |
| Biosynth |
| BLDpharm |
| Clearsynth |
| Others |
Pricing and Supply Chain Analysis
EPA Tier III emission standards for phosphorus-containing compounds gate both supplier qualification and price differentiation simultaneously. Producers investing in ICP-MS capabilities command premium positioning for certified low-emission grades, while non-compliant manufacturers face margin compression from restricted market access.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical grades from standard flame retardant tiers. Contract-based long-term offtake dominates procurement, with price differentiation resting on certification grade and volume scale. Cost compression in technical-grade solvents is intensifying because methanol feedstock volatility transmits directly to manufacturing economics. Agricultural formulators exhibit highest price sensitivity, while pharmaceutical CDMOs prioritize specification reliability over unit cost.
Supply Chain Analysis
Inbound logistics costs from Gulf Coast port congestion and container availability constraints on Asia-North America trade lanes elevate landed costs for phosphorus pentoxide imports. Supply concentrates in the United States, Canada, and Mexico under USMCA integration. The chain draws from phosphorus pentoxide, methanol, and hydrolysis catalyst feedstocks. Single-source vulnerability concentrates among three integrated phosphorus chemical producers. Distribution runs through bulk railcar and tank truck channels serving chemical corridor manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution pressure from halogenated flame retardants regaining cost competitiveness in electronics applications. Defense requires structural positioning against this substitute threat.
For Market Incumbents: Fortify backward integration into phosphorus pentoxide to secure margin stability against feedstock concentration risk. Expand ICP-MS analytical capabilities ahead of EPA detection limit tightening. Channel control through dedicated logistics infrastructure protects against toll-manufacturing disintermediation in the Corn Belt.
For New Entrants and Emerging Players: Lead with California Proposition 65 safe harbor compliance as a first-mover positioning lever. The most penetrable white space sits in bio-based phosphorus chemistry from agricultural waste pyrolysis routes. Target Querétaro and Nuevo León automotive manufacturers qualifying North American flame retardants under USMCA preferences.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty distributors lacking in-house regulatory affairs capabilities. Five-to-ten year viability hinges on EPA compliance infrastructure rather than commodity volume positioning. Watch for phosphorus load restriction tightening in watershed regulations as the inflection signal for certified low-impurity grade premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phosphorus pentoxide supply insulates margin stability from merchant market concentration. |
| ICP-MS Capability Expansion | In-house analytical chemistry meets EPA Tier III parts-per-billion detection thresholds ahead of compliance windows. |
| Long-term Supply Agreement | Multi-year contracts with Boston-Cambridge CDMOs lock in pharmaceutical-grade volume commitments. |
| Joint Venture | Monterrey toll-manufacturing partnerships capture USMCA tariff preferences for Querétaro appliance producers. |
| Green Manufacturing Transition | Agricultural waste pyrolysis routes open certified renewable content grades for brand-owner sustainability commitments. |
Research Methodology
A standing panel of plant managers at Gulf Coast phosphorus chemical facilities, procurement leads at downstream agrochemical formulators, distribution channel partners serving the Corn Belt, and technical R&D directors at pharmaceutical CDMOs provided ongoing calibration. Primary interview insights combined with secondary validation from EPA emission filings, customs trade data, SEC chemical sector disclosures, and ACC industry reports. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs derived from historical trajectory analysis and demand elasticity factors incorporated methanol price correlation coefficients and phosphorus pentoxide supply concentration indices as industry-specific inputs.
Forecasts assume regulatory continuity in EPA Tier III standards and Health Canada-PMRA synchronized review protocols; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Alkali Metal Hydroxides Market