
 Sodium Permanganate Market | 2026-2036
Sodium Permanganate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Permanganate Market Analytics
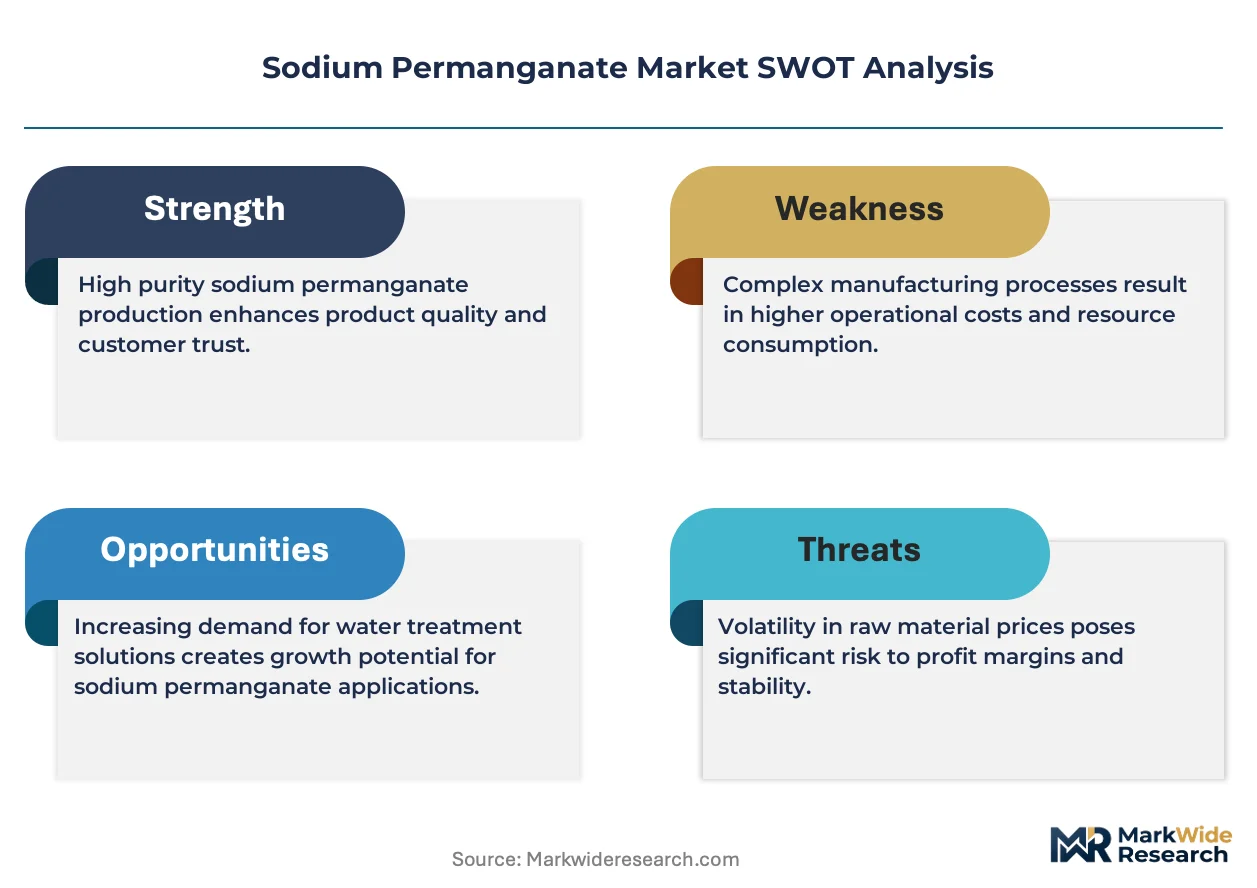
The price-performance gap between pharmaceutical-grade and industrial-grade sodium permanganate is hardening as purity specifications diverge across end-use sectors. Carus leverages its captive permanganate production chain to sustain cost advantages in North American water treatment. Chongqing Changyuan Chemical anchors supply for Asian textile bleaching operations, while Nippon Chemical differentiates through precision control of heavy-metal impurities for electronics-adjacent applications.
Sodium permanganate is an inorganic salt with the formula NaMnO₄, typically supplied as a deep purple aqueous solution containing approximately 40% active compound by weight, manufactured through electrolytic oxidation of sodium manganate or chemical conversion from potassium permanganate. The compound functions primarily as a selective oxidant in water pretreatment, organic synthesis, and surface preparation. Industrial grade commands volume leadership in municipal water treatment, where margin pools concentrate in long-term supply contracts. Pharmaceutical grade carries premium pricing due to compendial compliance burdens, while laboratory grade occupies a stable niche with limited supplier fragmentation.
EPA regulations under the Safe Drinking Water Act and OSHA permissible exposure limits govern handling, storage, and discharge thresholds for sodium permanganate in U.S. industrial settings. REACH registration requirements in Europe impose substance evaluation protocols that shape import access and formulation standards. Stakeholders must monitor evolving PFAS co-treatment protocols, as sodium permanganate's oxidation kinetics against fluorinated compounds will determine its competitive position against alternative advanced oxidation processes.
Market Dynamics
EPA's tightening limits on iron, manganese, and hydrogen sulfide in drinking water are forcing municipal utilities toward pre-oxidation chemistry upgrades. This regulatory compression is accelerating procurement cycles for sodium permanganate across aging U.S. distribution networks.
Growth Catalysts
- Safe Drinking Water Act amendments:Stricter maximum contaminant levels for secondary standards are mandating pre-treatment oxidation in small and medium municipal systems.
- PFAS co-treatment protocols:Pilot programs evaluating sodium permanganate's oxidation kinetics against fluorinated compounds are expanding its addressable application set.
- Electronics surface preparation:Semiconductor fabrication demand for ultra-pure oxidants with controlled heavy-metal specifications is opening premium-grade volume channels.
Market Restraints
- Manganese ore price volatility:Electrolytic production economics swing with raw material costs concentrated in South African and Gabonese supply.
- Permanganate production concentration:North American supply chains depend on a limited set of captive electrolytic oxidation facilities.
- Advanced oxidation process substitution:Ozonation and UV-hydrogen peroxide systems compete for pre-oxidation contracts in large-capacity municipal bids.
Strategic Opportunities
- Indian textile bleaching modernization:Water-intensive dyeing operations face central pollution control board discharge mandates that favor permanganate over chlorine-based alternatives.
- REACH registration completion:Full substance evaluation protocols for sodium permanganate will clarify import access rules and formulation standards across EU member states.
- On-site generation systems:Containerized electrolytic units are converging with remote mining camp and military base water treatment requirements.
Industry Challenges
- Electrolytic cell technician scarcity:Skilled operators for sodium manganate oxidation processes are concentrated at legacy production sites with limited training pipeline expansion.
- Compendial certification timelines:Pharmaceutical-grade qualification against USP and EP monographs requires 18-24 month stability validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Permanganate Market |
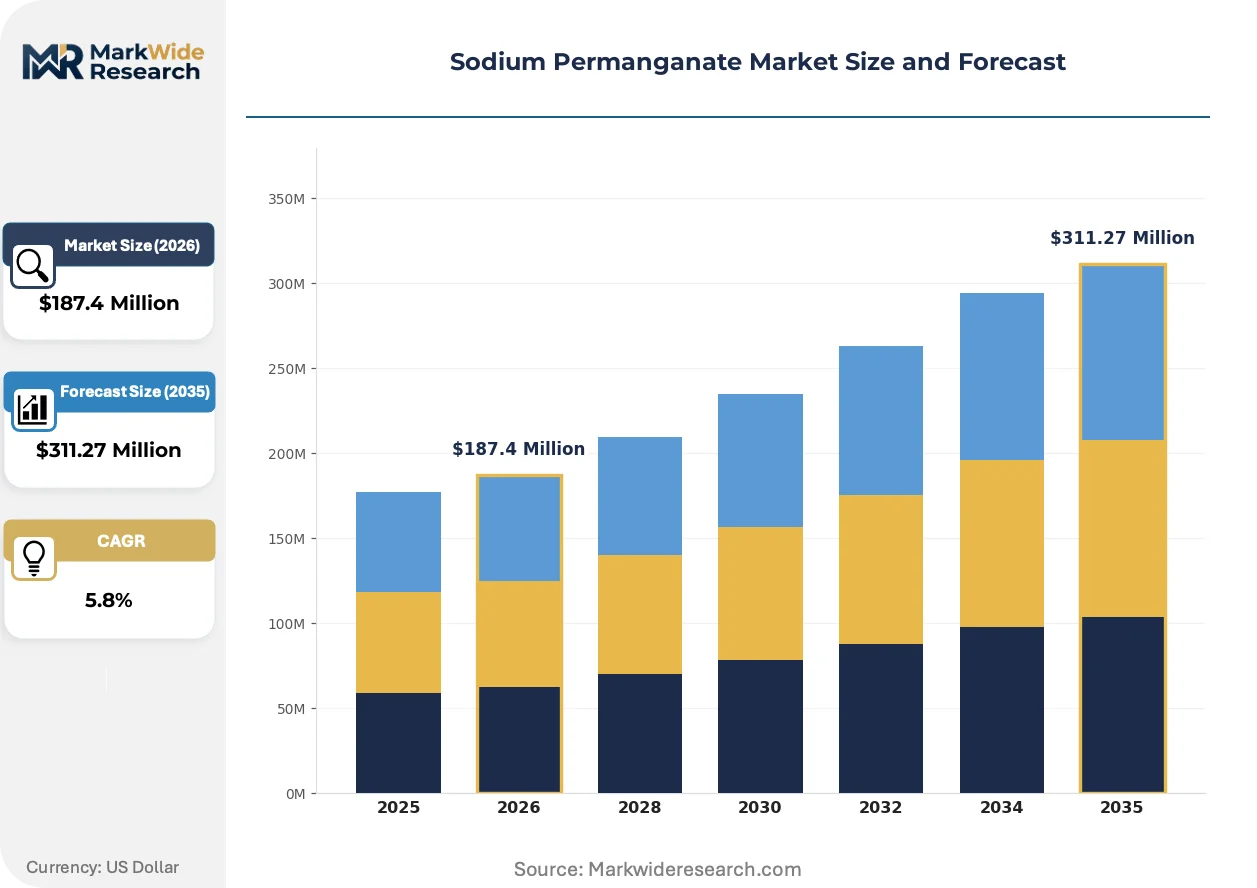
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Laboratory Grade End Use Industry: Water Treatment, Textile, Chemical Manufacturing, Pharmaceuticals Application: Oxidizing Agent, Disinfectant, Antiseptic, Color Indicator Form: Crystals, Powder, Liquid, Tablet |
| Companies Covered | Carus, Chongqing Changyuan Chemical, Guangdong Hangxin Technology, Nippon Chemical, Hepure, Changsha Yonta Industry, Nanjing Kaimubo Pharmatech, Aurora Fine Chemicals, CBW Chemie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Permanganate Market Evolving Landscape
Electrochemical manufacturing advances and regulatory chemistry requirements are reshaping how sodium permanganate is produced, specified, and procured across industrial and municipal end-uses.
Continuous-flow electrolytic oxidation is converging with real-time process analytical technology for active compound concentration control. Water treatment chemical distributors are adopting these systems to reduce transportation costs for high-volume 40% solution deliveries. The technology is converging with predictive maintenance platforms that cut unplanned downtime at captive production facilities.
REACH substance evaluation protocols are imposing new import documentation burdens on non-EU sodium permanganate suppliers. Industrial-grade formulations face enhanced heavy-metal impurity disclosure requirements that favor producers with integrated raw material traceability. European textile bleaching operations are responding by consolidating supplier relationships with registered REACH dossier holders.
Specification-driven procurement is compressing traditional spot-market purchasing for municipal water treatment chemicals. Utilities are locking into multi-year supply agreements with guaranteed purity certificates and emergency response service levels. This pattern is most visible across Great Lakes states where seasonal manganese release events demand reliable oxidation chemical availability.
Sodium Permanganate Market Segmentation
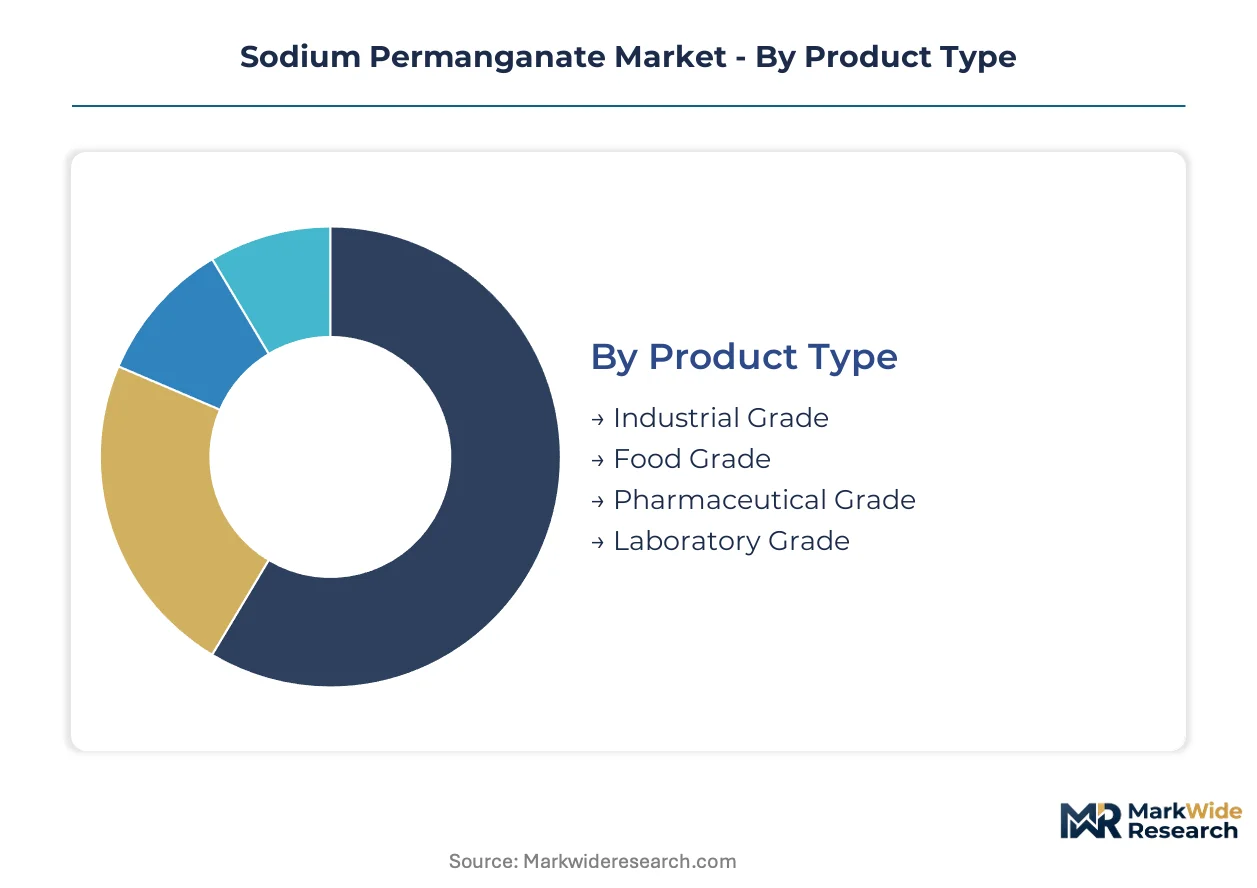
Sodium permanganate's value chain fragments sharply across purity tiers and application contexts, with grade specifications determining integration depth into municipal infrastructure versus specialized industrial processes. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate procurement dynamics.
Product Type:
Industrial grade operates as a standalone feedstock delivered in bulk solution form, while pharmaceutical and laboratory grades embed into tightly regulated manufacturing workflows requiring certificate-of-analysis documentation.
- Industrial Grade:Supplied as approximately 40% aqueous solution for municipal water pre-oxidation and textile bleaching. Procurement concentrates in long-term supply contracts with Great Lakes utilities managing seasonal manganese release events.
- Pharmaceutical Grade:Manufactured to USP and EP monograph standards with 18-24 month stability validation cycles. Demand clusters in compounding pharmacies and API synthesis operations where heavy-metal impurity controls command premium pricing.
- Food Grade:Meets FCC specifications for equipment sanitization in beverage processing and brewing applications.
- Laboratory Grade:Serves analytical chemistry and educational institutions with standardized reagent concentrations.
Volume placements concentrate in Industrial Grade; the faster expansion belongs to Pharmaceutical Grade.
End Use Industry:
Cost tier stratification separates capital-intensive municipal infrastructure from discretionary industrial chemical spending, with water treatment absorbing transportation-inflated delivered pricing that smaller end-uses cannot sustain.
- Water Treatment:Municipal utilities deploy sodium permanganate for iron, manganese, and hydrogen sulfide pre-oxidation under tightening EPA secondary standards. Procurement cycles accelerate across aging U.S. distribution networks facing infrastructure replacement deadlines.
- Textile:Bleaching operations in water-intensive dyeing facilities face discharge mandates favoring permanganate over chlorine-based alternatives. Indian modernization programs are consolidating supplier relationships with integrated raw material traceability.
- Chemical Manufacturing:Serves as a selective oxidant in organic synthesis and fine chemical production.
- Pharmaceuticals:Supports API oxidation steps and equipment decontamination protocols.
Water Treatment captures the dominant procurement volumes; Pharmaceuticals generates the steepest expansion trajectory.
Application:
Functional role determines specification stringency, with oxidizing applications tolerating broader impurity bands than disinfectant or diagnostic uses where trace contamination alters efficacy.
- Oxidizing Agent:Core function in water pretreatment and organic synthesis. Municipal utilities specify active compound concentration for predictable reaction stoichiometry in iron and manganese removal.
- Disinfectant:Applied in equipment sanitization and secondary water treatment where oxidation kinetics must align with contact time constraints.
- Antiseptic:Limited topical and wound care applications requiring biocompatibility certification.
- Color Indicator:Analytical chemistry applications leveraging the compound's distinct purple coloration for redox titration endpoints.
Oxidizing Agent applications anchor procurement volumes; Disinfectant use is gaining share fastest in food processing sanitation protocols.
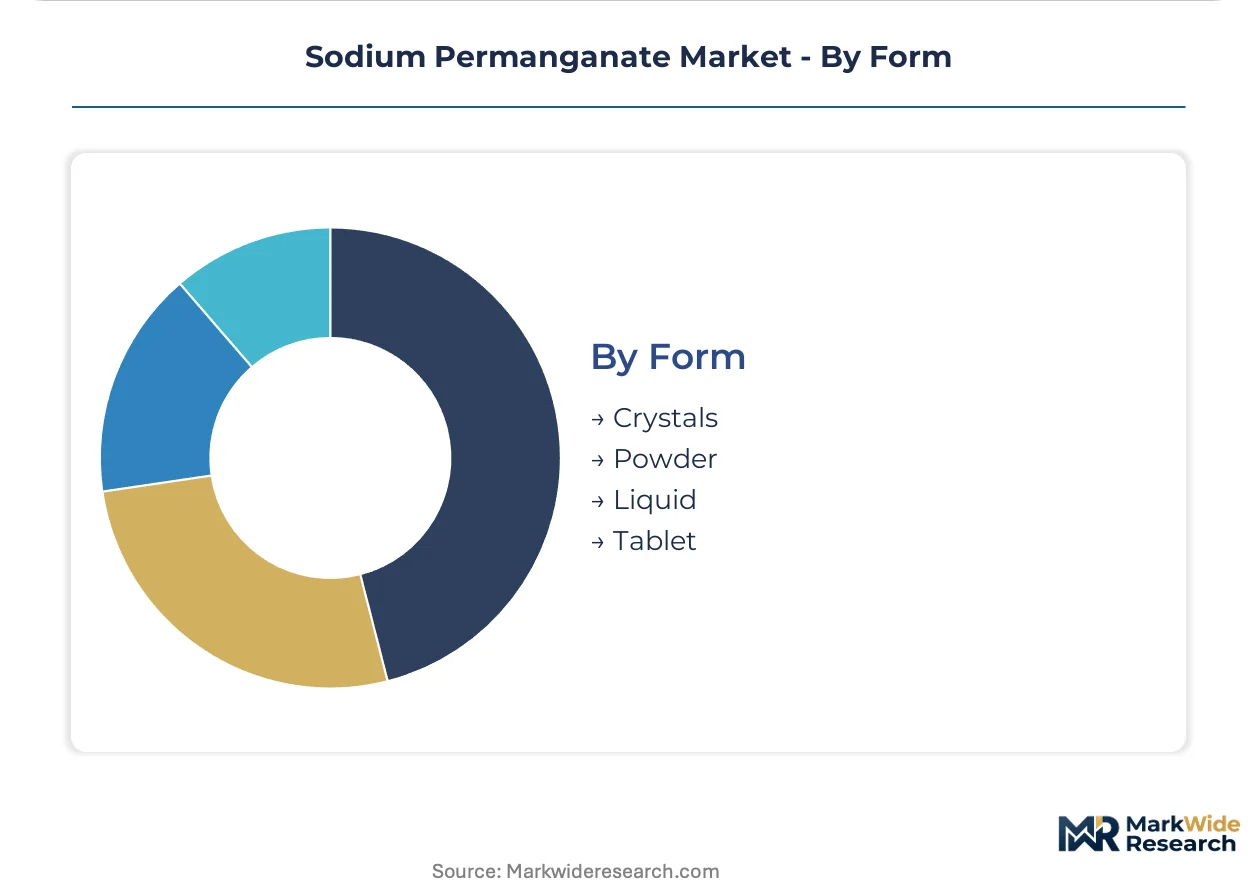
Form:
Supply chain economics favor liquid delivery for high-volume consumers, while solid forms address remote sites and applications requiring precise dosing flexibility.
- Liquid:40% aqueous solution dominates municipal procurement through reduced handling hazards and direct feed system compatibility. Distributors adopt continuous-flow electrolytic oxidation with real-time analytical technology to cut transportation costs.
- Powder:Preferred in textile bleaching operations requiring dry chemical storage stability and flexible concentration preparation.
- Crystals:Serves laboratory and specialized industrial applications with extended shelf-life requirements.
- Tablet:Deployed in remote mining camps and military base water treatment where on-site generation systems converge with containerized electrolytic units.
Liquid formulations command the volume concentration; Tablet formats are climbing the fastest through decentralized water treatment adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carus operates its captive electrolytic oxidation facility in LaSalle, Illinois, anchoring North American supply chains for municipal water treatment chemicals. This single-site concentration shapes procurement patterns across the Great Lakes corridor where seasonal manganese release events drive emergency oxidation chemical demand.
United States
EPA secondary standards for iron and manganese are tightening across small and medium municipal systems. The Safe Drinking Water Act amendments are accelerating pre-treatment oxidation upgrades in aging distribution networks. Great Lakes utilities in Michigan and Wisconsin are locking into multi-year sodium permanganate supply agreements with guaranteed purity certificates and emergency response service levels.
China
Textile bleaching operations in water-intensive dyeing facilities face discharge mandates favoring permanganate over chlorine-based alternatives. MIIT environmental compliance protocols are consolidating supplier relationships with integrated raw material traceability. The Yangtze River Delta chemical corridor hosts electrolytic oxidation capacity serving both domestic textile mills and export pharmaceutical synthesis operations.
India
Central Pollution Control Board mandates are modernizing water-intensive textile operations toward permanganate-based bleaching. BIS formulation standards are clarifying import access rules for industrial-grade sodium permanganate. Gujarat's chemical manufacturing belt is absorbing new oxidation chemical capacity as dyeing houses upgrade effluent treatment infrastructure.
Germany
REACH substance evaluation protocols are imposing enhanced heavy-metal impurity disclosure requirements on industrial-grade formulations. ECHA registration completion is clarifying import access rules and formulation standards across EU member states. The Rhine-Ruhr industrial corridor maintains specialized oxidation chemical distribution serving electronics surface preparation and pharmaceutical synthesis operations.
Japan
Semiconductor fabrication demand for ultra-pure oxidants with controlled heavy-metal specifications is opening premium-grade volume channels. METI chemical substance management frameworks govern handling, storage, and discharge thresholds for permanganate in industrial settings. The Kyushu electronics manufacturing cluster sources precision-grade sodium permanganate for wafer surface preparation protocols.
Sodium Permanganate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade stratification, with pharmaceutical-grade certification commanding 18-24 month stability validation cycles that filter out speculative entrants. The vendor base organizes around three strategic archetypes: captive electrolytic producers with backward integration into manganese ore processing, regional distributors with continuous-flow generation systems, and specialty chemical houses focused on compendial-grade certification. Dominant competitive moves include multi-year municipal supply contract lock-ins with emergency response service levels, and geographic expansion through containerized on-site generation systems for remote mining and military applications.
Among North American captive producers, Carus exemplifies the integrated electrolytic oxidation archetype with its Illinois-based production chain. Chinese chemical manufacturers including Chongqing Changyuan Chemical and Guangdong Hangxin Technology occupy positions within the volume-driven industrial-grade tier, supplying textile bleaching operations across Asia-Pacific markets. Japanese specialty chemical representation includes Nippon Chemical, which sits within the premium-grade segment addressing electronics surface preparation requirements with precision-controlled heavy-metal specifications.
| Leading Market Players |
|---|
| Carus |
| Chongqing Changyuan Chemical |
| Guangdong Hangxin Technology |
| Nippon Chemical |
| Hepure |
| Changsha Yonta Industry |
| Nanjing Kaimubo Pharmatech |
| Aurora Fine Chemicals |
| CBW Chemie GmbH |
| Others |
Value Network & Pricing Analysis
Skilled electrolytic cell technicians concentrated in Illinois and South Africa widen labor-cost differentials between pharmaceutical-grade and industrial-grade sodium permanganate pricing tiers. EPA compendial certification burdens and REACH registration requirements amplify these spreads as compliant producers capture premium positioning.
Pricing Analysis
Contract-based long-term offtake with guaranteed purity certificates anchors municipal procurement, with price differentiation driven by USP/EP certification level and volume scale. Pharmaceutical-grade qualification commands premium positioning due to 18-24 month stability validation cycles, while industrial-grade spot markets face cost compression from manganese ore price volatility. Small and medium municipal utilities exhibit highest price sensitivity; semiconductor fabricators show lowest sensitivity due to ultra-pure oxidant specifications.
Supply Chain Analysis
India's BIS formulation standards and domestic-content preferences for effluent treatment chemicals are reshaping sourcing patterns for textile bleaching operations. Supply concentrates in the United States, China, and India, with electrolytic oxidation capacity drawing from South African and Gabonese manganese ore. Single-source vulnerability at Carus's LaSalle facility creates structural risk for North American municipal utilities. Distribution runs through regional chemical distributors with captive generation systems and emergency response service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA Safe Drinking Water Act amendments and REACH substance evaluation protocols erect regulatory moats favoring dossier-holding incumbents.
For Market Incumbents: Deepen backward integration into manganese ore processing to offset raw material volatility from South African supply concentration. Lock multi-year municipal supply contracts with emergency response service levels before advanced oxidation process competitors displace pre-oxidation bids in large-capacity utility tenders.
For New Entrants and Emerging Players: Direct-to-municipal digital procurement platforms offer low-friction entry for containerized on-site generation systems serving remote mining camps and military bases. Target Indian textile modernization programs where Central Pollution Control Board discharge mandates favor permanganate over chlorine-based alternatives.
For Investors and Strategic Acquirers: The window for entry favors captive electrolytic producers with integrated raw material traceability over pure-play distributors. Acquisition targets should demonstrate REACH registration completion and USP monograph qualification. Watch PFAS co-treatment pilot program results as inflection indicator for oxidation kinetics competitiveness against ozonation alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese Ore Processing | Carus's captive supply chain insulates margin pools from Gabonese ore price swings. |
| REACH Registration Completion | ECHA dossier holders clarify import access rules across EU member states. |
| Long-term Supply Agreement with Emergency Response | Great Lakes utilities guarantee purity certificates for seasonal manganese release events. |
| Containerized On-site Generation Systems | Remote mining camps and military bases cut transportation costs for 40% solution deliveries. |
| Compendial Certification Investment | USP and EP monograph qualification opens API synthesis and equipment decontamination channels. |
Research Methodology
Independent corroboration across water treatment utility procurement directors, electrolytic plant managers, and textile bleaching operations heads underwrites the qualitative findings. Primary interviews with municipal chemical buyers, distribution channel partners, and pharmaceutical API synthesis directors combined with secondary validation from EPA enforcement data, ECHA registration databases, and customs trade records. Bottom-up segmentation triangulation across grade tier, end-use industry, and regional production hub converged with top-down macroeconomic factor assessment.
Rate-of-change decomposition across the analysis window modeled volume and value trajectories through grade-specific pricing elasticity and application penetration curves. Segmentation dimensions included purity tier, end-use industry, packaging format, and regional regulatory cluster. CAGRs derived from electrolytic capacity expansion timelines, municipal infrastructure replacement cycles, and textile modernization program adoption rates.
The model holds under stable manganese ore supply conditions and sustained EPA secondary standard enforcement; deviation in PFAS regulatory acceleration or advanced oxidation process cost curves would shift competitive positioning. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Sodium Dicyanamide Market