
 TPO Roofing Membrane Market | 2026-2036
TPO Roofing Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
TPO Roofing Membrane Market Analysis
Buyer concentration among national commercial roofing contractors is shifting toward integrated building envelope specialists with in-house membrane fabrication capacity. GAF leverages its vertically integrated manufacturing network to control raw polypropylene resin sourcing. Carlisle SynTec Systems anchors its position through dedicated TPO sheet calendering lines and regional distribution hubs. Firestone Building Products competes by bundling membrane supply with approved installer certification programs.
TPO roofing membrane is a thermoplastic polyolefin-based flexible sheet, typically reinforced with polyester scrim and manufactured through extrusion calendering at thicknesses ranging from 45 mil to 80 mil, designed primarily for watertight building envelope protection and solar reflectance in low-slope commercial roofing. The 60 mil specification dominates current specification volumes due to its balance of puncture resistance and material economy, while 80 mil products command premium positioning in hail-prone zones. Mechanically attached installation sustains the largest share of deployment, though fully adhered methods are gaining specification share in high-wind regions where uplift resistance governs engineering review.
The EPA ENERGY STAR program and FM Global wind uplift standards shape product qualification requirements and limit market access for uncertified membrane producers. ASTM D6878 governs material composition and dimensional stability testing, creating baseline technical barriers for new entrants. Stakeholders must monitor evolving state-level building code adoptions of cool roof mandates, as these regulatory trajectories will determine specification priority between reflectance-optimized and durability-optimized membrane formulations.
Market Dynamics
Commercial roofing specification authority is migrating from general contractors to building envelope engineers who demand performance-guaranteed membrane systems with documented lifecycle cost data. This technical buyer consolidation rewards manufacturers with in-house testing laboratories and certified installer networks.
Growth Catalysts
- Cool roof mandates:California's Title 24 Building Energy Efficiency Standards and similar codes across Arizona, Texas, and Florida are mandating minimum solar reflectance values that TPO membranes satisfy natively.
- Insurance underwriting incentives:FM Global's wind uplift ratings and hail damage resistance classifications are steering commercial property coverage terms toward certified membrane installations.
- Retrofit volume concentration:Aging single-ply stock across Sun Belt distribution centers, logistics facilities, and retail portfolios is reaching replacement age simultaneously.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to propylene monomer supply from Gulf Coast petrochemical complexes compress membrane gross margins unpredictably.
- Calendering equipment scarcity:Specialized extrusion lines for 60-80 mil sheet production concentrate among three domestic equipment fabricators, creating 18-24 month order backlogs.
- EPDM substitution persistence:Black rubber membrane retains specification share in northern climates where heating-load reduction outweighs cooling benefits.
Strategic Opportunities
- Solar-ready membrane integration:Pre-certified TPO sheets with factory-applied attachment zones for photovoltaic racking systems are capturing rooftop energy project specifications.
- Extended warranty monetization:20-30 year no-dollar-limit coverage programs create recurring service revenue streams and lock out competitor retrofits.
- Urban heat island compliance:Chicago, New York, and Philadelphia municipal ordinances are expanding cool roof requirements to existing building renovations beyond new construction.
Industry Challenges
- Installer certification throughput:Factory-trained mechanic shortages limit approved contractor network expansion in high-growth metropolitan markets.
- ASTM D6878 testing backlog:Third-party laboratory capacity constraints delay new product qualification timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TPO Roofing Membrane Market |
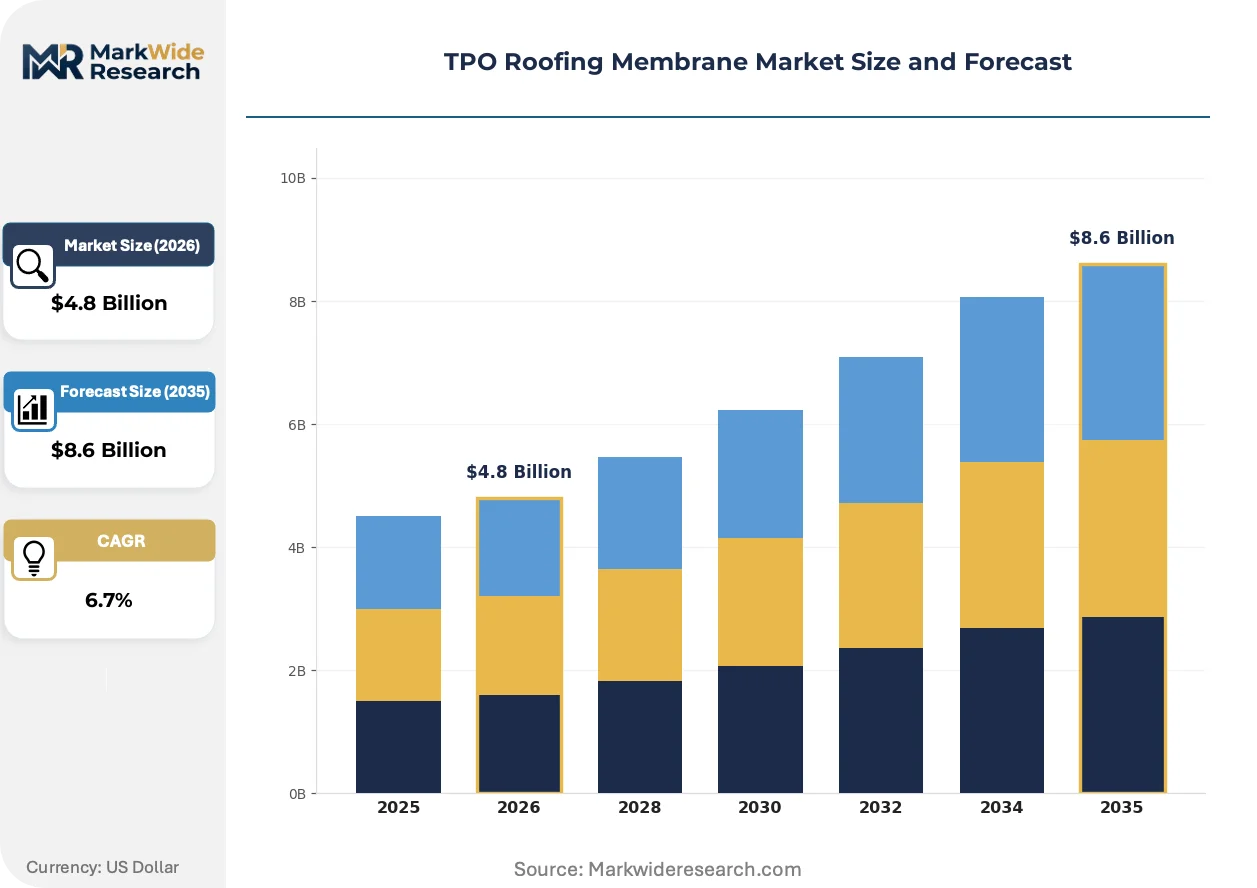
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Ply, Bi-Layer, Flexible, Custom Sheet Installation Method: Fully Adhered, Mechanically Attached, Ballasted, Hybrid End User: Commercial Buildings, Industrial Facilities, Residential Properties, Infrastructure Projects Thickness: 45 mil, 60 mil, 80 mil, 100 mil |
| Companies Covered | Mule-Hide, Versico Roofing Systems, GAF, Firestone Building Products, Elevate, Carlisle SynTec Systems, Duro-Last, SIKA, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TPO Roofing Membrane Market Emerging Trajectories
Membrane manufacturing is converging with digital building information modeling and field quality assurance systems. Specification decisions now integrate thermal performance simulation, drone-based installation verification, and predictive maintenance algorithms.
Reinforced TPO cap sheets with octene-based polyolefin elastomers are decentralizing specification authority from national distributor networks toward regional contractor co-ops with direct mill relationships. These advanced formulations deliver improved low-temperature flexibility and seam strength. Mid-size commercial roofing contractors in the Southeast and Southwest are bypassing traditional distribution tiers to secure volume pricing and custom color runs.
The EPA's pending revision to ENERGY STAR roof product specifications will tighten initial solar reflectance minimums and introduce three-year aged reflectance maintenance requirements. Manufacturers with in-house accelerated weathering laboratories will gain first-mover certification advantages. Specification priority will shift toward membrane formulations with enhanced UV stabilizer packages and top-surface protective coatings.
Building owners are unbundling material procurement from installation contracting, separating membrane supply agreements from labor bids. National retail chains and logistics operators with multi-site portfolios are negotiating direct supply contracts with membrane producers. This disintermediation concentrates purchasing power among facility management platforms with centralized capital planning functions.
TPO Roofing Membrane Market Segmentation
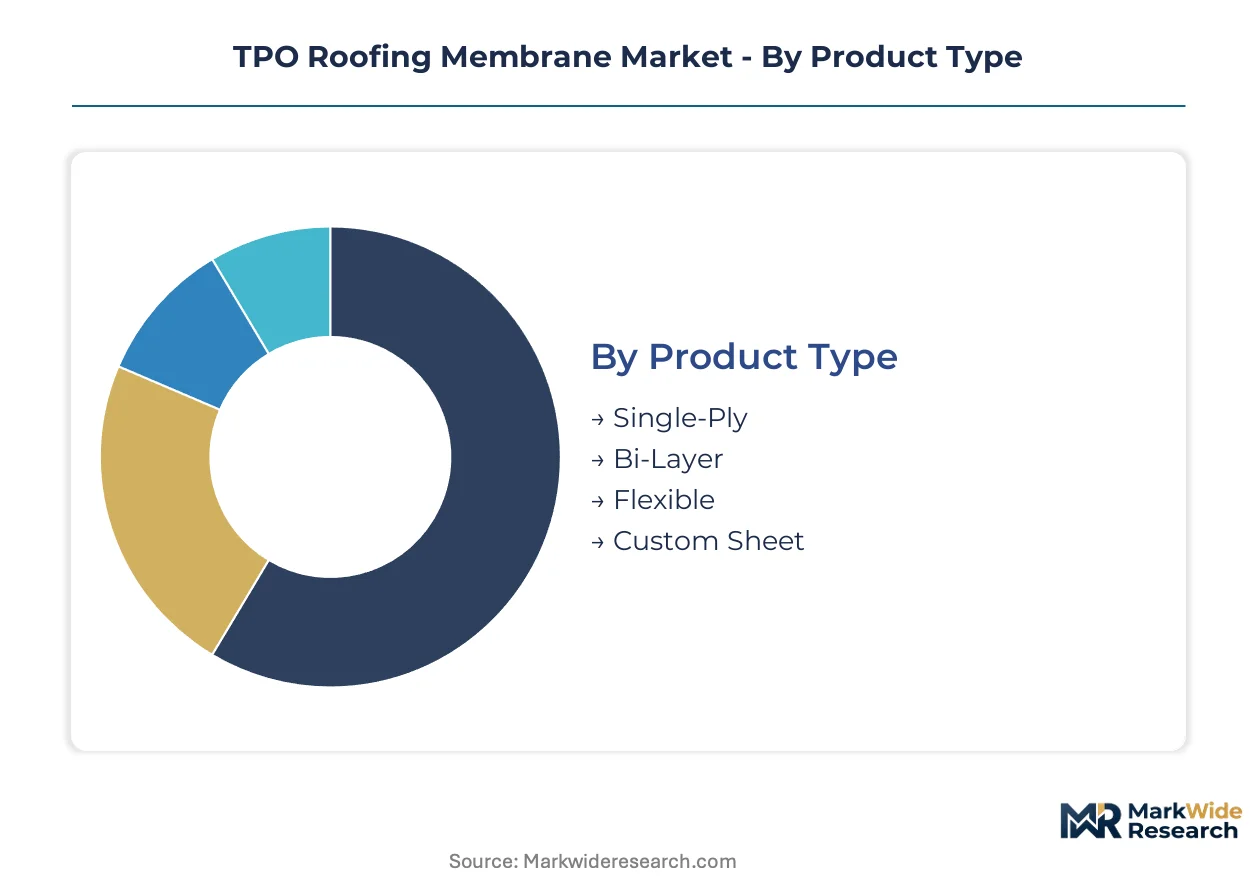
TPO membrane specification varies sharply by building type, climate exposure, and installation constraints. Product thickness and attachment method determine both material cost and labor intensity, creating distinct procurement patterns across contractor tiers.
Product Type:
Capital intensity concentrates in bi-layer manufacturing, where co-extrusion lines demand dual resin feed systems and precise layer thickness control.
- Single-Ply:Homogeneous thermoplastic sheets dominate retrofit specifications due to straightforward heat-welded seam formation and lower material cost per square foot. Demand clusters in Sun Belt distribution centers where 60 mil specifications balance puncture resistance against economy.
- Bi-Layer:Factory-laminated cap sheets over reinforced base layers command premium positioning in hail-prone zones. The co-extrusion equipment requirement limits production to major integrated manufacturers with dedicated calendering capacity.
- Flexible:Octene-based elastomer formulations deliver enhanced low-temperature flexibility for northern climate specifications.
- Custom Sheet:Color-matched and pre-printed membranes serve branded retail portfolios with corporate identity requirements.
Single-ply absorbs the bulk of installed capacity; bi-layer is expanding most quickly in severe weather markets.
Installation Method:
Mechanical attachment systems require the heaviest upfront tool investment, with automated fastener deployment rigs costing substantially more than adhesive spray equipment.
- Fully Adhered:Water-based or solvent adhesive bonding eliminates fastener penetrations and maximizes wind uplift resistance. Specification is climbing fastest in Florida and Gulf Coast markets where FM Global ratings govern insurance coverage terms.
- Mechanically Attached:Plates and screws secure membrane at engineered fastener patterns. This method sustains the largest deployment share due to speed advantages and substrate tolerance.
- Ballasted:Loose-laid membrane held by stone or concrete pavers persists in large-footprint industrial roofs with adequate structural capacity.
- Hybrid:Combined mechanical and adhered zones optimize material usage in complex roof geometries with varying wind exposure.
Mechanically attached retains dominant specification share; fully adhered is gaining fastest in high-wind corridors.
End User:
Commercial building procurement concentrates specification authority among national facility management platforms with centralized envelope standards.
- Commercial Buildings:Retail, office, and logistics portfolios drive volume through standardized 60 mil TPO specifications across multi-site rollouts. The EPA ENERGY STAR cool roof mandate in California Title 24 locks in reflective membrane demand.
- Industrial Facilities:Manufacturing and warehouse roofs with heavy mechanical equipment traffic specify 80 mil or reinforced membranes for puncture resistance.
- Residential Properties:Low-slope multifamily and estate home applications represent a narrow niche with distinct aesthetic requirements.
- Infrastructure Projects:Airport terminals, transit facilities, and public buildings impose extended warranty and performance bonding requirements.
Commercial buildings command the largest addressable spend; industrial facilities are expanding fastest as aging stock reaches replacement age.
Thickness:
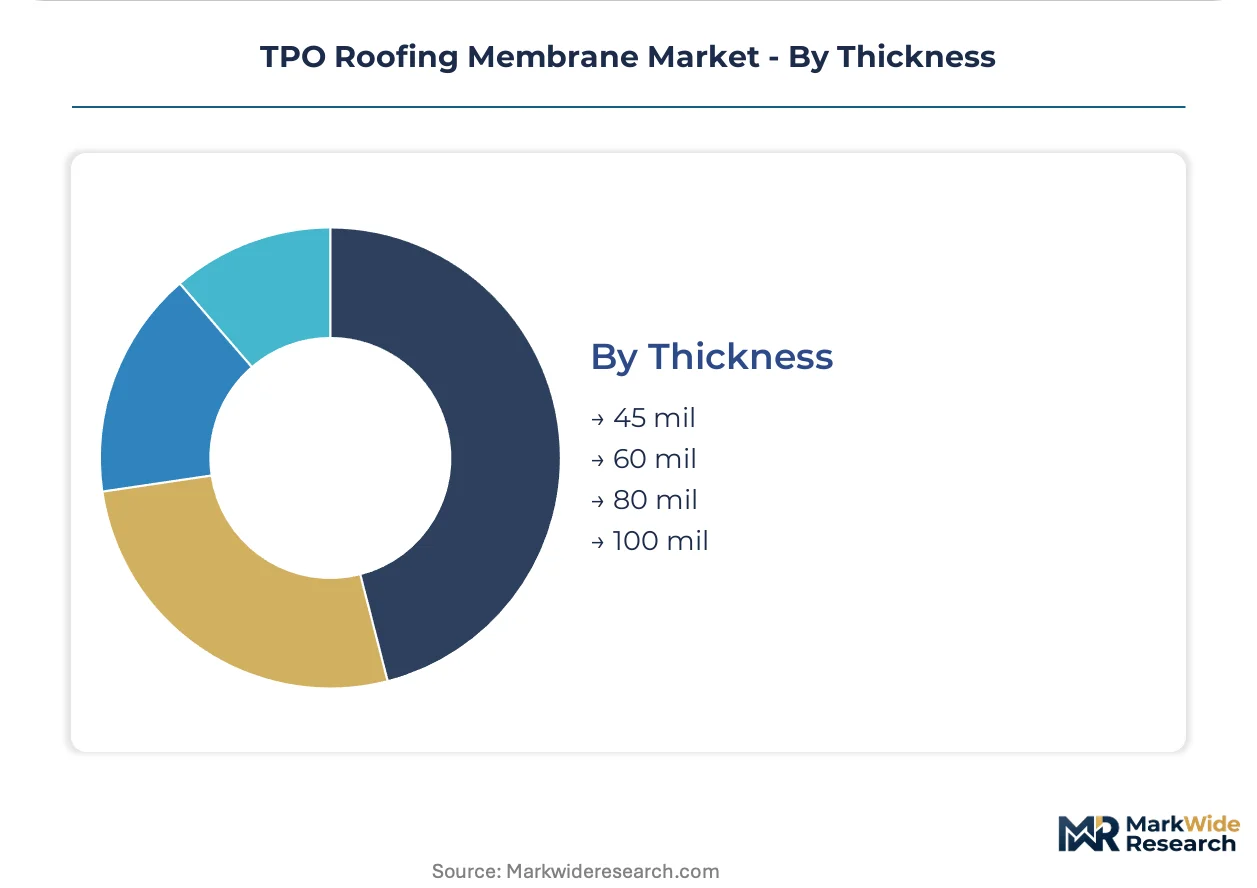
Calendering line configuration determines which thickness bands each manufacturer can produce economically, with 60 mil and 80 mil requiring distinct roller gap settings.
- 60 mil:The dominant specification balances material economy against adequate puncture resistance for standard commercial applications. This thickness captures the highest volume across Sun Belt metropolitan markets.
- 80 mil:Enhanced durability for hail zones and high-traffic roofs commands measurable price premiums and extended warranty eligibility.
- 45 mil:Economy-grade membranes serve temporary structures and budget-constrained retrofits with shorter planned service life.
- 100 mil:Heavy-duty specifications for extreme industrial environments remain a specialty production run with limited fabricator capacity.
60 mil dominates current specification volumes; 80 mil is climbing fastest in severe weather and high-wind markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial roofing demand concentrates in the United States, where cooling-load reduction drives specification decisions across Sun Belt metropolitan areas. The EPA's ENERGY STAR certification requirements shape product qualification across North America. Distribution networks anchor in Dallas, Atlanta, and Phoenix logistics corridors.
United States
California's Title 24 Building Energy Efficiency Standards mandate minimum solar reflectance values that TPO membranes satisfy natively. The EPA ENERGY STAR program shapes product qualification requirements and limits market access for uncertified producers. Dallas-Fort Worth anchors distribution for Southwest commercial retrofits, with contractors specifying 60 mil membranes for logistics facilities.
Canada
Cool roof adoption accelerates in Ontario and British Columbia as building codes tighten thermal performance standards. Health Canada's environmental product declarations influence specification for federal infrastructure projects. The Greater Toronto Area concentrates demand for 80 mil reinforced membranes in industrial warehouse construction.
Mexico
Manufacturing facility construction in Nuevo León and Baja California drives specification for durable single-ply systems. The country's national building code adoption of cool roof guidelines lags US standards but advances in border states. Monterrey industrial parks specify mechanically attached TPO for large-footprint distribution centers.
Germany
Industrial roofing renovation in North Rhine-Westphalia and Bavaria creates demand for high-performance membrane systems. The EU Green Deal's building renovation targets accelerate specification of energy-efficient envelope materials. The Rhine-Ruhr metropolitan region concentrates contractor networks for commercial retrofit projects.
China
Logistics facility construction in the Yangtze River Delta and Pearl River Delta absorbs imported membrane technologies. The country's dual carbon goals drive adoption of reflective roofing in coastal manufacturing zones. Shanghai's commercial building stock replacement cycle favors 60 mil specifications for rapid installation.
TPO Roofing Membrane Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue solar-ready membrane integration and extended warranty monetization. The vendor base clusters around integrated building envelope specialists with in-house fabrication capacity. Three archetypes dominate: vertically integrated resin-to-membrane manufacturers, regional calendering specialists with direct contractor relationships, and building materials conglomerates bundling membrane supply with installation certification. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as equipment backlogs stretch 18-24 months.
Among North American fabricators, GAF and Carlisle SynTec Systems exemplify the integrated manufacturing archetype, while Firestone Building Products occupies a position emphasizing installer network development. These three represent distinct strategic postures within a market where raw material sourcing control and certified mechanic throughput determine competitive viability.
| Leading Market Players |
|---|
| Mule-Hide |
| Versico Roofing Systems |
| GAF |
| Firestone Building Products |
| Elevate |
| Carlisle SynTec Systems |
| Duro-Last |
| SIKA |
| Johns Manville |
| Others |
Supply Flow & Price Mechanics
California's Title 24 Building Energy Efficiency Standards gate qualified supply and premium-tier pricing access by mandating minimum solar reflectance values that only certified TPO formulations achieve. Manufacturers with in-house accelerated weathering laboratories and EPA ENERGY STAR pre-qualification capture pricing premiums, while uncertified producers face exclusion from commercial specification pipelines across the Sun Belt.
Pricing Analysis
High-volume 60 mil specifications trade at thinner margins than premium 80 mil and bi-layer products engineered for hail zones. Price differentiation hinges on FM Global wind uplift certification tier and factory-applied solar-ready attachment zones for photovoltaic integration. Cost compression in standard single-ply grades is intensifying because polypropylene resin volatility from Gulf Coast petrochemical complexes squeezes producer margins unpredictably. National facility management platforms with multi-site portfolios wield lowest price sensitivity; regional contractor co-ops with limited volume scale face highest pressure.
Supply Chain Analysis
Freight cost sensitivity shapes membrane procurement geography, with Dallas-Fort Worth, Atlanta, and Phoenix anchoring distribution corridors for Sun Belt deployment. Manufacturing concentrates in the United States, with secondary fabrication in Canada and Mexico serving border-state projects. Raw material supply draws from propylene monomer production along the Texas-Louisiana petrochemical corridor, polyester scrim textile mills in the Southeast, and UV stabilizer chemical specialists. Single-source vulnerability sits with domestic calendering equipment fabricators, where 18-24 month order backlogs constrain capacity expansion. Distribution runs through national building envelope specialists with regional contractor certification networks and direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TPO roofing membrane market functions as a vertical-integration race where control over polypropylene resin sourcing and in-house calendering capacity determines margin defense. Players are pursuing backward integration into raw material supply as the decisive upstream lever.
For Market Incumbents: Anchor market position through captive polypropylene resin supply agreements with Gulf Coast petrochemical complexes and dedicated 80 mil calendering line investments. EPDM substitution persistence in northern climates threatens volume growth; counter through octene-based elastomer formulations for low-temperature flexibility certification. Factory-trained mechanic throughput constraints limit network expansion; prioritize regional training center deployment in high-growth metropolitan markets. For New Entrants and Emerging Players: Solar-ready membrane integration with factory-applied photovoltaic racking attachment zones offers a technology-first wedge into rooftop energy project specifications. Target commercial building owners unbundling material procurement from installation contracting, particularly national retail chains and logistics operators with centralized capital planning functions. Pursue direct supply contract positioning with facility management platforms bypassing traditional distributor tiers. For Investors and Strategic Acquirers: EPA's pending ENERGY STAR specification revision tightening aged reflectance maintenance requirements is the leading indicator that manufacturers with in-house accelerated weathering laboratories will capture first-mover certification advantages and pricing power. Over the coming decade, acquisition value concentrates in regional calendering specialists with direct contractor relationships and certified installer network density. Monitor state-level building code adoption trajectories for cool roof mandates as the signal for specification shift timing between reflectance-optimized and durability-optimized formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin Supply | Captive raw material sourcing insulates margins from Gulf Coast petrochemical price volatility. |
| Calendering Capacity Expansion | Dedicated 60-80 mil production lines secure allocation priority amid 18-24 month equipment backlogs. |
| Solar-Ready Membrane Certification | Factory-applied PV attachment zones capture rooftop energy project specifications ahead of competitors. |
| Extended Warranty Program Launch | 20-30 year no-dollar-limit coverage creates recurring service revenue and locks out competitor retrofits. |
| Installer Certification Network Buildout | Factory-trained mechanic density determines approved contractor throughput in high-growth metropolitan markets. |
Methodological Framework
Document review covered ASTM D6878 material standards, EPA ENERGY STAR roof product specifications, FM Global wind uplift rating documentation, and state-level building code adoptions, complemented by interviews with commercial roofing contractors, building envelope engineers, facility management procurement directors, and membrane manufacturing plant managers. Secondary validation drew from SEC filings of building materials conglomerates, American Chemistry Council petrochemical supply reports, and construction industry trade association membership data. Bottom-up volume estimates from contractor deployment patterns were triangulated against top-down resin consumption figures.
Cross-referencing historical specification trends with panel input from regional distributor networks and national account managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product thickness tier, installation method, end-use building type, and climate exposure zone. CAGRs were derived from elasticity-adjusted demand curves incorporating cooling-load reduction economics and insurance underwriting incentive trajectories. Key inputs encompassed polypropylene resin price forecasting models and urban heat island ordinance adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polypropylene supply disruption scenarios or accelerated state-level cool roof mandate adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Gas Barrier Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market