
 Powdered Cellulose Market | 2026-2036
Powdered Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Powdered Cellulose Market Outlook
Microcrystalline cellulose is shifting powdered cellulose economics as pharmaceutical formulators seek higher compressibility and flowability in direct-compression tablet manufacturing. JRS J. Rettenmaier & Söhne GmbH & Co. KG leverages vertical integration from wood pulp sourcing to micronized grades, sustaining cost advantages across European supply chains. International Fiber Corporation anchors North American availability through dedicated food-grade and technical cellulose production lines. Accent Microcell Pvt. Ltd. specializes in pharmaceutical-grade microcrystalline cellulose, competing on compendial compliance and particle-size customization for Indian and export markets.
Powdered cellulose consists of purified, mechanically disintegrated cellulose fibers derived from wood pulp or cotton linters, typically exhibiting particle sizes below 150 microns and moisture content of 3-5% by weight, functioning primarily as a bulking agent, anti-caking additive, and flow aid across food, pharmaceutical, and industrial applications. The microcrystalline cellulose product type leads value contribution due to premium pricing in oral solid dosage forms, while the food and beverages application segment differentiates through clean-label positioning as manufacturers replace synthetic anti-caking agents with plant-derived alternatives. Granules and powder forms dominate volume flows, though flake variants occupy niche positions in specialty cosmetic formulations where tactile properties command margin premiums.
FDA inactive ingredient guidance and EMA excipient quality standards shape pharmaceutical-grade specifications, while REACH registration requirements and F-Gas Regulation indirect pressures influence cellulose processing chemistry and solvent recovery systems. The EU Green Deal's biobased material targets and USDA biopreferred program criteria expand food-grade cellulose eligibility in sustainable procurement frameworks. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, EP, and JP monographs, as divergence in residual solvent limits and microbial specifications threatens cross-border formulation compliance and supplier qualification costs.
Market Dynamics
Pharmaceutical formulators are compressing supplier qualification timelines as FDA and EMA tighten residual solvent limits and microbial specifications, forcing cellulose mills to revalidate purification trains ahead of pharmacopeial harmonization deadlines.
Growth Catalysts
- Direct-compression tablet manufacturing:Oral solid dosage producers are specifying microcrystalline cellulose for its superior compressibility and flowability, displacing traditional wet granulation workflows.
- REACH registration tiering:ECHA's differentiated dossier requirements for cellulose derivatives are streamlining market access for purified mechanical grades across German and Benelux chemical processing clusters.
- Clean-label food reformulation:Synthetic anti-caking agent restrictions under USDA biopreferred procurement criteria are pulling plant-derived cellulose into bakery and dairy applications.
Market Restraints
- Alpha-cellulose feedstock volatility:Dissolving pulp contract prices swing with Nordic sawmill output and textile fiber competition, squeezing toll milling margins.
- Pharmaceutical-grade capacity concentration:Compendial-compliant micronization assets cluster in southern Germany and the US Midwest, creating single-source risk for qualified suppliers.
- Silicon dioxide substitution:Synthetic amorphous silica retains cost advantage in high-volume food anti-caking despite clean-label headwinds.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO's alignment with ICH Q3D elemental impurity guidelines creates first-mover advantage for cellulose producers achieving USP-NF and EP dual certification.
- Cellulosic encapsulation films:Convergence of modified cellulose ethers with HPMC capsule shell technology opens oral dosage delivery formats beyond tablets.
- Brazilian food additive re-registration:ANVISA's 2025 additive inventory update offers pathway for powdered cellulose inclusion in processed meat and beverage categories.
Industry Challenges
- Pharmacopeial auditor scarcity:USP and EP inspector availability bottlenecks are extending supplier qualification timelines to 18-24 months for new cellulose milling facilities.
- Solvent recovery capex burdens:F-Gas Regulation compliance for cellulose derivative processing requires nitrogen blanketing and closed-loop recovery systems that strain mid-cap mill balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powdered Cellulose Market |
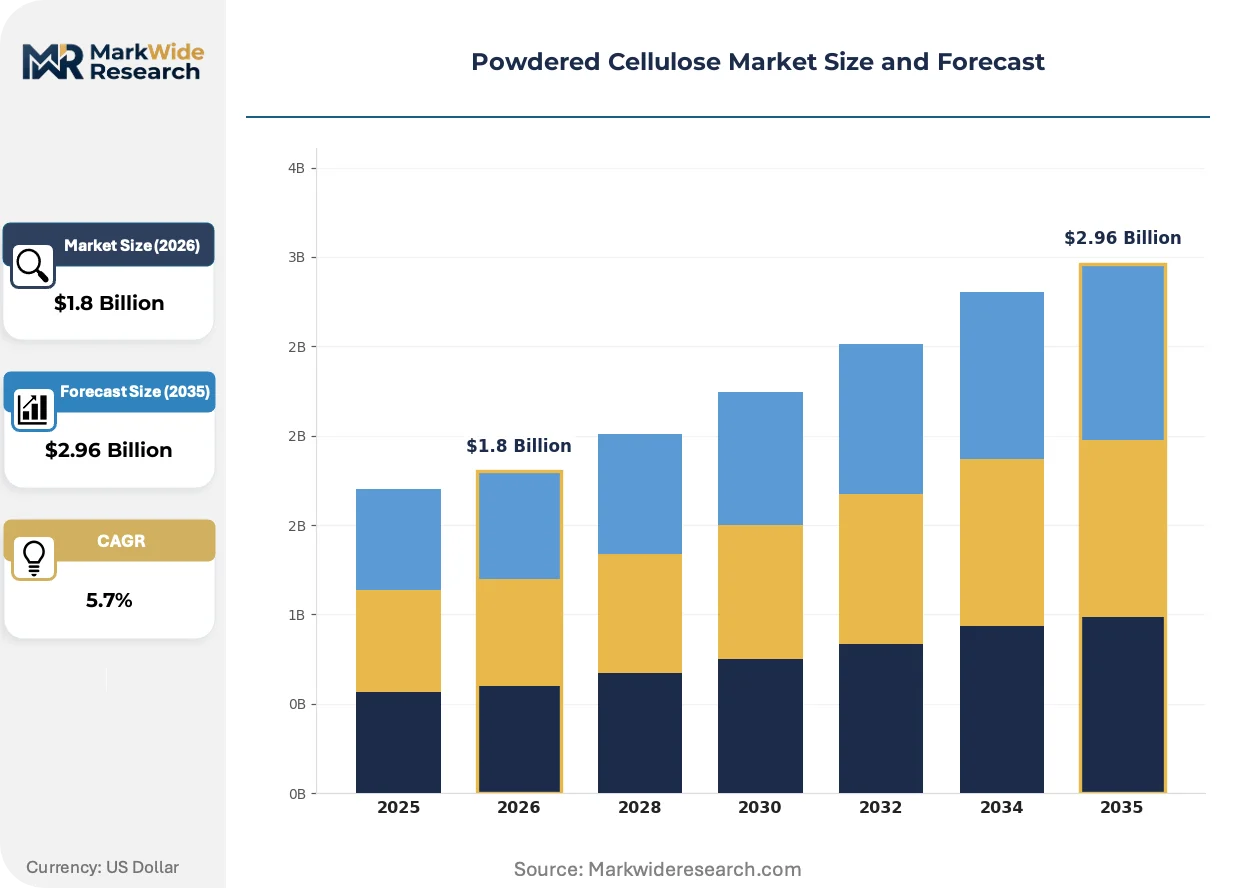
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcrystalline Cellulose, Avicel, Powdered Cellulose, Other Cellulose Application: Food & Beverages, Pharmaceuticals, Cosmetics, Personal Care Form: Granules, Powder, Flakes, Pellets End User: Manufacturers, Retailers, Distributors, Others |
| Companies Covered | JRS J. Rettenmaier & Söhne GmbH & Co. KG, International Fiber Corporation, Hosokawa Micron Powder Systems, Suhal Cellulose LLP, Jelu-Werk Josef Ehrler GmbH & Co. KG, Ankit Pulps and Boards Pvt. Ltd., Accent Microcell Pvt. Ltd., Cargill, Incorporated, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powdered Cellulose Market Strategic Shifts
Cellulose fiber engineering is converging with pharmaceutical process analytical technology, compressing development cycles for functional excipients while regulatory divergence between USP-NF, EP, and JP monographs complicates cross-border formulation strategies.
Co-processed microcrystalline cellulose-silicon dioxide composites are unifying disintegration and glidant functions in single-excipient systems. Generic drug manufacturers in India and Eastern Europe are adopting these grades to reduce tablet press changeover times. This unifying formulation approach is compressing traditional multi-excipient procurement workflows and squeezing standalone anti-caking agent volumes.
EMA's revised excipient risk assessment guidelines are mandating nitrosamine impurity screening for cellulose sources exposed to recycled process water. Toll manufacturers serving European pharmaceutical clients are retrofitting ultrafiltration and reverse osmosis purification trains. The guideline's 2025 enforcement window is accelerating capital deployment among German and Swiss cellulose processors ahead of qualification audits.
Formulation houses are consolidating excipient purchasing through platform agreements that bundle cellulose grades with binders and disintegrants. Large generic pharmaceutical manufacturers in the United States are displacing spot procurement with multi-year supply contracts tying volume commitments to technical service support. This purchasing consolidation is most visible among FDA-registered facilities in New Jersey and Puerto Rico seeking to reduce supplier audit burdens.
Powdered Cellulose Market Segmentation
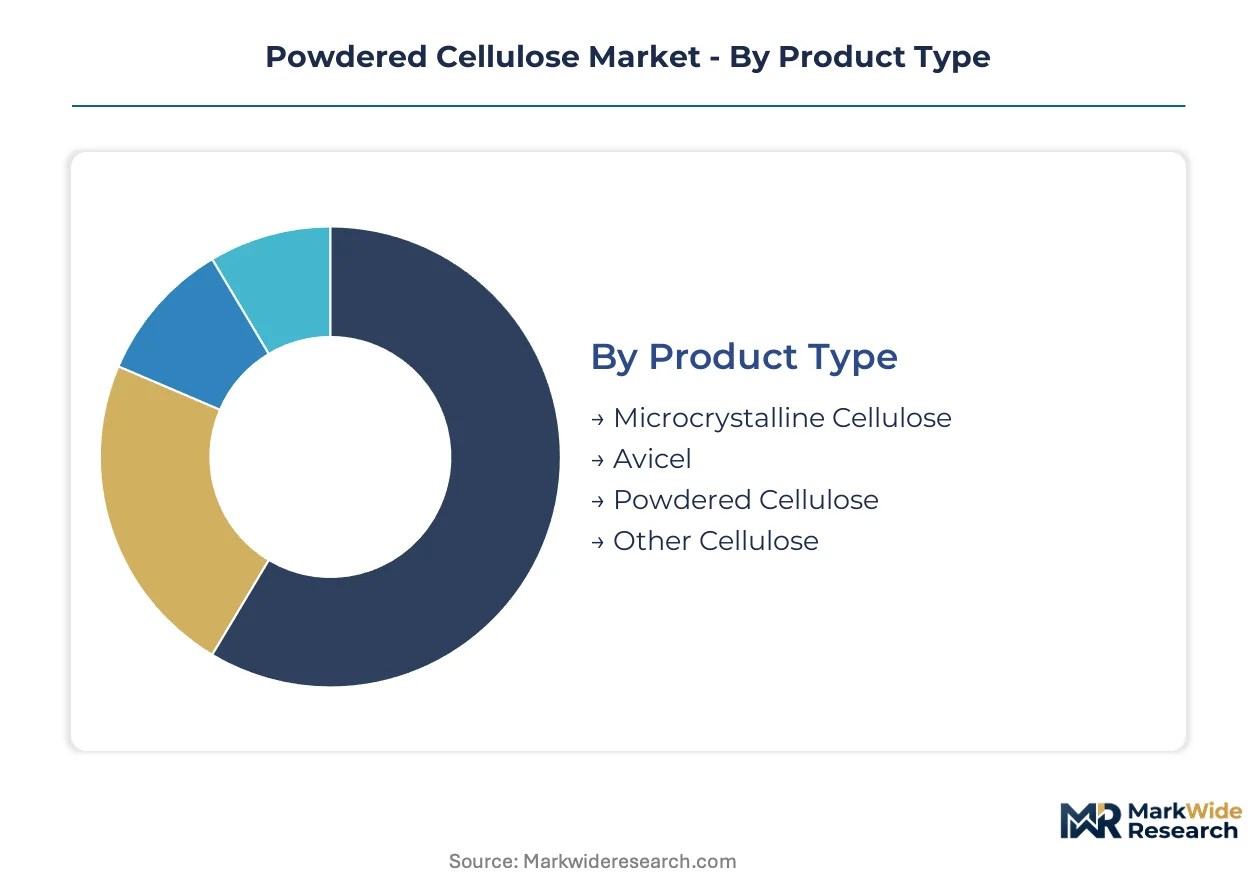
Powdered cellulose segmentation reflects divergent purity requirements across pharmaceutical compendial standards and food-grade specifications. Product type and application categories drive fundamentally different margin structures, with compendial grades commanding premium positioning against commodity food additives.
Product Type:
Customization intensity spans from compendial-grade micronization to commodity mechanical disintegration, with each tier demanding distinct purification asset configurations.
- Microcrystalline Cellulose:Partially depolymerized cellulose processed through controlled hydrolysis yields crystalline aggregates with superior compressibility indices. German and US Midwest pharmaceutical clusters specify this grade for direct-compression tablet lines, with residual solvent limits tightening under USP-NF and EP harmonization pressures.
- Avicel:A proprietary microcrystalline cellulose brand standard recognized across FDA-regulated facilities, distinguished by tightly controlled particle size distributions and moisture specifications. Formulators in New Jersey and Puerto Rico specify Avicel grades to reduce tablet press changeover validation burdens.
- Powdered Cellulose:Mechanically disintegrated alpha-cellulose fibers with particle sizes below 150 microns serve as bulking agents and anti-caking additives.
- Other Cellulose:Specialty grades including colloidal and low-density variants occupy niche encapsulation and sustained-release applications.
Most installed capacity flows through Microcrystalline Cellulose. Expansion is steepest in Other Cellulose as modified grades penetrate oral dosage delivery formats.
Application:
Cost-to-performance thresholds separate premium pharmaceutical excipient positioning from commodity food additive supply, with regulatory burden intensity determining supplier qualification timelines.
- Pharmaceuticals:Oral solid dosage manufacturing specifies compendial grades for binders, diluents, and disintegrants, with EMA nitrosamine screening mandates and FDA inactive ingredient guidance tightening purity benchmarks. Toll manufacturers in southern Germany and Switzerland are retrofitting ultrafiltration trains ahead of qualification audits.
- Food & Beverages:Clean-label reformulation is pulling plant-derived cellulose into bakery, dairy, and processed meat categories as synthetic anti-caking agents face restriction under USDA biopreferred procurement frameworks.
- Cosmetics:Tactile properties in specialty formulations command margin premiums for flake and micronized grades.
- Personal Care:Powder forms dominate absorbent and texturizing applications in topical formulations.
Pharmaceuticals concentrates the highest-margin volume. Food & Beverages is gaining share fastest as clean-label mandates accelerate synthetic displacement.
Form:
Volume scale and handling characteristics differentiate bulk powder flows from specialized geometry variants serving niche performance requirements.
- Powder:Below-150-micron particulate dominates high-volume pharmaceutical and food additive flows, with bulk density specifications varying by end-use compaction requirements.
- Granules:Agglomerated forms improve flowability in high-speed tablet press feeds and instant beverage dry mixes.
- Flakes:Flattened fiber morphology delivers distinctive tactile properties in cosmetic exfoliants and specialty personal care formats.
- Pellets:Spheronized cellulose serves as inert cores for active pharmaceutical ingredient layering in controlled-release formulations.
Powder commands the largest installed base. Pellets is expanding most quickly as multiparticulate dosage formats gain formulation share.
End User:
Procurement sophistication separates direct manufacturing relationships from intermediary distribution channels, with qualification depth scaling accordingly.
- Manufacturers:Pharmaceutical and food processing facilities source qualified grades through multi-year platform agreements bundling cellulose with binders and disintegrants, displacing spot procurement.
- Distributors:Regional chemical and ingredient distributors serve mid-cap formulators with shorter lead times and technical service support.
- Retailers:Private-label and specialty channel players procure smaller volumes for direct-to-consumer supplement and natural product lines.
- Others:Research institutions and contract development organizations source experimental grades for formulation feasibility studies.
Manufacturers absorb the majority of qualified volume. Distributors is climbing the fastest as mid-cap formulators consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southern German chemical processing belt anchors global pharmaceutical-grade cellulose capacity, with compendial-compliant micronization assets clustering around established pulp-to-excipient supply chains.
United States
Direct-compression tablet manufacturing in New Jersey and Puerto Rico drives demand for microcrystalline cellulose with tightly controlled particle specifications. FDA inactive ingredient guidance tightens residual solvent benchmarks, forcing toll manufacturers to revalidate purification trains. The US Midwest hosts specialized milling facilities serving FDA-registered pharmaceutical facilities.
Germany
REACH registration tiering through ECHA streamlines market access for purified mechanical grades across Benelux chemical corridors. The EU Green Deal's biobased material targets expand food-grade cellulose eligibility in sustainable procurement frameworks. Bavarian and Baden-Württemberg processors retrofit ultrafiltration systems ahead of EMA nitrosamine screening deadlines.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines creates qualification pathways for domestic excipient producers. Generic drug manufacturers in Gujarat and Maharashtra adopt co-processed cellulose composites to compress tablet press changeover times. Mumbai-Pune pharmaceutical clusters drive dual-certification demand for USP-NF and EP compliance.
Switzerland
Swissmedic oversight of excipient quality standards shapes premium-grade specifications for European export markets. Swiss cellulose processors deploy closed-loop solvent recovery systems under F-Gas Regulation compliance mandates. Basel-region chemical hubs concentrate modified cellulose ether production for encapsulation film applications.
Brazil
ANVISA's 2025 food additive inventory update opens processed meat and beverage categories for powdered cellulose inclusion. Clean-label reformulation in São Paulo-state dairy operations pulls plant-derived anti-caking agents into bakery applications. Domestic toll milling capacity expands to serve Mercosur pharmaceutical formulators.
Powdered Cellulose Market Competitive Environment
Global majors compete with regional champions across compendial certification depth, with market structure tiering by purification asset scale and pharmacopeial qualification breadth. German and US-based processors anchor premium pharmaceutical-grade supply through captive pulp sourcing and micronization capabilities. Three archetypes dominate: vertically integrated pulp-to-excipient operators, toll manufacturers serving qualified pharmaceutical clients, and regional food-grade specialists. Capacity expansion and strategic platform agreements bundling cellulose with binders represent the dominant competitive moves.
Among German integrated processors, JRS J. Rettenmaier & Söhne GmbH & Co. KG exemplifies backward integration from wood pulp sourcing through compendial-grade production. International Fiber Corporation anchors North American availability through dedicated food-grade and technical cellulose lines. Accent Microcell Pvt. Ltd. occupies a position within the Indian pharmaceutical excipient tier, competing on particle-size customization for export markets.
| Leading Market Players |
|---|
| JRS J. Rettenmaier & Söhne GmbH & Co. KG |
| International Fiber Corporation |
| Hosokawa Micron Powder Systems |
| Suhal Cellulose LLP |
| Jelu-Werk Josef Ehrler GmbH & Co. KG |
| Ankit Pulps and Boards Pvt. Ltd. |
| Accent Microcell Pvt. Ltd. |
| Cargill, Incorporated |
| ADM |
| Others |
Value Chain & Pricing Dynamics
Dissolving pulp contract prices swing through Nordic sawmill output cycles and textile fiber competition, compressing toll milling margins before pharmaceutical-grade premiums recover downstream. This feedstock volatility stratifies pricing across compendial, food-grade, and technical cellulose tiers as buyers lock in volume commitments to buffer spot market exposure.
Pricing Analysis
Input-cost pass-through from alpha-cellulose feedstock dominates pricing mechanics, with compendial-grade micronization commanding substantial premiums over commodity mechanical disintegration. Price differentiation rests on USP-NF and EP dual certification depth, with German and US Midwest processors capturing margin premiums from qualified pharmaceutical buyers. Cost compression in food-grade segments intensifies because synthetic silica alternatives retain cost advantage despite clean-label headwinds. Generic drug manufacturers in India and Eastern Europe exhibit highest price sensitivity, while FDA-registered facilities in New Jersey and Puerto Rico prioritize technical service bundling over unit cost.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle qualified-grade demand through multi-year platform agreements bundling cellulose with binders and disintegrants. Geographic supply concentration centers on southern Germany, the US Midwest, and Switzerland where compendial-compliant micronization assets cluster around established pulp-to-excipient supply chains. Raw material dependencies draw from Nordic dissolving pulp, cotton linters, and recycled process water systems. Single-source vulnerability runs through pharmaceutical-grade capacity concentration in Bavarian and Baden-Württemberg processing hubs. Distribution runs through specialized chemical distributors serving mid-cap formulators with shorter lead times and technical qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between REACH-registered European supply and CDSCO-aligned Indian qualification pathways, with regulatory compliance cost differentials exceeding feedstock differentials across these corridors.
For Market Incumbents: To counter silicon dioxide substitution in high-volume food applications, deepen backward integration into Nordic pulp sourcing to secure feedstock cost advantage and accelerate USP-NF and EP dual certification investment ahead of pharmacopeial harmonization deadlines. For New Entrants and Emerging Players: Co-processed microcrystalline cellulose-silicon dioxide composite technology offers entry wedge into Indian generic pharmaceutical clusters where tablet press changeover compression drives specification demand. Target CDSCO-aligned excipient qualification as the most penetrable regulatory pathway, leveraging technical partnerships with Mumbai-Pune formulation houses for go-to-market traction. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmacopeial auditor scarcity extends supplier qualification timelines to 18-24 months, creating captive value in existing qualified assets. Mid-cap toll manufacturers with existing USP-NF or EP certification represent prime acquisition targets. Monitor EMA nitrosamine screening enforcement windows as inflection indicator for accelerated capital deployment among European processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Sourcing | Captive feedstock supply buffers dissolving pulp contract volatility for German processors. |
| Dual Certification Investment | USP-NF and EP alignment opens Indian pharmaceutical export markets ahead of CDSCO deadlines. |
| Ultrafiltration System Retrofit | EMA nitrosamine compliance enables continued European pharmaceutical client qualification. |
| Co-processed Composite Development | Unified excipient systems reduce procurement complexity for Indian generic manufacturers. |
| Platform Agreement Expansion | Multi-year supply contracts with FDA-registered facilities displace spot procurement volumes. |
Study Parameters
Multiple input streams — primary interviews with pharmaceutical formulators, cellulose mill technical directors, and regulatory affairs specialists; secondary validation through FDA inactive ingredient databases, EMA excipient quality guidelines, and USP-NF monograph documentation; customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured qualification timeline pressures, purification asset deployment patterns, and procurement consolidation trends across New Jersey, Puerto Rico, southern Germany, and Mumbai-Pune clusters.
Data-stream reconciliation anchored volume and value outputs across product type, application, form, and end-user segmentation dimensions, with additional modeling of regional regulatory cluster effects. CAGRs were derived from installed capacity expansion trajectories, pharmacopeial harmonization schedule impacts, and clean-label substitution elasticity parameters. Forecast inputs incorporated REACH registration tiering effects, F-Gas Regulation compliance capex burdens, and CDSCO-ICH Q3D alignment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial divergence between USP-NF, EP, and JP monographs, Nordic sawmill output volatility, and synthetic anti-caking agent regulatory restriction pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Tin Fluoborate Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Isatoic Acid Anhydride Market