
 Bistrifluoromethanesulfonimide Lithium Market | 2026-2036
Bistrifluoromethanesulfonimide Lithium Market Size, Share, and Industry Trends Forecast 2026-2036
Bistrifluoromethanesulfonimide Lithium Market Insights
Battery-grade purity thresholds above 99.9 percent is redrawing supplier hierarchies in the bistrifluoromethanesulfonimide lithium space. Solvay S.A. leverages its integrated fluorochemistry platform to secure precursor control across European manufacturing nodes. Mitsubishi Chemical Corporation anchors long-term catholyte partnerships with South Korean cell producers. Central Glass Co., Ltd. specializes in halide purification routes that differentiate its material for next-generation solid-state architectures.
Bistrifluoromethanesulfonimide lithium, commonly abbreviated as LiTFSI, is a lithium salt featuring two trifluoromethanesulfonyl imide groups bonded to a central nitrogen, yielding high ionic conductivity and thermal stability above 200 degrees Celsius in non-aqueous electrolytes. The compound functions primarily as a conductive salt and additive in lithium-metal and lithium-ion cells where low moisture sensitivity and wide electrochemical windows prove critical. Electrolytic solutions command the dominant revenue share due to their direct integration into cell assembly lines, while additives represent the fastest-expanding margin pool as manufacturers seek dendrite suppression and interfacial stabilization. The automotive end-user segment absorbs the largest volume flows, though aerospace qualification pathways for high-altitude energy storage are opening secondary demand channels.
REACH registration requirements in Europe, China's GB/T standards for lithium battery materials, and South Korea's K-Battery strategy collectively elevate compliance costs for non-integrated producers while rewarding certified supply chains. The EU Battery Regulation's carbon footprint declarations and recycled content mandates will reshape sourcing decisions for cell manufacturers importing electrolyte salts. Stakeholders must monitor purity certification timelines and regional qualification bottlenecks rather than capacity announcements alone.
Market Dynamics
Ultra-high-purity certification requirements above 99.9 percent are fragmenting supplier tiers in bistrifluoromethanesulfonimide lithium, forcing capital-intensive purification retrofits while rewarding integrated fluorochemistry platforms with captive precursor supply.
Growth Catalysts
- Solid-state battery commercialization:Automotive OEMs in South Korea and Japan are qualifying LiTFSI-based catholytes for lithium-metal anode architectures, creating pull-through demand for battery-grade salts.
- EU Battery Regulation impurity thresholds:Tightening limits on halide and moisture content in electrolyte salts are disqualifying commodity-grade producers from European cell supply chains.
- China's dual carbon goals:Domestic NMPA and MIIT mandates for energy density improvements in EV cells are accelerating substitution of conventional LiPF6 with thermally stable alternatives.
Market Restraints
- Fluorinated precursor concentration:Trifluoromethanesulfonyl chloride supply concentrates among Japanese and Chinese specialty chemical producers, exposing non-integrated salt manufacturers to input volatility.
- REACH registration cost barriers:Full substance dossier requirements for LiTFSI in Europe impose six-figure compliance burdens that exclude mid-scale entrants from commercial supply.
- LiPF6 cost-performance parity:Established lithium hexafluorophosphate retains cost advantages in liquid electrolyte applications, limiting LiTFSI penetration in price-sensitive cell segments.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Domestic manufacturing incentives create first-mover openings for electrolyte salt producers establishing local purification capacity ahead of cathode plant commissioning.
- Aerospace high-altitude storage qualification:Extended thermal stability requirements for stratospheric drones and satellite power systems favor LiTFSI over conventional salts in emerging defense and commercial aviation contracts.
- Direct catholyte supply contracts:Bypassing merchant electrolyte blenders through long-term partnerships with solid-state cell developers captures margin pools currently retained by formulation intermediaries.
Industry Challenges
- Halide contamination control:Maintaining sub-ppm chloride and fluoride levels through multi-stage crystallization requires specialized process engineering talent scarce outside Japanese and German chemical corridors.
- Qualification timeline compression:South Korean cell producers are compressing supplier certification cycles from 24 months to 12 months, straining quality system documentation and audit bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bistrifluoromethanesulfonimide Lithium Market |
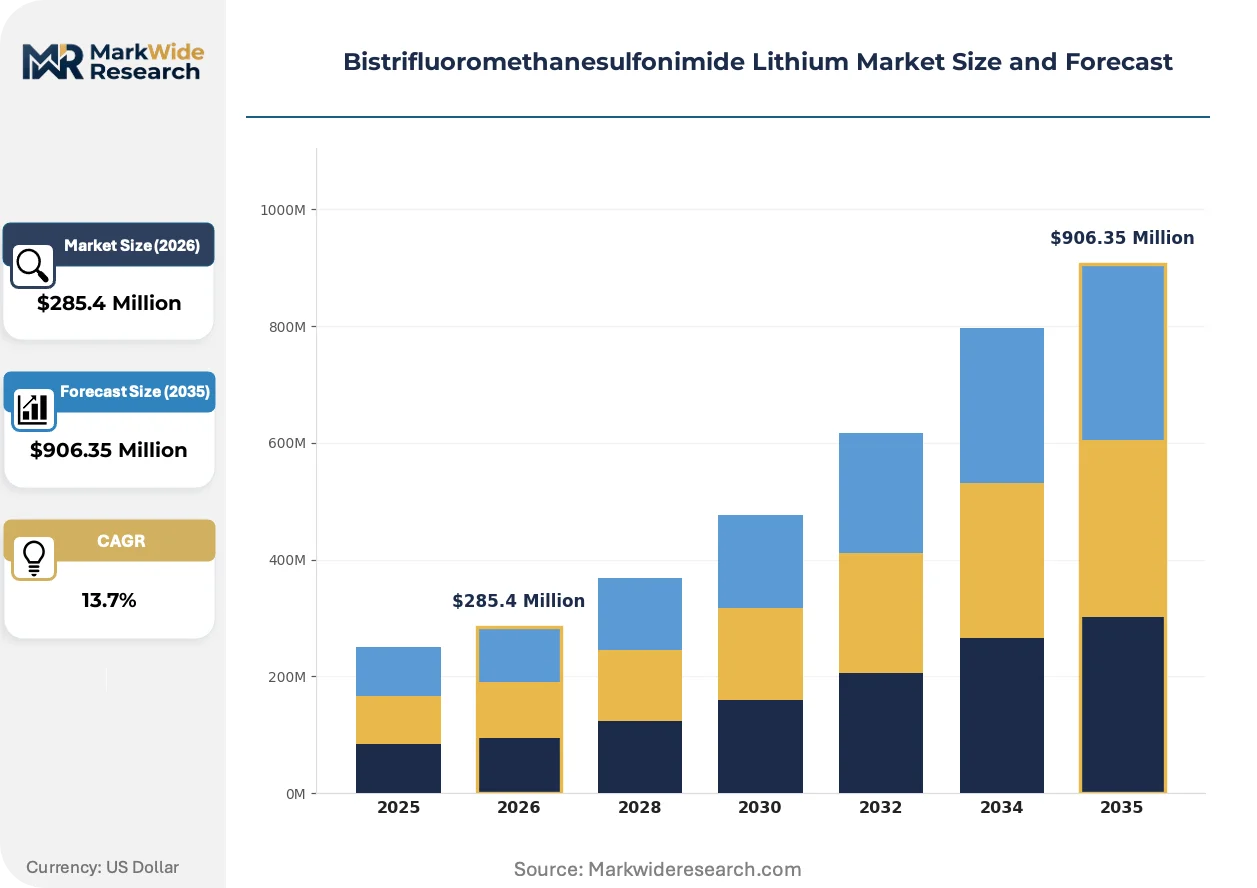
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Solutions, Additives, Conductive Polymers, Battery Components Application: Lithium Batteries, Fuel Cells, Supercapacitors, Energy Storage Systems End User: Automotive Sector, Electronics Manufacturers, Renewable Energy Providers, Aerospace Industry Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Solvay S.A., Mitsubishi Chemical Corporation, Tinci Materials, Zhangjiagang Hicomer Chemical Co., Ltd., Jiangsu Guotai Super Power New Materials Co., Ltd., Central Glass Co., Ltd., Nippon Shokubai Co., Ltd., 3M, Morita Chemical Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bistrifluoromethanesulfonimide Lithium Market Trends and Innovations
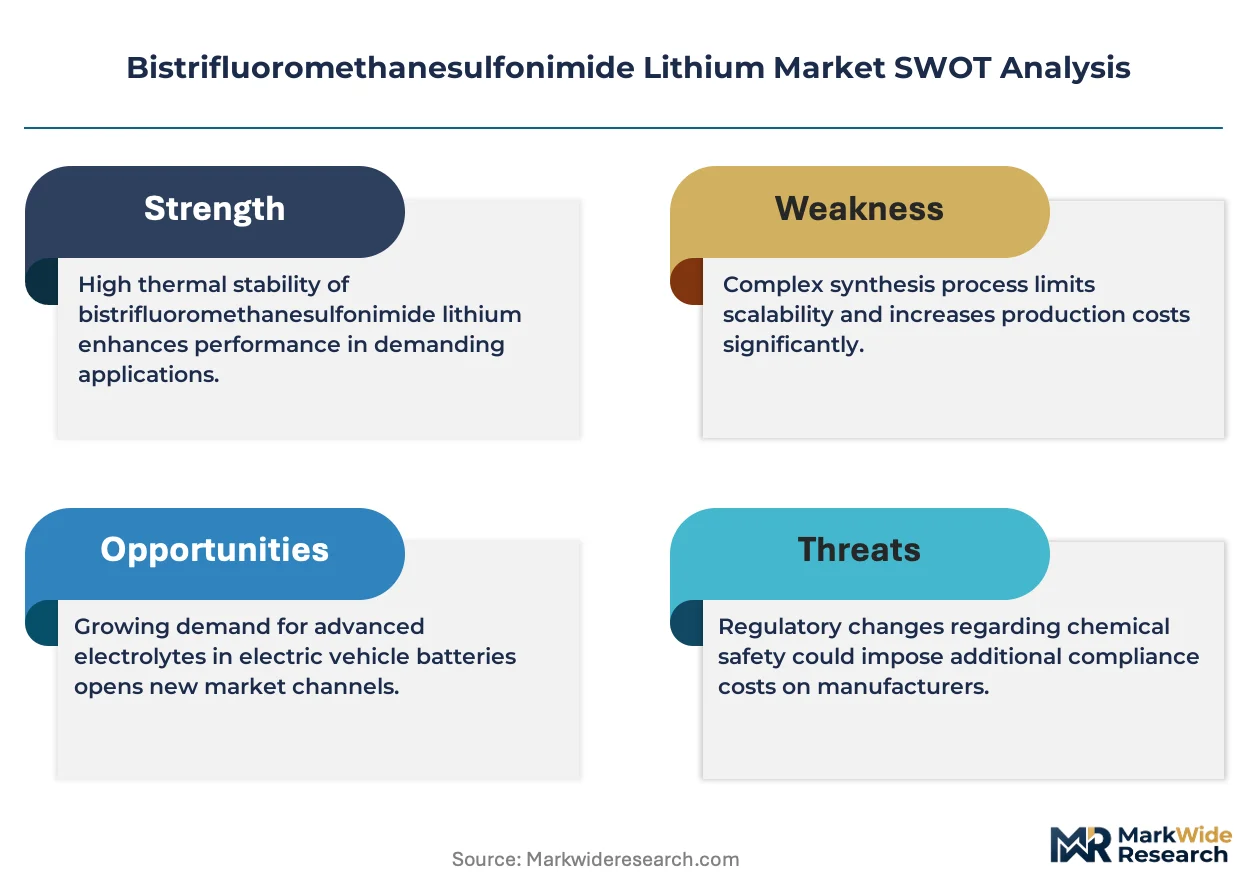
Synthetic route innovation and regulatory disclosure mandates are actively restructuring competitive advantage in bistrifluoromethanesulfonimide lithium, favoring producers with integrated environmental compliance and advanced purification capabilities.
Halide-free synthesis pathways for LiTFSI are bifurcating competitive positioning in the electrolyte salt market. Solid-state battery developers in Japan and South Korea are prioritizing salts produced via non-halide routes for reduced interfacial corrosion in lithium-metal cells. This technology divergence is compressing margins for legacy producers dependent on conventional fluorination while enabling premium pricing for certified low-halide grades.
REACH's expanded SCIP database requirements for recycled content tracking are forcing supply chain transparency investments across European-bound LiTFSI shipments. Cell manufacturers importing electrolyte salts must now document carbon footprint and recycled material percentages at the batch level. German and French battery assembly plants are responding by consolidating supplier bases to qualified partners with certified lifecycle data systems.
Long-term offtake contracting is displacing spot market procurement for battery-grade LiTFSI as cathode producers seek volume certainty ahead of solid-state production ramps. South Korean cell makers are locking five-year supply agreements directly with salt manufacturers, bypassing traditional electrolyte formulation houses. This channel compression is most visible in the Incheon and Ulsan industrial corridors where integrated cathode-electrolyte joint ventures are forming.
Bistrifluoromethanesulfonimide Lithium Market Segmentation
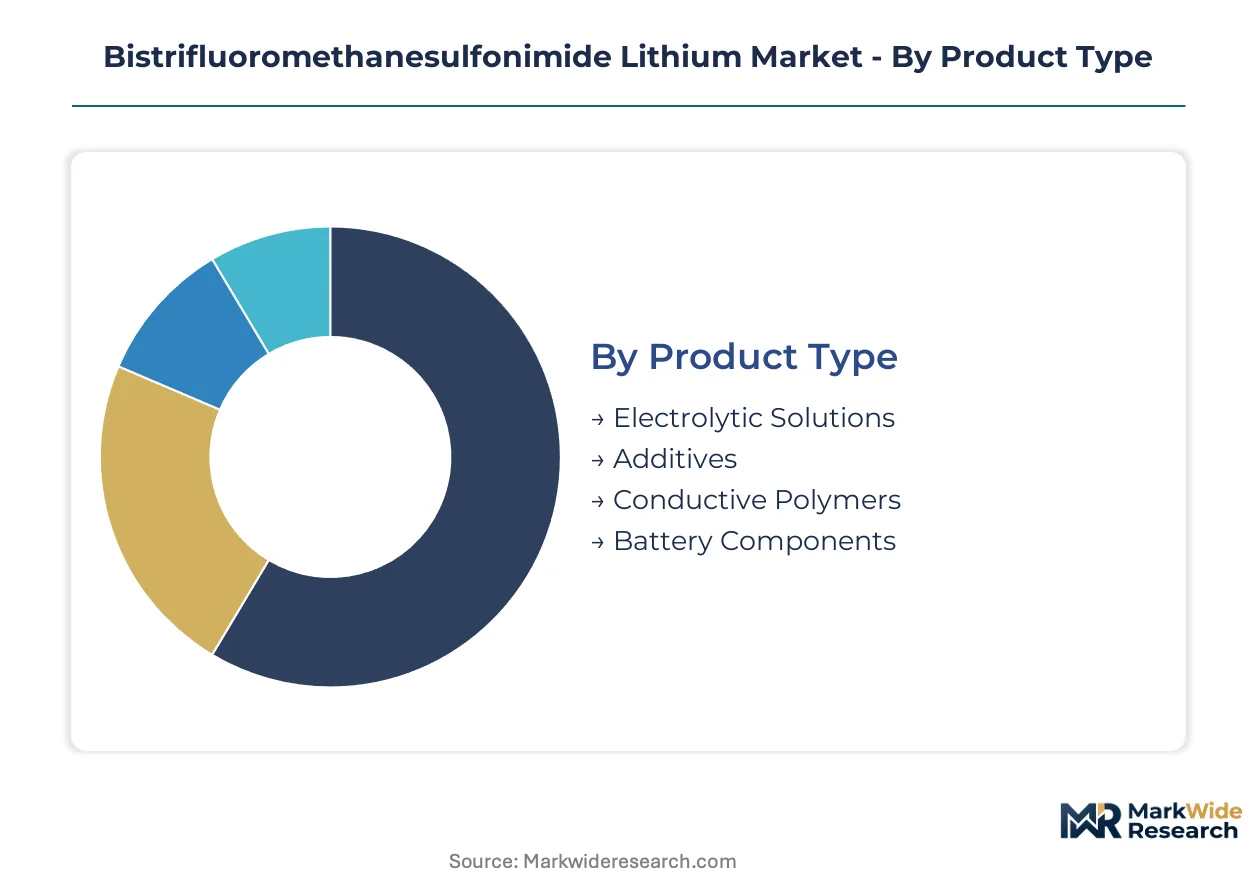
Segmentation in bistrifluoromethanesulfonimide lithium reveals how purity grades and application specifications fragment procurement patterns across battery supply chains. Regulatory thresholds on halide content and moisture levels now determine which product categories qualify for automotive and aerospace contracts.
Product Type:
REACH registration and China's GB standards enforce divergent purity specifications across product categories, with battery-grade certification requiring sub-ppm halide thresholds that commodity grades cannot meet.
- Electrolytic Solutions:Liquid formulations integrating LiTFSI as the primary conductive salt in non-aqueous solvents. Automotive cell producers in South Korea's Incheon corridor absorb the dominant volume flows for lithium-metal and high-nickel cathode architectures. Established volume favors electrolytic solutions; emerging adoption favors additives.
- Additives:Concentrated LiTFSI doses blended at 1-5 weight percent to suppress dendrite formation and stabilize solid-electrolyte interphases. Solid-state battery developers in Japan's Kansai chemical corridor are accelerating procurement of ultra-high-purity additive grades ahead of production ramps.
- Conductive Polymers:LiTFSI-doped polymer electrolytes for flexible and structural battery applications.
- Battery Components:Pre-formulated catholyte pastes and separator coatings incorporating LiTFSI for direct cell assembly integration.
Cost tier differentiation separates premium battery-grade certifications from industrial-grade commodity supply.
Application:
Application segmentation tracks how thermal stability requirements above 200 degrees Celsius redirect demand from conventional lithium-ion systems toward next-generation architectures.
- Lithium Batteries:Primary application spanning liquid-electrolyte lithium-ion, lithium-metal, and solid-state cell formats. Japan's METI-funded battery consortia are qualifying LiTFSI for silicon-anode and lithium-metal systems where LiPF6 thermal degradation proves prohibitive.
- Energy Storage Systems:Grid-scale and residential battery installations prioritizing calendar life and fire safety over energy density. China's MIIT mandates for energy density improvements are accelerating LiTFSI substitution in premium EV cell segments.
- Fuel Cells:Proton exchange membrane systems utilizing LiTFSI as an ionic liquid additive for humidity management.
- Supercapacitors:High-power density storage devices employing LiTFSI electrolytes for extended voltage windows.
Volume concentration in lithium batteries sustains supplier economies of scale; margin expansion concentrates in energy storage qualification pathways.
End User:
End-user segmentation reflects how carbon footprint disclosure mandates under the EU Battery Regulation reshape procurement authority across downstream sectors.
- Automotive Sector:Cell manufacturers and OEMs specifying electrolyte salts for electric vehicle powertrains. South Korea's K-Battery strategy is consolidating cathode-electrolyte joint ventures in Ulsan that lock multi-year LiTFSI offtake directly with salt producers.
- Aerospace Industry:Stratospheric drone and satellite power system developers requiring extended thermal stability for high-altitude energy storage. Defense and commercial aviation contractors are opening secondary demand channels as qualification pathways mature.
- Electronics Manufacturers:Consumer device and industrial electronics producers integrating LiTFSI in compact battery formats.
- Renewable Energy Providers:Solar and wind farm operators procuring grid-scale storage with enhanced safety profiles.
Procurement scale favors automotive sector volume commitments; technical specification stringency favors aerospace industry premium pricing.
Distribution Channel:
Channel segmentation tracks how South Korean cell producers are compressing supplier tiers through direct contracting strategies that bypass traditional formulation intermediaries.
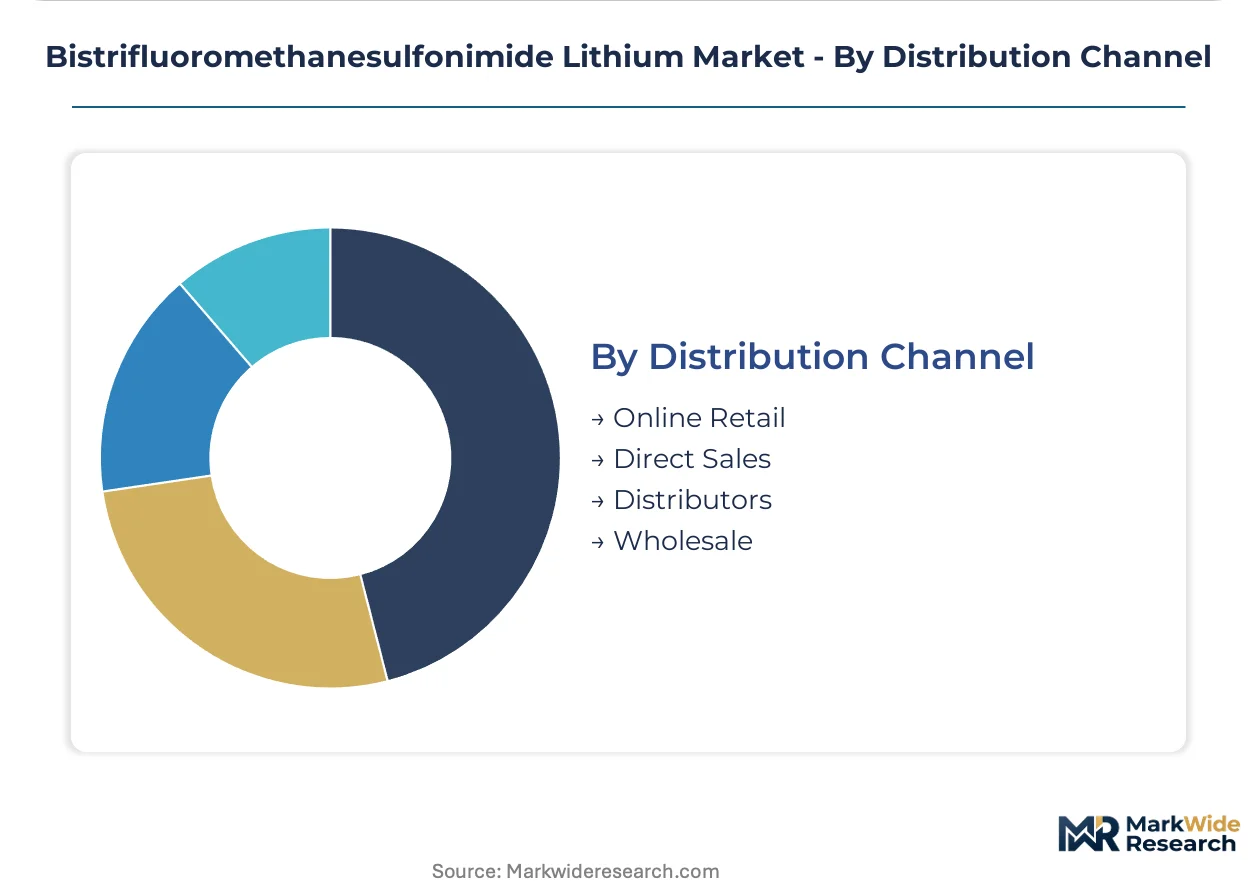
- Direct Sales:Long-term supply agreements between LiTFSI manufacturers and cathode or cell producers. South Korea's K-Battery industrial policy is accelerating channel compression as cathode plants in Incheon and Ulsan form integrated joint ventures with salt suppliers.
- Distributors:Specialty chemical distributors handling qualification documentation and regional logistics for mid-scale cell producers.
- Online Retail:E-commerce platforms serving research institutions and pilot-scale battery developers with small-batch procurement.
- Wholesale:Volume traders supplying commodity-grade LiTFSI for industrial applications outside battery certification pathways.
Contract security favors direct sales for battery-grade volumes; spot flexibility favors distributors for qualification sampling and process development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorinated precursor supply and cathode manufacturing capacity cluster disproportionately across East Asian chemical corridors and select European industrial zones. Regulatory divergence on purity certification is fragmenting qualification pathways by geography.
South Korea
Cell producers in Ulsan and Incheon are compressing supplier certification cycles for solid-state catholyte programs. The K-Battery strategy directs state support toward integrated cathode-electrolyte joint ventures. Samsung SDI and LG Energy Solution procurement teams are locking five-year offtake agreements directly with salt manufacturers, bypassing traditional formulation intermediaries.
Japan
METI-funded battery consortia are qualifying LiTFSI for silicon-anode and lithium-metal systems where thermal stability requirements exclude conventional salts. JIS standards for battery materials enforce sub-ppm halide thresholds that disqualify commodity-grade imports. The Kansai chemical corridor around Osaka anchors halide-free synthesis development for next-generation solid-state architectures.
China
MIIT mandates for energy density improvements in EV cells are accelerating substitution of LiPF6 with thermally stable alternatives. GB/T standards for lithium battery materials tighten impurity thresholds annually. Yangtze River Delta cathode plants in Jiangsu and Zhejiang provinces are absorbing expanding domestic LiTFSI output for high-nickel cell formats.
Germany
ECHA REACH registration requirements impose six-figure compliance burdens that exclude non-integrated producers from European cell supply chains. The EU Battery Regulation's carbon footprint declarations are reshaping sourcing decisions for electrolyte salts. BASF and Volkswagen-backed battery assembly plants in Lower Saxony and Baden-Württemberg are consolidating supplier bases to qualified partners with certified lifecycle data systems.
United States
IRA production tax credits for domestic battery manufacturing are attracting electrolyte salt qualification programs. EPA and OSHA oversight of fluorinated chemical production elevates compliance costs for imported material. Michigan and Ohio-based cell plants are evaluating North American purification capacity to reduce trans-Pacific supply exposure.
Bistrifluoromethanesulfonimide Lithium Market Competitive Landscape
Concentration sits with integrated fluorochemistry platforms possessing captive precursor supply and multi-stage purification capabilities. The supplier base fragments across three tiers: battery-grade certified producers commanding premium pricing, industrial-grade commodity suppliers serving non-automotive applications, and emerging entrants seeking qualification pathways. Strategic moves center on backward integration into trifluoromethanesulfonyl chloride production and long-term offtake contracting with cathode manufacturers.
Among European integrated chemical producers, Solvay S.A. anchors the premium tier through its fluorochemistry platform controlling precursor supply across manufacturing nodes. Japanese specialty chemical houses occupy positions defined by halide purification expertise; Mitsubishi Chemical Corporation exemplifies this archetype through long-term catholyte partnerships with South Korean cell producers. Chinese material suppliers including Tinci Materials represent the scale-driven segment serving domestic cathode expansion.
| Leading Market Players |
|---|
| Solvay S.A. |
| Mitsubishi Chemical Corporation |
| Tinci Materials |
| Zhangjiagang Hicomer Chemical Co., Ltd. |
| Jiangsu Guotai Super Power New Materials Co., Ltd. |
| Central Glass Co., Ltd. |
| Nippon Shokubai Co., Ltd. |
| 3M |
| Morita Chemical Industries Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracting locks in both supply access and price visibility for bistrifluoromethanesulfonimide lithium, as South Korean cell producers bypass merchant electrolyte blenders to secure five-year volume commitments directly with salt manufacturers ahead of solid-state production ramps.
Pricing Analysis
EU Battery Regulation dictates the pricing tier structure across the bistrifluoromethanesulfonimide lithium market, enforcing carbon footprint declarations and recycled content mandates that separate certified battery-grade supply from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects halide contamination thresholds and REACH registration status, with ultra-high-purity grades above 99.9 percent commanding substantial premiums. Cost compression in standard grades is intensifying because LiPF6 retains cost advantages in liquid electrolyte applications, limiting LiTFSI penetration in price-sensitive cell segments. Automotive OEM procurement teams demonstrate lowest price sensitivity due to performance requirements, while industrial electronics manufacturers remain most responsive to per-kilogram differentials.
Supply Chain Analysis
Trifluoromethanesulfonyl chloride precursor supply concentrates among Japanese and Chinese specialty chemical producers, exposing non-integrated salt manufacturers to input volatility and qualification bottlenecks. Manufacturing gravity centers on South Korea, Japan, and Germany, with each corridor feeding distinct regional cell assembly networks. Raw material dependencies draw from fluorinated intermediate streams, lithium carbonate feedstock, and specialized crystallization equipment. Single-source vulnerability runs through the Yangtze River Delta and Kansai chemical corridors where halide purification expertise concentrates. Distribution runs through direct sales channels for battery-grade volumes, with specialty chemical distributors handling mid-scale qualification sampling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bistrifluoromethanesulfonimide lithium market demands substitution defense against lithium hexafluorophosphate cost-performance parity, as established LiPF6 supply chains threaten to cap penetration in price-sensitive liquid electrolyte segments.
For Market Incumbents: Fortify captive precursor control through backward integration into trifluoromethanesulfonyl chloride production, eliminating exposure to Japanese and Chinese specialty chemical concentration. Deepen certification investments for EU Battery Regulation carbon footprint compliance, securing preferred supplier status at BASF and Volkswagen-backed battery assembly plants in Lower Saxony. Lock multi-year offtake agreements with South Korean cathode-electrolyte joint ventures before qualification timelines compress further. For New Entrants and Emerging Players: Anchor in India's PLI scheme for advanced chemistry cells, establishing local purification capacity ahead of cathode plant commissioning in Gujarat and Tamil Nadu. Target aerospace high-altitude storage qualification pathways where extended thermal stability requirements favor LiTFSI over conventional salts and incumbent supplier relationships remain underdeveloped. Pursue direct catholyte supply contracts with solid-state cell developers, bypassing formulation intermediaries to capture margin pools. For Investors and Strategic Acquirers: Capital is best deployed toward integrated fluorochemistry platforms with captive precursor supply and existing REACH registration dossiers, as six-figure compliance burdens exclude mid-scale entrants from European commercial supply. Monitor halide-free synthesis pathway maturation as the inflection indicator for technology divergence between premium and commodity grade positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursors | Captive trifluoromethanesulfonyl chloride supply eliminates input volatility from Japanese and Chinese concentration. |
| REACH Registration Completion | Full substance dossier unlocks European cell supply chains under ECHA requirements. |
| Halide-Free Synthesis Development | Non-halide routes command premium pricing from Japan and South Korea solid-state developers. |
| Direct Catholyte Partnerships | Long-term agreements with Samsung SDI and LG Energy Solution bypass merchant electrolyte blenders. |
| India Purification Capacity Buildout | Domestic manufacturing incentives create first-mover positioning ahead of cathode plant commissioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, chemical industry association reports, and SEC filings from listed specialty chemical producers, combining interviews with plant managers, procurement leads at cathode manufacturers, and technical R&D directors with bottom-up and top-down triangulation. Primary engagement spanned electrolyte salt producers, solid-state battery developers, and regulatory compliance officers across European, East Asian, and North American manufacturing corridors.
Segmentation dimensions modeled include purity grade tier, application specification, end-user sector, and regional regulatory cluster across the projection horizon. CAGRs were derived through demand-side build-up from cathode manufacturing capacity announcements and supply-side validation against fluorinated precursor availability. Forecast inputs incorporated solid-state battery commercialization timelines, EU Battery Regulation implementation phases, and China's MIIT energy density mandates without year-specific anchoring.
Decision-makers should treat outputs as directional under assumptions of sustained solid-state battery development and stable fluorinated precursor supply; material deviation in lithium-metal anode qualification rates or trifluoromethanesulfonyl chloride availability would warrant model refresh. Practitioners should keep alternative scenarios live as REACH disclosure requirements and carbon footprint certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Tallow Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market