
 South America Lactic Acid Market | 2026-2036
South America Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
South America Lactic Acid Market Analytics
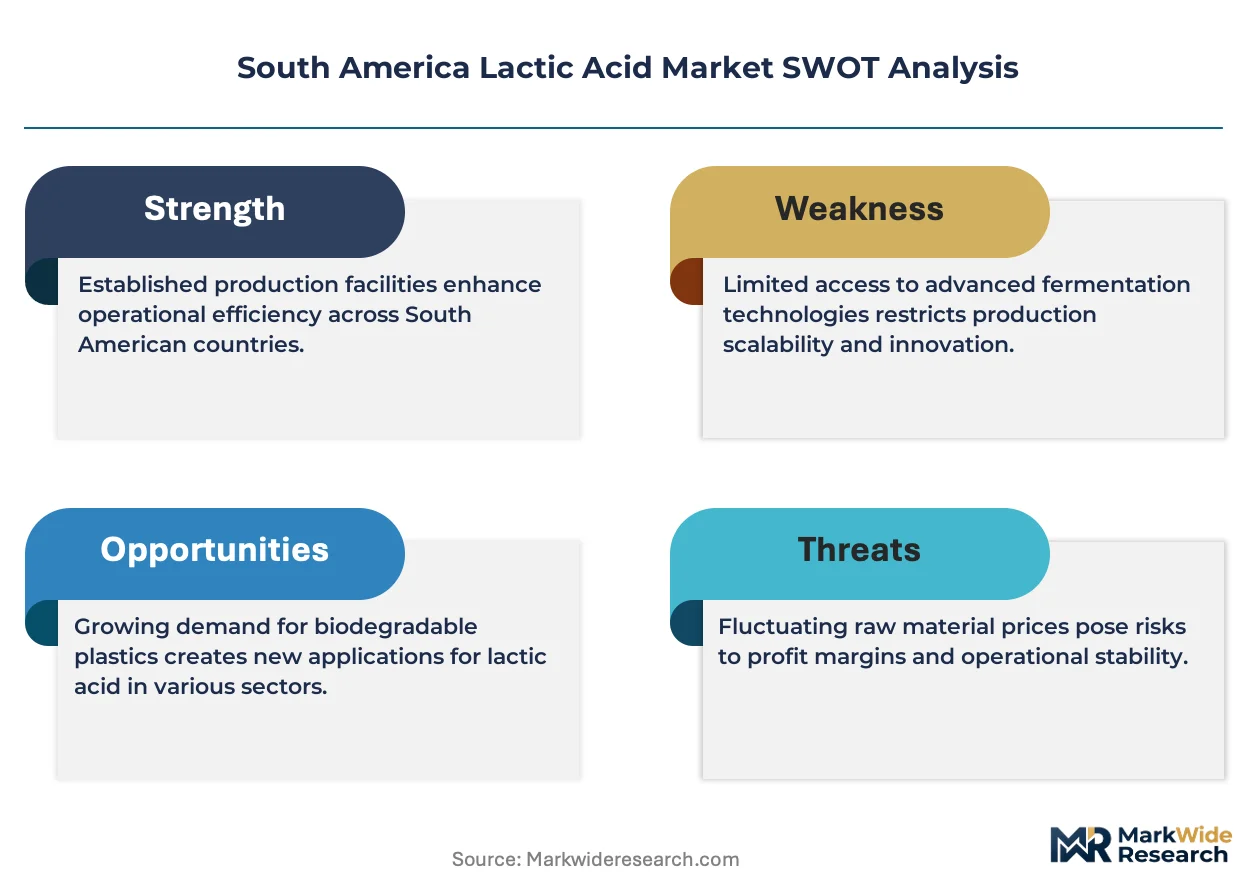
The price spread between pharmaceutical-grade and commodity food-grade lactic acid is hardening across South American trade channels. Corbion leverages its captive fermentation capacity in Brazil to sustain margin on high-purity grades, while Cargill anchors regional supply through its corn-derived feedstock network. Jungbunzlauer Suisse AG competes on citric-to-lactic acid substitution chemistry, and Galactic differentiates via specialized lactide intermediates for polymerization.
Lactic acid is a carboxylic acid produced via carbohydrate fermentation, typically achieving concentrations of 80-90% before purification into technical, food, or pharmaceutical grades. The compound serves as a pH regulator, preservative, and chiral building block for biodegradable polymer synthesis. Polylactic acid dominates value capture due to its thermoplastic properties and compostability profile, while food and beverage applications occupy volume leadership through preservative and flavoring functions. Pharmaceutical-grade L-lactic acid registers the fastest structural expansion, driven by parenteral solution and medical device biocompatibility standards.
ANVISA governs pharmaceutical-grade purity thresholds in Brazil, while Argentina's national bioeconomy framework incentivizes fermentation-based chemical production. REACH-aligned import standards from MERCOSUR trade partners constrain non-EU-certified material entry. Stakeholders must monitor regulatory divergence between Brazilian pharmaceutical mandates and Argentine industrial policy to align capacity investments with enforceable compliance pathways.
Market Dynamics
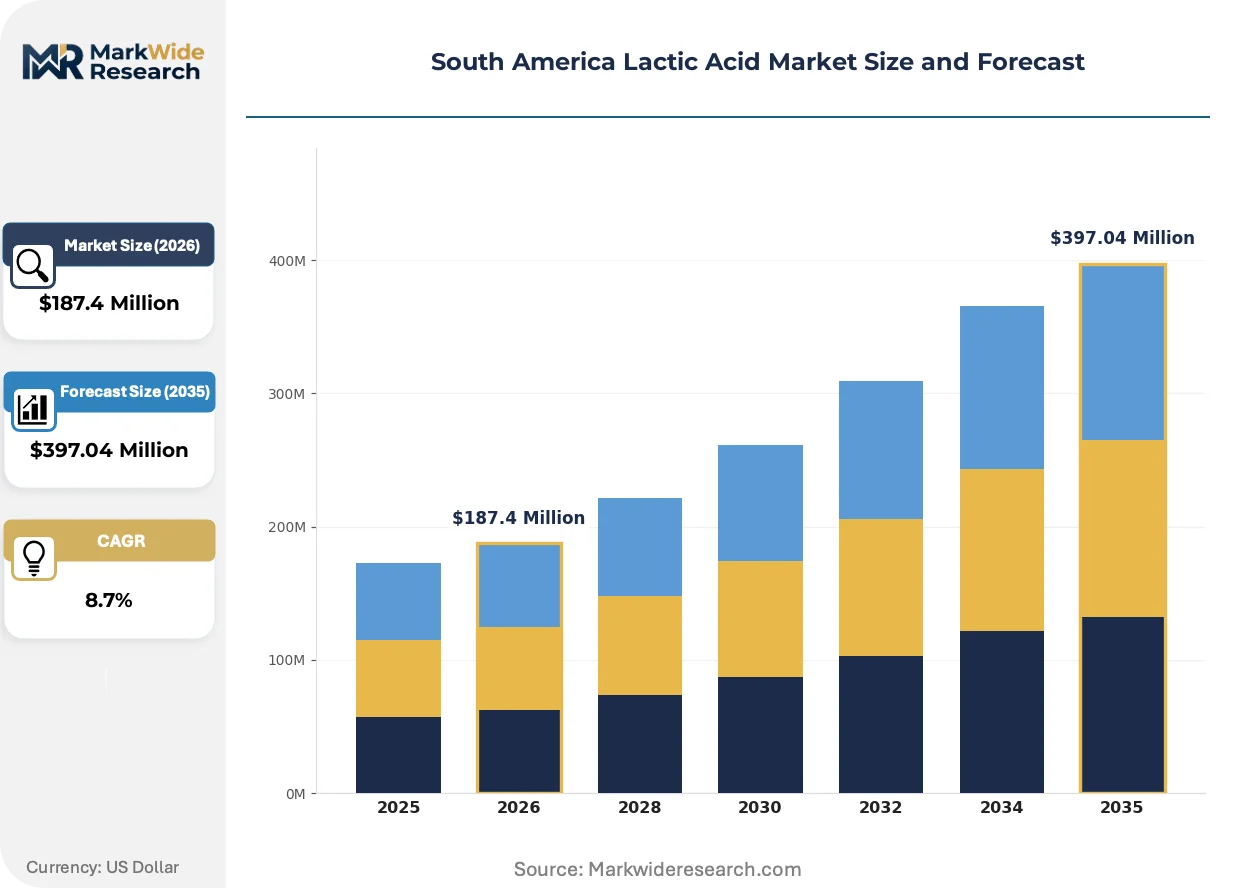
Fermentation-based production capacity in Brazil's São Paulo industrial corridor is redirecting capital flows as ANVISA pharmaceutical-grade certification requirements harden purity thresholds. This structural shift compresses margins for commodity-grade producers while concentrating value capture among certified fermentation operators.
Growth Catalysts
- ANVISA pharmaceutical-grade mandates:Brazil's national health surveillance agency tightened purity specifications for parenteral applications, forcing import substitution toward domestic fermentation capacity.
- Polylactic acid feedstock procurement:Biodegradable plastics manufacturers across Brazil's packaging sector expanded long-term offtake agreements for polymer-grade lactic acid.
- Argentina's bioeconomy incentives:Federal tax credits for fermentation-based chemical production redirected Argentine corn processors toward lactic acid diversification.
Market Restraints
- Corn feedstock price volatility:Brazilian grain markets exposed fermentation operators to input cost swings that compress margin stability during planting cycle disruptions.
- Supply concentration in São Paulo state:Over two-thirds of certified fermentation capacity clusters within a single Brazilian industrial corridor, creating geographic risk exposure.
- Citric acid substitution chemistry:Jungbunzlauer's citric-to-lactic acid substitution technology threatens price premiums in food-grade preservative applications.
Strategic Opportunities
- Underpenetrated Andean markets:Colombia and Peru lack domestic fermentation infrastructure, creating import substitution potential for Brazilian certified producers.
- Medical device biocompatibility standards:Emerging surgical suture and orthopedic implant applications demand pharmaceutical-grade L-lactic acid with chiral purity specifications.
- MERCOSUR REACH alignment:Converging import standards with European chemical registration frameworks open duty-advantaged export channels for certified Brazilian material.
Industry Challenges
- ANVISA certification timeline compression:Pharmaceutical-grade approval cycles now extend eighteen to twenty-four months, freezing capacity deployment schedules.
- Fermentation strain IP fragmentation:Proprietary Lactobacillus delbrueckii subspecies licensing across Brazilian, Argentine, and European patent holders complicates technology access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Lactic Acid Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DL-Lactic Acid, L-Lactic Acid, Polylactic Acid, Lactic Acid Derivatives Application: Food & Beverage, Pharmaceuticals, Biodegradable Plastics, Personal Care End User: Food Manufacturers, Beverage Companies, Cosmetic Brands, Medical Device Manufacturers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Corbion, Cargill, BASF SE, Galactic, Dow, NatureWorks LLC, Henan Jindan Lactic Acid Technology Co. Ltd., Jungbunzlauer Suisse AG, Musashino Chemical Laboratory Ltd., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Lactic Acid Market Evolving Landscape
Continuous fermentation technology is displacing batch processes across Brazilian installed capacity, while regulatory convergence between ANVISA and European pharmacopeia standards reconfigures certification economics. These forces reshape competitive positioning around purity tier differentiation.
Membrane filtration purification is expanding into pharmaceutical-grade production lines, replacing solvent-based crystallization with electrodialysis and nanofiltration cascades. Brazilian fermentation operators adopting this technology achieve chiral purity thresholds exceeding ANVISA specifications. The capital efficiency of this approach is compressing payback periods for certified capacity expansions.
ANVISA's pharmaceutical-grade monograph revision aligns purity testing protocols with European Pharmacopoeia 11.0 standards, eliminating redundant certification costs for export-oriented Brazilian producers. This regulatory convergence accelerates MERCOSUR-EU trade corridor development for high-purity lactic acid. Argentine fermentation projects now design for dual-certification compliance from commissioning.
Long-term offtake contracting is displacing spot market procurement across Brazil's polylactic acid feedstock buyers. Biodegradable plastics manufacturers now secure three-to-five-year supply agreements with price collars indexed to corn futures. This pattern concentrates most visible in São Paulo state's packaging industrial cluster, where polymerization facilities demand supply certainty for capital-intensive lactide reactor investments.
South America Lactic Acid Market Segmentation
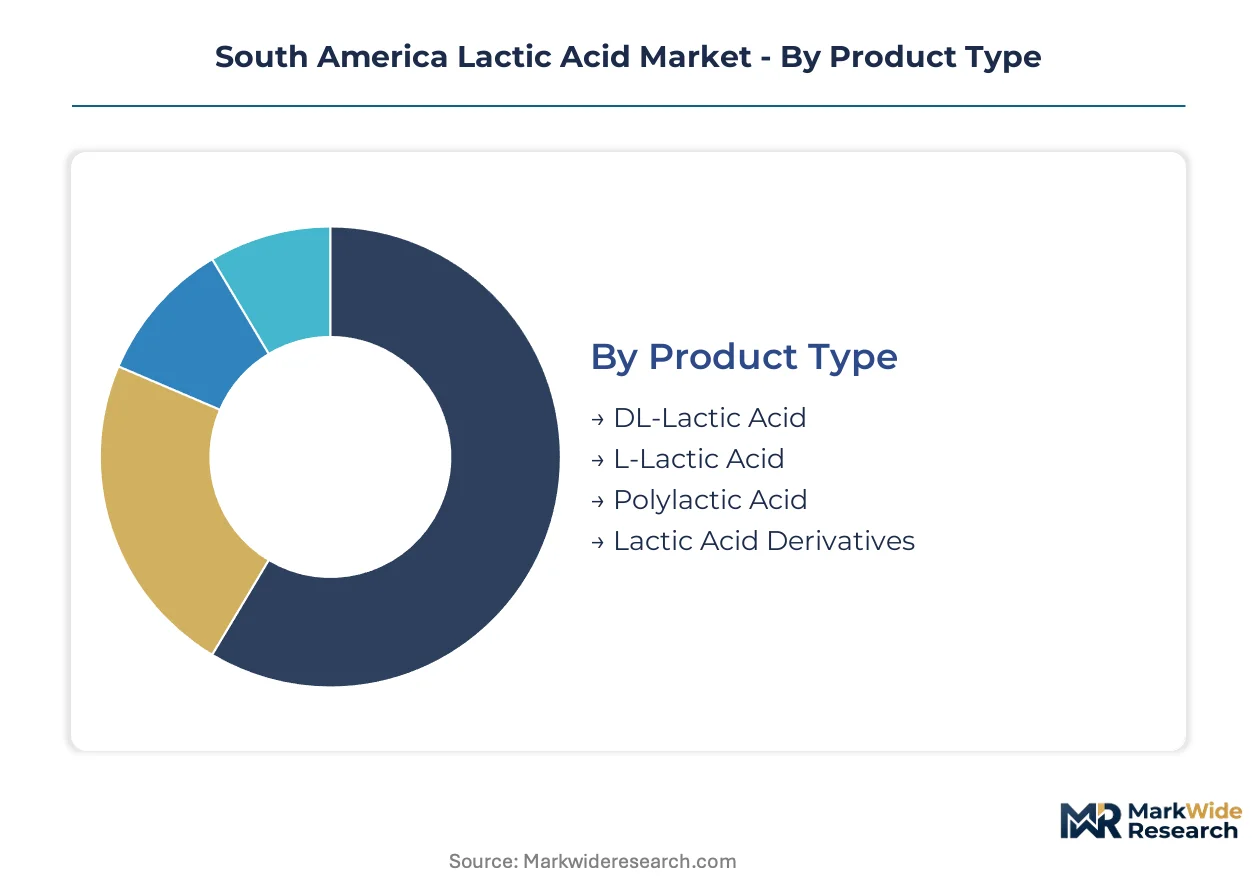
Lactic acid segmentation in South America reflects divergent purity requirements across end-use verticals. Pharmaceutical-grade certification thresholds and polylactic acid polymerization specifications create distinct commercial tiers with margin structures that reward chiral purity and fermentation process control.
Product Type:
DL-Lactic acid operates as a standalone commodity input for industrial applications, while L-lactic acid and polylactic acid embed into higher-value downstream systems requiring stereochemical precision.
- DL-Lactic Acid:Racemic mixture produced through chemical synthesis or non-selective fermentation serves as a low-cost pH regulator and industrial chemical precursor. Demand concentrates in Brazil's São Paulo state food processing corridor, where preservative applications tolerate optical impurity in exchange for cost efficiency.
- L-Lactic Acid:Enantiomerically pure form achieved through Lactobacillus delbrueckii subspecies fermentation commands premium positioning for pharmaceutical and polymer-grade specifications. ANVISA's tightened parenteral solution mandates are redirecting procurement toward certified Brazilian fermentation capacity.
- Polylactic Acid:Ring-opening polymerization of lactide intermediates yields biodegradable thermoplastics with compostability certification for packaging applications.
- Lactic Acid Derivatives:Esterified and oligomerized forms including lactate esters and polyols extend functionality into solvent and surfactant applications.
DL-lactic acid leads volumes today; L-lactic acid is gaining share fastest.
Application:
Application segmentation tracks the cost-to-performance gradient from bulk preservative functions through medical-grade biocompatibility requirements.
- Food & Beverage:Volume anchor consuming technical and food-grade material for pH adjustment, microbial inhibition, and flavor modulation across processed meat, dairy, and beverage categories. Brazilian processors in Minas Gerais and Rio Grande do Sul states represent concentrated procurement.
- Pharmaceuticals:Parenteral solutions, dialysis fluids, and excipient applications demand pharmaceutical-grade L-lactic acid with chiral purity exceeding ANVISA monograph specifications. Sterile manufacturing requirements in Brazil's São Paulo pharmaceutical cluster sustain import substitution momentum.
- Biodegradable Plastics:Polymer-grade feedstock for polylactic acid resin production serves packaging converters seeking compostability certification under MERCOSUR environmental standards.
- Personal Care:Alpha-hydroxy acid functionality drives cosmetic formulation demand for exfoliation and pH buffering in skincare products.
Food and beverage anchors volume; pharmaceuticals climbs the fastest.
End User:
End user segmentation distinguishes between formulation-integrated buyers and standalone chemical processors with varying technical service requirements.
- Food Manufacturers:Meat processors, dairy cooperatives, and prepared food producers integrate lactic acid directly into preservation systems. Brazilian giants in Santa Catarina's protein processing belt negotiate long-term supply agreements indexed to corn futures.
- Beverage Companies:Soft drink and brewing operations employ lactic acid for pH stability and flavor balance in acidified formulations.
- Cosmetic Brands:Formulators source USP-grade material for alpha-hydroxy acid skincare positioning, with Argentine and Brazilian beauty markets driving regional consumption.
- Medical Device Manufacturers:Surgical suture, orthopedic implant, and drug delivery system producers specify pharmaceutical-grade L-lactic acid with residual monomer controls for biocompatibility certification.
Food manufacturers dominate procurement scale; medical device manufacturers expand most quickly.
Distribution Channel:
Channel segmentation reflects the technical support intensity required across purity grades, with direct relationships dominating pharmaceutical and polymer applications.
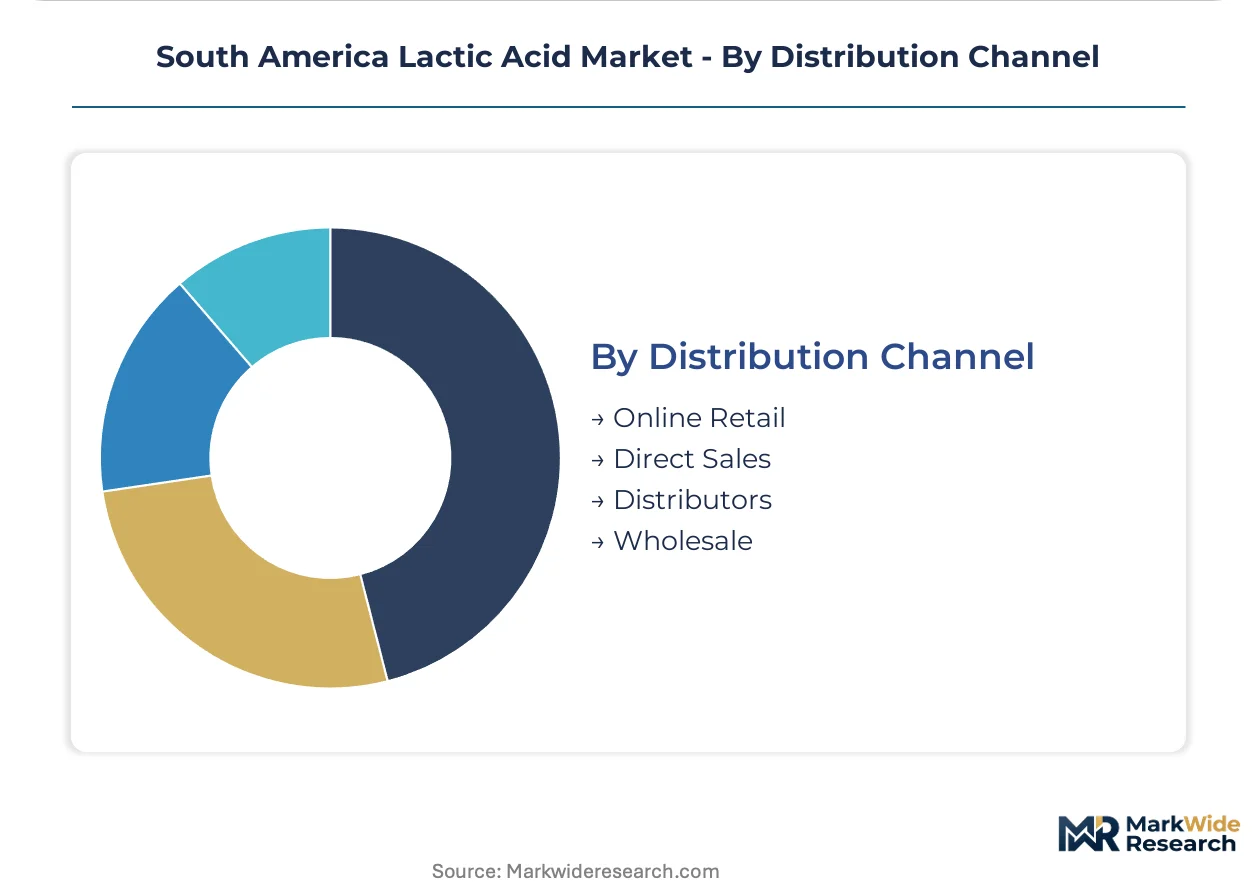
- Direct Sales:Captive supply relationships between Brazilian fermentation operators and polylactic acid polymerization facilities in São Paulo's packaging industrial cluster. Technical service integration including lactide reactor optimization support locks in three-to-five-year offtake structures.
- Distributors:Regional chemical distributors aggregate food-grade and technical-grade volumes for fragmented Brazilian and Argentine processor bases, warehousing inventory in Campinas and Buenos Aires logistics hubs.
- Online Retail:E-commerce platforms serve small-scale cosmetic formulators and research institutions requiring laboratory-scale quantities with rapid fulfillment.
- Wholesale:Bulk terminal operations handle import flows from European and Asian producers for commodity-grade material not covered by domestic fermentation capacity.
Direct sales captures the highest value concentration; distributor channels move the greatest tonnage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation technicians and biochemical engineers concentrate in Brazil's São Paulo industrial corridor, anchoring regional production capacity. Argentina's corn belt supplies feedstock expertise. Chile and Colombia lack comparable talent pools, creating import dependency.
Brazil
Pharmaceutical-grade certification mandates from ANVISA and polylactic acid feedstock procurement from biodegradable plastics manufacturers drive demand. The national health surveillance agency tightened parenteral solution purity specifications, forcing import substitution toward domestic fermentation capacity. São Paulo state's industrial corridor hosts over two-thirds of certified fermentation installations, with Campinas and Piracicaba anchoring technical-grade production clusters.
Argentina
Federal bioeconomy tax credits redirect corn processors toward lactic acid diversification, while pharmaceutical-grade import substitution creates fermentation investment incentives. The national bioeconomy framework incentivizes fermentation-based chemical production through production tax credits. Buenos Aires province and Córdoba's agro-industrial belt concentrate project development, with Rosario's grain terminal network supplying feedstock logistics.
Chile
Cosmetic formulation demand for alpha-hydroxy acid functionality and food preservative applications sustain import volumes. The country's national pharmaceutical regulator enforces USP-grade import standards for parenteral applications. Santiago's metropolitan manufacturing cluster and Valparaíso's chemical import terminals handle regional distribution, with no domestic fermentation infrastructure operational.
Colombia
Processed food sector expansion and emerging biodegradable packaging regulations create latent demand for technical and polymer-grade material. The national food and drug surveillance institute governs food-grade additive approvals. Bogotá's pharmaceutical manufacturing corridor and Medellín's plastics processing cluster rely entirely on Brazilian and Argentine imports, presenting substitution opportunities for certified exporters.
Peru
Personal care product manufacturing growth and beverage industry pH regulation requirements sustain modest import volumes. The national health authority oversees cosmetic and pharmaceutical-grade material registration. Lima's coastal industrial zone and Arequipa's food processing belt represent concentrated demand nodes without domestic production capability.
South America Lactic Acid Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification, while commodity-grade producers compete on corn feedstock access and fermentation scale. The market exhibits tiered concentration around purity-grade capabilities rather than geographic coverage. Three archetypes dominate: integrated fermentation-to-polymer operators, diversified agricultural processors with biochemical divisions, and specialized pharmaceutical-grade refiners. Capacity expansion and long-term offtake contracting constitute the dominant competitive moves, with ANVISA certification timelines determining effective deployment speed.
Within the integrated fermentation tier, Corbion and Cargill exemplify divergent strategic positions. Corbion leverages its Brazilian captive fermentation infrastructure to serve pharmaceutical-grade demand, while Cargill anchors regional supply through its corn-derived feedstock network spanning agricultural procurement and biochemical processing. Jungbunzlauer Suisse AG occupies a substitution-specialist position, competing on citric-to-lactic acid chemistry rather than fermentation purity. Galactic represents the polymer-intermediate archetype, differentiating via specialized lactide production for downstream polymerization.
| Leading Market Players |
|---|
| Corbion |
| Cargill |
| BASF SE |
| Galactic |
| Dow |
| NatureWorks LLC |
| Henan Jindan Lactic Acid Technology Co. Ltd. |
| Jungbunzlauer Suisse AG |
| Musashino Chemical Laboratory Ltd. |
| Others |
Value Network & Pricing Analysis
Specialized fermentation technicians in Brazil's São Paulo industrial corridor command wage premiums that compress margins for commodity-grade producers while sustaining spreads for pharmaceutical-grade certification. Labor-cost differentials between certified and uncertified production tiers widen pricing stratification across Brazilian and Argentine supply channels.
Pricing Analysis
Service bundling separates certified fermentation operators from commodity traders. Three-tier pricing structure across pharmaceutical, food-grade, and technical levels tracks ANVISA certification status and chiral purity specifications. Cost compression in commodity grades intensifies because Jungbunzlauer's citric acid substitution erodes preservative premiums. Food manufacturers exhibit highest price sensitivity; medical device manufacturers accept substantial premiums for biocompatibility-grade material.
Supply Chain Analysis
ANVISA qualification gates upstream access for pharmaceutical-grade feedstock, concentrating certified capacity among Brazilian fermentation operators with validated Lactobacillus strains. Supply draws from Brazil, Argentina, and import terminals in Chile and Colombia. Corn feedstock, proprietary fermentation inoculants, and membrane filtration equipment anchor input dependencies. Single-source vulnerability clusters in São Paulo state's industrial corridor where two-thirds of certified capacity operates. Distribution runs through direct offtake contracts for polymer-grade buyers and regional chemical distributors for fragmented food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America lactic acid market compounds steadily as biodegradable plastics mandates across MERCOSUR jurisdictions sustain structural demand growth for polymer-grade feedstock.
For Market Incumbents: Hedge against citric acid substitution by deepening captive lactide intermediate production for polylactic acid polymerization facilities. Secure long-term corn supply agreements indexed to futures to buffer margin volatility from Brazilian grain market swings. Prioritize ANVISA-European Pharmacopoeia dual certification to capture export-advantaged positioning. For New Entrants and Emerging Players: Regional chemical distributors in Colombia and Peru represent the most accessible channel partners for import substitution plays. Target pharmaceutical-grade L-lactic acid for parenteral applications where ANVISA mandates have displaced European imports. Enter through toll manufacturing arrangements with Brazilian fermentation operators to bypass eighteen-month certification timelines. For Investors and Strategic Acquirers: Biodegradable plastics manufacturers are the most active acquirers in this space, seeking backward integration into lactide and lactic acid supply. Five-to-ten-year viability rests on polymer-grade capacity with validated offtake contracts. Monitor ANVISA certification queue lengths as the inflection signal for effective capacity deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Dual Certification Investment | European Pharmacopoeia alignment eliminates redundant testing costs for Brazilian exporters. |
| Long-term Corn Supply Agreement | Indexed contracting buffers São Paulo fermentation operators from Brazilian grain price volatility. |
| Membrane Filtration Technology Adoption | Electrodialysis purification achieves chiral purity thresholds exceeding ANVISA monograph specifications. |
| Andean Distribution Partnership | Colombian and Peruvian channel access addresses import substitution demand without local fermentation infrastructure. |
| Lactide Reactor Co-location | Campinas and Piracicaba clustering reduces logistics costs for polylactic acid polymerization facilities. |
Research Methodology
Bottom-up pharmaceutical and polymer-grade demand modeling reconciled against top-down Brazilian and Argentine fermentation capacity tracking forms the analytical core. Primary interviews with plant managers at São Paulo fermentation facilities, procurement leads at biodegradable plastics manufacturers, ANVISA regulatory affairs specialists, and distribution channel partners in Campinas and Buenos Aires informed capacity and demand assessments. Secondary validation drew from ANVISA certification registries, MERCOSUR trade statistics, SEC filings of publicly traded chemical processors, and Brazilian corn futures market data.
Input-output matrices mapped fermentation feedstock flows through purification tiers to end-use applications across the projection horizon. Segmentation dimensions modeled include product grade tier, application vertical, end-user category, and regional production hub. CAGRs derived from capacity expansion announcements, offtake contract volumes, and regulatory mandate implementation schedules. Forecast inputs incorporated ANVISA certification timeline distributions and polylactic acid polymerization facility commissioning patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MERCOSUR-EU trade agreement negotiations and Brazilian corn harvest variability. Projections reflect assumptions regarding ANVISA regulatory stability and fermentation strain licensing accessibility. A model refresh is warranted upon material change in ANVISA pharmaceutical-grade monograph revision timing or Argentine bioeconomy incentive program renewal.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Adipic Acid Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Barite Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Needle Coke Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market