
 Bulk Chemical Packaging Market | 2026-2036
Bulk Chemical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Chemical Packaging Market Analysis
Market Context
The capital-intensity divergence between integrated drum manufacturers and flexible bag specialists is bifurcating competitive dynamics across the sector. Greif, Inc. leverages its captive steel drum production network across North American industrial corridors. SCHÜTZ GmbH and Co. KGaA anchors European demand through its closed-loop IBC rental and reconditioning infrastructure. Mauser Packaging Solutions sustains margin pools via geographic density in hazardous chemical logistics.
Technical Definition and Segment Structure
Bulk chemical packaging encompasses engineered containment systems designed for transporting and storing liquid, powder, or gaseous chemicals in volumes typically exceeding twenty liters, constructed from plastic resins, carbon steel, fiberboard composites, or aluminum alloys with corrosion-resistant linings and UN-certified closures. These systems prevent contamination, enable hazardous material compliance, and optimize loading efficiency across rail, truck, and maritime freight. Plastic IBC totes capture expanding share in non-hazardous specialty chemicals where tare weight reduction drives freight economics. Steel drums retain dominance in flammable and corrosive petrochemical segments where thermal integrity and crush resistance command premium positioning. Fiber drums occupy niche growth in agricultural powder formulations where cost minimization outweighs reuse requirements.
Regulatory Frame and Outlook
EPA hazardous waste manifest rules, DOT 49 CFR hazardous materials regulations, and UN Recommendations on the Transport of Dangerous Goods collectively mandate performance-tested packaging for chemical shipment across US interstate commerce. ECHA REACH substance restrictions and EU Packaging and Packaging Waste Directive recyclability targets are elevating material traceability requirements for exporters serving European chemical manufacturers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and assess whether reconditioning network investments outpace single-use substitution economics.
Market Dynamics
Reusable IBC rental programs are compressing single-use packaging margins while forcing capital reallocation toward reconditioning infrastructure and reverse logistics networks across chemical manufacturing corridors.
Growth Catalysts
- ECHA REACH substance restrictions:German specialty chemical producers are accelerating reusable tote adoption to demonstrate compliance with extended producer responsibility mandates and reduce hazardous substance exposure documentation burdens.
- US Gulf Coast petrochemical corridor:Export terminal capacity expansion is generating concentrated demand for UN-certified intermediate bulk containers capable of withstanding maritime freight consolidation and multiple handling cycles.
- Lightweight composite materials:Advanced polymer formulations with enhanced chemical resistance are displacing traditional steel in non-hazardous applications where freight cost optimization outweighs thermal protection requirements.
Market Restraints
- Steel price volatility:Carbon steel drum manufacturers face margin compression from scrap metal input cost swings that resist immediate pass-through to long-term chemical supply contracts.
- Reconditioning network concentration:Closed-loop IBC infrastructure remains geographically clustered around Rotterdam, Houston, and Singapore, creating logistics dead zones for inland chemical processors.
- UN certification timeline friction:Performance testing protocols for new container designs extend commercialization cycles by 18-24 months, freezing innovation investment returns.
Strategic Opportunities
- India specialty chemical manufacturing:BIS certification alignment with UN standards is opening import substitution opportunities for domestic IBC producers serving agrochemical and dye intermediate sectors.
- Digital tracking integration:RFID-enabled container lifecycle management converging with blockchain traceability is creating premium service tiers for pharmaceutical and food-grade chemical logistics.
- EU Packaging and Packaging Waste Directive recyclability targets:Mandatory recycled content thresholds are accelerating demand for post-consumer resin IBC totes in cosmetic and personal care chemical supply chains.
Industry Challenges
- Multimodal certification complexity:Harmonizing DOT 49 CFR, IMDG Code, and RID/ADR testing requirements demands specialized regulatory affairs personnel that mid-tier manufacturers struggle to retain.
- Legacy ERP integration:Container tracking systems require real-time data exchange with customer inventory management platforms, forcing expensive middleware development for established packaging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Chemical Packaging Market |
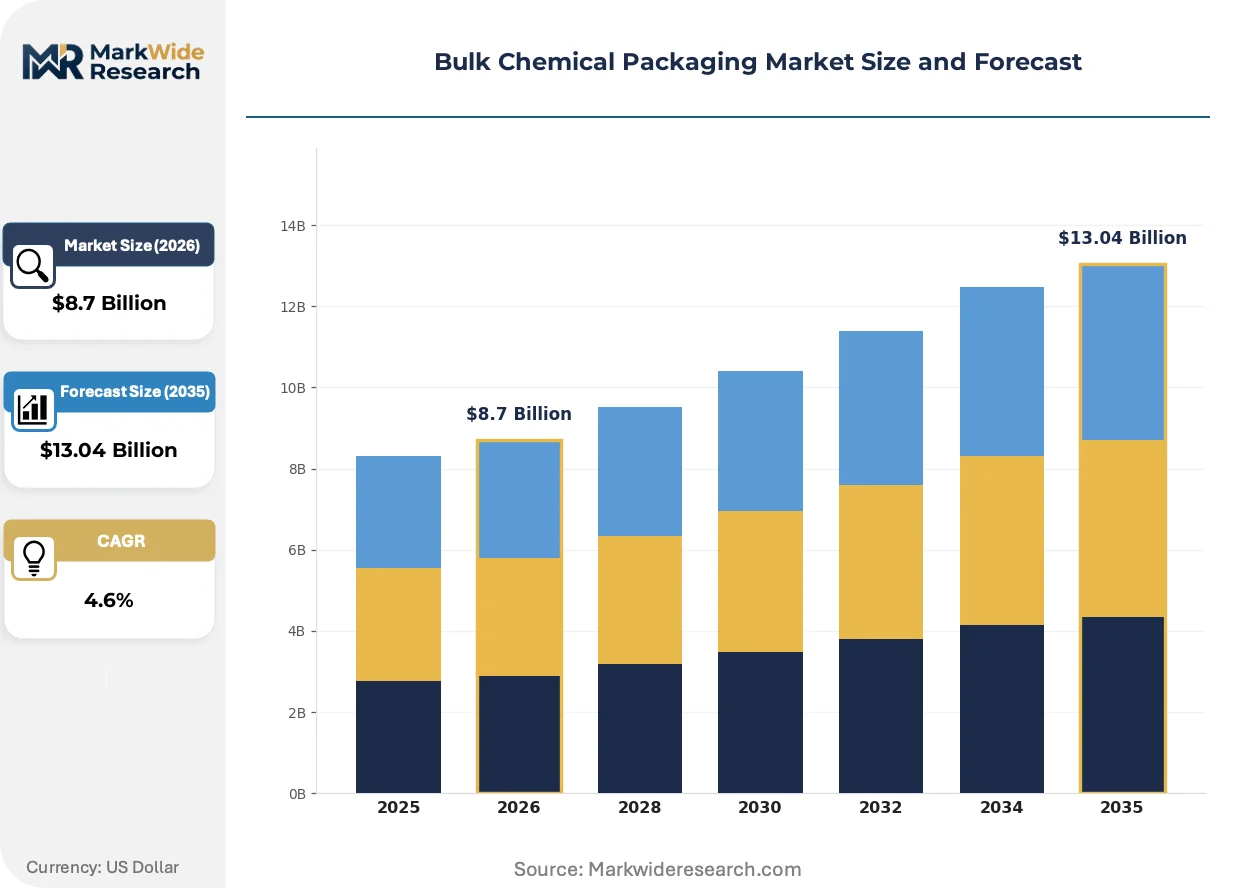
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Drums, IBC Totes, Bags, Containers Material: Plastic, Steel, Fiber, Aluminum End Use Industry: Pharmaceutical, Agriculture, Food & Beverage, Petrochemical Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Berry Global, DS Smith, Greif, Inc., Smurfit Kappa Group, Myers Industries, Mauser Packaging Solutions, Time Technoplast Ltd., Mondi, SCHÜTZ GmbH and Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Chemical Packaging Market Emerging Trajectories
Active intelligence embedded in packaging assets is transforming chemical logistics from a cost center into a data-generating service layer, with sensor-enabled containers now capturing temperature, shock, and location telemetry throughout multimodal transit.
Advanced barrier polymer linings is bifurcating the specialty chemical segment. Fluoropolymer-coated HDPE totes now handle aggressive solvents previously requiring stainless steel, enabling pharmaceutical intermediates producers to reduce tare weight by 60% for air freight. This technology is compressing steel drum demand in high-value, non-flammable chemical categories while creating premium pricing tiers for certified barrier performance.
ECHA REACH authorization requirements are restructuring material selection protocols. Substances of very high concern restrictions are forcing reformulation of adhesives and sealants used in composite IBC construction, triggering supplier qualification cascades through European chemical distribution networks. Affected segments include crop protection and industrial coating supply chains, where container material traceability now accompanies every shipment.
Buyer consolidation among multinational chemical distributors is compressing supplier rosters and extending contract durations. Procurement teams at integrated agrochemical enterprises now demand single-source accountability across drum, tote, and flexitank formats, displacing fragmented vendor relationships. This concentration is most visible in Brazil and Argentina, where regional distributors are ceding volume to global logistics platforms with captive packaging assets.
Bulk Chemical Packaging Market Segmentation
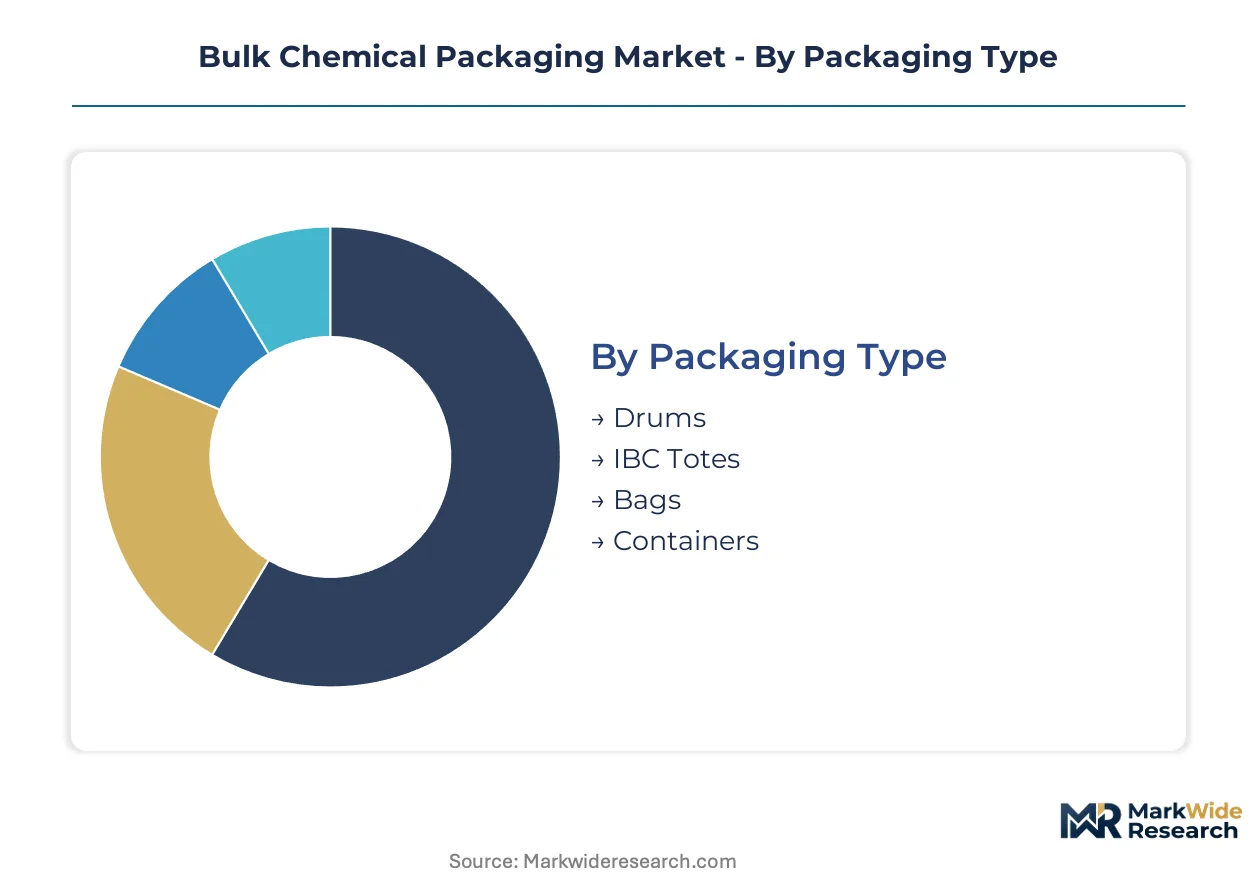
Segmentation in bulk chemical packaging reveals divergent margin structures and capital requirements across containment formats. Each category maps distinct regulatory burdens, reuse economics, and geographic demand patterns that shape supplier positioning and investment priorities.
Packaging Type:
Domestic chemical processors favor drum formats for established supply contracts, while export corridors drive IBC tote demand for maritime consolidation efficiency.
- Drums:Carbon steel and fiber constructions dominate flammable petrochemical logistics where UN-certified thermal integrity commands premium positioning. US Gulf Coast refineries and Rotterdam storage terminals anchor demand for 55-gallon steel formats in cross-border solvent shipments.
- IBC Totes:HDPE composite designs with fluoropolymer linings now handle aggressive pharmaceutical intermediates previously requiring stainless steel, cutting tare weight by 60% for air freight corridors. German specialty chemical producers are accelerating reusable rental programs under ECHA REACH extended producer responsibility mandates.
- Bags:Multi-layer flexitanks serve non-hazardous liquid agricultural formulations where single-use economics outweigh reconditioning costs.
- Containers:ISO tank systems concentrate in intermodal chemical logistics between Houston, Singapore, and Antwerp.
Drums command the established base. The steepest expansion runs through IBC Totes.
Material:
Cost tiers separate commodity resin applications from corrosion-resistant alloys in hazardous chemical segments.
- Plastic:Advanced polymer formulations with enhanced chemical resistance are displacing traditional steel in non-hazardous applications where freight cost optimization outweighs thermal protection requirements. Post-consumer resin IBC totes are gaining share in cosmetic and personal care supply chains facing EU Packaging and Packaging Waste Directive recyclability mandates.
- Steel:Carbon steel drums retain dominance in flammable and corrosive petrochemical segments where thermal integrity and crush resistance command premium positioning. Scrap metal input cost volatility compresses margins for drum manufacturers serving long-term chemical supply contracts.
- Fiber:Fiberboard drums occupy niche growth in agricultural powder formulations where cost minimization outweighs reuse requirements.
- Aluminum:Lightweight alloy containers serve high-value pharmaceutical intermediates where contamination prevention justifies material premiums.
Plastic formats are climbing the fastest on lightweighting and regulatory tailwinds. Steel retains the volume anchor in hazardous segments.
End Use Industry:
Application-specific certification requirements create divergent supplier qualification barriers and contract durations.
- Pharmaceutical:FDA and EMA compliance mandates drive RFID-enabled container lifecycle management with blockchain traceability for premium service tiers. Fluoropolymer-coated HDPE totes now handle aggressive solvents previously requiring stainless steel in pharmaceutical intermediate logistics.
- Agriculture:BIS certification alignment with UN standards is opening import substitution opportunities for domestic IBC producers serving Indian agrochemical and dye intermediate sectors. Multi-layer flexitanks dominate liquid fertilizer formulations.
- Food & Beverage:Food-grade chemical logistics demand specialized barrier linings and contamination prevention protocols.
- Petrochemical:Export terminal capacity expansion along the US Gulf Coast generates concentrated demand for UN-certified intermediate bulk containers capable of withstanding maritime freight consolidation and multiple handling cycles.
Petrochemical applications anchor volume scale. Pharmaceutical segments generate the steepest margin expansion through certification premiums.
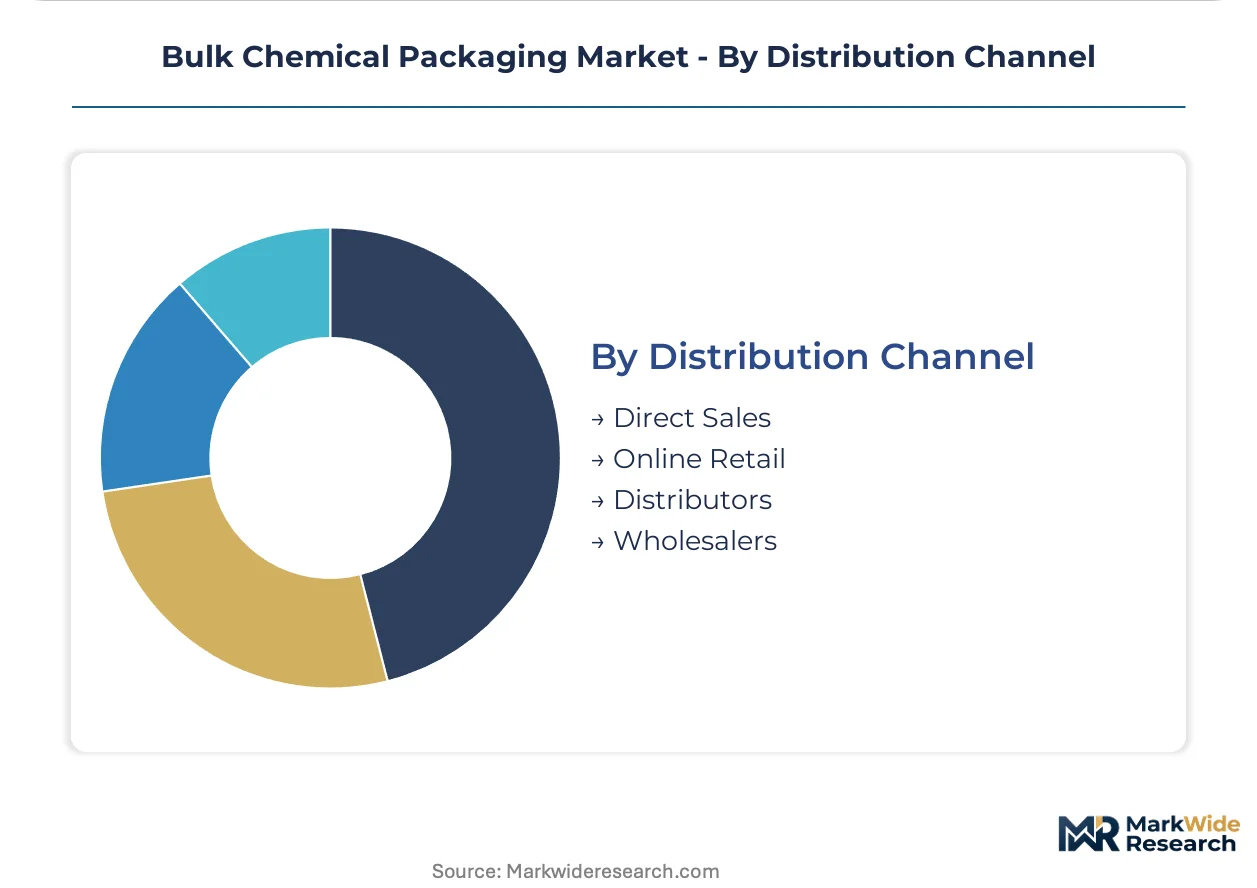
Distribution Channel:
Customer type and procurement scale determine channel selection, with integrated chemical enterprises consolidating vendor relationships.
- Direct Sales:Multinational chemical distributors are compressing supplier rosters and extending contract durations, demanding single-source accountability across drum, tote, and flexitank formats. Procurement teams at integrated agrochemical enterprises in Brazil and Argentina are ceding volume to global logistics platforms with captive packaging assets.
- Distributors:Regional packaging distributors serve mid-tier chemical processors lacking reverse logistics infrastructure for reusable container programs.
- Wholesalers:Volume aggregation points for standard drum formats in fragmented agricultural chemical markets.
- Online Retail:Emerging channel for standardized container specifications in small-batch specialty chemical procurement.
Direct Sales commands contract value concentration. Distributor relationships are gaining share fastest among mid-tier processors seeking logistics outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German specialty chemical producers leveraging closed-loop IBC rental infrastructure, while US Gulf Coast exporters absorb freight cost volatility through steel drum volume commitments. Rotterdam and Singapore reconditioning hubs command premium logistics margins unavailable to inland processors.
United States
Export terminal capacity expansion along the Houston Ship Channel and Corpus Christi drives UN-certified IBC demand for maritime freight consolidation. EPA hazardous waste manifest rules and DOT 49 CFR regulations mandate performance-tested packaging for interstate chemical shipments. The Permian Basin petrochemical corridor anchors steel drum consumption for flammable solvent logistics serving Latin American export markets.
Germany
Specialty chemical producers in Ludwigshafen and Leverkusen accelerate reusable tote adoption to satisfy ECHA REACH extended producer responsibility mandates. The EU Packaging and Packaging Waste Directive recyclability targets elevate material traceability requirements for container suppliers. Bavarian industrial clusters around Munich develop fluoropolymer-lined HDPE systems for pharmaceutical intermediate air freight.
China
Yangtze River Delta chemical processors expand domestic IBC manufacturing capacity to reduce import dependence for agrochemical packaging. NMPA alignment with UN testing standards accelerates certification timelines for local producers. The Shanghai-Pudong logistics corridor concentrates flexitank demand for liquid fertilizer export consolidation.
India
BIS certification harmonization with UN standards opens import substitution opportunities for domestic IBC producers serving Gujarat's dye intermediate sector. CDSCO pharmaceutical regulations drive RFID-enabled container traceability requirements for active ingredient logistics. Maharashtra's Mumbai-Pune industrial belt anchors steel drum demand for hazardous chemical distribution.
Brazil
São Paulo-based agrochemical distributors consolidate vendor relationships under ANVISA compliance frameworks for crop protection chemical logistics. Regional packaging suppliers cede volume to global logistics platforms with captive IBC assets. The Santos port complex generates concentrated demand for multi-layer flexitanks in liquid fertilizer export operations.
Bulk Chemical Packaging Market Vendor Landscape
Concentration sits with integrated drum manufacturers and closed-loop IBC rental operators commanding geographic density in chemical manufacturing corridors. The vendor base stratifies across three tiers: multinational steel drum networks, European reconditioning specialists, and emerging composite fabricators. Dominant competitive moves include reconditioning infrastructure expansion and backward integration into resin compounding for barrier polymer formulations.
Within the integrated packaging tier, Greif, Inc. and Mauser Packaging Solutions exemplify scale-driven operators with captive production networks across North American industrial corridors. SCHÜTZ GmbH and Co. KGaA occupies a position representing European closed-loop rental specialization. Berry Global and Mondi sit within the materials science archetype, leveraging polymer formulation capabilities for advanced barrier applications. These named entities anchor competitive dynamics without exhausting the strategic landscape.
| Leading Market Players |
|---|
| Berry Global |
| DS Smith |
| Greif, Inc. |
| Smurfit Kappa Group |
| Myers Industries |
| Mauser Packaging Solutions |
| Time Technoplast Ltd. |
| Mondi |
| SCHÜTZ GmbH and Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Ninety-day UN certification lead times for new IBC designs compress pricing power for composite fabricators while amplifying premiums for established reconditioning networks with pre-certified container pools. This inventory-service tradeoff concentrates margin capture with Rotterdam and Houston hub operators who bridge supply gaps for inland German and US Gulf Coast chemical processors.
Pricing Analysis
Customization-premium spreads widen substantially between standard HDPE totes and fluoropolymer-lined configurations for pharmaceutical intermediates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with UN-certified steel drums commanding material premiums over non-hazardous plastic alternatives. Cost compression in standard resin formats is intensifying because post-consumer resin supply constraints resist immediate scale-up. Mid-tier agricultural chemical distributors exhibit highest price sensitivity, while pharmaceutical logistics buyers prioritize barrier performance over unit economics.
Supply Chain Analysis
Just-in-time container procurement dominates non-hazardous specialty chemical segments, whereas strategic stockpiling of UN-certified steel drums persists among US Gulf Coast exporters facing maritime consolidation deadlines. Manufacturing concentration centers on Germany, China, and the United States for IBC assembly, with carbon steel drum fabrication anchored in India and Brazil. Raw material flows draw from Saudi Arabian polymer feedstock, Australian bauxite for aluminum containers, and Ukrainian carbon steel coil. Single-source vulnerability concentrates in fluoropolymer liner supply from Belgian specialty chemical producers. Distribution runs through integrated logistics platforms with captive reconditioning assets rather than fragmented regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container-as-a-service platforms are redefining competitive boundaries, with RFID-enabled lifecycle management creating interoperability lock-in between packaging suppliers and chemical enterprise ERP systems.
For Market Incumbents: Shield reconditioning network density through capacity expansion in Singapore and Antwerp hub zones. Carbon steel price volatility and emerging composite barrier technologies threaten drum-centric margin pools. Backward integration into barrier polymer compounding secures formulation control for pharmaceutical-grade IBC linings. For New Entrants and Emerging Players: BIS-UN certification fast-track alignment opens white-space penetration in Gujarat's dye intermediate sector and Maharashtra's agrochemical corridor. India's import substitution momentum represents the most penetrable geography for domestic IBC fabrication. Digital-first rental platforms with integrated reverse logistics offer differentiated go-to-market positioning against established drum distributors. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because extended producer responsibility mandates are structurally advantaging closed-loop rental operators over single-use manufacturers. Acquisition targets should emphasize reconditioning network geographic density and UN certification asset bases. The signal to watch is ECHA REACH substance restriction expansion into adhesive and sealant categories, which would trigger container material qualification cascades and consolidation pressure on fragmented composite fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Reconditioning Network Expansion | Captures margin pools in Rotterdam, Houston, and Singapore logistics corridors. |
| Barrier Polymer Backward Integration | Secures fluoropolymer-coated HDPE supply for pharmaceutical intermediate applications. |
| RFID-Blockchain Traceability Integration | Creates premium service tiers for FDA and EMA-compliant pharmaceutical logistics. |
| Post-Consumer Resin Scale-Up | Addresses EU Packaging and Packaging Waste Directive recyclability mandates. |
| India BIS Certification Alignment | Unlocks import substitution opportunities in Gujarat dye intermediate sectors. |
Methodological Framework
Desk research of customs trade databases, SEC 10-K filings, and ECHA REACH substance registration data preceded structured interviews with plant managers at specialty chemical producers, procurement leads at downstream agrochemical distributors, reconditioning network operators, and technical R&D directors at barrier polymer suppliers. Bottom-up volume estimates triangulated against top-down trade flow analysis.
Variance decomposition across packaging format, material grade, end-use industry, and regional production hub segments shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporated UN certification timeline data, scrap metal price volatility indices, and EPR policy implementation schedules.
Decision-makers should treat outputs as directional under assumptions of sustained ECHA REACH enforcement and stable maritime freight consolidation patterns; material deviation would warrant model refresh. Revision becomes warranted when carbon steel input cost volatility or fluoropolymer supply disruption crosses thresholds that alter reconditioning versus single-use substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Sodium Bicarbonate Market