
 US Magnesium Stearate Market | 2026-2036
US Magnesium Stearate Market Size, Share, and Industry Trends Forecast 2026-2036
US Magnesium Stearate Market Intelligence
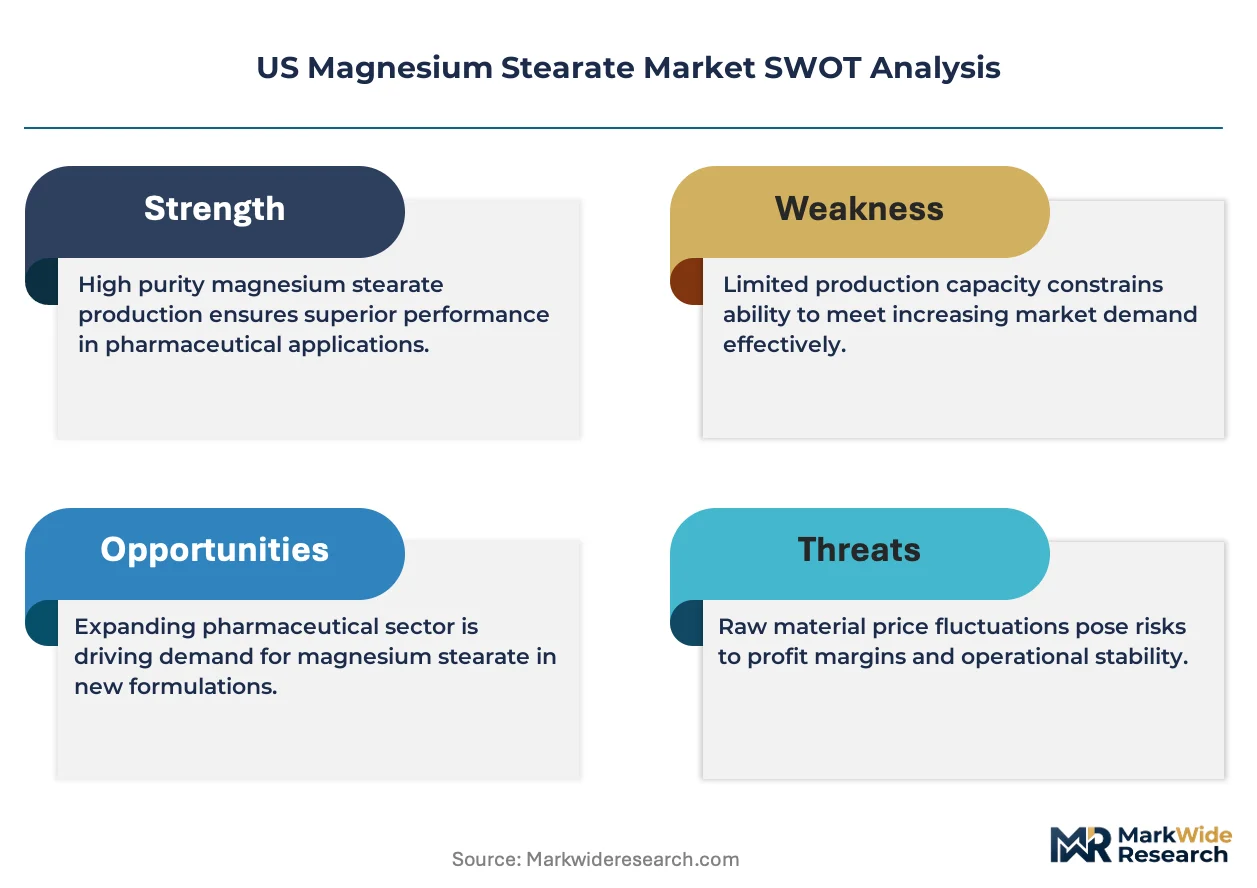
Pharmaceutical-grade chemical technician availability is collapsing across the US, constraining batch consistency at domestic magnesium stearate plants. Mallinckrodt Pharmaceuticals leverages captive sourcing to buffer against labor volatility, while PMC Biogenix sustains output through automated blending investments. Valtris Specialty Chemicals anchors its position via backward integration into stearic acid supply, reducing feedstock exposure.
Magnesium stearate is a metallic salt of stearic acid, typically containing 4.0–5.0% magnesium content and functioning as a hydrophobic lubricant with a melting point near 88°C, manufactured through saponification or direct reaction processes to prevent active pharmaceutical ingredient adhesion to tablet punches. The powder grade dominates pharmaceutical applications due to superior surface area coverage during blending, while the food industry segment differentiates through kosher and halal certification requirements that command premium positioning. Contract manufacturers represent the most concentrated end-user pool, with direct sales channels capturing the majority of volume through long-term supply agreements.
FDA enforces Current Good Manufacturing Practice standards that mandate excipient traceability, while USP-NF monographs define magnesium stearate identity and assay thresholds that determine batch release eligibility. OSHA process safety management rules govern dust explosion hazards in grinding and milling operations, elevating capital requirements for new entrants. Stakeholders must monitor excipient supply security as pharmaceutical onshoring policies reshape domestic sourcing obligations.
Market Dynamics
Pharmaceutical onshoring policies and USP-NF monograph revisions are tightening domestic sourcing obligations for tablet excipients, compressing supply options and elevating compliance costs across the Northeast manufacturing corridor.
Growth Catalysts
- Tablet Production Intensification:Pharmaceutical formulators are expanding batch volumes to meet domestic drug manufacturing targets, pulling magnesium stearate demand upward through direct input scaling.
- Current Good Manufacturing Practice Standards:FDA-mandated excipient traceability requirements are locking in qualified suppliers and extending contract durations for compliant domestic producers.
- Northeast Pharmaceutical Corridor Concentration:New Jersey and Pennsylvania host the densest cluster of contract tablet manufacturers in the US, creating localized demand gravity that favors regional supply nodes.
Market Restraints
- Stearic Acid Feedstock Volatility:Palm oil and tallow price swings transmit directly into magnesium stearate production costs, compressing margin stability for non-integrated processors.
- Pharmaceutical-Grade Technician Scarcity:The collapsing availability of trained chemical operators is constraining batch consistency and limiting plant utilization rates at domestic facilities.
- Dust Explosion Compliance Burden:OSHA process safety management rules for grinding and milling operations elevate capital requirements for new entrants and facility expansions.
Strategic Opportunities
- Automated Blending Technology Convergence:Robotics integration with continuous manufacturing lines is miniaturizing labor dependency and enabling 24-hour production cycles at reduced headcount.
- Kosher and Halal Certification Premiums:Food-grade applications command price differentiation through religious compliance, opening margin expansion for dual-certified production assets.
- Backward Integration into Stearic Acid:Captive supply of feedstock raw material buffers against commodity volatility and secures batch-to-batch consistency for pharmaceutical customers.
Industry Challenges
- Batch Release Timeline Compression:USP-NF assay threshold verification and identity testing are extending quality control cycles, straining just-in-time delivery commitments to contract manufacturers.
- Legacy Equipment Integration Friction:Pharmaceutical plants running decades-old tablet presses face compatibility issues with modified magnesium stearate grades engineered for high-speed lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Magnesium Stearate Market |
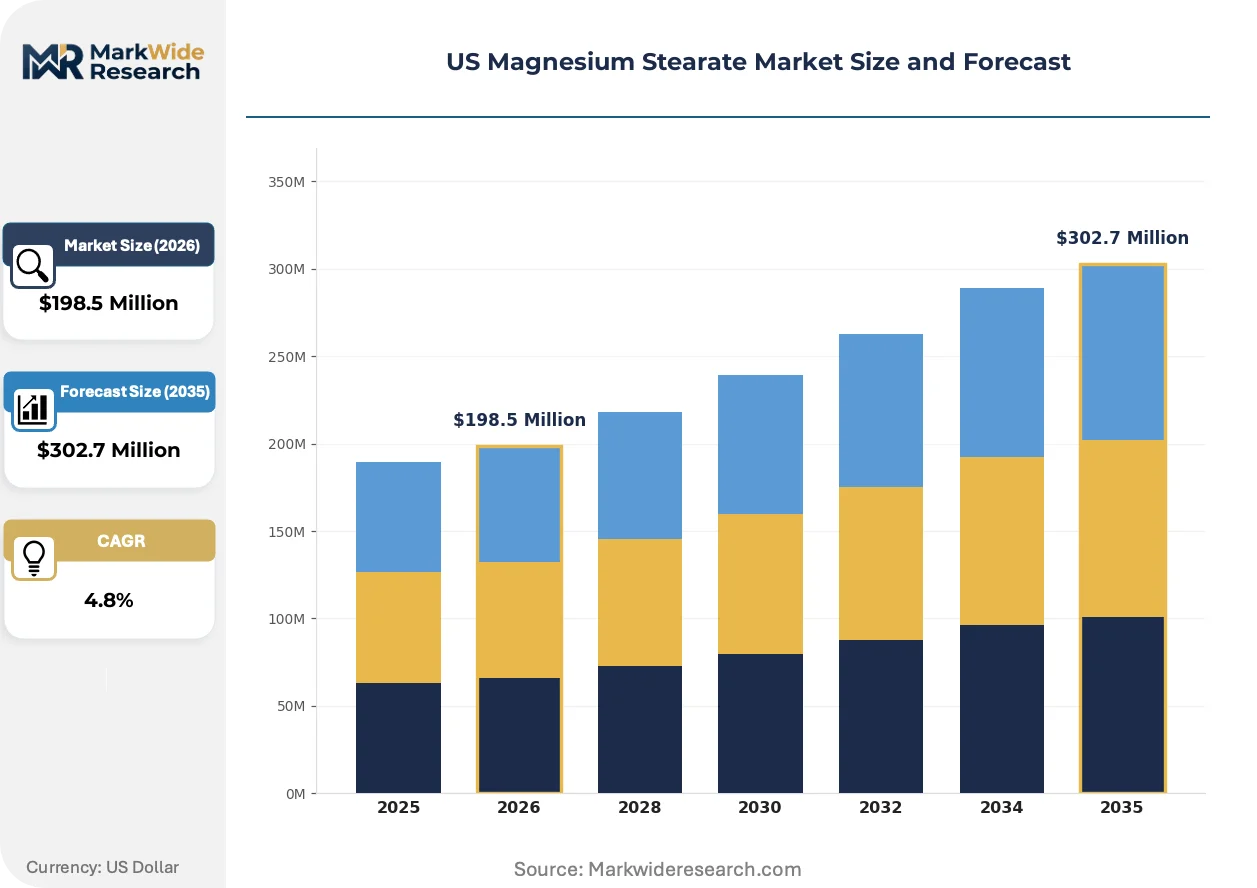
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $302.7 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Capsules Application: Pharmaceuticals, Food Industry, Cosmetics, Plastics End User: Contract Manufacturers, Formulators, Retailers, Distributors Distribution Channel: Online, Direct Sales, Wholesalers, Retail Stores |
| Companies Covered | Mallinckrodt Pharmaceuticals, PMC Biogenix, Valtris Specialty Chemicals, Acme Hardesty, Peter Greven, Spectrum Chemical Mfg. Corp., Parchem Fine & Specialty Chemicals, Thermo Fisher Scientific, Faci S.p.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Magnesium Stearate Market Strategic Shifts & Innovations
Continuous processing technologies and excipient quality-by-design frameworks are displacing batch manufacturing paradigms, while regulatory digitization is compressing documentation cycles across the pharmaceutical supply chain.
Continuous direct compression systems are miniaturizing traditional batch blending operations into streamlined powder-to-tablet workflows. Major contract manufacturers in New Jersey and Pennsylvania are retrofitting facilities to accommodate these lines, which reduce magnesium stearate variability through real-time lubricant dispersion monitoring. The technology is miniaturizing quality control overhead by embedding spectroscopic verification directly into production flow rather than segregated testing bays.
FDA's advancing quality management maturity program is elevating excipient supplier qualification thresholds beyond minimum USP-NF compliance. Domestic magnesium stearate producers must now demonstrate statistical process control and risk-based contamination prevention to maintain preferred vendor status with large pharmaceutical buyers. The policy is reshaping competitive positioning by favoring processors with documented quality systems over commodity-grade suppliers.
Direct sourcing agreements are displacing distributor-mediated procurement for high-volume tablet manufacturers. Pharmaceutical formulators in the Northeast corridor are consolidating supplier panels and negotiating multi-year magnesium stearate contracts with fixed-volume escalators, compressing spot market participation. This concentration is most visible among top-20 generic drug producers seeking supply security under pharmaceutical onshoring mandates.
US Magnesium Stearate Market Segmentation
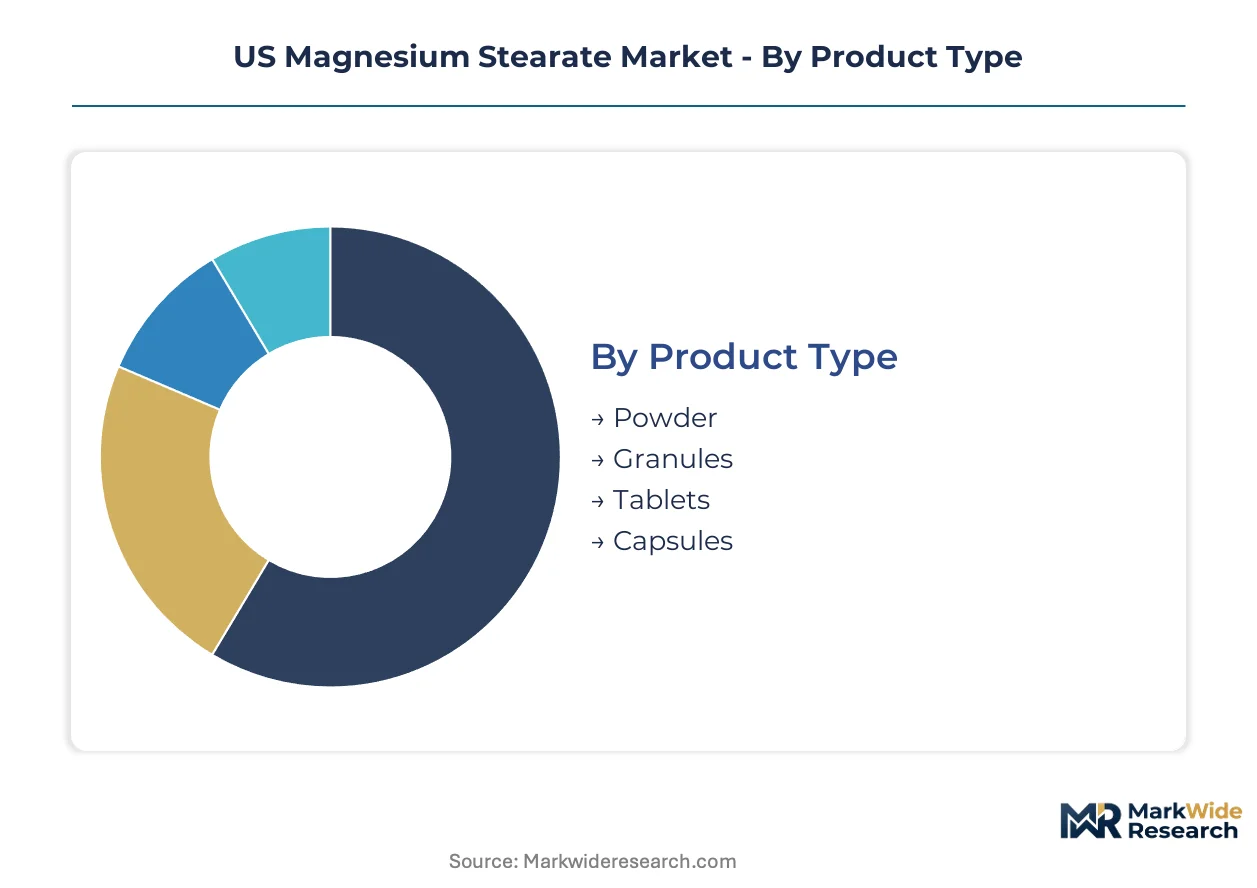
Magnesium stearate segmentation reveals how pharmaceutical-grade specifications, application purity thresholds, and channel economics fragment supply strategies across the US market. Channel selection directly constrains which product forms and customer tiers suppliers can profitably serve.
Product Type:
Channel economics favor powder for high-volume pharmaceutical contracts, while granules and compacted forms penetrate specialized niches through distributor networks.
- Powder:Fine particulate morphology with 4.0–5.0% magnesium content delivers superior surface area coverage during tablet blending. Demand concentrates among Northeast contract manufacturers running high-speed rotary presses, where lubricant efficiency directly determines batch throughput.
- Granules:Agglomerated particles reduce dust generation and improve flowability for automated feeding systems. Food industry applications in kosher-certified baking operations drive procurement, with religious compliance premiums supporting distributor-mediated supply chains.
- Tablets:Pre-compressed lubricant cakes simplify handling for small-batch compounders and veterinary formulators lacking sophisticated powder handling infrastructure.
- Capsules:Encapsulated magnesium stearate serves nutraceutical contract manufacturers seeking precise dosing control in dietary supplement production.
Powder dominates installed base. Granules are where expansion concentrates.
Application:
Cost tiers separate pharmaceutical-grade production from industrial applications, with certification requirements determining margin structure and supplier qualification burden.
- Pharmaceuticals:USP-NF monograph compliance and FDA Current Good Manufacturing Practice traceability mandate dedicated production lines. Northeast corridor tablet manufacturers lock in multi-year direct supply agreements, compressing spot market participation for this segment.
- Food Industry:FDA food-grade specifications plus kosher and halal certifications create three-tier pricing stratification. Premium positioning attaches to dual-certified production assets supplying bakery and confectionery processors.
- Cosmetics:Personal care formulators utilize magnesium stearate as emulsion stabilizer and texture modifier, with lower regulatory burden enabling distributor-channel procurement.
- Plastics:Polymer processors deploy metallic stearates as release agents and acid scavengers, competing on price against calcium and zinc variants in commodity resin applications.
Pharmaceuticals anchors revenue concentration. Food Industry is climbing the fastest.
End User:
Volume concentration among contract manufacturers shapes supplier relationship economics, while formulator and retail channels fragment procurement patterns.
- Contract Manufacturers:Northeast tablet production facilities in New Jersey and Pennsylvania consolidate demand through direct sales channels with fixed-volume escalators and statistical process control requirements.
- Formulators:Branded pharmaceutical developers and generic drug producers maintain qualified supplier panels with documented quality management maturity, extending contract durations beyond commodity excipient norms.
- Retailers:Nutraceutical and dietary supplement brands purchasing through distributor networks face higher per-unit costs but avoid minimum order commitments.
- Distributors:Chemical supply houses and excipient specialists intermediate for smaller volume accounts, capturing margin through technical service and inventory positioning.
Contract Manufacturers dominate installed base. Formulators are gaining share fastest.
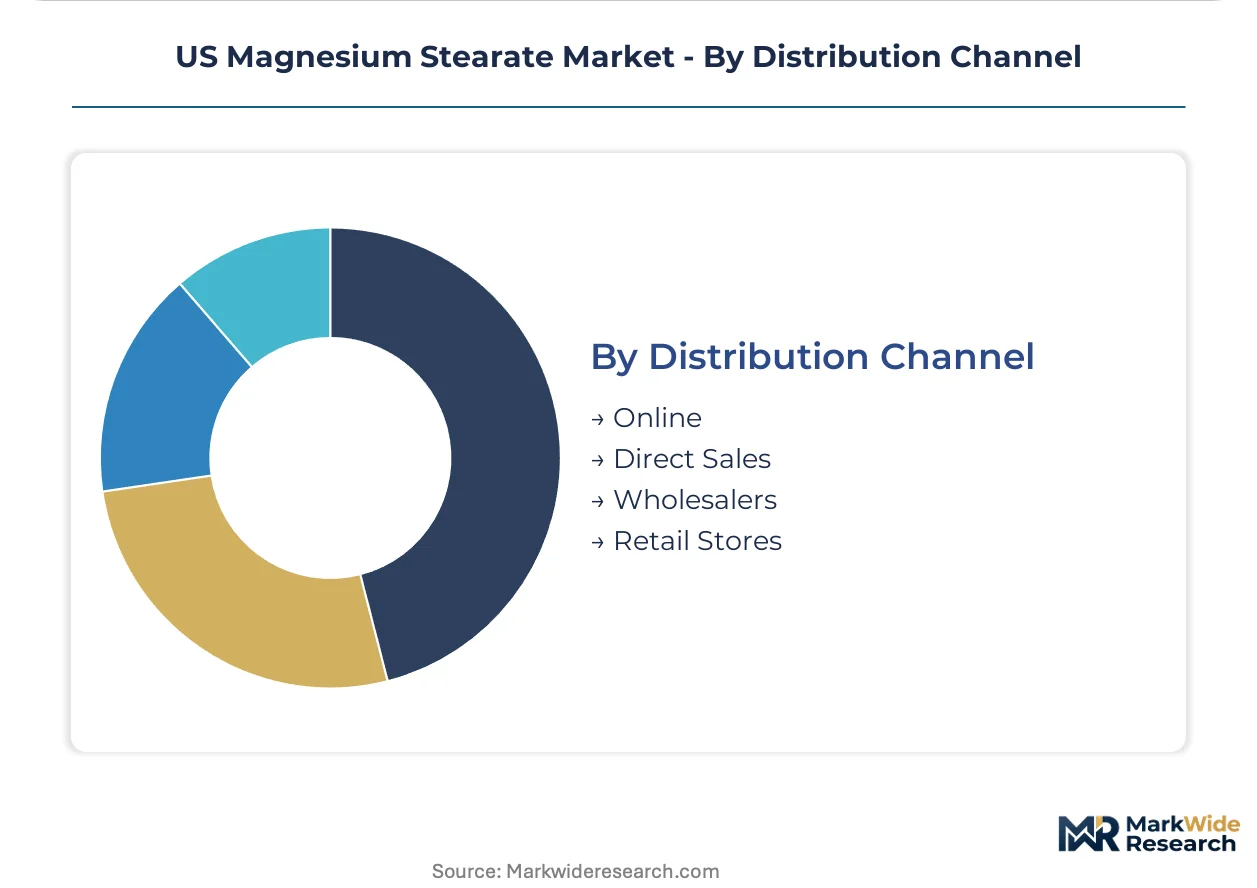
Distribution Channel:
Supply concentration in direct sales reflects pharmaceutical onshoring mandates, while digital channels penetrate lower-specification applications with reduced service requirements.
- Direct Sales:Long-term supply agreements with qualified pharmaceutical producers lock in volume through technical collaboration and joint quality system development. FDA excipient traceability requirements reinforce channel stickiness.
- Online:E-procurement platforms serve nutraceutical compounders and research-scale buyers with standardized powder grades, compressing lead times for non-critical applications.
- Wholesalers:Chemical distributors maintain regional inventory positions for food-grade and cosmetic applications, absorbing demand volatility through pooled purchasing.
- Retail Stores:Limited penetration confined to small-scale bakery supply and hobbyist cosmetic formulation, with minimal relevance to commercial magnesium stearate volume.
Direct Sales dominates installed base. Online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Northeast pharmaceutical corridor while feedstock-advantaged processors in the Gulf Coast compete on cost. Domestic sourcing mandates under pharmaceutical onshoring policies are redrawing regional supply maps. FDA compliance burdens favor established production clusters with documented quality systems.
Northeast Corridor
New Jersey and Pennsylvania host the densest concentration of contract tablet manufacturers in the US. FDA Current Good Manufacturing Practice standards and USP-NF monograph compliance requirements lock in qualified supplier relationships. Mallinckrodt Pharmaceuticals anchors regional supply security through captive sourcing arrangements in this corridor.
Gulf Coast
Texas and Louisiana leverage proximity to stearic acid feedstock derived from regional tallow and palm oil processing. OSHA process safety management rules for dust explosion hazards elevate capital barriers for new grinding and milling facilities. PMC Biogenix sustains output through automated blending investments that reduce labor dependency.
Midwest
Illinois and Ohio maintain legacy chemical processing infrastructure serving pharmaceutical and food-grade applications. USDA and FDA food-grade specifications plus kosher certification requirements create tiered pricing for dual-certified production assets. Valtris Specialty Chemicals reduces feedstock exposure through backward integration into stearic acid supply.
Southeast
North Carolina and Georgia attract nutraceutical contract manufacturers seeking lower operating costs than the Northeast corridor. Dietary supplement producers purchasing through distributor networks face higher per-unit costs but avoid minimum order commitments. Thermo Fisher Scientific serves research-scale buyers through regional distribution nodes.
West Coast
California's pharmaceutical formulators drive demand for high-purity powder grades with superior surface area coverage. EPA environmental compliance and Cal/OSHA workplace safety rules add regulatory layers beyond federal baselines. Spectrum Chemical Mfg. Corp. supplies standardized grades to nutraceutical compounders through e-procurement platforms.
US Magnesium Stearate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the US magnesium stearate market. The supplier base consolidates around three strategic tiers: integrated pharmaceutical chemical producers, specialty excipient processors, and diversified chemical distributors. Competitive dynamics center on backward integration into stearic acid supply and automated manufacturing investments that compress labor requirements.
Within the integrated pharmaceutical tier, Mallinckrodt Pharmaceuticals exemplifies captive sourcing strategies that buffer against labor volatility and raw material disruption. PMC Biogenix and Valtris Specialty Chemicals occupy positions among specialty processors pursuing operational efficiency through capital-intensive automation. These three companies anchor the competitive structure by representing divergent pathways—vertical integration, manufacturing technology, and feedstock control—through which suppliers defend margin position against commodity pressure.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| PMC Biogenix |
| Valtris Specialty Chemicals |
| Acme Hardesty |
| Peter Greven |
| Spectrum Chemical Mfg. Corp. |
| Parchem Fine & Specialty Chemicals |
| Thermo Fisher Scientific |
| Faci S.p.A |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day lead times for pharmaceutical-grade magnesium stearate concentrate negotiating power among Northeast contract manufacturers, while Gulf Coast processors leverage feedstock proximity to offset logistics premiums. Inventory buffers at qualified suppliers now determine contract eligibility under FDA traceability mandates, compressing spot market liquidity and elevating long-term agreement premiums.
Pricing Analysis
Northeast pharmaceutical corridor pricing commands a fifteen-to-twenty percent premium over Gulf Coast delivered equivalents, reflecting FDA compliance overhead and regional demand density. Three-tier pricing stratifies across USP-NF certified pharmaceutical grade, kosher-halal dual-certified food grade, and industrial release-agent specifications. Cost compression in food-grade tiers is intensifying because palm oil derivative volatility transmits directly into stearic acid feedstock costs. Contract manufacturers in New Jersey and Pennsylvania exhibit lowest price sensitivity due to supply security mandates, while nutraceutical retailers through distributor channels face highest elasticity.
Supply Chain Analysis
Inbound logistics costs from Southeast Asian palm oil terminals through Port of Houston have compressed margin structures for non-integrated processors dependent on imported stearic acid. Domestic production draws from Texas and Louisiana tallow processing, Malaysian and Indonesian palm oil derivatives, and Midwest rendered fat streams. Single-source vulnerability concentrates in Southeast Asian oleochemical feedstock, where weather and trade policy disruptions propagate rapidly. Distribution runs through direct sales agreements with qualified pharmaceutical producers, with distributor networks serving residual food and cosmetic applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade chemical technician availability has collapsed below replacement rates, constraining batch consistency and plant utilization across domestic magnesium stearate facilities. This capability gap now determines competitive viability more than feedstock access or equipment scale.
For Market Incumbents: Fortify backward integration into stearic acid supply to buffer against commodity volatility and secure batch-to-batch consistency for FDA-audited customers. Automated blending investments that reduce headcount dependency represent the critical lever against labor scarcity, while joint quality system development with Northeast contract manufacturers locks in multi-year offtake against emerging automation-equipped competitors. For New Entrants and Emerging Players: USP-NF certification fast-track through third-party quality system partnerships enables penetration of the nutraceutical distributor channel before pharmaceutical qualification timelines mature. White-space concentrates in Southeast dietary supplement contract manufacturing, where minimum order thresholds exclude smaller compounders from incumbent direct sales relationships. A kosher-halal dual-certified food-grade positioning with regional chemical distributors captures margin premiums while building toward pharmaceutical qualification. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automated manufacturing assets with documented statistical process control will absorb volume from labor-constrained legacy facilities. Target acquisition archetype: specialty excipient processors with captive stearic acid supply and FDA-audited quality systems in the Northeast corridor. The signal to watch is pharmaceutical onshoring policy expansion accelerating qualified supplier consolidation beyond organic growth rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stearic Acid | Captive feedstock supply buffers against palm oil volatility and secures batch consistency for FDA-audited pharmaceutical customers. |
| Automated Blending Technology Deployment | Robotics integration reduces labor dependency and enables continuous manufacturing alignment with high-speed tablet press requirements. |
| USP-NF Certification Investment | Regulatory qualification opens direct sales channels to Northeast contract manufacturers under pharmaceutical onshoring mandates. |
| Long-term Supply Agreement Negotiation | Fixed-volume escalators with statistical process control requirements lock in preferred vendor status with top-20 generic drug producers. |
| Kosher-Halal Dual Certification | Religious compliance premiums support distributor-mediated food-grade positioning with bakery and confectionery processors. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical formulation scientists, contract manufacturing procurement directors, chemical plant operations managers, and excipient distribution specialists. Secondary validation drew from FDA Current Good Manufacturing Practice guidance documents, USP-NF monograph revisions, OSHA process safety management directives, and SEC filings from publicly traded chemical producers. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments from domestic production facilities.
Across the analysis window, projections incorporate pharmaceutical tablet production intensification, excipient supply security policies, and continuous manufacturing technology diffusion. Segmentation modeling spans product morphology, application purity tier, end-user concentration, and distribution channel structure. CAGRs were derived from regression analysis against historical pharmaceutical output correlations and stearic acid feedstock price elasticity. Forecast inputs include contract manufacturer capacity expansion announcements and FDA quality management maturity program implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained pharmaceutical onshoring policy commitment and stable palm oil derivative trade flows; material deviation would warrant model refresh. Specific risk factors include accelerated technician attrition, dust explosion regulatory tightening, or Southeast Asian feedstock export restrictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Stilbene Market