
 Methyl Cyclohexane Market | 2026-2036
Methyl Cyclohexane Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Cyclohexane Market Foresight
Petroleum-derived cyclohexane is expanding its share in solvent applications as manufacturers seek alternatives to benzene-based formulations with stricter workplace exposure limits. SK Geo Centric leverages integrated aromatics complexes in South Korea to sustain cost-competitive supply chains for Asian coating manufacturers. Chevron Phillips Chemical anchors North American production through Gulf Coast cracking infrastructure, while Sinopec dominates captive consumption within China's expanding nylon-6 value chain.
Methyl cyclohexane is a saturated cyclic hydrocarbon produced through catalytic hydrogenation of toluene, typically exhibiting 99% minimum purity and a boiling point near 101 degrees Celsius; it functions primarily as a non-polar solvent and chemical feedstock for adipic acid and caprolactam synthesis. Industrial grade material commands the largest volume share due to bulk consumption in nylon precursor manufacturing, though specialty grade formulations are capturing margin pools from pharmaceutical and electronics cleaning applications where residue specifications tighten. The chemical intermediate application segment leads absolute consumption, while performance enhancers for fuel blending represent the fastest-growing category as refiners pursue octane recovery strategies.
The EPA regulates methyl cyclohexane under the Toxic Substances Control Act with reporting thresholds for manufacturing and processing, while REACH mandates registration and hazard communication across European supply chains; China's MEE enforces volatile organic compound emission controls that favor lower-aromatic solvent alternatives in coastal industrial zones. Japan's METI maintains JIS standards for solvent purity that constrain import eligibility from non-certified suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification investments with regional demand corridors.
Market Dynamics
REACH compliance in Europe and evolving EPA standards in the United States are tightening purity specifications for industrial-grade material, forcing producers to reconfigure hydrogenation catalyst systems and quality-assurance protocols across integrated aromatics complexes.
Growth Catalysts
- Caprolactam synthesis expansion:Nylon-6 precursor manufacturing is absorbing rising volumes of chemical intermediates as textile and engineering polymer applications multiply.
- MEE emission controls:China's volatile organic compound regulations favor lower-aromatic solvent alternatives in coastal industrial zones around Shanghai and Ningbo.
- Fuel blending recovery:Refiners pursuing octane recovery strategies are incorporating performance enhancers into gasoline formulations.
Market Restraints
- Toluene feedstock volatility:Crude oil price swings transmit directly into methyl cyclohexane production economics through catalytic hydrogenation input costs.
- Supply concentration in East Asia:Integrated petrochemical clusters in South Korea and China control disproportionate share of exportable volume.
- Benzene substitution ceiling:Workplace exposure limit regulations on benzene-based solvents have already captured accessible conversion demand in mature markets.
Strategic Opportunities
- Pharmaceutical-grade purification:Residue specifications for electronics cleaning and API synthesis are expanding addressable margin pools beyond industrial grades.
- India's chemical corridor expansion:Dahej and Mundra petrochemical zones lack integrated solvent production, creating import substitution openings.
- EU Green Deal solvent taxonomy:Renewable hydrogen integration into hydrogenation processes may qualify material for preferential procurement under emerging sustainable chemistry frameworks.
Industry Challenges
- Catalyst expertise scarcity:Noble metal hydrogenation process engineering talent concentrates at a handful of licensors and operating companies.
- Multi-jurisdiction certification lag:Parallel REACH registration, EPA TSCA reporting, and JIS standard compliance extend product qualification timelines for specialty grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Cyclohexane Market |
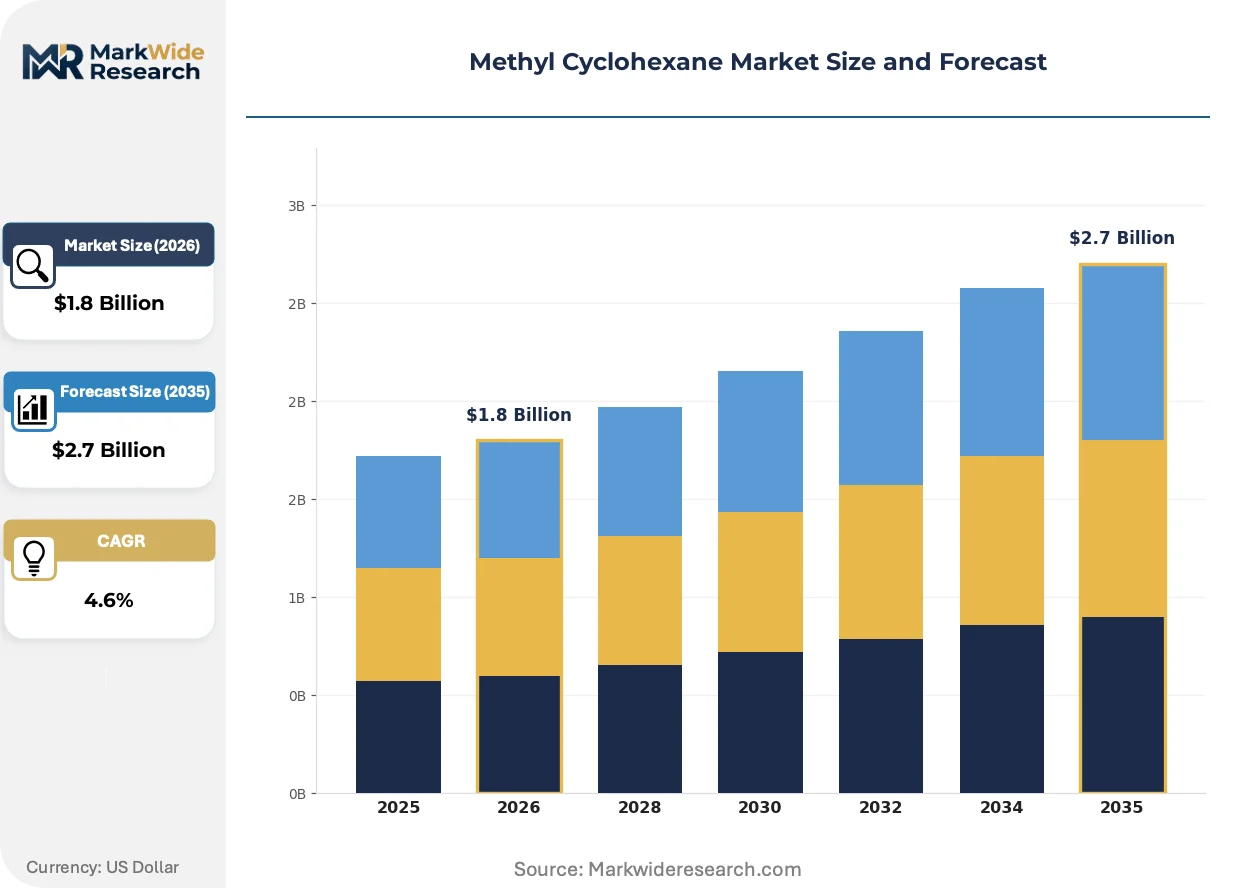
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Solvents, Fuel Additives, Chemical Intermediate, Performance Enhancers Product Type: Industrial Grade, Laboratory Grade, Commercial Grade, Specialty Grade End User: Manufacturing, Automotive, Chemical Processing, Pharmaceutical Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Shell Chemicals, SK Geo Centric, Chevron Phillips Chemical, Idemitsu Kosan, Huntsman Corporation, TotalEnergies, Maruzen Petrochemical, Sinopec, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Cyclohexane Market Shifts & Advancements
Membrane separation technologies and advanced catalytic systems are redrawing process economics, while regulatory divergence between jurisdictions is fragmenting product specification requirements across supply chains.
Advanced membrane separation for final-stage purification is decentralizing quality control away from centralized refinery complexes toward modular downstream units. Electronics manufacturers and pharmaceutical formulators are adopting containerized solvent finishing systems at point-of-use. This technology is decentralizing geographic concentration of high-purity supply, enabling regional producers to capture specialty margins without integrated aromatics infrastructure.
REACH authorization requirements for substances of very high concern are tightening hazard communication obligations across European supply chains. Industrial coating and adhesive formulators must now document full substance identity through extended safety data sheets. Adipic acid producers serving EU nylon value chains are responding by demanding certified low-impurity methyl cyclohexane with comprehensive analytical packages.
Specification-driven vendor consolidation is compressing approved supplier lists among multinational coating and electronics manufacturers. Third-party testing laboratories and certification bodies are displacing informal quality assurances in procurement workflows. This pattern is most visible in Japan, where METI-administered JIS standards constrain import eligibility and concentrate purchasing among pre-qualified domestic distributors.
Methyl Cyclohexane Market Segmentation
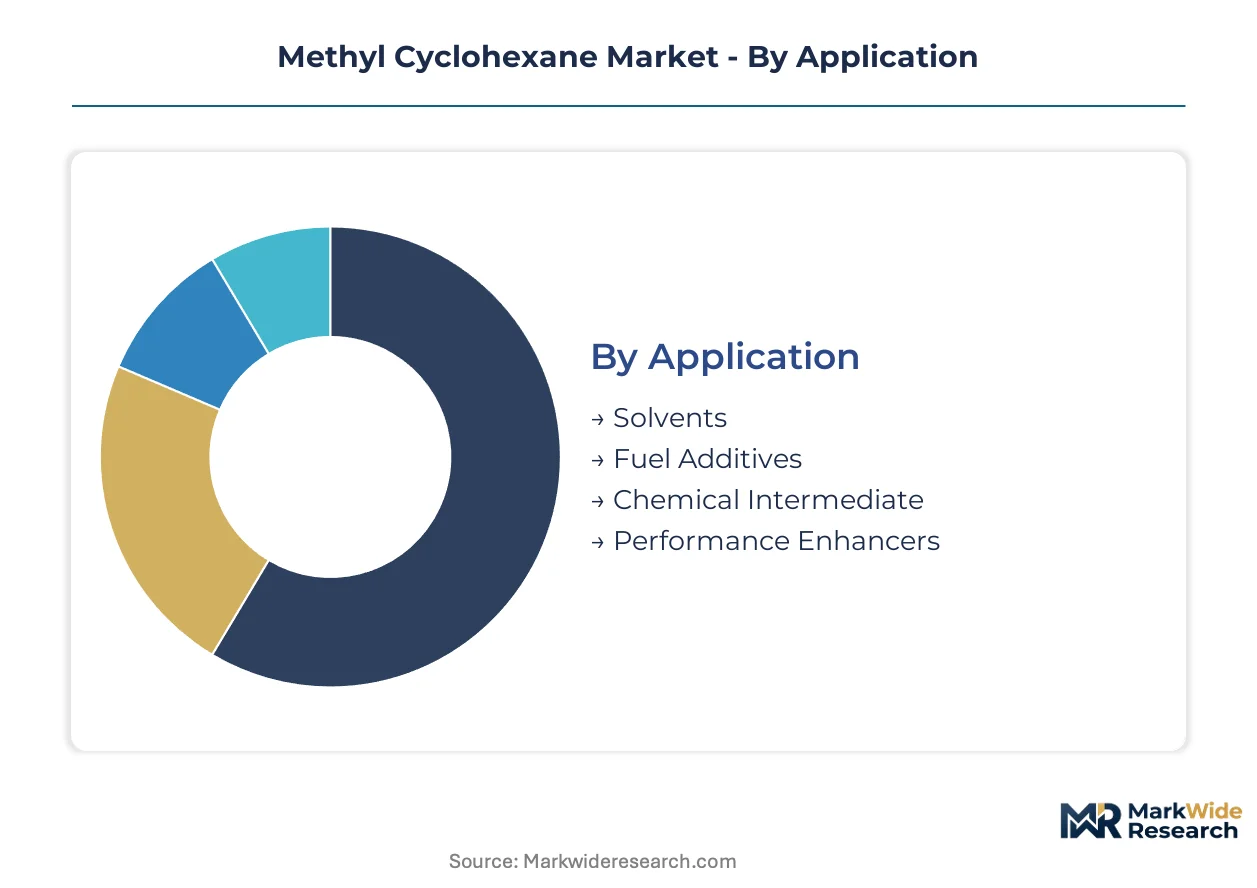
Segmentation in methyl cyclohexane markets tracks divergent purity thresholds and regulatory burdens across solvent, fuel, and chemical intermediate applications. Specification tiers determine whether producers compete on volume through integrated aromatics complexes or capture specialty margins via point-of-use purification systems.
Application:
Chemical Intermediate and Solvents carry distinct certification loads under REACH, EPA TSCA, and China's MEE frameworks, with fuel additives and performance enhancers facing additional transport and storage hazard classifications.
- Chemical Intermediate:Material serves adipic acid and caprolactam synthesis with 99% minimum purity specifications. Nylon-6 precursor manufacturing in China's Shanghai-Ningbo petrochemical corridor absorbs the dominant share of industrial-grade volume, driven by textile and engineering polymer expansion.
- Solvents:Non-polar formulations replace benzene-based alternatives in coating and adhesive applications where workplace exposure limits have tightened. Electronics cleaning and pharmaceutical formulators in Japan demand JIS-certified material with comprehensive analytical documentation.
- Fuel Additives:Refiners incorporate octane recovery compounds into gasoline blending pools. MEE emission controls in China's coastal industrial zones favor lower-aromatic solvent alternatives.
- Performance Enhancers:Additive packages improve combustion characteristics and engine cleanliness. Transport hazard classifications complicate cross-border distribution logistics.
Chemical Intermediate sits at the top of the volume ranking, with Performance Enhancers climbing the fastest.
Product Type:
Cost tiers separate captive consumption within integrated petrochemical complexes from spot-market procurement by regional formulators lacking hydrogenation infrastructure.
- Industrial Grade:Bulk material with 99% purity minimum dominates nylon precursor manufacturing. SK Geo Centric's integrated aromatics complexes in South Korea and Sinopec's captive consumption within China's expanding nylon-6 value chain control disproportionate supply share.
- Specialty Grade:Ultra-low residue formulations meet electronics and API synthesis specifications. Containerized solvent finishing systems at point-of-use enable regional producers to capture margins without refinery integration.
- Laboratory Grade:Analytical reagent specifications support R&D and quality control applications. Third-party testing laboratories displace informal quality assurances in procurement workflows.
- Commercial Grade:Intermediate purity tier serves general industrial cleaning and degreasing. Price differentiation reflects volume scale rather than certification burden.
Industrial Grade commands absolute volume leadership, though Specialty Grade expands most quickly as residue specifications tighten.
End User:
Customer type determines whether procurement flows through long-term offtake agreements with integrated producers or spot-market distributors serving fragmented regional formulators.
- Chemical Processing:Adipic acid and caprolactam manufacturers anchor industrial-grade demand. REACH authorization requirements for substances of very high concern tighten hazard communication obligations across European nylon value chains.
- Manufacturing:Coating, adhesive, and polymer producers consume solvent-grade material. Specification-driven vendor consolidation compresses approved supplier lists among multinational manufacturers.
- Automotive:Fuel blending operations incorporate performance enhancers into gasoline formulations. Refiners pursue octane recovery strategies as reformate yields shift.
- Pharmaceutical:API synthesis and cleaning applications demand certified low-impurity material. Extended safety data sheets document full substance identity through supply chains.
Chemical Processing leads absolute consumption, with Pharmaceutical gaining share fastest on residue specification tightening.
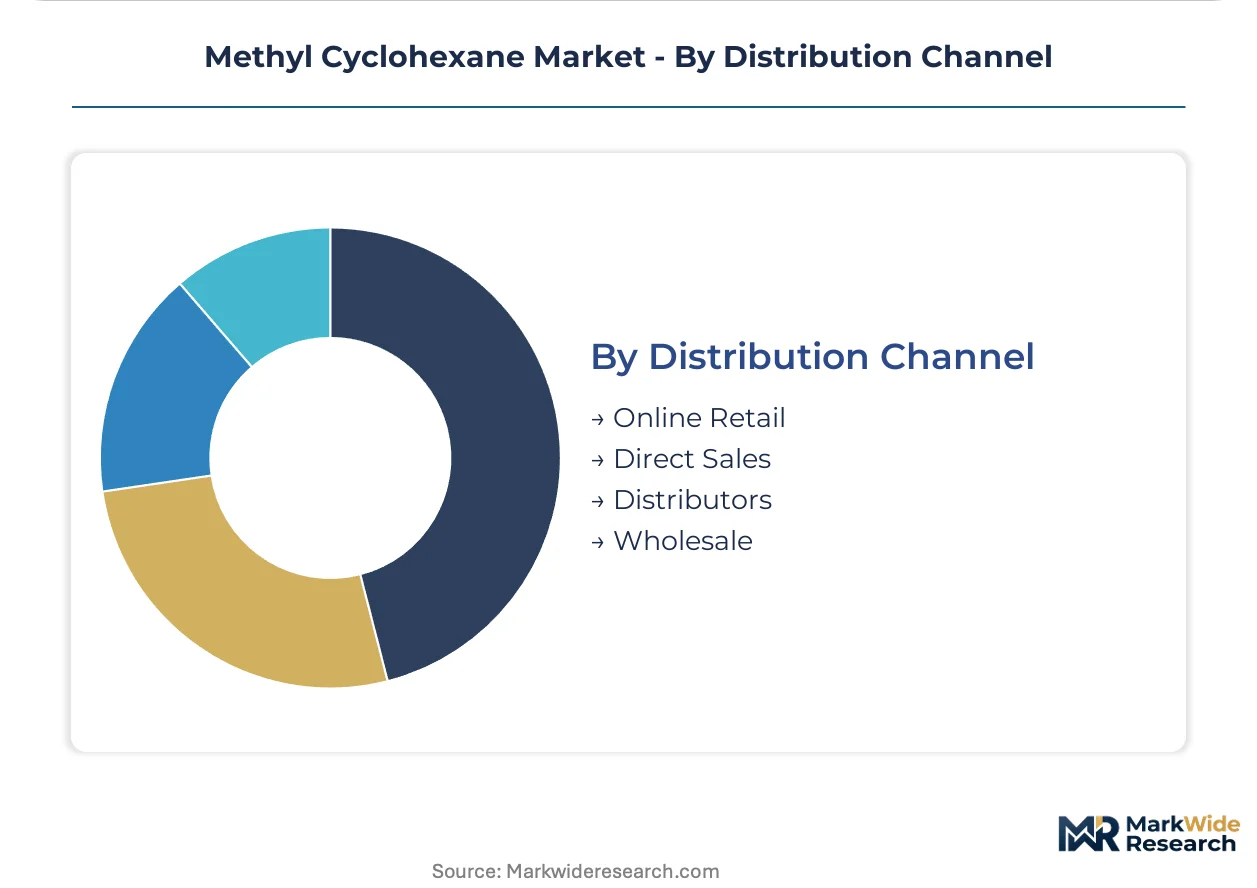
Distribution Channel:
Supply concentration in East Asian integrated complexes favors direct sales and wholesale arrangements, while specialty grades fragment through distributors and emerging online channels.
- Direct Sales:Captive offtake agreements link integrated aromatics producers to nylon and coating manufacturers. Chevron Phillips Chemical anchors North American supply through Gulf Coast cracking infrastructure.
- Distributors:Pre-qualified domestic distributors concentrate purchasing in Japan under METI-administered JIS standards. Regional producers leverage distributor networks to reach electronics and pharmaceutical formulators.
- Wholesale:Bulk volume moves through petrochemical trading hubs around Shanghai and Ningbo. Dahej and Mundra petrochemical zones in India lack integrated solvent production, creating import substitution openings.
- Online Retail:Emerging channel serves laboratory-grade and small-volume specialty procurement. Modular downstream units decentralize geographic concentration of high-purity supply.
Direct Sales captures the dominant volume position, with Online Retail expanding most quickly for laboratory and specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo petrochemical corridor absorbs dominant volumes of methyl cyclohexane as nylon-6 precursor manufacturing expands. Regulatory divergence across jurisdictions fragments product specifications and certification requirements. Industrial clusters in East Asia, North America, and Europe each concentrate distinct supply chain functions.
China
Caprolactam synthesis for textile and engineering polymers drives consumption volumes around Shanghai and Ningbo. MEE volatile organic compound emission controls in coastal industrial zones favor lower-aromatic solvent alternatives. Sinopec's captive consumption within integrated aromatics complexes dominates domestic supply allocation.
United States
EPA TSCA reporting thresholds shape manufacturing and processing compliance burdens for industrial-grade material. Chevron Phillips Chemical anchors production through Gulf Coast cracking infrastructure. Refiners along the Texas-Louisiana corridor incorporate performance enhancers into gasoline blending pools for octane recovery.
South Korea
SK Geo Centric leverages integrated aromatics complexes to sustain cost-competitive supply chains for Asian coating manufacturers. The country's national environmental regulator enforces emission standards that align with MEE frameworks across the Yellow Sea. Ulsan petrochemical zones export specialty-grade formulations to electronics manufacturers in Japan.
Japan
METI-administered JIS standards constrain import eligibility and concentrate purchasing among pre-qualified domestic distributors. Electronics cleaning and pharmaceutical formulators demand certified low-impurity material with comprehensive analytical documentation. Maruzen Petrochemical serves captive demand within domestic nylon and solvent applications.
Germany
REACH authorization requirements for substances of very high concern tighten hazard communication obligations across European nylon value chains. Adipic acid producers serving EU markets demand certified low-impurity methyl cyclohexane with extended safety data sheets. The EU Green Deal solvent taxonomy may qualify renewable hydrogen-integrated material for preferential procurement.
Methyl Cyclohexane Market Competitive Landscape
Global majors compete with regional champions across integrated aromatics infrastructure and specialty purification capabilities. The vendor base separates into captive consumers within petrochemical conglomerates and merchant suppliers serving spot-market procurement. Three archetypes dominate: integrated oil majors with backward control over feedstock, Asian petrochemical conglomerates with coastal cluster advantages, and specialty chemical houses with point-of-use purification systems. Competitive moves concentrate on catalyst system licensing and modular downstream unit deployment.
Within the integrated oil major tier, Shell Chemicals and ExxonMobil Chemical exemplify global supply network operators with aromatics complex integration. SK Geo Centric anchors the Asian petrochemical conglomerate archetype, representing regional champions that leverage coastal infrastructure for cost-competitive export supply. These three companies occupy positions that span industrial-grade volume leadership and specialty-grade certification capabilities.
| Leading Market Players |
|---|
| Shell Chemicals |
| SK Geo Centric |
| Chevron Phillips Chemical |
| Idemitsu Kosan |
| Huntsman Corporation |
| TotalEnergies |
| Maruzen Petrochemical |
| Sinopec |
| ExxonMobil Chemical |
| Others |
Supply & Pricing Matrix
China's MEE volatile organic compound emission controls gate qualified supply access and premium-tier pricing power for lower-aromatic solvent alternatives. Refiners and coating formulators seeking compliant material face contracted supplier lists and certificate-of-analysis requirements that stratify procurement costs.
Pricing Analysis
Toluene feedstock volatility transmits directly into methyl cyclohexane production economics through catalytic hydrogenation input costs. Three-tier pricing structure across specialty, industrial, and commercial grades reflects certification burden and residue specification stringency. Cost compression in industrial-grade material is intensifying because South Korean and Chinese integrated producers leverage coastal cluster scale. Pharmaceutical formulators demonstrate least price sensitivity due to analytical documentation requirements, while general industrial cleaning buyers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-nylon-manufacturer channels handle caprolactam producer demand through long-term offtake agreements with Sinopec and SK Geo Centric. Supply concentrates in South Korea, China, and the United States, with Ulsan and Shanghai-Ningbo petrochemical corridors anchoring exportable volume. Noble metal catalyst systems and hydrogen feedstock draw from limited qualified suppliers, creating single-source vulnerability for specialty-grade purification. Distribution runs through pre-qualified domestic distributors in Japan under METI-administered JIS standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Methyl cyclohexane functions as a stable compounder anchored by nylon-6 precursor demand from textile and engineering polymer expansion. Regulatory specification tightening across REACH, EPA TSCA, and China's MEE frameworks sustains steady margin improvement for certified suppliers.
For Market Incumbents: Acquire point-of-use purification technology assets to capture pharmaceutical and electronics cleaning margins without integrated aromatics infrastructure. Defend against membrane separation decentralization by locking long-term offtake agreements with adipic acid producers in China's Shanghai-Ningbo corridor. Invest in noble metal hydrogenation catalyst expertise to maintain process licensing leverage.
For New Entrants and Emerging Players: Begin with India's Dahej and Mundra petrochemical zones where integrated solvent production gaps create import substitution openings. Target specialty-grade formulations for electronics manufacturers in Japan seeking JIS-certified material with comprehensive analytical packages. Pursue containerized solvent finishing systems as the go-to-market angle to bypass refinery integration requirements.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialty purification operators because specification-driven vendor consolidation compresses approved supplier lists among multinational coating and electronics manufacturers. Five-to-ten-year viability rests on regulatory divergence persisting across REACH, EPA, and MEE frameworks. Watch for EU Green Deal solvent taxonomy implementation as the inflection indicator for renewable hydrogen-integrated production premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Supply | Captive renewable hydrogen production qualifies material for EU Green Deal preferential procurement status. |
| Specialty Grade Capacity Expansion | Modular downstream units in India capture electronics and pharmaceutical margin pools without coastal refinery assets. |
| Long-term Supply Agreement | Chevron Phillips Chemical anchors North American coating manufacturers through Gulf Coast cracking infrastructure. |
| Green Manufacturing Transition | Renewable hydrogen integration into hydrogenation processes aligns with emerging sustainable chemistry frameworks. |
| Joint Venture | SK Geo Centric leverages Ulsan petrochemical zones to export specialty-grade formulations to Japanese electronics manufacturers. |
Research Methodology
Multiple input streams — primary interviews with plant managers, procurement leads at downstream nylon manufacturers, distribution channel partners, and technical R&D directors; secondary validation through customs/trade data, ACC/Cefic industry reports, and SEC 10-K filings; plus regulatory database monitoring — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Historical volume trajectories were cross-referenced against expert panel input to anchor growth assumptions across the analysis window. The analytical framework modeled grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating caprolactam capacity expansion schedules, MEE emission control implementation timelines, and refiner octane recovery strategy shifts.
Several conditions sit outside the modeled scope, including force majeure disruptions to toluene supply chains and abrupt regulatory harmonization between REACH, EPA TSCA, and China's MEE frameworks. Forecasts reflect base-case assumptions regarding sustained nylon-6 precursor demand and continued specification divergence across jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Mesifurane Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Refined Wax Market
Bulk Chemicals
Methionine Market