
 Glass Product Market | 2026-2036
Glass Product Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Product Market Analysis
High-performance low-emissivity coating specifications are redrawing competitive boundaries across architectural and automotive supply chains. Saint-Gobain leverages vertical integration from raw material extraction to coated float lines, sustaining cost advantages in European and North American project markets. AGC Inc. dominates thin glass production for display and electronics substrates, while Fuyao Glass Industry Group Co., Ltd. anchors automotive OEM supply through dedicated plant locations adjacent to vehicle assembly operations.
Glass products encompass silicate-based materials formed through melting, forming, and controlled cooling processes, with compositions varying by alkali content, iron oxide levels, and functional additives to achieve specific optical, thermal, or mechanical properties. Float glass occupies the largest production volume position due to continuous ribbon manufacturing efficiency, yet insulated glass configurations command premium positioning as energy code stringency escalates in commercial building envelopes. Tempered glass competes on safety certification requirements across automotive side and rear glazing, while laminated glass extends into hurricane-rated architectural and acoustic dampening applications where interlayer performance differentiates supplier offerings.
The EPA enforces emissions standards under the Clean Air Act that constrain melting furnace operations, while the EU Green Deal's carbon border adjustment mechanism shapes export competitiveness for Asian producers serving European construction markets. China's MEE implements dual carbon goals through industrial energy intensity benchmarks that affect glass plant operating permits and capacity expansion approvals. Stakeholders must monitor regulatory trajectory divergence between jurisdictions to align capital deployment with emerging compliance cost structures and product certification requirements.
Market Dynamics
The EU Green Deal's embodied carbon rules are forcing glassmakers to reformulate batch compositions and adopt electric melting technologies, fundamentally restructuring capital deployment and competitive positioning across the value chain.
Growth Catalysts
- Solar photovoltaic expansion:Utility-scale and distributed generation projects are multiplying, intensifying demand for high-transmission solar glass from panel manufacturers.
- MEE dual carbon benchmarks:China's industrial energy intensity rules are accelerating furnace upgrades and capacity consolidation among domestic producers.
- Automotive glazing specifications:OEMs are specifying larger panoramic roof assemblies and head-up display compatibility, pulling specialty laminated and thin glass volumes.
Market Restraints
- Soda ash and silica sand cost volatility:Energy-intensive mining and processing operations expose margins to input price swings from concentrated suppliers.
- Float line concentration in China:Over half of global flat glass capacity sits within a single jurisdiction, creating geopolitical and logistics concentration risk.
- Polycarbonate substitution in automotive:Lightweighting mandates are displacing tempered side glazing with transparent polymer alternatives in specific vehicle segments.
Strategic Opportunities
- India building code enforcement:Energy conservation building codes are tightening across Maharashtra and Gujarat, opening insulated glass unit penetration in commercial construction.
- Electrochromic smart windows:Integration of conductive oxide coatings with building management systems is creating premium retrofit and new-build specification channels.
- EU carbon border adjustment mechanism:The phased implementation is creating first-mover advantage for European producers with verified low-carbon batch formulations.
Industry Challenges
- Electric furnace engineering talent scarcity:The shift from fossil-fired to resistive or plasma melting requires process engineers with rare hybrid skill sets in thermal management and power electronics.
- Low-carbon certification timeline compression:Third-party embodied carbon verification under evolving EU Green Deal protocols is extending product qualification cycles for export-bound shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Product Market |
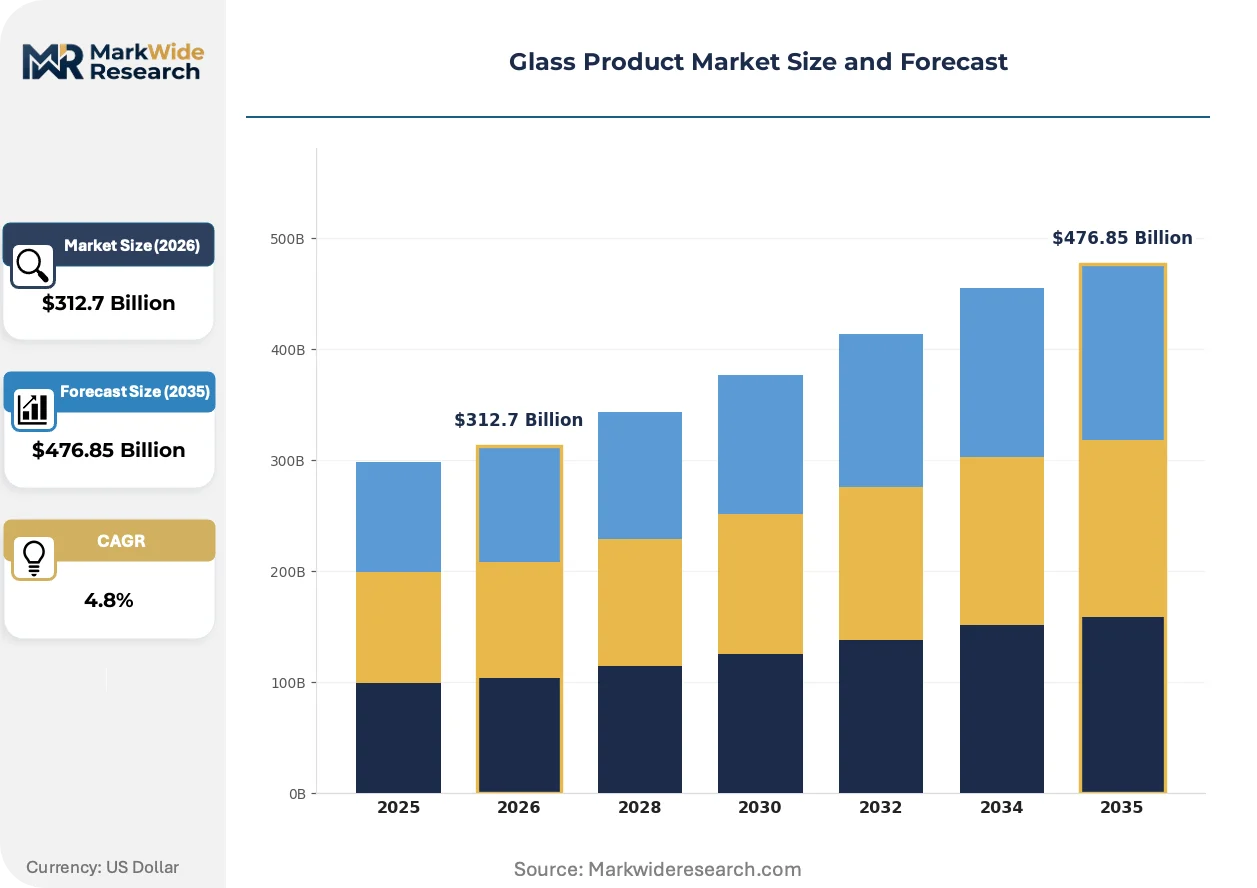
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Glass, Tempered Glass, Laminated Glass, Insulated Glass End User: Construction, Automotive, Consumer Goods, Electronics Form: Sheet Glass, Container Glass, Fiberglass, Glass Wool Application: Windows, Mirrors, Packaging, Solar Panels |
| Companies Covered | Saint-Gobain, AGC Inc., Corning Incorporated, Nippon Sheet Glass Co., Ltd., Şişecam, Cardinal Glass Industries, Fuyao Glass Industry Group Co., Ltd., Schott AG, Xinyi Glass Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Product Market Emerging Trajectories
Active reformulation of melting chemistries and coating stacks is compressing the performance gap between commodity float and specialty architectural products.
Perovskite-silicon tandem cell integration is decomposing the traditional solar glass specification. Module manufacturers in Germany and South Korea are qualifying 2.0mm chemically strengthened substrates to replace standard 3.2mm tempered covers. This thickness reduction is decomposing the volume-per-watt glass intensity of utility installations while demanding tighter warp and micro-crack tolerances from suppliers.
REACH authorization requirements for boron compounds are restricting access to specific refining agents in European melting operations. Glassmakers are responding with boron-free or reduced-boron batch designs that modify viscosity curves and fining behavior. Container and tableware segments are absorbing most reformulation costs, while flat glass producers with longer qualification cycles face compressed implementation timelines.
Building developers are consolidating glazing procurement under envelope-performance contracting rather than material-only purchasing. General contractors in California and New York are bundling insulated glass unit supply with installation and thermal modeling guarantees. This model compresses supplier count per project and shifts risk allocation toward integrated system performance rather than component specification compliance.
Glass Product Market Segmentation
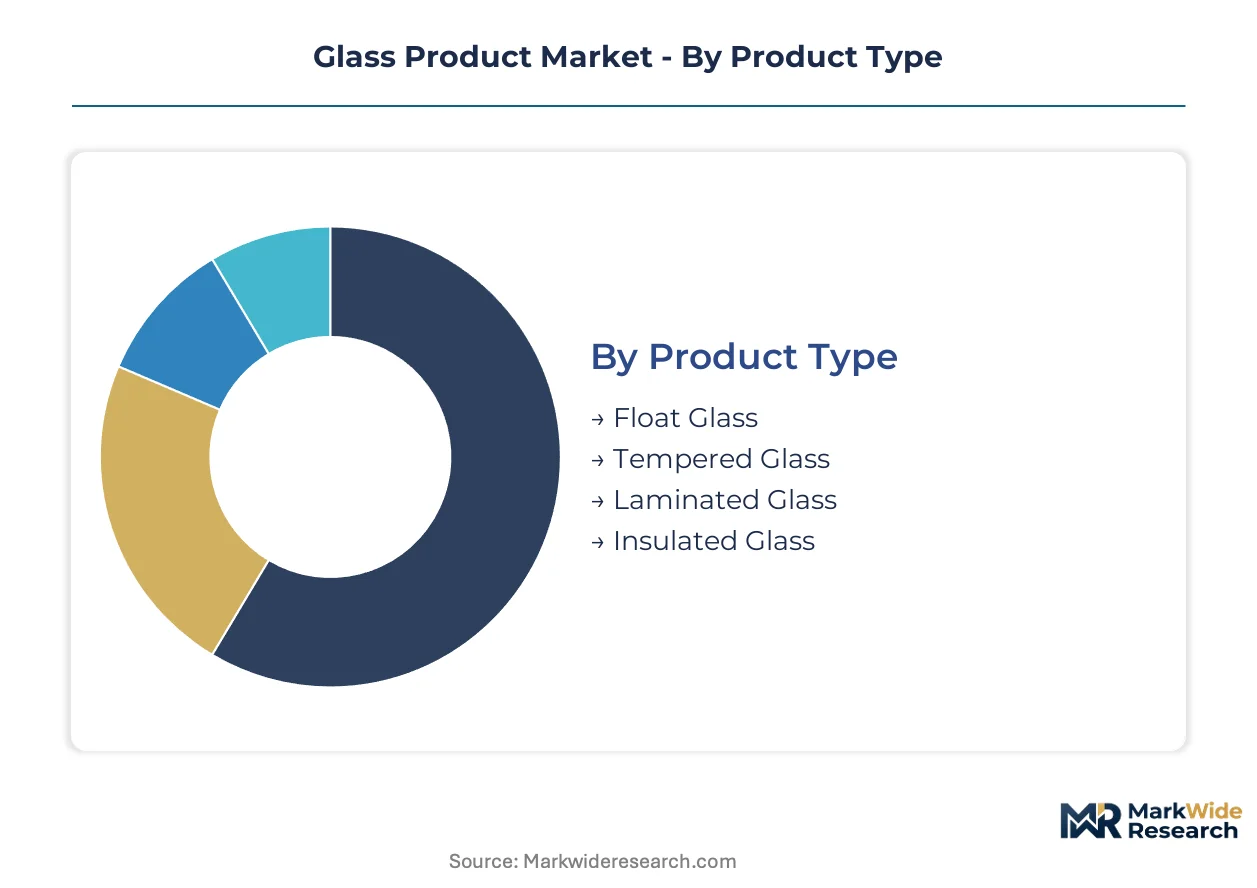
Glass product segmentation reveals how regulatory pressures and end-use specifications fragment manufacturing capabilities across distinct technical and commercial boundaries. Each dimension carries implications for furnace configuration, coating investment, and certification pathways.
Product Type:
EPA Clean Air Act emissions standards and EU Green Deal embodied carbon thresholds are driving divergence in melting technology choices across product categories.
- Float Glass:Continuous ribbon manufacturing produces optical-grade flat sheets through controlled tin bath flotation. Construction clusters in China and automotive assembly corridors in Germany absorb the bulk of output, though EU carbon border adjustment mechanisms are reshaping export economics for Asian suppliers.
- Tempered Glass:Controlled thermal or chemical strengthening creates safety-certified fragmentation patterns required for automotive side glazing and architectural guardrails. OEM panoramic roof specifications are expanding thickness ranges and optical distortion tolerances beyond traditional passenger car applications.
- Laminated Glass:Polyvinyl butyral interlayers bond multiple glass plies for hurricane-rated envelopes and acoustic dampening.
- Insulated Glass:Sealed dual-pane configurations with low-emissivity coatings and argon fills meet escalating energy code stringency in commercial building envelopes.
Float glass handles the majority of throughput; insulated glass is expanding most quickly on specification intensity.
End User:
Customer procurement patterns split between project-based construction contracting and continuous automotive supply agreements with diverging margin profiles.
- Construction:Envelope-performance contracting models in California and New York are bundling insulated glass unit supply with installation guarantees. Megacity clusters in China consume substantial flat and specialty volumes through consolidated developer procurement.
- Automotive:Dedicated plant locations adjacent to vehicle assembly operations anchor supply security for OEM panoramic roof and head-up display programs.
- Consumer Goods:Container and tableware segments absorb boron-free batch reformulation costs under REACH authorization pressures.
- Electronics:Display substrate qualification demands sub-millimeter thickness tolerances and warp control.
Construction captures the dominant share of volume; electronics is climbing the fastest on specification premium.
Form:
Physical configuration determines downstream processing equipment requirements and logistics cost structures.
- Sheet Glass:Flat ribbon output serves architectural glazing and automotive windshield precursor applications.
- Container Glass:Blow-molded bottles and jars for beverage and pharmaceutical packaging face recycled content mandates under EU packaging regulations.
- Fiberglass:Continuous filament and chopped strand formats supply composite reinforcement for wind turbine blades and corrosion-resistant piping.
- Glass Wool:Fiberized insulation batts and loose-fill products compete with mineral wool in building thermal envelope applications.
Sheet glass dominates value contribution; fiberglass is gaining share fastest on renewable energy infrastructure pull.
Application:
Functional specification intensity varies sharply between commodity replacement demand and engineered system integration.
- Windows:Building code enforcement across Maharashtra and Gujarat is opening insulated glass unit penetration in Indian commercial construction.
- Mirrors:Silvering and aluminum coating lines serve automotive rear-view and architectural decorative applications.
- Packaging:Pharmaceutical and premium food segments drive lightweighting and barrier coating investments.
- Solar Panels:Perovskite-silicon tandem cell integration is decomposing traditional specifications as module manufacturers qualify thinner chemically strengthened substrates.
Windows maintains the largest installed base; solar panels is expanding most rapidly on photovoltaic deployment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are shifting as carbon border mechanisms reshape trade flows for energy-intensive materials. Glassmakers in high-cost jurisdictions are defending position through low-carbon batch certification, while Asian producers face mounting compliance costs to access premium European construction markets.
China
Megacity construction clusters and automotive production hubs absorb substantial flat and specialty glass volumes. The MEE enforces dual carbon goals through industrial energy intensity benchmarks that constrain plant operating permits and capacity expansion approvals. The Yangtze River Delta and Pearl River Delta concentrate over half of global flat glass capacity, creating geopolitical concentration risk for downstream supply chains.
Germany
Automotive OEM panoramic roof programs and building envelope retrofits pull premium laminated and coated glass specifications. The EU Green Deal's carbon border adjustment mechanism is reshaping export economics for Asian suppliers serving German construction markets. The industrial corridor between Cologne and Frankfurt anchors specialized automotive glazing operations adjacent to vehicle assembly plants.
United States
Commercial building code enforcement in California and New York is bundling insulated glass unit supply with installation and thermal modeling guarantees. The EPA enforces emissions standards under the Clean Air Act that constrain melting furnace operations in Ohio and Pennsylvania manufacturing belts. The Southeast automotive corridor from South Carolina to Alabama is expanding tempered and laminated glass demand for domestic vehicle production.
India
Energy conservation building codes are tightening across Maharashtra and Gujarat, opening insulated glass unit penetration in commercial construction. The Bureau of Indian Standards implements certification requirements for safety glass in building applications that affect import qualification timelines. The Delhi-Mumbai Industrial Corridor is attracting float line investments to serve domestic demand growth and reduce reliance on Chinese imports.
Japan
Display substrate qualification for electronics manufacturers demands sub-millimeter thickness tolerances and warp control from specialty glass suppliers. METI industrial policy supports domestic melting technology development to maintain competitiveness against Korean and Taiwanese substrate producers. The Kyushu and Chubu regions concentrate precision glass manufacturing for semiconductor and display supply chains.
Glass Product Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology licensing dimensions. The market structure consolidates around integrated multinationals with captive raw material positions, while regional fabricators defend niche specifications through proximity to automotive assembly corridors. Three archetypes dominate: vertically integrated material-to-coating operators, display substrate specialists with precision forming capabilities, and automotive-dedicated plants with OEM co-location strategies. Competitive moves center on electric furnace technology licensing partnerships and low-carbon batch formulation certification to secure EU market access.
Within the integrated multinational tier, Saint-Gobain exemplifies backward integration from raw material extraction through coated float line operations. AGC Inc. and Nippon Sheet Glass Co., Ltd. occupy positions spanning architectural, automotive, and electronics substrate segments with differentiated regional footprints. Fuyao Glass Industry Group Co., Ltd. represents the automotive co-location archetype through dedicated plant positioning adjacent to vehicle assembly operations.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Corning Incorporated |
| Nippon Sheet Glass Co., Ltd. |
| Şişecam |
| Cardinal Glass Industries |
| Fuyao Glass Industry Group Co., Ltd. |
| Schott AG |
| Xinyi Glass Holdings Limited |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied carbon verification gates both supply qualification and price differentiation simultaneously, forcing Asian exporters to absorb certification costs while European producers capture premium positioning through verified low-carbon batch formulations. Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in standard float glass is intensifying because of soda ash and silica sand volatility from concentrated suppliers. Automotive OEMs exhibit lowest price sensitivity due to co-location dependencies, while commodity construction buyers drive aggressive negotiation on large project volumes.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures with thermal performance guarantees bundled into envelope-performance contracting. Price differentiation separates low-carbon certified products from conventional grades, with geographic delivery cost and customization level as secondary drivers. Margins are tightening due to electric furnace engineering talent scarcity and extended qualification cycles under evolving EU protocols. Construction developers show highest price sensitivity through consolidated procurement, while electronics substrate buyers accept substantial premiums for sub-millimeter thickness tolerances.
Supply Chain Analysis
Yangtze River Delta port congestion underwrites logistics vulnerability for global flat glass distribution. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies on Australian silica sand, Turkish soda ash, and Chinese processed minerals. Supply chain risk centers on single-source vulnerability from concentrated boron compound suppliers facing REACH authorization restrictions. Distribution runs through regional fabrication hubs adjacent to construction clusters and automotive assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glass product market sits in early-cycle expansion, with photovoltaic deployment acceleration and building code tightening across India creating penetration tailwinds for insulated and solar glass specifications.
For Market Incumbents: Compound defensive positioning through captive soda ash supply arrangements and electric melting technology licensing partnerships. Polycarbonate substitution in automotive lightweighting threatens tempered glass volumes, necessitating capacity consolidation in European low-carbon certified production. Backward integration into raw material extraction preserves margin control against input volatility. For New Entrants and Emerging Players: Differentiate on boron-free batch formulation expertise to serve European container and tableware segments under compressed REACH implementation timelines. The most penetrable white space sits in Indian commercial construction, where energy conservation code enforcement is opening insulated glass unit demand. A technical licensing route with established regional fabricators accelerates market access without greenfield furnace investment. For Investors and Strategic Acquirers: EU carbon border adjustment mechanism phased implementation reshapes the acquisition landscape toward European assets with verified low-carbon production. Long-term viability favors targets with electric furnace operational experience and established OEM co-location contracts. The signal to watch is MEE dual carbon benchmark tightening, which will force capacity consolidation among Chinese producers and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Melting Technology Licensing | Partnerships with power electronics specialists accelerate furnace conversion under EU Green Deal compliance deadlines. |
| Low-Carbon Batch Certification Program | Third-party verification under evolving EU protocols secures premium positioning in German and French construction markets. |
| Automotive Co-Location Expansion | Dedicated plant positioning adjacent to Southeast US vehicle assembly corridors captures OEM panoramic roof program volumes. |
| Perovskite-Silicon Substrate Qualification | 2.0mm chemically strengthened glass development addresses module manufacturer thickness reduction requirements. |
| India Distribution Partnership | Joint ventures with Maharashtra and Gujarat fabricators leverage tightening energy conservation building code enforcement. |
Methodological Framework
Desk research of customs trade data, EU ETS registry filings, and SEC 10-K disclosures preceded structured interviews with glass plant operations directors, automotive OEM procurement leads, construction envelope contractors, and solar module manufacturing engineers. Primary fieldwork combined with secondary validation from China MEE industrial policy documents and BIS certification requirement updates. Bottom-up capacity and shipment estimates triangulated against top-down end-use demand modeling across construction, automotive, and photovoltaic segments.
Variance decomposition across product type, end user, physical form, and application dimensions drove analytical framework construction over the projection horizon. CAGRs derived from regression against macro drivers including photovoltaic installation forecasts, vehicle production schedules, and commercial construction permitting data. Industry-specific inputs encompassed furnace fuel mix transition assumptions and low-carbon batch formulation adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation or abrupt photovoltaic subsidy withdrawal would require recalibration. Forecasts reflect documented assumptions regarding MEE enforcement intensity and REACH authorization timeline compression. Practitioners should keep alternative scenarios live as carbon border mechanism phase-in schedules and perovskite cell commercialization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Middle-East and Africa Flat Glass Market
Glass
Screen-Printing Glass Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Mexico Flat Glass Market
Glass
Glass Lens Market
Glass
Mirrored Glass Market
Glass
Recycled Glass Aggregates Market
Glass
Insulated Glass Market
Glass
Antibacterial Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Borosilicate Glass Market
Glass
Global Ultra-Thin Glass Market
Glass
Laboratory Glass Container Market
Glass
United States Flat Glass Market
Glass
Optical Materials Market
Glass
Birefringent Crystals Market