
 United States Lime Market | 2026-2036
United States Lime Market Size, Share, and Industry Trends Forecast 2026-2036
United States Lime Market Analytics
The gap between premium high-calcium lime and commodity-grade product is realigning procurement patterns across the United States. Carmeuse dominates the Great Lakes corridor with captive limestone quarries and vertical kilns that sustain cost advantages in bulk quicklime. Graymont competes through specialized hydrated lime grades tailored to municipal water treatment standards.
Lime is calcium oxide or calcium hydroxide produced by calcining limestone at temperatures exceeding 900 degrees Celsius, yielding quicklime that slakes to hydrated lime for pH control, fluxing, and chemical synthesis. Quicklime commands the largest revenue pool in steel and flue gas treatment, while hydrated lime is displacing alternatives in municipal water alkalinity adjustment. Dolomitic lime occupies a defensible niche in glass manufacturing and specialty agriculture where magnesium content carries premium pricing.
EPA enforcement of the Clean Air Act and National Ambient Air Quality Standards forces continuous investment in dry sorbent injection systems at coal-fired utilities, directly lifting lime consumption. OSHA permissible exposure limits for respirable crystalline silica shape workplace handling protocols and product packaging specifications. Stakeholders must weigh EPA mercury and air toxics standards against the pace of coal plant retirements when committing to long-term supply contracts.
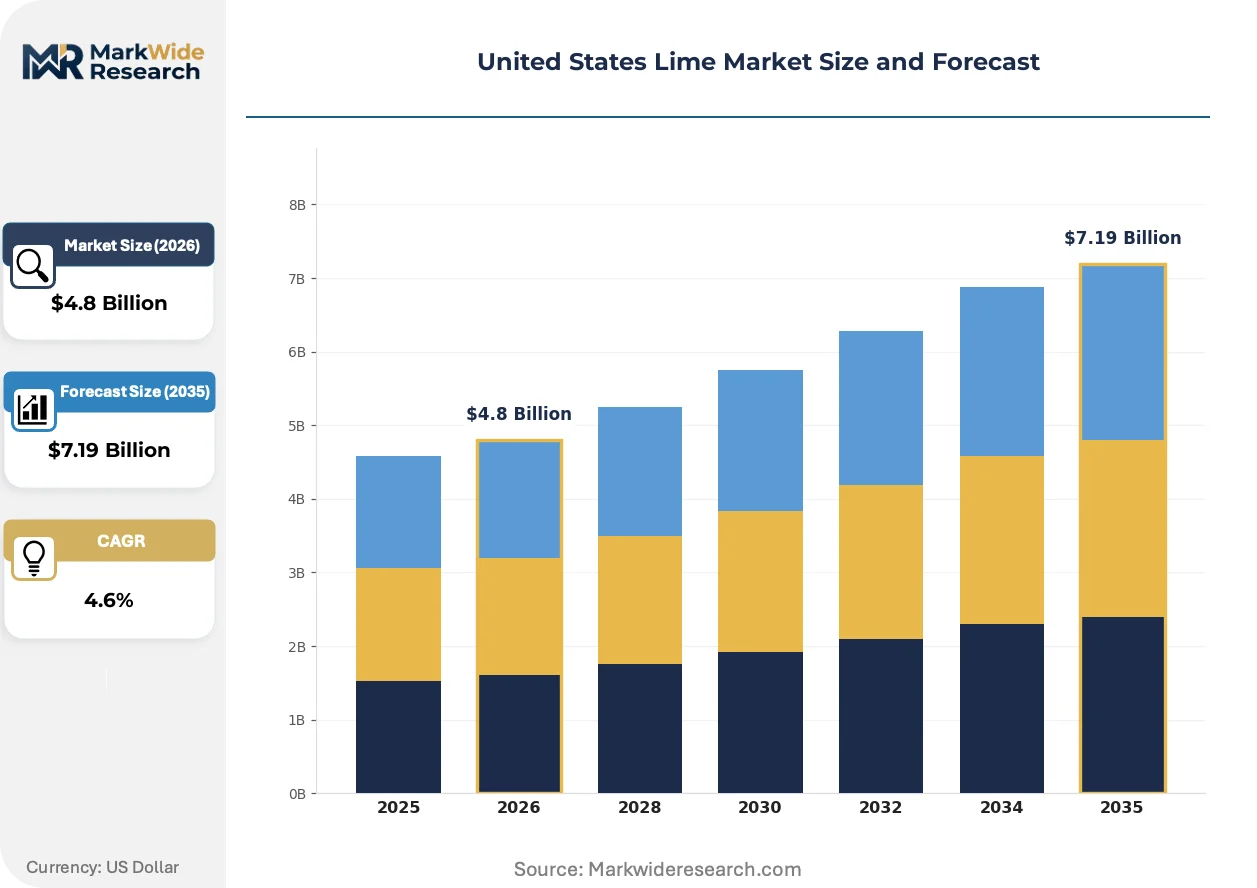
Market Dynamics
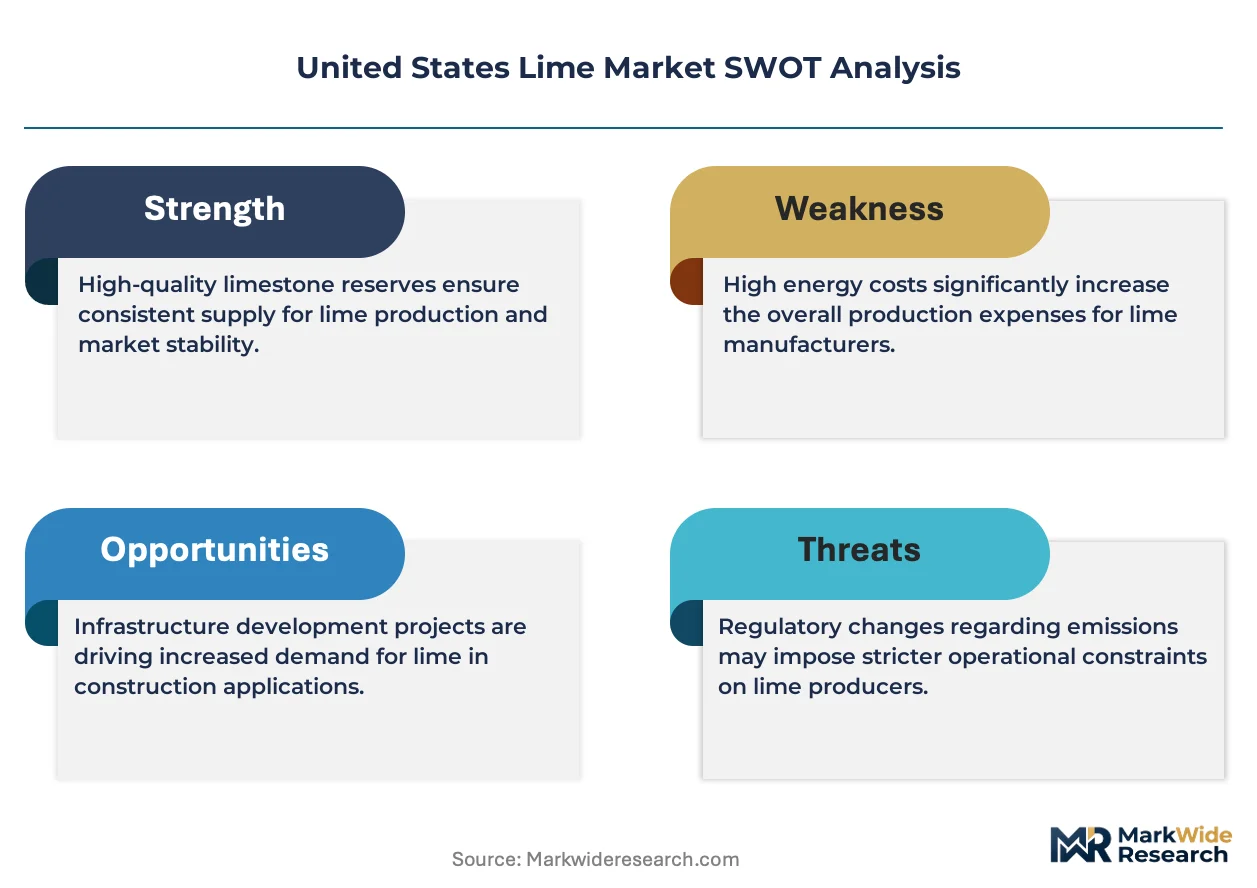
EPA enforcement of the Clean Air Act and National Ambient Air Quality Standards is forcing continuous capital deployment in dry sorbent injection systems at coal-fired utilities, directly lifting lime consumption while tightening product specifications for mercury capture efficiency.
Growth Catalysts
- Steel decarbonization mandates:Electric arc furnace expansion in the Great Lakes corridor is intensifying demand for high-calcium quicklime in slag conditioning and sulfur removal.
- EPA Mercury and Air Toxics Standards:Compliance deadlines at coal-fired power plants are accelerating dry sorbent injection retrofits that specify hydrated lime reactivity above 90 percent.
- Limestone quarry clustering:Captive dolomitic reserves in Michigan and Ohio are securing supply-chain cost advantages for glass and specialty agriculture customers.
Market Restraints
- Natural gas price volatility:Kiln fuel accounts for 35-45 percent of quicklime production cost, exposing margins to Henry Hub fluctuations.
- Coal plant retirement schedules:Utility demand erosion in the Ohio River Valley is creating stranded capacity in regional calcining infrastructure.
- Fly ash substitution:Supplementary cementitious materials are displacing hydrated lime in select soil stabilization applications.
Strategic Opportunities
- Carbon capture alkalinity:Direct air capture facilities in Texas and Louisiana are piloting calcium looping cycles that consume quicklime in sorbent regeneration.
- Precision agriculture expansion:Variable-rate dolomitic lime application in the Corn Belt is opening service-based revenue models tied to soil pH mapping.
- Infrastructure corrosion control:EPA stormwater permits are mandating hydrated lime for concrete washout neutralization at highway construction sites.
Industry Challenges
- Skilled kiln operator shortage:Vertical shaft and rotary kiln expertise is aging out faster than apprenticeship programs in the Great Lakes region can replenish.
- OSHA silica compliance:Respirable crystalline silica monitoring and packaging redesign are extending product qualification timelines for new hydrated lime grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Lime Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrated Lime, Quicklime, Calcined Lime, Dolomitic Lime End User: Construction, Agriculture, Water Treatment, Chemical Manufacturing Application: Soil Stabilization, Flue Gas Treatment, Pulp & Paper, Steel Production Packaging Type: Bags, Bulk, Drums, Pallets |
| Companies Covered | Carmeuse, Graymont, Martin Marietta Materials, Lhoist North America, United States Lime & Minerals, Mississippi Lime, Cheney Lime & Cement Company, Linwood Mining & Minerals Corporation, Minerals Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Lime Market Evolving Landscape
Digital process control and emissions monitoring are converging to redefine lime quality specifications across steel, water treatment, and environmental compliance verticals. These shifts are compressing batch-to-batch variability tolerances and rewarding suppliers with captive analytical capabilities.
Advanced reactivity testing using laser diffraction particle size analysis is expanding into contract specifications for dry sorbent injection. Coal-fired utilities in the Ohio River Valley are mandating specific surface area minimums above 15 square meters per gram to guarantee mercury oxidation efficiency. This instrumentation requirement is compressing the supplier base to operations with in-house metrology labs.
EPA's proposed Good Neighbor Plan updates under the Clean Air Act are tightening ozone transport budgets for upwind states. Industrial facilities in Texas and the Midwest are responding by accelerating hydrated lime purchases for selective catalytic reduction support. The rulemaking timeline is compressing procurement cycles from annual to quarterly contracting.
Steel mills are consolidating lime purchasing through integrated supply agreements that bundle quicklime with slag handling services. ArcelorMittal and Cleveland-Cliffs operations in Indiana and Ohio are leading this shift away from spot-market transactions. The model is displacing traditional distributor relationships in the Great Lakes corridor.
United States Lime Market Segmentation
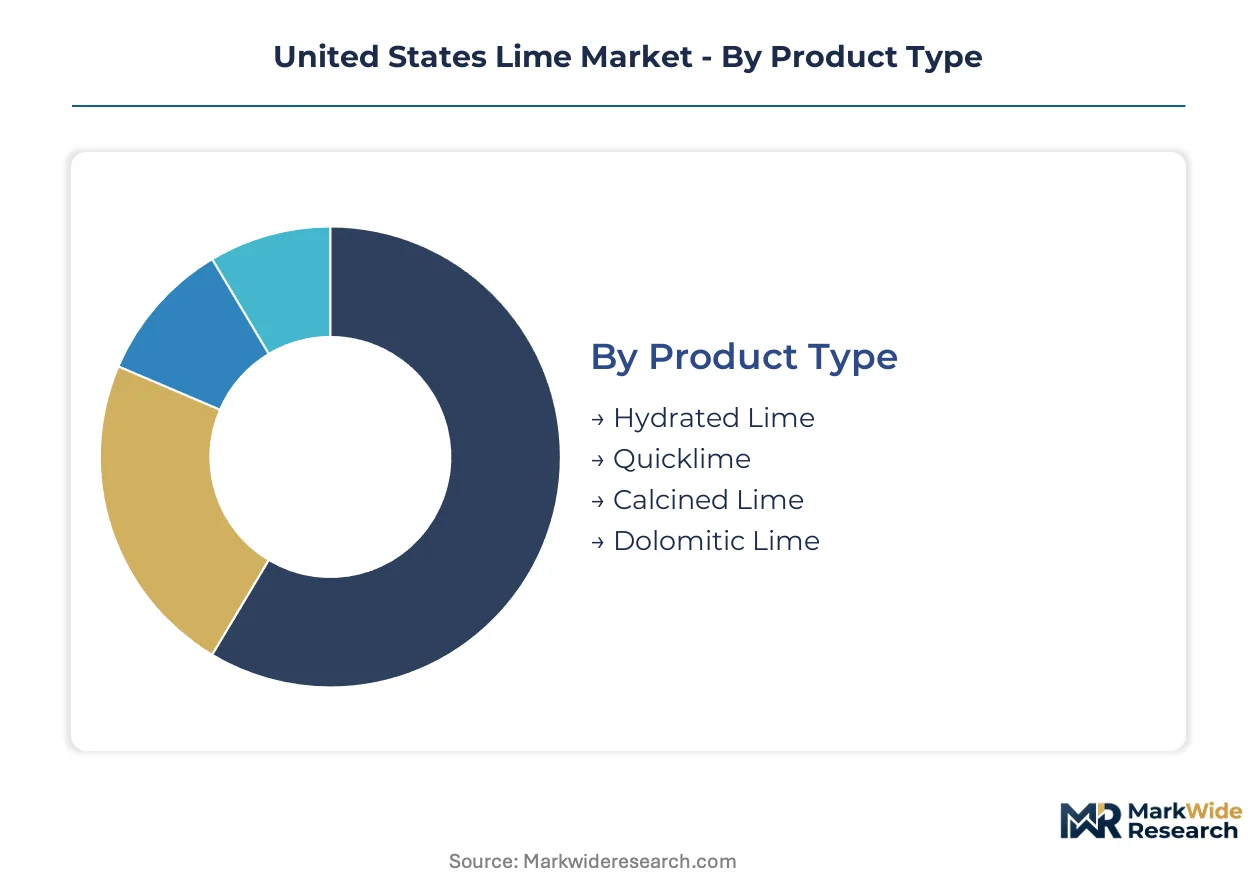
Lime procurement in the United States splits across technical specifications, delivery formats, and end-use chemistry requirements. Each segmentation axis carries distinct margin profiles and supply-chain rigidity that shapes vendor selection and contract structuring.
Product Type:
Calcination temperature and limestone feedstock chemistry define the four product categories, with reactivity and magnesium content determining application fit.
- Quicklime:Calcium oxide produced at kiln temperatures exceeding 900°C, yielding the highest available calcium content and reactivity for steel fluxing. Demand concentrates in Great Lakes steel corridors where ArcelorMittal and Cleveland-Cliffs operations require consistent slag conditioning chemistry.
- Hydrated Lime:Calcium hydroxide formed through controlled slaking of quicklime, offering safer handling and precise pH control for water treatment. Municipal utilities in the Ohio River Valley are expanding specifications for mercury capture efficiency above 90 percent reactivity.
- Calcined Lime:Intermediate calcination product with variable porosity used in specialty chemical synthesis and refractory applications. Demand tracks pharmaceutical and glass manufacturing clusters in New Jersey and Pennsylvania.
- Dolomitic Lime:Double carbonate containing magnesium oxide, commanding premium pricing in specialty agriculture and container glass where magnesium content reduces thermal expansion.
Mature deployment sits with Quicklime in legacy steel and chemical infrastructure. Newer deployment is concentrated in Hydrated Lime as EPA flue gas treatment mandates tighten reactivity specifications.
End User:
Customer concentration and contract duration vary sharply across industrial, municipal, and agricultural buyers.
- Construction:Soil stabilization and asphalt modification drive bulk consumption, with state DOT specifications in Texas and California mandating hydrated lime for clay modification. Highway spending cycles create lumpiness in quarterly demand.
- Agriculture:Corn Belt pH correction and specialty crop magnesium supplementation sustain regional dolomitic lime consumption. Variable-rate application technology is shifting purchasing from commodity spot to service-integrated contracts.
- Water Treatment:Municipal alkalinity adjustment and industrial wastewater neutralization require certified low-impurity grades. EPA Lead and Copper Rule revisions are tightening purity specifications for drinking water applications.
- Chemical Manufacturing:Precipitated calcium carbonate feedstock and acetylene production consume high-calcium quicklime with strict trace metal limits. Gulf Coast petrochemical corridors anchor demand.
Long-term supply agreements dominate Water Treatment procurement. Spot-market flexibility persists in Agriculture where seasonal application windows compress purchasing decisions.
Application:
Process integration depth and regulatory exposure differentiate the four application clusters.
- Steel Production:Slag conditioning and desulfurization consume the highest volume per facility, with electric arc furnace expansion in Indiana and Ohio intensifying quicklime specifications for sulfur removal efficiency.
- Flue Gas Treatment:Dry sorbent injection at coal-fired utilities and industrial boilers specifies surface area minimums above 15 square meters per gram for mercury oxidation. EPA Mercury and Air Toxics Standards compliance deadlines are compressing procurement cycles.
- Soil Stabilization:Highway subgrade modification and contaminated site remediation use hydrated lime for clay pozzolanic reaction. Fly ash substitution is eroding share in select geotechnical applications.
- Pulp & Paper:Chemical recovery and bleaching operations consume high-availability quicklime, though capacity closures in the Southeast are dampening regional demand.
Regulatory enforcement intensity peaks in Flue Gas Treatment. Technology transition risk concentrates in Pulp & Paper as digital substitution accelerates.
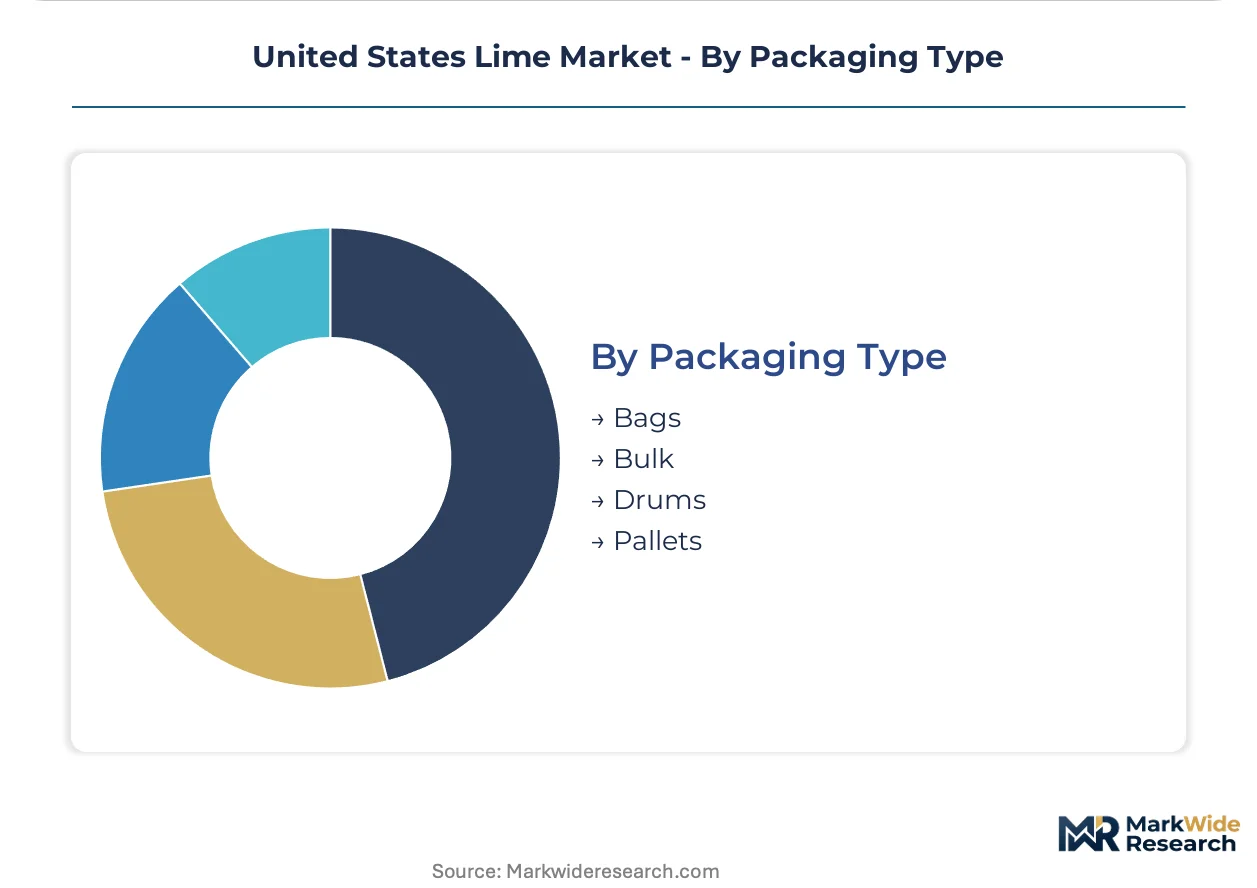
Packaging Type:
Logistics economics and handling safety requirements segment delivery formats.
- Bulk:Pneumatic tanker delivery dominates high-volume steel and utility customers, minimizing handling costs and silica exposure. Great Lakes corridor operations favor captive rail unloading infrastructure.
- Bags:50-pound multi-wall paper sacks serve construction and agricultural spot buyers requiring inventory flexibility. OSHA silica compliance is driving breathable packaging redesign.
- Drums:Steel and fiber containers protect high-reactivity hydrated lime from moisture degradation in humid Gulf Coast climates.
- Pallets:Unitized loads support just-in-time delivery for mid-scale water treatment facilities with limited storage silo capacity.
Cost minimization favors Bulk for integrated industrial consumers. Handling safety and inventory constraints sustain Bags for fragmented construction and agricultural buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes industrial corridor anchors United States lime consumption, with calcining infrastructure clustered along Lake Michigan and Lake Erie to serve steel mills and coal-fired utilities. Regional demand patterns track EPA enforcement zones, limestone deposit geology, and electric arc furnace expansion timelines across the Midwest and Southeast.
Great Lakes Region
Steel production in Indiana and Ohio consumes the highest per-facility lime volumes for slag conditioning and desulfurization. EPA Mercury and Air Toxics Standards compliance deadlines at utilities along the Ohio River are accelerating hydrated lime procurement for dry sorbent injection retrofits. Carmeuse and Graymont maintain captive quarry-kiln networks in Michigan and Ohio to secure cost advantages for bulk quicklime delivery.
Southeast
Pulp and paper operations in Georgia and Alabama sustain regional quicklime demand for chemical recovery, though digital substitution is compressing capacity utilization. EPA stormwater permit enforcement across Florida highway construction is mandating hydrated lime for concrete washout neutralization. Dolomitic lime consumption for container glass manufacturing concentrates near Atlanta and Charlotte.
Texas and Louisiana
Gulf Coast petrochemical corridors anchor chemical-grade quicklime demand for acetylene production and precipitated calcium carbonate feedstock. Direct air capture pilot facilities in Houston and Lake Charles are testing calcium looping cycles that regenerate quicklime sorbents. OSHA silica exposure monitoring requirements are reshaping packaging specifications for humid-climate hydrated lime storage.
California
State DOT specifications for highway subgrade modification sustain hydrated lime consumption for clay soil stabilization in Central Valley infrastructure projects. EPA National Ambient Air Quality Standards enforcement in the Los Angeles basin is tightening flue gas treatment requirements at remaining industrial boilers. Water treatment utilities in the Bay Area are expanding low-impurity hydrated lime specifications for Lead and Copper Rule compliance.
Mountain West
Precision agriculture adoption in Colorado and Idaho is shifting dolomitic lime purchasing toward service-integrated contracts tied to soil pH mapping. Natural gas price volatility exposes kiln margins in Wyoming and Utah, where remote quarry locations lack rail access to bulk industrial buyers. Regional steel demand remains minimal compared to Great Lakes and Southeast corridors.
United States Lime Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across distinct procurement channels in the United States lime market. The supplier base concentrates around vertically integrated quarry-kiln operators with captive limestone reserves and regional distributors serving fragmented construction and agricultural buyers. Three archetypes dominate: integrated producers with rail-served calcining infrastructure, regional specialists in hydrated lime grades, and construction-material distributors bundling lime with cement and aggregates. Competitive positioning hinges on securing captive limestone reserves and securing long-term supply agreements with steel mills and utilities.
Within the integrated producer tier, Carmeuse and Graymont exemplify archetypes of scale-driven quarry-kiln operators with Great Lakes corridor dominance. Mississippi Lime occupies a position among regional specialists focused on high-reactivity hydrated lime grades for water treatment and environmental compliance. United States Lime & Minerals represents the publicly traded independent model with Texas-based operations serving chemical and petrochemical demand.
| Leading Market Players |
|---|
| Carmeuse |
| Graymont |
| Martin Marietta Materials |
| Lhoist North America |
| United States Lime & Minerals |
| Mississippi Lime |
| Cheney Lime & Cement Company |
| Linwood Mining & Minerals Corporation |
| Minerals Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Natural gas kiln fuel traces a direct path from Henry Hub volatility through production cost tiers to contract pricing differentials between integrated Great Lakes producers and regional distributors serving fragmented agricultural buyers.
Pricing Analysis
Yield-based pricing anchors quicklime contracts to sulfur removal efficiency in electric arc furnace slag conditioning, with ArcelorMittal and Cleveland-Cliffs operations penalizing batch variability above tight specification bands. Price differentiation separates high-reactivity hydrated lime certified for mercury capture above 90 percent reactivity from commodity grades used in construction soil stabilization. Pricing pressure stems from coal plant retirement schedules eroding utility offtake volumes in the Ohio River Valley. Municipal water treatment utilities exhibit lowest price sensitivity due to regulatory compliance mandates, while seasonal agricultural spot buyers negotiate aggressively on delivered cost per ton.
Supply Chain Analysis
Regional distribution centers in Michigan and Ohio operate hub-and-spoke patterns radiating from captive quarry-kiln complexes to steel mill silos and utility storage domes. Geographic supply concentrates in the Great Lakes corridor, Texas-Louisiana Gulf Coast, and scattered Mountain West operations. Raw material dependencies include high-calcium limestone deposits, dolomitic reserves for specialty grades, and consistent natural gas supply for calcining heat. Supply chain risk centers on single-source vulnerability where rail-served kilns lack modal alternatives. Distribution runs through pneumatic tanker bulk for integrated industrial consumers and bagged pallet loads for construction and agricultural channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coal plant retirement timelines are forcing calcining capacity consolidation, eliminating regional players lacking long-term steel or water treatment supply agreements.
For Market Incumbents: Hedge utility demand erosion by deepening captive supply relationships with electric arc furnace operators in Indiana and Ohio. Secure limestone reserve extensions through lease conversions in Michigan dolomitic corridors before competing bidders emerge. Reinforce analytical capabilities for laser diffraction particle size testing to meet tightening mercury capture specifications from EPA enforcement. For New Entrants and Emerging Players: Capture precision agriculture service contracts in Colorado and Idaho where variable-rate application technology shifts purchasing from commodity spot to soil pH mapping bundles. Target carbon capture alkalinity pilots in Texas and Louisiana where direct air capture facilities are testing calcium looping sorbent regeneration. Enter through equipment-integrated service models rather than standalone lime supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor rail-served calcining assets with captive limestone reserves in the Great Lakes corridor where stranded utility capacity creates acquisition opportunities. Long-term viability hinges on exposure to steel decarbonization and EPA compliance rather than coal plant economics. Monitor EPA Mercury and Air Toxics Standards enforcement intensity as the inflection signal for hydrated lime demand recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Carmeuse and Graymont secure cost advantages through captive Michigan and Ohio quarry control. |
| Long-term Supply Agreement with Steel Producers | ArcelorMittal and Cleveland-Cliffs bundle quicklime procurement with slag handling services. |
| Green Manufacturing Transition | Electric arc furnace expansion intensifies demand for high-calcium quicklime in sulfur removal. |
| Joint Venture for Carbon Capture Alkalinity | Texas and Louisiana pilots test calcium looping cycles for direct air capture sorbent regeneration. |
| Capacity Expansion in Water Treatment Grades | EPA Lead and Copper Rule revisions tighten purity specifications for municipal hydrated lime. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving kiln operations managers, steel procurement leads, municipal water treatment engineers, and EPA compliance officers. National Lime Association production surveys, EIA energy cost data, SEC 10-K filings from publicly traded producers, and EPA enforcement databases provided quantitative foundations. Bottom-up capacity modeling triangulated against top-down consumption estimates from end-use industry associations.
Granularity-level modeling deployed separate reactivity and purity specifications across quicklime, hydrated lime, calcined lime, and dolomitic lime product tiers. End-use segmentation tracked steel production, flue gas treatment, water treatment, construction, agriculture, and chemical manufacturing demand pools. Geographic disaggregation captured Great Lakes, Southeast, Texas-Louisiana, California, and Mountain West regional dynamics. CAGRs were derived from regression-weighted capacity utilization trends and regulatory compliance deadline impacts across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to coal plant retirement acceleration, natural gas price volatility, and electric arc furnace expansion timing. Forecasts reflect documented assumptions regarding EPA enforcement continuity and steel decarbonization policy stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Maleic Anhydride Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Sodium Thiosulphate Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Ethylene and Propylene Market