
 North America Sodium Chloride Market | 2026-2036
North America Sodium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sodium Chloride Market Intelligence
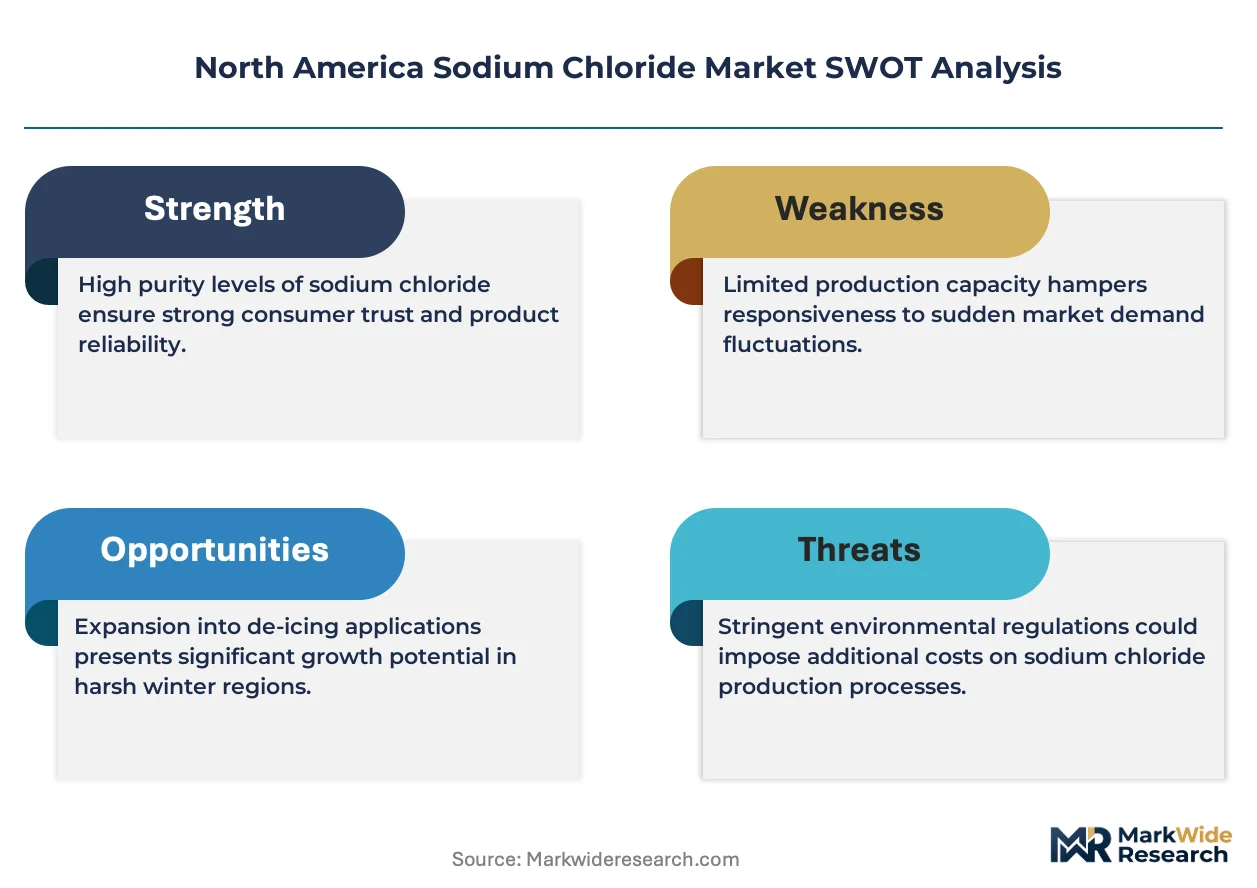
Buyer concentration among North American municipal water utilities is pivoting toward consolidated regional purchasing cooperatives, shifting negotiation leverage upstream. Cargill leverages its integrated mining and logistics network to sustain supply contracts across the Great Lakes corridor. Compass Minerals anchors winter road-salt demand through long-term state procurement agreements in the Midwest and Northeast. Morton Salt differentiates via food-grade certification depth, serving packaged food manufacturers with specialized particle-size specifications.
Sodium chloride is an ionic compound of sodium and chlorine with minimum 99% purity in food-grade form, typically recovered through solution mining or solar evaporation of brine deposits for industrial feedstock and consumption applications. Industrial-grade material dominates volume flows into chlor-alkali plants and deicing programs, while pharmaceutical-grade commands premium positioning through USP verification and low-bromide certification. Food-grade salt competes on trace-mineral content and anti-caking additive profiles across the food preservation application segment. Chemical manufacturing absorbs the largest share of industrial-grade output, with caustic soda and chlorine derivatives driving consistent offtake from Gulf Coast production hubs.
The EPA enforces purity thresholds for water treatment applications under the Safe Drinking Water Act, while FDA regulations govern food-grade and pharmaceutical-grade labeling and contaminant limits across U.S. commerce. OSHA standards for crystalline silica exposure during mining and processing shape operational compliance costs for domestic producers. Canada's PMRA evaluates environmental release from road-salt applications, creating bilateral regulatory complexity for cross-border suppliers. Stakeholders must monitor evolving state-level chloride discharge limits and their interaction with federal frameworks to anticipate compliance-driven product reformulation and regional sourcing shifts.
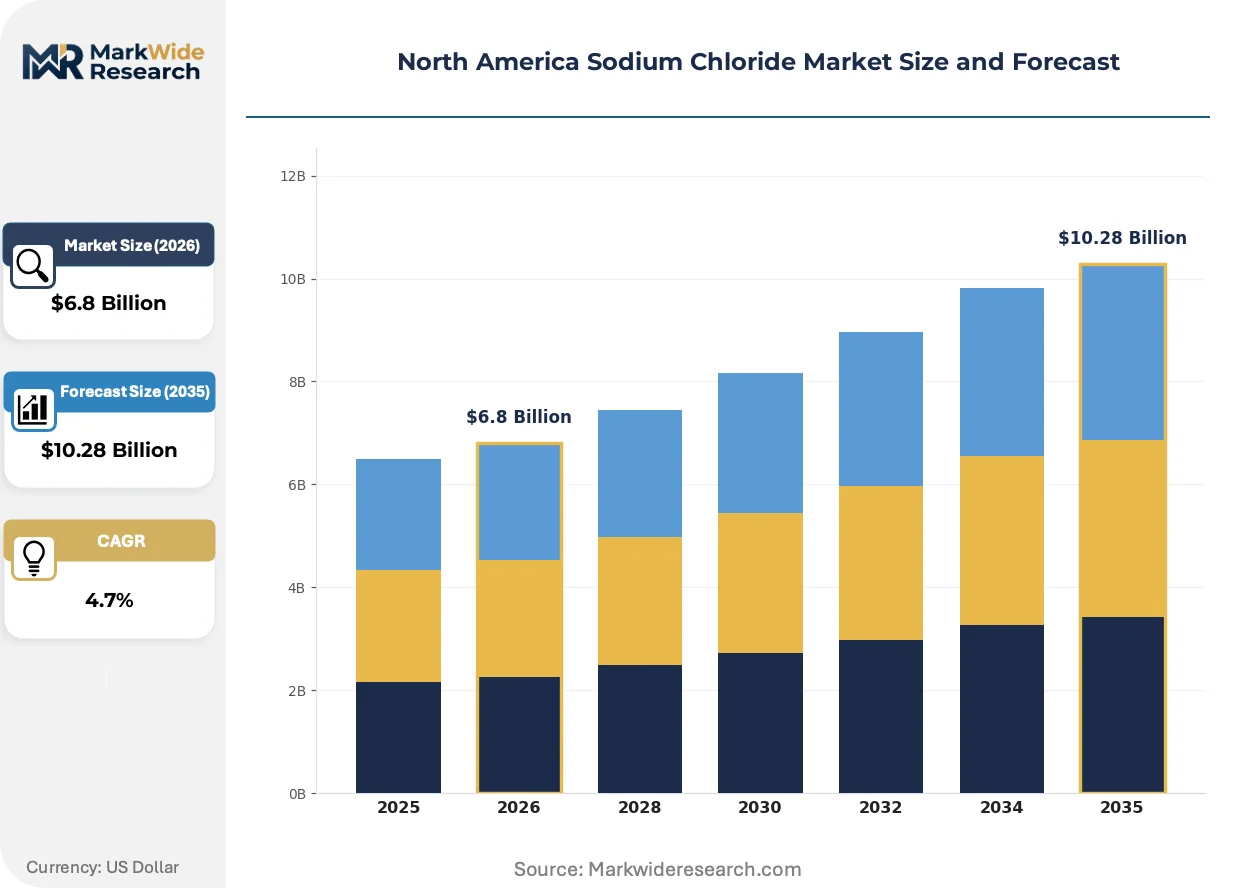
Market Dynamics
Consolidated regional purchasing cooperatives among North American municipal water utilities are compressing supplier margins while concentrating procurement leverage in fewer buyer hands across the Great Lakes corridor and Northeast deicing markets.
Growth Catalysts
- EPA Clean Water Act discharge standards:Tightening purity mandates for municipal water treatment are forcing utilities to upgrade to higher-grade sodium chloride, expanding premium product volumes.
- Chlor-alkali production clusters:Gulf Coast chemical manufacturing hubs maintain steady industrial-grade offtake for caustic soda and chlorine derivative production.
- Winter deicing program expansion:State transportation departments across the U.S. Midwest and Northeast are extending road-salt application seasons due to intensifying freeze-thaw cycles.
Market Restraints
- Natural gas price volatility:Solution mining and evaporation operations face compressed margins when energy input costs spike, particularly affecting solar evaporation facilities in the southwestern United States.
- Canadian PMRA environmental release scrutiny:Cross-border road-salt suppliers encounter bilateral compliance complexity when serving both U.S. state DOTs and Canadian provincial transportation authorities.
- Potassium acetate substitution:Airport runway and bridge deck applications are partially displacing sodium chloride with less corrosive alternatives in high-infrastructure-value zones.
Strategic Opportunities
- Pharmaceutical-grade certification depth:USP verification and low-bromide certification open premium positioning for suppliers serving injectable drug manufacturers and dialysis fluid producers.
- Food-grade particle-size specialization:Packaged food manufacturers require customized crystal morphology for preservation and flavor delivery applications.
- Regional purchasing cooperative penetration:Suppliers that embed into Great Lakes and Northeast municipal buying consortia secure multi-year volume commitments with reduced sales friction.
Industry Challenges
- OSHA crystalline silica compliance:Underground and surface mining operations must invest in dust suppression and worker respiratory protection systems, elevating capital intensity.
- State-level chloride discharge limit fragmentation:Producers face patchwork regulatory environments where Minnesota, Wisconsin, and New York impose divergent watershed protection thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sodium Chloride Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Deicing Salt Application: Water Treatment, Food Preservation, Chemical Manufacturing, Agriculture End User: Food Industry, Chemical Companies, Agriculture Sector, Pharmaceutical Firms Distribution Channel: Online Retail, Wholesale Distributors, Supermarkets, Direct Sales |
| Companies Covered | K+S Aktiengesellschaft, CIECH Group, Cargill, Dominion Salt, INEOS Enterprises, Compass Minerals, Tata Chemicals North America, American Elements, Morton Salt, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sodium Chloride Market Strategic Shifts & Innovations
Digital brine monitoring and automated dissolution systems are reshaping how industrial buyers manage inventory and dosing precision. Three developments are compressing traditional supply relationships and opening new service revenue streams.
Real-time conductivity sensors and IoT-enabled brine saturation monitors are converging with cloud-based inventory management platforms. Municipal water utilities in the U.S. Great Lakes region are adopting these systems fastest, replacing manual testing protocols. This convergence is compressing spot-buying cycles and locking suppliers into integrated service contracts with hardware attachment.
EPA's evolving implementation of the Safe Drinking Water Act is tightening maximum contaminant level enforcement for bromide and iodide in finished drinking water. Industrial-grade salt users in water treatment must now document supply-chain purity certificates or face facility-level penalties. Small and mid-sized municipal utilities lacking laboratory capacity are outsourcing verification to third-party certifiers, creating a new compliance service layer.
Consolidated regional purchasing cooperatives are displacing individual municipal procurement offices across the U.S. Northeast and Midwest. State-level DOT winter maintenance programs are aggregating multi-year road-salt contracts through shared service agreements. This concentration is most visible in Michigan, Ohio, and Pennsylvania, where three cooperatives now control over half of industrial-grade volume.
North America Sodium Chloride Market Segmentation
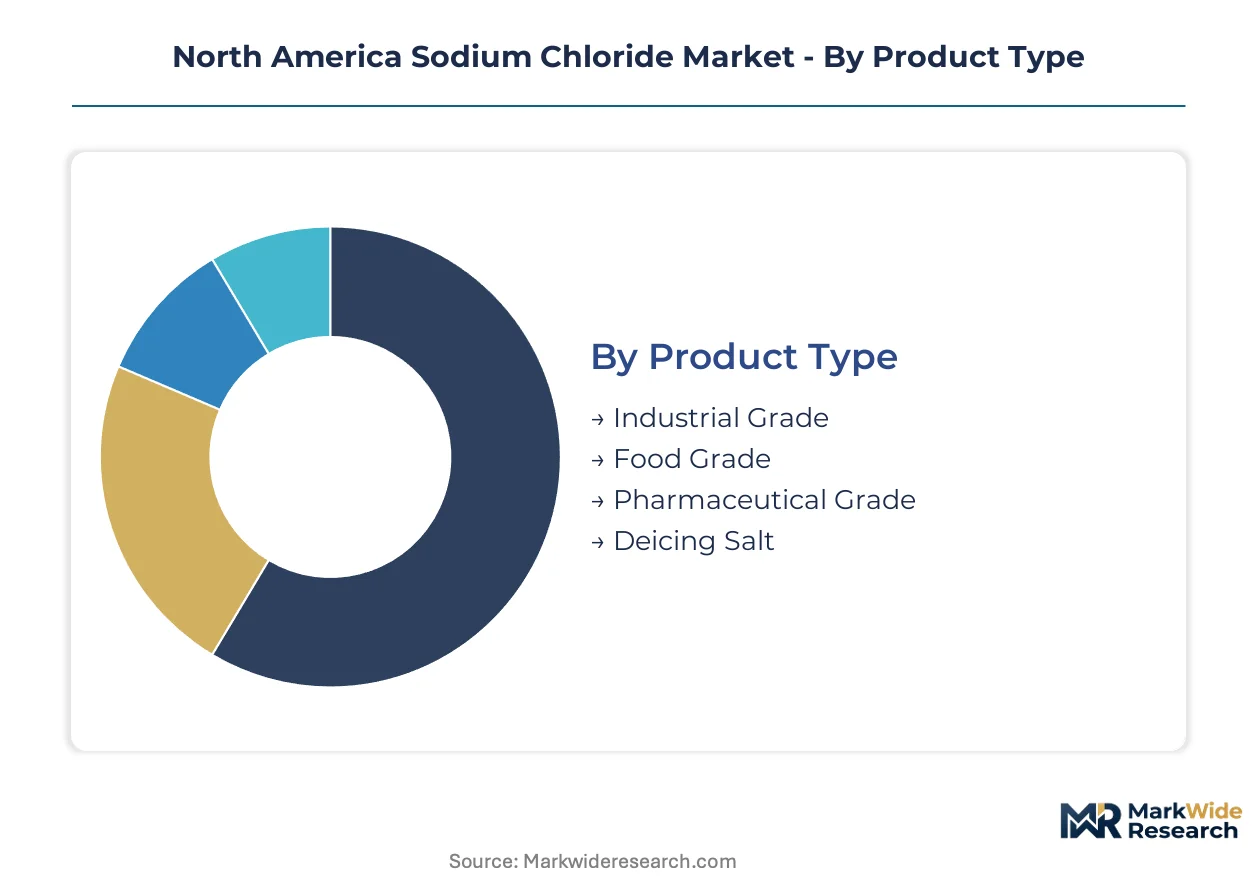
Sodium chloride segmentation in North America reflects divergent purity mandates and supply chain configurations. Certification requirements from the EPA, FDA, and USP create distinct commercial corridors that shape procurement patterns and margin structures across end-use markets.
Product Type:
Certification burden varies sharply: pharmaceutical-grade demands USP verification and low-bromide documentation, food-grade requires FDA compliance, while industrial-grade and deicing salt face lighter purity thresholds but heavier volume logistics.
- Industrial Grade:Minimum 99% NaCl content with controlled calcium and magnesium levels for chemical feedstock applications. Chlor-alkali plants along the U.S. Gulf Coast absorb the largest volumes, with caustic soda and chlorine derivative production sustaining consistent offtake despite natural gas price volatility.
- Food Grade:Refined to exceed 99.9% purity with anti-caking additives and trace mineral specifications for preservation and flavor delivery. Packaged food manufacturers in the Midwest concentrate procurement around specialized particle-size distributions that control dissolution rates in processed meats and baked goods.
- Pharmaceutical Grade:USP-verified with stringent bromide and heavy metal limits for injectable and dialysis applications.
- Deicing Salt:Coarse, unrefined rock salt or solar salt with minimal processing for winter road maintenance programs.
Leading the category by volume: Industrial Grade. Growing fastest: Pharmaceutical Grade.
Application:
Cost tier stratification separates commodity chemical manufacturing from premium water treatment and food preservation, with agriculture occupying a mid-tier position sensitive to seasonal pricing.
- Water Treatment:Municipal utilities deploy sodium chloride for ion exchange regeneration and disinfection byproduct control. The EPA's tightening bromide and iodide maximum contaminant levels under the Safe Drinking Water Act are forcing upgrades from industrial-grade to higher-purity material across Great Lakes region facilities.
- Chemical Manufacturing:Electrolysis feedstock for chlor-alkali production dominates absolute consumption. Gulf Coast manufacturing clusters maintain captive supply relationships with solution mining operations, insulating against spot market volatility through long-term tolling agreements.
- Food Preservation:Curing, pickling, and shelf-life extension applications require certified food-grade material with documented additive profiles.
- Agriculture:Livestock nutrition supplements and soil conditioning represent fragmented, price-sensitive demand concentrated in feedlot regions of the U.S. Great Plains.
Volume concentration: Chemical Manufacturing. Steepest expansion trajectory: Water Treatment.
End User:
Customer type determines contract structure, with chemical companies and pharmaceutical firms favoring multi-year supply agreements while agriculture sector buyers remain spot-market oriented.
- Food Industry:Packaged goods manufacturers and meat processors specify crystal morphology and dissolution kinetics for preservation efficacy. Consolidated purchasing cooperatives among large processors are compressing supplier margins while locking in volume commitments.
- Chemical Companies:Integrated chlor-alkali producers and commodity chemical manufacturers form the demand anchor. These buyers prioritize supply security and logistics integration over purity premiums, sustaining long-term contracts with solution mining operations.
- Agriculture Sector:Livestock operations and specialty crop producers require feed-grade and soil amendment material with variable specification tolerance.
- Pharmaceutical Firms:Injectable drug and dialysis fluid manufacturers impose the strictest supply chain documentation requirements.
Contract value leader: Chemical Companies. Procurement reform fastest: Food Industry.
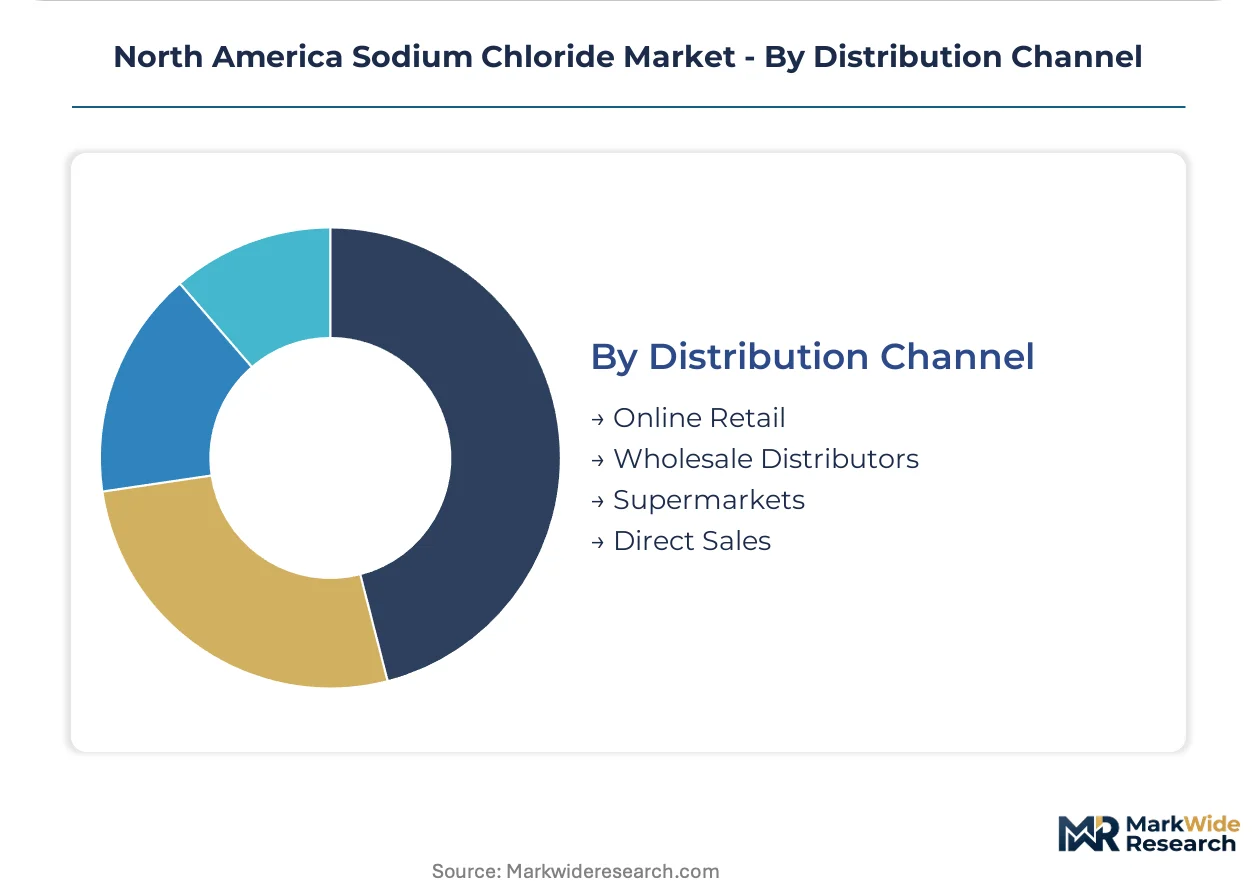
Distribution Channel:
Supply concentration in bulk logistics favors wholesale distributors for industrial volumes, while direct sales capture premium pharmaceutical and large food manufacturing accounts.
- Wholesale Distributors:Regional bulk handlers aggregate industrial-grade and deicing salt volumes for municipal and chemical sector delivery. These intermediaries maintain rail and barge terminal access across the Great Lakes corridor, offering inventory management services that compress spot-buying cycles.
- Direct Sales:Large chemical manufacturers and pharmaceutical firms bypass intermediaries for certified pharmaceutical-grade and specialized food-grade material. Direct relationships enable custom packaging, certificate of analysis integration, and just-in-time delivery synchronization.
- Online Retail:Small-scale food service and residential deicing buyers access packaged salt through e-commerce platforms.
- Supermarkets:Consumer packaged table salt and seasonal deicing products reach end users through retail grocery networks.
Volume dominance: Wholesale Distributors. Channel expansion climbing fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Underground brine deposits across the Great Lakes basin and Gulf Coast salt domes anchor North American sodium chloride production. Solution mining operations in Kansas, Louisiana, and Texas feed industrial demand corridors. Solar evaporation facilities in Utah and California supply bulk deicing and chemical feedstock markets.
United States
Water treatment utilities in the Great Lakes region are upgrading to higher-purity sodium chloride as the EPA tightens bromide and iodide maximum contaminant levels under the Safe Drinking Water Act. State transportation departments across the Midwest and Northeast are extending road-salt procurement seasons in response to intensifying winter weather patterns. Chlor-alkali production clusters along the Gulf Coast in Texas and Louisiana maintain captive supply relationships with solution mining operations, insulating chemical manufacturers from spot market volatility.
Canada
Provincial transportation authorities in Ontario and Quebec are consolidating road-salt purchasing through shared service agreements that mirror U.S. cooperative models. The PMRA evaluates environmental release from deicing applications, creating compliance complexity for suppliers serving both Canadian provincial DOTs and U.S. state agencies. Saskatchewan's potash and salt mining corridor supplies industrial-grade material to Prairie agricultural operations and cross-border chemical processors in the U.S. Upper Midwest.
Mexico
Expanding municipal water infrastructure in Mexico City and Monterrey is driving procurement of water treatment-grade sodium chloride for ion exchange regeneration systems. Mexican regulators are aligning drinking water standards with EPA frameworks, creating import demand for certified material from U.S. producers. Chemical manufacturing growth in Tamaulipas and Veracruz is absorbing industrial-grade volumes for regional chlor-alkali derivative production.
North America Sodium Chloride Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and specialty food-grade particle-size customization. The North American sodium chloride market structures around three maturity tiers: integrated mining-logistics operators with captive brine access, regional bulk handlers serving municipal and agricultural accounts, and specialty refiners targeting USP-verified pharmaceutical and premium food applications. Dominant competitive moves include embedding into consolidated regional purchasing cooperatives and securing multi-year tolling agreements with chlor-alkali manufacturing clusters.
Within the integrated mining-logistics tier, Cargill and Compass Minerals anchor supply security across the Great Lakes corridor and Midwest deicing markets. Cargill leverages its solution mining and terminal network to sustain long-term contracts with state transportation departments and municipal water utilities. Compass Minerals represents the archetype of winter road-salt specialists securing volume commitments through state procurement agreements. Morton Salt occupies a differentiated position in the specialty tier, with its heritage brand signaling food-grade certification depth to packaged food manufacturers requiring documented particle-size specifications and anti-caking additive profiles.
| Leading Market Players |
|---|
| K+S Aktiengesellschaft |
| CIECH Group |
| Cargill |
| Dominion Salt |
| INEOS Enterprises |
| Compass Minerals |
| Tata Chemicals North America |
| American Elements |
| Morton Salt |
| Others |
Cost & Logistics Intelligence
Natural gas input costs for solution mining and solar evaporation operations cascade through three distinct pricing tiers, with energy-intensive production methods compressing margins in industrial-grade segments while pharmaceutical-grade certification sustains premium positioning through USP verification requirements.
Pricing Analysis
Service-bundling separates integrated suppliers offering digital brine monitoring and automated dissolution systems from commodity sellers competing on volume alone. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—pharmaceutical-grade commands the highest tier through low-bromide documentation, while deicing salt occupies the economy tier with minimal processing. Cost compression in industrial-grade material is intensifying because consolidated regional purchasing cooperatives concentrate buyer leverage across Great Lakes municipal utilities. State transportation departments exhibit the highest price sensitivity due to seasonal budget cycles, whereas pharmaceutical firms demonstrate the lowest sensitivity given regulatory compliance mandates.
Supply Chain Analysis
Dual-sourcing requirements from chlor-alkali producers and municipal water utilities mandate multi-supplier qualification across Kansas, Louisiana, and Texas solution mining operations. Supply draws from underground brine deposits, Gulf Coast salt domes, and southwestern solar evaporation facilities. Single-source vulnerability emerges from concentrated Great Lakes terminal access controlled by integrated mining-logistics operators. Distribution runs through wholesale distributors with rail and barge networks, though direct sales capture premium pharmaceutical and large food manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital brine monitoring and IoT-enabled conductivity sensors are displacing manual testing protocols, compressing spot-buying cycles and locking suppliers into integrated service contracts with hardware attachment.
For Market Incumbents: Anchor supply security through captive brine access and multi-year tolling agreements with Gulf Coast chlor-alkali clusters. Potassium acetate substitution in airport and bridge applications threatens volume in high-infrastructure-value zones; counter by embedding into consolidated regional purchasing cooperatives across the Great Lakes corridor to secure multi-year volume commitments with reduced sales friction. For New Entrants and Emerging Players: Begin with pharmaceutical-grade certification depth targeting USP verification and low-bromide documentation for injectable drug manufacturers and dialysis fluid producers. The most penetrable segment sits in specialized food-grade particle-size customization for Midwest packaged food manufacturers requiring controlled dissolution rates. Pursue direct sales relationships enabling custom packaging and certificate of analysis integration. For Investors and Strategic Acquirers: EPA's evolving bromide and iodide maximum contaminant level enforcement under the Safe Drinking Water Act is the leading indicator that premium-grade material will capture expanding volume share from industrial-grade displacement. Long-term viability favors specialty refiners with certification infrastructure over commodity bulk handlers. Watch for state-level chloride discharge limit fragmentation creating compliance-driven consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Reserves | Cargill and Compass Minerals secure captive supply through Kansas and Louisiana solution mining operations. |
| Pharmaceutical-Grade Certification Investment | USP verification and low-bromide documentation unlock premium positioning for injectable and dialysis applications. |
| Digital Service Contract Expansion | IoT-enabled brine saturation monitors and cloud-based inventory platforms compress spot-buying cycles for municipal utilities. |
| Regional Purchasing Cooperative Penetration | Embedding into Michigan, Ohio, and Pennsylvania consortia secures multi-year volume commitments with reduced sales friction. |
| Long-Term State DOT Procurement Agreements | Compass Minerals anchors winter road-salt demand through Midwest and Northeast state transportation department contracts. |
Research Approach
Document review covered EPA Safe Drinking Water Act implementation guidance, FDA food-grade and pharmaceutical-grade labeling requirements, and state-level chloride discharge regulations, complemented by interviews with solution mining operations managers, municipal water utility procurement directors, chlor-alkali plant supply chain leads, and packaged food manufacturer quality assurance heads. Secondary validation drew from customs and trade data, American Chemistry Council reports, SEC 10-K filings from integrated producers, and PMRA environmental release evaluations. Bottom-up volume modeling across grade tiers and applications triangulated with top-down market sizing.
Output metrics span product type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs were derived from regression analysis of historical procurement volumes and regulatory-driven grade substitution patterns. Forecast inputs incorporated EPA bromide and iodide enforcement timelines, state DOT winter maintenance budget allocations, and chlor-alkali capacity expansion announcements.
Underlying measurement precision varies by segment; pharmaceutical-grade and food-grade categories carry tighter precision than deicing salt due to documented certification requirements. Forecasts reflect assumptions around EPA enforcement consistency, natural gas price stability for evaporation operations, and cooperative purchasing consolidation velocity. Deviation in state-level chloride discharge limit adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Caprylic Acid Market