
 Copper Sulfate Market | 2026-2036
Copper Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Sulfate Market Analysis
Electroplating-grade purity thresholds above 99% copper sulfate pentahydrate is unwinding legacy supply arrangements across the value chain. Freeport-McMoRan leverages captive copper concentrate access to sustain downstream chemical output. Glencore competes through integrated smelter-to-salt logistics spanning multiple continents. BASF differentiates via formulated blends that incorporate copper sulfate into broader crop protection portfolios.
Copper sulfate denotes the inorganic compound CuSO₄·5H₂O, typically manufactured through copper scrap or ore dissolution in sulfuric acid followed by crystallization, with standard agricultural grades requiring 25% minimum copper content by weight for fungicidal efficacy. The application dimension shows agriculture occupying the dominant volume share as fungicide and fertilizer feedstock demand persists, while mining chemical consumption for flotation reagents represents the fastest-expanding margin pool amid copper ore grade decline globally. Water treatment applications anchor steady offtake from municipal utilities confronting algal bloom management mandates.
EPA registration requirements under FIFRA govern agricultural copper sulfate formulations in the United States, while REACH substance evaluation in Europe restricts impurities in grades destined for aquaculture and drinking water treatment. China's MEE enforces wastewater discharge limits that elevate demand for high-purity copper sulfate in industrial effluent remediation. Stakeholders must monitor evolving heavy metal thresholds across jurisdictions to anticipate reformulation costs and specification migration timelines.
Market Dynamics
Copper sulfate production gravitates toward jurisdictions with integrated copper smelting infrastructure, as acid regeneration economics and captive concentrate access determine unit cost competitiveness across agricultural and industrial grades.
Growth Catalysts
- Fertilizer manufacturer procurement:Rising phosphate fertilizer blending requirements in Brazil and India pull pentahydrate volumes for micronutrient fortification.
- REACH substance evaluation:Tightening heavy metal thresholds for aquaculture grades in Europe is forcing specification upgrades that favor established high-purity producers.
- Flotation chemistry:Declining copper ore grades globally expand consumption of copper sulfate as an activator in sulfide mineral separation circuits.
Market Restraints
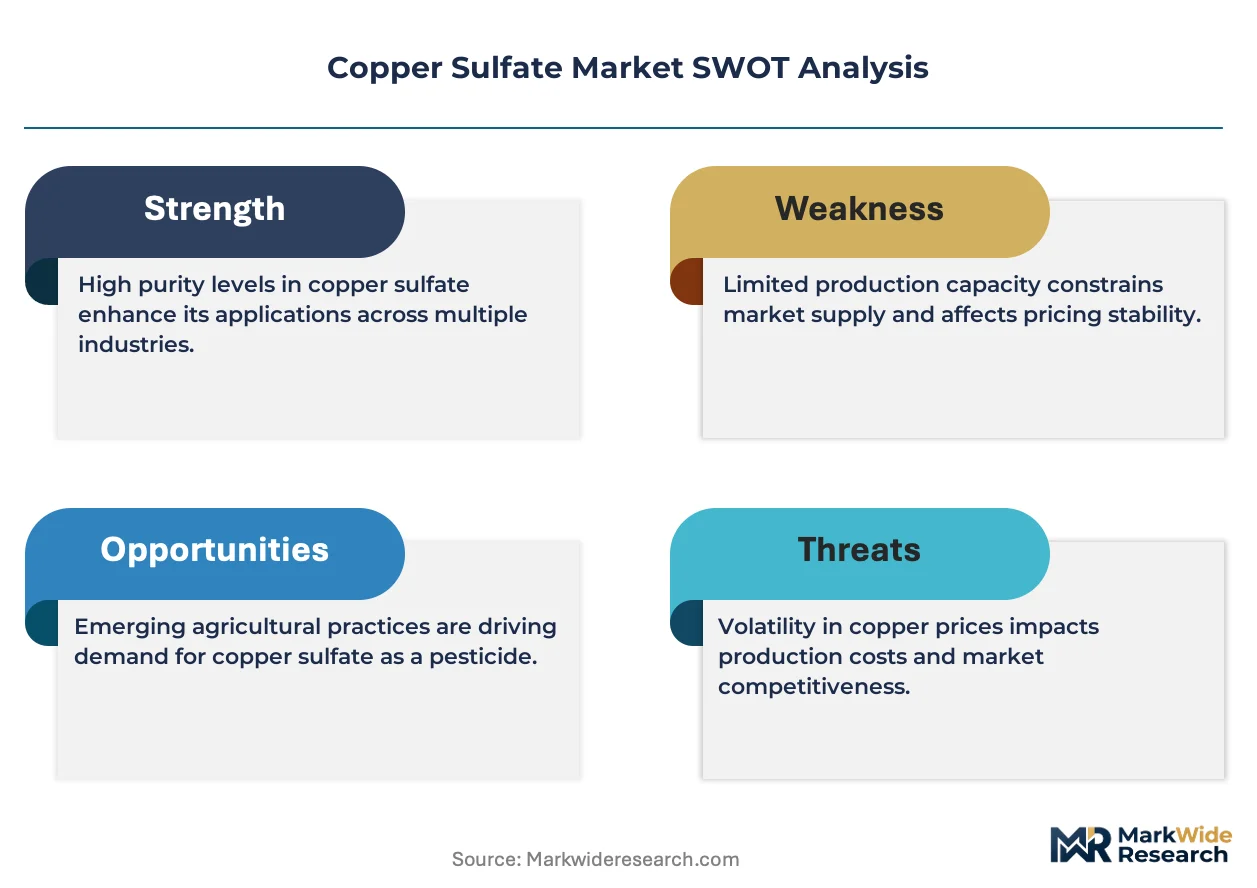
- Input cost volatility:Sulfuric acid pricing tracks energy markets, creating margin compression for crystallization-dependent producers without captive acid supply.
- Supply concentration risk:China controls approximately two-thirds of merchant copper sulfate capacity, exposing importers to export license and environmental enforcement variability.
- Substitution threat:Chelated copper alternatives and organic fungicides displace pentahydrate in high-value horticultural applications where phytotoxicity tolerance is low.
Strategic Opportunities
- Underpenetrated African markets:Fungicide demand in cocoa and coffee belts of Ghana and Côte d'Ivoire outpaces local formulation capacity, creating import substitution openings.
- Regulatory tailwind:China's MEE wastewater discharge mandates for heavy metals elevate demand for high-purity copper sulfate in electroplating effluent treatment.
- Technology convergence:Integration of copper sulfate dosing with automated irrigation systems creates precision agriculture service bundles beyond commodity chemical sales.
Industry Challenges
- Certification timeline compression:EPA FIFRA registration renewal cycles for agricultural formulations compress from 15 years to 7 years, elevating regulatory affairs overhead.
- Capex intensity for purity upgrades:Crystallizer and centrifuge investments required for electroplating-grade production exceed agricultural-grade equipment costs by multiples.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Sulfate Market |
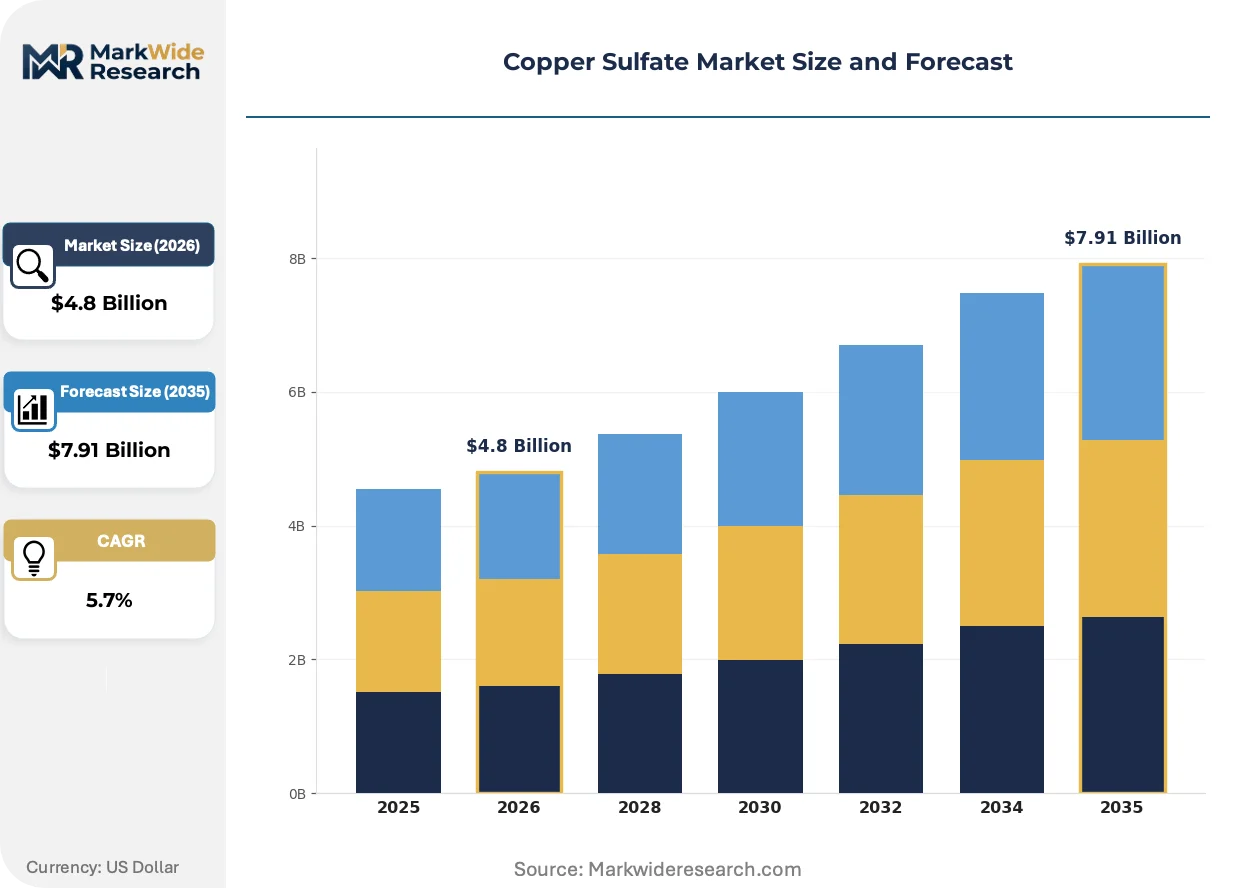
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystal, Liquid Application: Agriculture, Mining, Water Treatment, Chemical Manufacturing End User: Fertilizer Manufacturers, Mining Companies, Aquaculture, Laboratories Packaging Type: Bag, Drum, Sachet, Bulk |
| Companies Covered | Freeport-McMoRan Inc., Glencore plc, BASF SE, Aurubis AG, Southern Copper Corporation, Sumitomo Metal Mining Co., Ltd., Rio Tinto Group, Merck KGaA, JX Nippon Mining & Metals Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Sulfate Market Emerging Trajectories
Electrochemical process intensification and regulatory chemistry are redrawing competitive boundaries between commodity producers and formulated product specialists.
Membrane electrowinning recovery systems are fragmenting traditional copper scrap dissolution economics. Electroplaters in Germany and Japan adopt closed-loop regeneration to recover copper from spent etchant solutions, reducing virgin pentahydrate purchases by half in some facilities. This technology compresses addressable demand in mature industrial markets while creating equipment-service revenue pools for process licensors.
REACH Annex XV dossier restrictions on impurities are tightening specification bands for grades entering European aquaculture and drinking water treatment. The ECHA evaluation of nickel, cobalt, and arsenic thresholds forces reformulation investments among traders supplying Nordic and Alpine municipal utilities. Agricultural grade producers without multi-stage crystallization capability face exclusion from premium water treatment segments.
Buyer concentration among multinational fertilizer blenders is compressing procurement cycles and elevating contract volume commitments. Yara and Nutrien now negotiate annual offtake agreements with minimum 5,000-tonne volumes, displacing spot market purchases that historically sustained smaller regional producers. This pattern concentrates supplier relationships in Black Sea and Yangtze River corridor production clusters where scale economies align with blender logistics requirements.
Copper Sulfate Market Segmentation
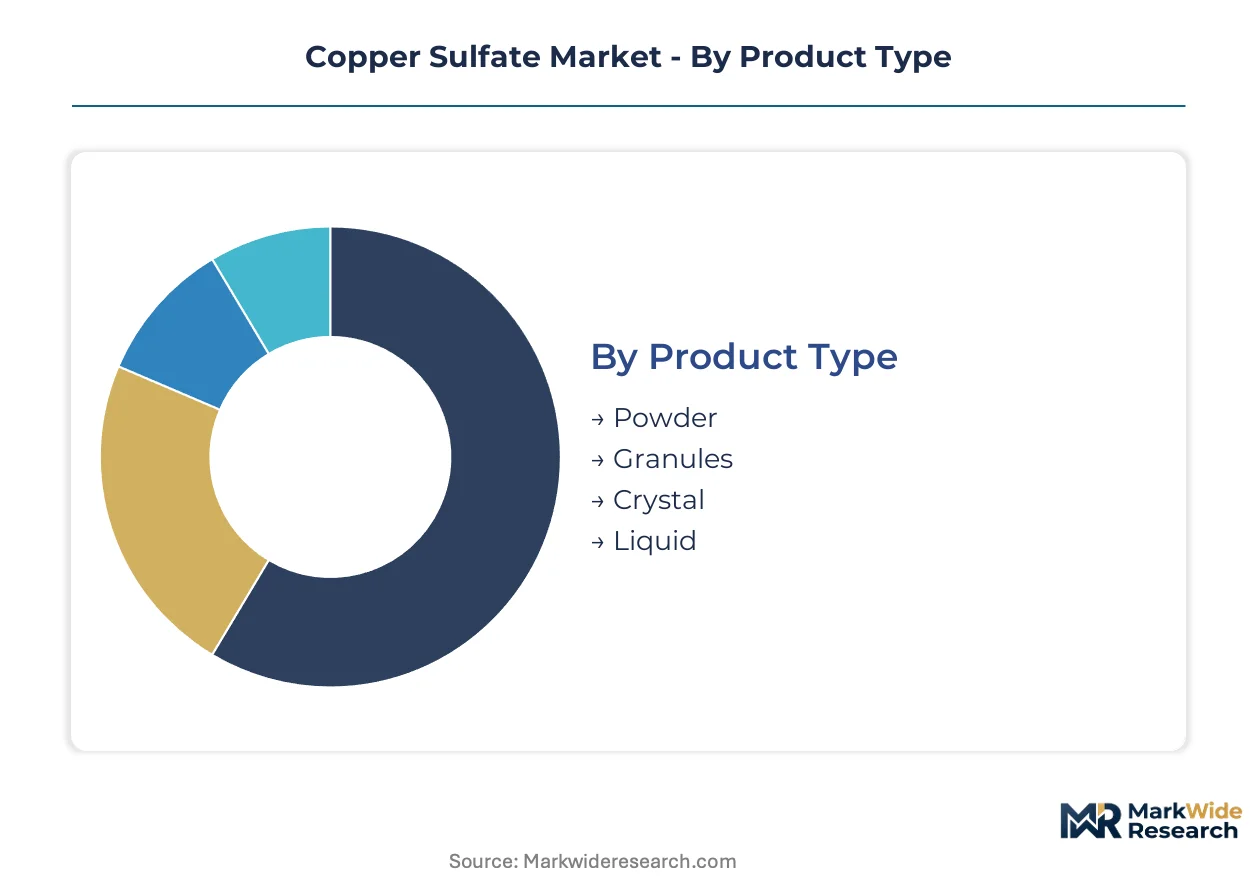
Copper sulfate procurement channels diverge sharply by physical form and purity specification, with agricultural distributors favoring bulk powder while electroplaters require sealed drum packaging for moisture-sensitive crystal grades. Understanding these flow patterns exposes margin concentration points and logistics bottlenecks across the value chain.
Product Type:
Powder and granule grades dominate commodity agricultural channels, while crystal and liquid formulations command premium placement through specialty chemical distributors.
- Powder:Fine-ground pentahydrate with 25% minimum copper content serves high-volume fungicide blending operations. Fertilizer manufacturers in Brazil and India pull containerized powder volumes through port-adjacent warehouses for phosphate fortification campaigns.
- Granules:Dense, low-dust particles between 2-4mm diameter enable mechanized spreading equipment compatibility. Australian and Argentinian broadacre wheat producers specify granule grades to minimize drift during aerial application.
- Crystal:Large pentahydrate crystals exceeding 5mm meet electroplating bath dissolution rate requirements. German and Japanese printed circuit board fabricators source drum-packed crystal through certified chemical distributors under REACH substance evaluation protocols.
- Liquid:Pre-dissolved aqueous solutions at 15-20% copper concentration eliminate crystallization handling for automated irrigation integration. California and Israeli precision agriculture operators specify liquid for fertigation system compatibility.
By volume, powder leads agricultural procurement. By growth pace, liquid is expanding most quickly through precision agriculture adoption.
Application:
Margin structures vary threefold across applications, with mining flotation chemistry capturing value from ore grade decline while agricultural volumes face price compression from buyer consolidation.
- Agriculture:Fungicidal sprays and micronutrient fertilizers consume the majority of pentahydrate output. Vineyard operators in France and Chile apply copper sulfate for downy mildew control under EU Sustainable Use Directive and national residue limits.
- Mining:Sulfide mineral flotation activator demand climbs as copper ore grades decline globally. Peruvian and Chilean concentrators increase copper sulfate consumption per tonne of recovered metal to maintain recovery rates from porphyry deposits.
- Water Treatment:Algal bloom suppression and heavy metal precipitation anchor municipal utility offtake. Great Lakes region utilities in the United States deploy copper sulfate under EPA NPDES permits for invasive species management.
- Chemical Manufacturing:Feedstock for copper-based pigments, catalysts, and battery materials. Chinese cathode active material producers consume high-purity grades for lithium-ion precursor synthesis.
Agriculture commands the largest share of volume. Mining chemical applications gain share fastest through ore quality deterioration.
End User:
Procurement sophistication separates multinational fertilizer blenders negotiating annual tonnage commitments from spot-buying aquaculture operators.
- Fertilizer Manufacturers:Yara and Nutrien negotiate 5,000-tonne minimum annual contracts with crystallization-integrated producers in the Yangtze River corridor and Black Sea region.
- Mining Companies:Integrated copper producers with captive smelters source internally; independent concentrators in Zambia and Kazakhstan rely on merchant traders.
- Aquaculture:Norwegian and Scottish salmon farmers specify ultra-low arsenic grades under ECHA evaluation thresholds for net antifouling treatments.
- Laboratories:Analytical reagent grades at 99%+ purity serve academic and industrial R&D through specialty chemical channels.
Fertilizer manufacturers dominate tonnage. Aquaculture specifications are tightening fastest under regulatory chemistry pressures.
Packaging Type:
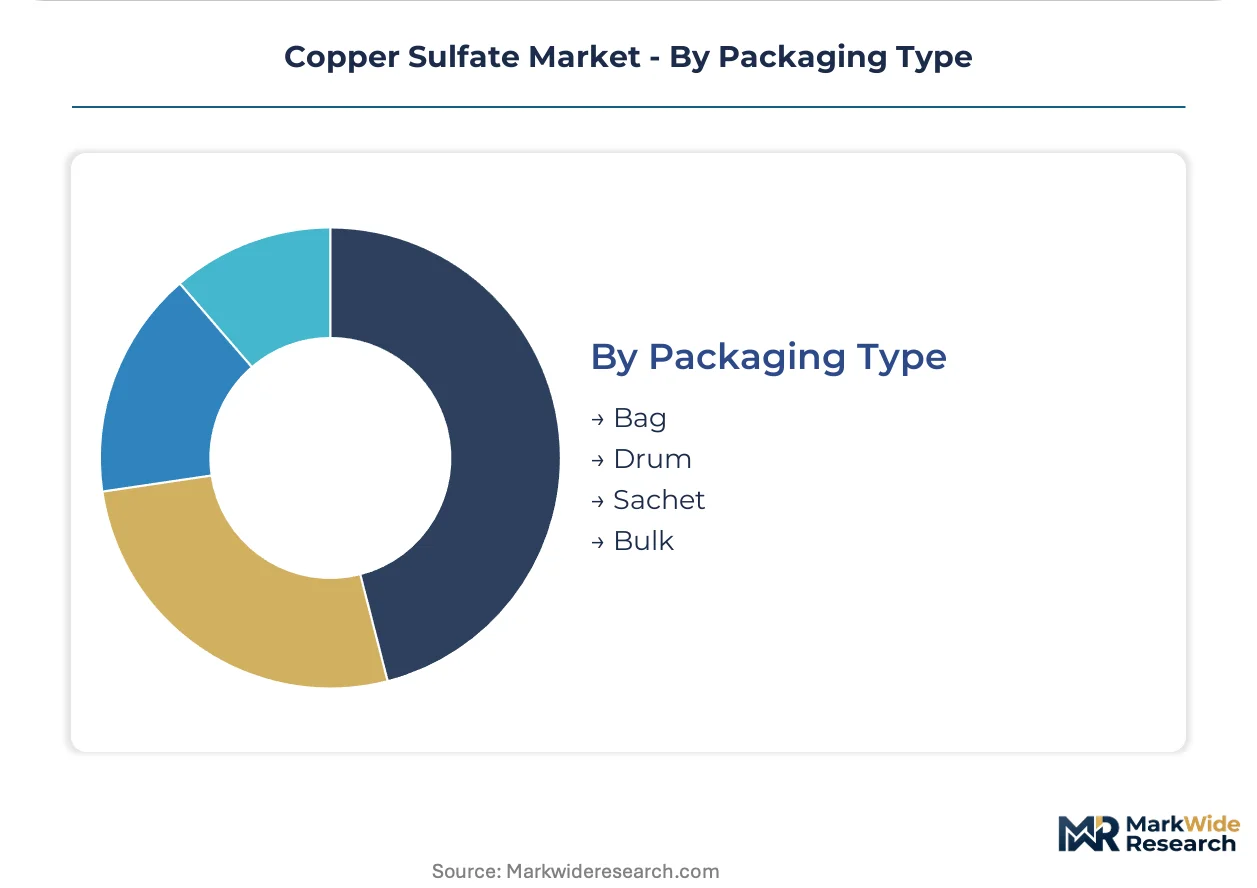
Packaging selection tracks handling automation levels and moisture sensitivity, with bulk gaining ground in integrated supply chains.
- Bag:25-50kg woven polypropylene sacks serve smallholder agricultural markets and regional distributors in West African cocoa belts.
- Drum:Sealed steel or plastic containers protect hygroscopic crystal grades for electroplating and laboratory end users.
- Sachet:Pre-measured water-soluble packets target hobby viticulture and ornamental horticulture retail channels.
- Bulk:Tanker and hopper truck delivery eliminates packaging costs for integrated fertilizer blenders with pneumatic handling systems.
Bag packaging leads in shipment count. Bulk delivery is climbing fastest as blender consolidation concentrates purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances reshape copper sulfate procurement patterns across consuming regions. China maintains surplus capacity serving Asian fertilizer blenders and electroplaters. European REACH compliance costs elevate import substitution incentives for Black Sea producers.
China
Yangtze River corridor smelters supply domestic fertilizer manufacturers and electroplating clusters with captive acid regeneration economics. MEE wastewater discharge mandates for heavy metals elevate demand for high-purity grades in Jiangsu and Zhejiang effluent treatment facilities. Guangdong printed circuit board fabricators source drum-packed crystal through certified distributors under tightening impurity thresholds.
United States
Great Lakes municipal utilities deploy copper sulfate under EPA NPDES permits for invasive species management in drinking water reservoirs. FIFRA registration renewal cycles compressing from 15 years to 7 years elevate regulatory affairs overhead for agricultural formulation suppliers. Arizona and New Mexico copper concentrators increase flotation reagent consumption as ore grades decline across Southwest porphyry deposits.
Germany
REACH Annex XV dossier restrictions on nickel, cobalt, and arsenic thresholds force reformulation investments among traders supplying Nordic municipal utilities. Membrane electrowinning recovery systems in Bavarian and North Rhine-Westphalia electroplating facilities reduce virgin pentahydrate purchases through closed-loop regeneration. BASF formulated blends incorporating copper sulfate into crop protection portfolios dominate agricultural distribution through Rhine-Ruhr logistics corridors.
Brazil
Phosphate fertilizer blending requirements in Minas Gerais and São Paulo pull containerized powder volumes through Santos port-adjacent warehouses for micronutrient fortification campaigns. ANVISA agrochemical registration timelines create working capital intensity for importers navigating seasonal demand peaks. Cerrado soybean producers specify granule grades for mechanized spreading compatibility during fungicide application windows.
India
Fertilizer manufacturers in Gujarat and Maharashtra negotiate annual offtake agreements with crystallization-integrated producers for phosphate fortification campaigns. BIS purity specifications for agricultural grades create compliance barriers for spot-market traders. Telangana and Karnataka vineyard operators apply copper sulfate for downy mildew control under state residue limit enforcement.
Copper Sulfate Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The vendor base stratifies between integrated mining-chemical conglomerates with captive concentrate access and merchant producers dependent on scrap feedstock spot markets. Three archetypes dominate: smelter-integrated majors crystallizing downstream salts, formulated product specialists bundling copper sulfate into crop protection portfolios, and regional traders serving aquaculture and water treatment niches. Capacity expansion in Yangtze River corridor clusters and backward integration into acid regeneration infrastructure represent the dominant competitive moves.
Among integrated mining-chemical conglomerates, Freeport-McMoRan Inc. and Glencore plc exemplify the smelter-to-salt archetype leveraging captive concentrate access. BASF SE occupies a position within the formulated product specialist tier, bundling copper sulfate into broader agricultural chemical portfolios. These three entities anchor competitive dynamics across agricultural and industrial grade segments.
| Leading Market Players |
|---|
| Freeport-McMoRan Inc. |
| Glencore plc |
| BASF SE |
| Aurubis AG |
| Southern Copper Corporation |
| Sumitomo Metal Mining Co., Ltd. |
| Rio Tinto Group |
| Merck KGaA |
| JX Nippon Mining & Metals Corp. |
| Others |
Supply Flow & Price Mechanics
Acid regeneration scale economies in Yangtze River corridor smelters compress unit costs below merchant producers dependent on spot sulfuric acid purchases, concentrating supply relationships among crystallization-integrated operators and establishing price floors that scrap-dependent competitors cannot match.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across electroplating and fertilizer blending segments. Price differentiation separates REACH-certified aquaculture grades from standard agricultural powder through multi-stage crystallization overhead and heavy metal testing protocols. Cost compression in agricultural grades is intensifying because Yara and Nutrien procurement consolidation extracts volume discounts from 5,000-tonne annual commitments. Fertilizer manufacturers exhibit highest price sensitivity due to commodity phosphate pricing exposure, while aquaculture operators accept premiums for ultra-low arsenic certification under ECHA evaluation thresholds.
Supply Chain Analysis
China, Russia, and India anchor merchant copper sulfate crystallization capacity serving global agricultural and industrial demand. Feedstock supply draws from copper concentrate spot markets, sulfuric acid regeneration economics, and scrap dissolution operations. Single-source vulnerability concentrates in Yangtze River corridor clusters where environmental enforcement variability threatens export license continuity. Distribution runs through port-adjacent warehouses at Santos and Mumbai for fertilizer blender consolidation, with drum-packed crystal flowing through certified chemical distributors to German and Japanese electroplating facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper sulfate procurement is reshaping around REACH compliance timelines and precision agriculture integration, with regulatory chemistry and automated dosing convergence creating differentiation openings beyond commodity crystallization scale.
For Market Incumbents: Compound captive concentrate access through backward integration into acid regeneration infrastructure across Yangtze River and Black Sea production clusters. Accelerate multi-stage crystallizer investments to defend REACH-certified aquaculture segments against traders lacking impurity control capability. Lock annual offtake agreements with Yara and Nutrien before procurement consolidation excludes mid-scale competitors from contract eligibility.
For New Entrants and Emerging Players: ECHA fast-track certification for ultra-low arsenic grades opens premium placement in Norwegian and Scottish salmon farming net antifouling applications. Target underpenetrated cocoa and coffee belts in Ghana and Côte d'Ivoire where fungicide demand outpaces local formulation capacity. Pursue liquid copper sulfate aqueous solutions for California and Israeli precision agriculture fertigation system integration as a service-bundle entry point.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulated product specialists bundling copper sulfate into crop protection portfolios with annual subscription-like blending contracts. Five-to-ten-year viability favors smelter-integrated operators with captive acid economics over scrap-dependent merchant producers exposed to sulfuric acid volatility. Monitor EPA FIFRA registration renewal cycle compression as a signal for regulatory affairs overhead escalation that will strain smaller agricultural formulation suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Regeneration | Yangtze River smelters achieve unit cost parity through captive sulfuric acid supply. |
| REACH Annex XV Compliance Investment | Multi-stage crystallization capability secures Nordic municipal utility water treatment placement. |
| Long-term Supply Agreement with Fertilizer Blenders | 5,000-tonne annual commitments with Yara and Nutrien displace spot market dependence. |
| Precision Agriculture Service Bundling | Liquid formulation integration with automated irrigation creates recurring revenue beyond commodity sales. |
| Joint Venture in Underpenetrated African Markets | Import substitution openings in Ghana and Côte d'Ivoire cocoa belts bypass Chinese supply concentration. |
Methodological Framework
Desk research of customs trade data, ACC and Cefic chemical industry reports, and SEC 10-K filings preceded structured interviews with copper smelter operations managers, fertilizer procurement leads at Yara and Nutrien, electroplating technical directors in Germany and Japan, and aquaculture certification officers in Norway. Primary fieldwork with distributors across Rhine-Ruhr and Yangtze River logistics corridors validated secondary volume estimates. Bottom-up crystallization capacity modeling and top-down end-use consumption triangulation anchored market size construction.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub segmentation dimensions informed projection mechanics. CAGRs were derived through regression analysis of historical volume trajectories against copper ore grade decline curves and fertilizer micronutrient fortification adoption rates. Mining flotation chemistry expansion and REACH substance evaluation timeline acceleration served as industry-specific forecast sensitivity inputs across the modeling period.
Decision-makers should treat outputs as directional under base assumptions of continued Chinese smelter capacity dominance and stable sulfuric acid pricing; material deviation in environmental enforcement stringency or phosphate fertilizer demand would warrant model refresh. Recalibration cycles align with material shifts in EPA FIFRA registration timelines and ECHA heavy metal threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
South America Carbon Black Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Isobutene Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Global Sodium Percarbonate Market