
 Ferric Sulphate and Polyferric Sulphate Market | 2026-2036
Ferric Sulphate and Polyferric Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Ferric Sulphate and Polyferric Sulphate Market Analysis
China is rewriting capacity dynamics in the Ferric Sulphate and Polyferric Sulphate Market through aggressive domestic chemical manufacturing expansion. Kemira Oyj leverages its Nordic R&D base to sustain premium liquid formulation output for European municipal clients. Hunan Yide Chemical anchors regional supply chains with integrated ferric salt production serving central Chinese industrial corridors. BASF SE competes through specialized high-purity grades targeting pharmaceutical and electronics water treatment segments.
Ferric sulphate and polyferric sulphate comprise iron-based coagulants synthesized through controlled oxidation of ferrous precursors, with polyferric variants containing hydroxyl-bridged polymerized iron species that enhance flocculation efficiency at lower dosages than conventional ferric salts. These compounds function primarily as coagulating and flocculating agents in water and wastewater treatment, removing suspended solids, phosphorus, and heavy metals through charge neutralization and sweep coagulation mechanisms. Liquid formulations dominate municipal procurement channels due to handling convenience and dosing precision, while powder grades retain structural importance in remote industrial sites lacking bulk liquid infrastructure. Water treatment applications command the deepest margin pools as regulatory tightening on phosphorus discharge escalates coagulant intensity per treatment volume.
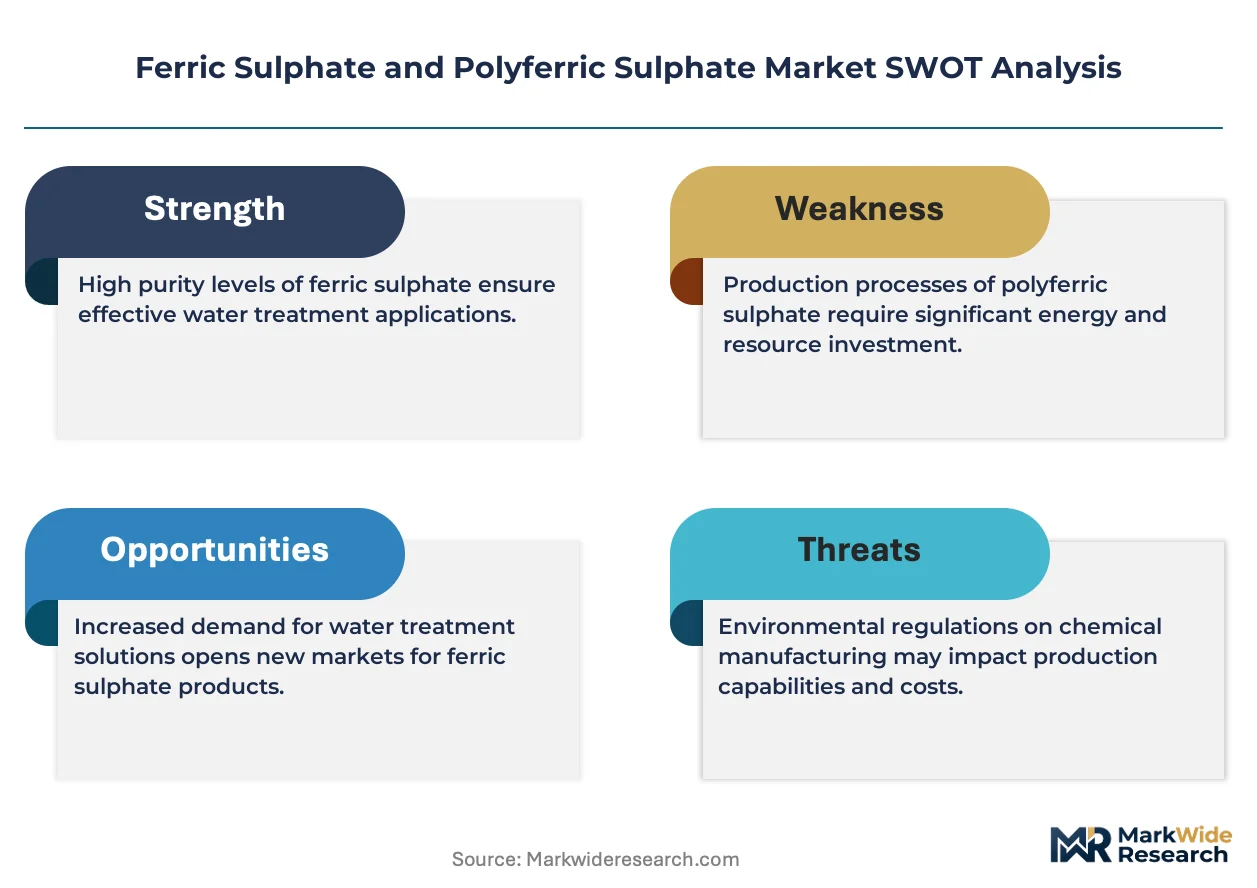
EPA drinking water standards and the EU Water Framework Directive shape product purity thresholds and application protocols across North American and European markets, while China's MEE enforces progressively stricter wastewater discharge limits that directly expand ferric coagulant consumption. ISO 9001 and NSF/ANSI 60 certifications function as gatekeeping requirements for supplier qualification in municipal tender processes, filtering out non-compliant regional producers. Stakeholders must monitor evolving polymerization technology patents and regional carbon-accounting rules that could restructure manufacturing cost advantages between ferric sulphate and emerging bio-based alternatives.
Market Dynamics
China's MEE enforcement of stricter wastewater discharge limits is compressing coagulant selection cycles and forcing municipal utilities to double ferric salt dosages for phosphorus removal. This regulatory compression is restructuring procurement volumes and supplier qualification requirements across industrial water treatment.
Growth Catalysts
- EU Water Framework Directive:Phosphorus discharge caps across German and French municipal systems are mandating higher coagulant intensity per treated volume.
- Polymerization technology:Hydroxyl-bridged iron species in polyferric formulations achieve equivalent flocculation at 30-40% lower dosage than conventional ferric sulphate.
- Southeast Asian industrial zones:Indonesian and Vietnamese electronics manufacturers are displacing aluminium-based coagulants with iron-based alternatives to meet export-market purity standards.
Market Restraints
- Sulphuric acid cost volatility:Ferric sulphate production remains exposed to sulphuric acid feedstock price swings tied to smelter output and fertilizer demand cycles.
- China supply concentration:Hunan and Shandong provinces host over 60% of global polyferric sulphate capacity, creating single-geography disruption risk.
- Aluminium chlorohydrate substitution:Mature alum-based coagulants retain cost advantages in legacy municipal systems with lower phosphorus removal requirements.
Strategic Opportunities
- India's Ganga rejuvenation program:Central government funding for sewage treatment infrastructure is opening municipal procurement channels for imported ferric coagulants.
- High-purity electronics-grade formulations:Semiconductor fabs in Taiwan and South Korea require ultra-low heavy-metal ferric salts for process water treatment.
- Carbon-accounting rules:EU CBAM and emerging Scope 3 disclosure requirements favor regional European producers with verifiable low-carbon sulphuric acid sourcing.
Industry Challenges
- NSF/ANSI 60 certification timelines:New entrants face 12-18 month approval cycles for municipal drinking water applications in North American markets.
- Liquid formulation logistics:Bulk liquid ferric sulphate requires specialized tanker fleets and storage infrastructure that constrains remote site delivery economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferric Sulphate and Polyferric Sulphate Market |
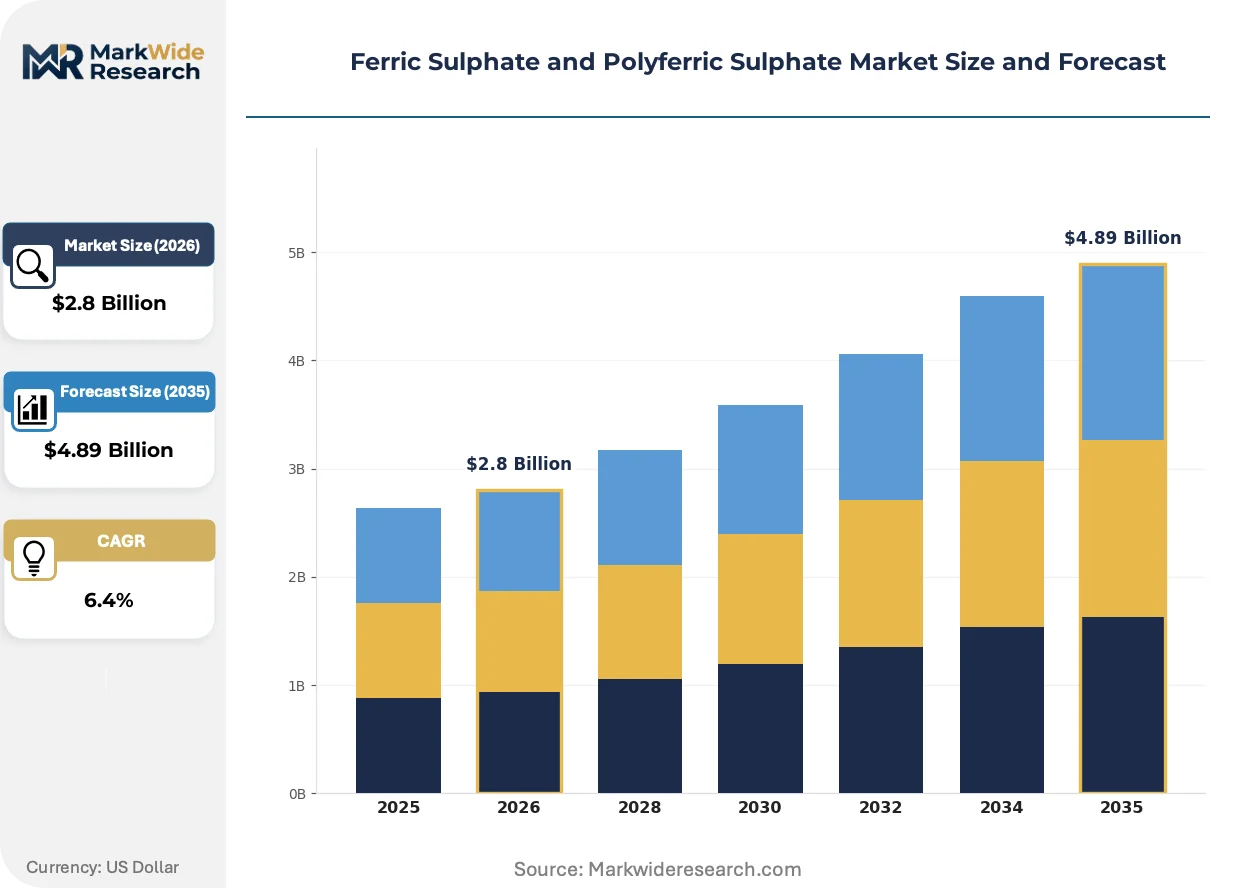
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Solution Application: Water Treatment, Wastewater Treatment, Oil & Gas, Pulp & Paper End User: Municipalities, Industrial Plants, Construction, Agriculture Distribution Channel: Direct Sales, Distributors, Retail, Online Sales |
| Companies Covered | Kemira Oyj, BASF SE, Chemtrade Logistics Inc., Pencco Inc., AkzoNobel N.V., Hunan Yide Chemical Co., Ltd., Airedale Chemical, Chemifloc Limited, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferric Sulphate and Polyferric Sulphate Market Emerging Trajectories
Digital dosing control systems and real-time turbidity feedback loops are compressing coagulant consumption variability and enabling precision chemistry management across distributed treatment networks.
Membrane bioreactor integration is virtualizing ferric coagulant deployment in advanced wastewater treatment plants. European municipal operators in the Netherlands and Denmark are adopting predictive dosing algorithms that synchronize ferric salt injection with membrane fouling cycles. This convergence is virtualizing the traditional batch-based coagulation model into continuous, sensor-driven processes that minimize chemical overfeed.
REACH authorization requirements for aluminium-based coagulants are redirecting formulation R&D toward iron-based alternatives in EU member states. The European Chemicals Agency's scrutiny of polyaluminium chloride ecotoxicity profiles is accelerating ferric sulphate qualification in French and German potable water systems. Municipal tenders in Bavaria and Rhône-Alpes now specify iron-based chemistry for new plant construction.
Specification consolidation among large water utilities is compressing supplier diversity and favoring multi-year framework agreements. Thames Water and Suez have consolidated coagulant procurement into single-source liquid ferric contracts with embedded volume flexibility clauses. This concentration is most visible in UK and French municipal sectors where privatized operators seek supply security through captive tank farm investments at treatment sites.
Ferric Sulphate and Polyferric Sulphate Market Segmentation
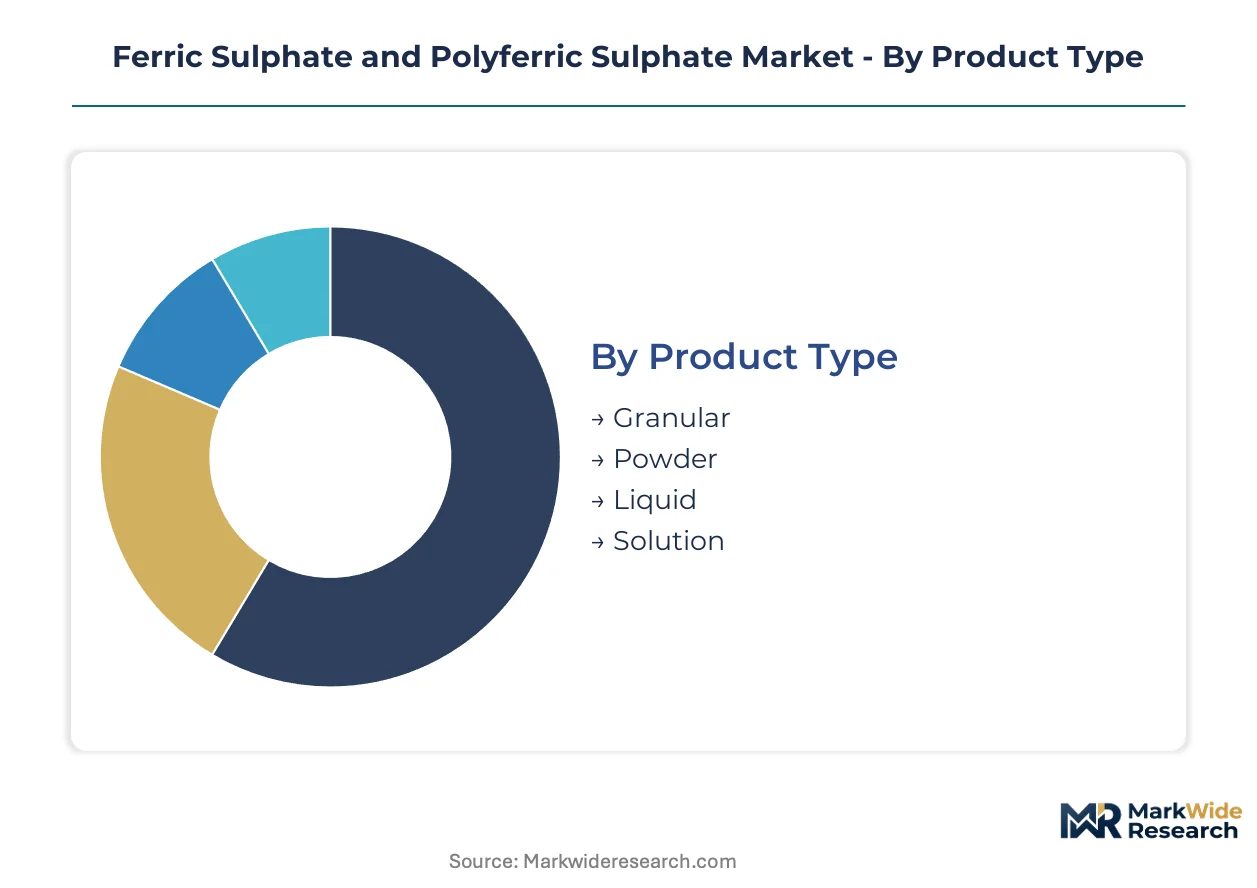
Segmentation in ferric sulphate and polyferric sulphate markets reveals divergent procurement rhythms. Municipal utilities operate on multi-year framework agreements with predictable volume cycles, while industrial end-users face compressed replenishment schedules tied to production batch timing and discharge compliance deadlines.
Product Type:
Liquid formulations turn inventory fastest through continuous municipal dosing systems, while powder grades sit longer in remote industrial stockpiles lacking bulk handling infrastructure.
- Liquid:Pump-ready formulations dominate municipal procurement channels where automated dosing systems demand consistent viscosity and iron content. Chinese utilities along the Yangtze corridor specify liquid ferric sulphate for phosphorus removal under MEE discharge mandates. Tank farm investments at treatment plants lock in supplier relationships through embedded infrastructure.
- Solution:Pre-diluted polyferric sulphate solutions reduce on-site handling complexity for smaller treatment facilities lacking chemical preparation capacity. Electronics manufacturers in Taiwan's Hsinchu Science Park specify ultra-low heavy-metal solution grades for process water treatment. Ready-to-feed formats compress commissioning timelines for new semiconductor fabs.
- Powder:Solid ferric sulphate serves remote mining operations and construction dewatering sites without liquid bulk logistics.
- Granular:Free-flowing granules suit agricultural runoff treatment and small-scale pond management applications.
Liquid dominates installed base. Solution is where expansion concentrates.
Application:
Water treatment commands premium pricing through certification requirements, while oil and gas applications tolerate broader specification ranges at lower margins.
- Water Treatment:Potable water coagulation demands NSF/ANSI 60 certified ferric salts with strict arsenic and heavy-metal thresholds. German municipal operators under the EU Water Framework Directive specify polyferric sulphate for enhanced phosphorus removal. Certification timelines of 12-18 months filter out non-compliant regional suppliers.
- Wastewater Treatment:Industrial discharge compliance drives ferric salt consumption for phosphorus and suspended solids reduction. French agro-food processors in Brittany deploy polyferric formulations to meet regional basin authority discharge caps. Seasonal production cycles create demand spikes during harvest processing windows.
- Oil & Gas:Produced water treatment utilizes ferric sulphate for solids separation before reinjection or surface discharge.
- Pulp & Paper:Bleach effluent treatment and color removal applications favor iron-based coagulants over aluminium alternatives for fiber quality preservation.
Wastewater treatment dominates installed base. Water treatment is where expansion concentrates.
End User:
Municipal procurement cycles stretch 24-36 months through tender processes, while industrial plants operate on quarterly or monthly replenishment schedules.
- Municipalities:Public water utilities consolidate coagulant procurement into multi-year framework agreements with volume flexibility clauses. Privatized operators in England and France invest in captive tank storage to secure supply continuity. Phosphorus discharge tightening across EU member states escalates coagulant intensity per treated volume.
- Industrial Plants:Manufacturing facilities face compressed selection cycles driven by batch process timing and variable effluent loads. Indonesian electronics manufacturers displace aluminium-based coagulants with iron-based alternatives to meet export-market purity standards. On-site storage constraints favor just-in-time liquid delivery.
- Construction:Dewatering and sediment control applications demand rapid-response powder or granular supply.
- Agriculture:Runoff treatment and pond management represent fragmented, price-sensitive demand.
Municipalities dominate installed base. Industrial plants is where expansion concentrates.
Distribution Channel:
Direct sales capture value through technical service attachment, while distributor networks extend geographic reach at margin compression.
- Direct Sales:Bulk liquid contracts with embedded technical support dominate municipal and large industrial accounts. Kemira and BASF maintain dedicated sales engineering teams for European water utility clients. Direct relationships enable real-time dosing optimization and inventory management.
- Distributors:Regional chemical distributors serve fragmented industrial and agricultural demand outside major metropolitan corridors. Southeast Asian industrial zones rely on distributor networks for localized inventory positioning. Distributor markups of 15-25% compress supplier margins while expanding addressable market.
- Retail:Small-package sales through agricultural supply stores serve hobbyist pond treatment and minor construction applications.
- Online Sales:E-commerce channels capture specification-grade powder and granular demand from remote facilities with predictable consumption patterns.
Direct sales dominate installed base. Distributors is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over sixty percent of polyferric sulphate capacity clusters in Hunan and Shandong provinces, concentrating feedstock access and sulfuric acid integration advantages in eastern China. This geographic compression shapes procurement logistics and supplier qualification protocols across municipal and industrial channels worldwide.
China
Yangtze River Delta municipalities are expanding ferric coagulant procurement under MEE discharge mandates for phosphorus removal. The Ministry of Ecology and Environment enforces progressively stricter wastewater standards that double coagulant intensity per treated volume. Shanghai and Jiangsu water utilities specify liquid polyferric sulphate for automated dosing systems at riverbank treatment plants.
Germany
Bavarian and North Rhine-Westphalian utilities specify iron-based coagulants for new plant construction under EU Water Framework Directive phosphorus caps. The European Chemicals Agency's REACH scrutiny of aluminium-based alternatives accelerates ferric sulphate qualification in potable water systems. Rhine basin municipal operators deploy polyferric formulations to meet regional discharge limits.
United States
Mid-Atlantic and Great Lakes municipal utilities face EPA drinking water standards that filter suppliers through NSF/ANSI 60 certification requirements. Twelve-to-eighteen month approval cycles constrain new entrant participation in municipal tenders. Ohio and Pennsylvania water authorities consolidate procurement into multi-year framework agreements with volume flexibility clauses.
India
Central government funding for sewage treatment infrastructure under the Ganga rejuvenation program opens municipal procurement channels for ferric coagulants. State pollution control boards enforce industrial discharge limits that expand coagulant consumption in chemical and textile corridors. Uttar Pradesh and Bihar utilities are tendering for bulk liquid ferric sulphate delivery systems.
Indonesia
Electronics manufacturers in Batam and Jakarta industrial zones displace aluminium-based coagulants with iron-based alternatives to meet export-market purity standards. The country's national environmental regulator tightens effluent standards for semiconductor and textile processors. Java-based industrial parks specify polyferric sulphate for phosphorus removal in combined wastewater streams.
Ferric Sulphate and Polyferric Sulphate Market Vendor Landscape
Integrated chemical conglomerates and specialized water treatment chemical producers split the market between scale-driven commodity supply and technical service-intensive municipal relationships. The vendor base organizes around three archetypes: diversified multinational chemical groups with sulfuric acid backward integration, regional ferric salt specialists with captive iron ore or scrap processing, and water-focused chemical service providers with dosing equipment attachment. Competitive dynamics center on multi-year framework agreement capture and certification barrier maintenance rather than price competition.
Among Nordic-European chemical service providers, Kemira Oyj exemplifies the technical-intensive archetype through premium liquid formulation output and dedicated municipal sales engineering. German diversified chemical conglomerate BASF SE occupies a position in high-purity specialty grades targeting pharmaceutical and electronics water treatment segments. Chinese regional specialist Hunan Yide Chemical Co., Ltd. anchors central China supply chains through integrated ferric salt production serving industrial corridors along the Yangtze River basin.
| Leading Market Players |
|---|
| Kemira Oyj |
| BASF SE |
| Chemtrade Logistics Inc. |
| Pencco Inc. |
| AkzoNobel N.V. |
| Hunan Yide Chemical Co., Ltd. |
| Airedale Chemical |
| Chemifloc Limited |
| Lonza Group |
| Others |
Supply Flow & Price Mechanics
Hunan and Shandong provinces concentrate over sixty percent of global polyferric sulphate capacity, creating asymmetric pricing power for integrated producers serving municipal utilities under tightening phosphorus discharge mandates. This geographic compression elevates sulfuric acid feedstock access and iron ore proximity into decisive cost differentiators that ripple through contract negotiations across European and Asian procurement channels.
Pricing Analysis
EPA drinking water standards and the EU Water Framework Directive dictate the pricing tier structure across municipal procurement channels. Three-tier pricing stratifies across NSF/ANSI 60 certified premium grades for potable water, industrial-standard formulations for wastewater, and economy powder grades for remote construction sites. Cost compression in economy tiers intensifies because aluminum chlorohydrate substitutes retain legacy system advantages. Industrial electronics manufacturers exhibit lowest price sensitivity due to ultra-low heavy-metal specifications, while agricultural runoff treatment represents the most price-elastic demand segment.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from integrated Chinese producers are restructuring working capital requirements for Southeast Asian distributor networks. Manufacturing draws from sulfuric acid, ferrous scrap, and iron ore feedstocks concentrated in China, Germany, and the United States. Single-geography concentration risk in Hunan-Shandong corridor creates vulnerability to regional environmental enforcement actions or energy rationing. Distribution runs through direct bulk liquid contracts with municipal utilities, regional chemical distributors for fragmented industrial demand, and specialized tanker fleets for automated dosing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital dosing platform interoperability is transforming ferric coagulant procurement from commodity spot purchasing into integrated water-treatment-as-a-service ecosystems, compressing supplier margins while embedding incumbents through predictive algorithm partnerships.
For Market Incumbents: Build certification moats through accelerated NSF/ANSI 60 and ISO 9001 investment cycles that extend approval timelines for emerging competitors. Deepen backward integration into captive sulfuric acid production to neutralize feedstock volatility from smelter output cycles. Expand technical service attachment through real-time turbidity feedback system deployment, creating switching costs for municipal utilities consolidating procurement under multi-year framework agreements. For New Entrants and Emerging Players: India's Ganga rejuvenation program tenders represent the most penetrable municipal procurement channel for imported ferric coagulants, with central government funding bypassing incumbent supplier relationships. Taiwan and South Korean semiconductor fabs offer electronics-grade formulation entry points through ultra-low heavy-metal specifications that filter out commodity producers. Pursue joint-venture structures with regional distributors possessing existing tank farm infrastructure to circumvent capital-intensive logistics requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors water-focused chemical service providers with dosing equipment attachment and predictive algorithm capabilities over commodity ferric salt producers. Long-term viability hinges on polymerization technology patent portfolios and carbon-accounting transparency for EU CBAM compliance. Watch for MEE enforcement acceleration in China as the inflection signal indicating coagulant intensity expansion and import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive feedstock supply neutralizes smelter output volatility and fertilizer demand cycles. |
| Polymerization Technology Patent Investment | Hydroxyl-bridged iron species formulations command dosage efficiency premiums in municipal tenders. |
| Digital Dosing Platform Partnership | Predictive algorithm integration embeds suppliers through real-time turbidity feedback loops. |
| NSF/ANSI 60 Certification Acceleration | Twelve-to-eighteen month approval timelines filter regional competitors from North American municipal channels. |
| Carbon-Accounting Transparency Program | Verifiable low-carbon sulfuric acid sourcing qualifies European producers for EU CBAM advantage. |
Methodological Framework
A standing panel of municipal water utility procurement managers, industrial wastewater treatment plant operators, chemical distributor channel partners, and ferric salt R&D directors provided ongoing calibration across primary fieldwork and secondary validation. Data synthesis combined customs and trade flow records, MEE discharge enforcement bulletins, SEC filings from listed chemical conglomerates, and EU Water Framework Directive implementation reports. Bottom-up volume modeling from individual facility procurement and top-down capacity analysis from production cluster surveys were triangulated for convergence.
Scenario-bracketing around regulatory enforcement intensity and polymerization technology diffusion shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product formulation type, application end-use, purity certification tier, and regional production hub clustering. CAGRs were derived from installed base expansion rates and coagulant intensity per treated volume under tightening phosphorus caps. Forecast inputs incorporated MEE mandate implementation timelines and semiconductor fab construction pipelines for electronics-grade demand.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated Chinese producers or accelerated bio-based coagulant commercialization would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
Trona Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Global Ammonium Sulphate Market