
 Bromacil Market | 2026-2036
Bromacil Market Size, Share, and Industry Trends Forecast 2026-2036
Bromacil Market Analysis
Technical-grade bromacil formulations is redrawing procurement standards across specialty crop protection. Corteva Agriscience leverages its distribution network to dominate North American channels for residual herbicides. Syngenta Group anchors its portfolio through integrated seed-and-chemistry bundling in tropical agriculture. FMC Corporation differentiates via manufacturing scale in emulsifiable concentrate production.
Bromacil is a substituted uracil herbicide with the chemical formula 5-bromo-3-sec-butyl-6-methyluracil, functioning as a photosystem II inhibitor absorbed through plant roots for pre-emergent and post-emergent weed control in non-crop and selective crop settings. Liquid concentrates command the largest volume share due to ease of tank-mixing and calibrated application in industrial weed control programs, while soluble powders are gaining traction among greenhouse operators seeking precision dosing with reduced drift potential. Turf management applications generate premium pricing compared to commodity weed control segments.
EPA re-registration review under the Federal Insecticide, Fungicide, and Rodenticide Act shapes product label restrictions and buffer zone requirements for bromacil applications near water bodies. State-level departments of agriculture in Florida and California impose additional groundwater monitoring protocols that filter which formulation types reach end users. Stakeholders must track regulatory comment periods and state 24(c) special local need registrations to anticipate where formulation flexibility will expand or contract.
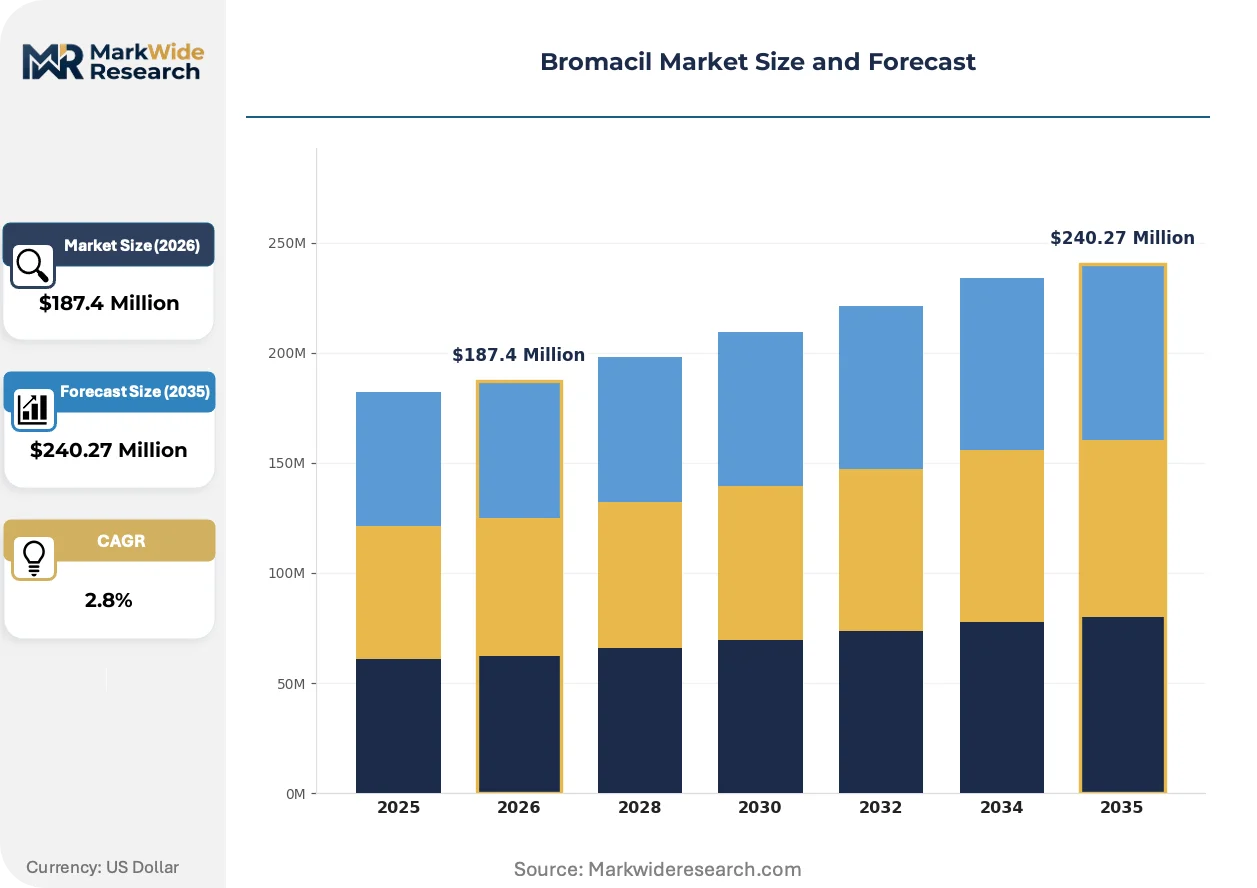
Market Dynamics
EPA re-registration protocols under FIFRA are compressing formulation flexibility while specialty crop acreage in Florida and Hawaii pulls residual herbicide demand upward, creating procurement pressure on technical-grade specifications.
Growth Catalysts
- Pineapple cultivation expansion:Hawaiian and Central American growers are extending residual weed control programs to manage grassy competition in ratoon fields, tightening specifications for root-absorbed chemistries.
- Citrus grove renovation cycles:Florida's replanting programs following HLB disease losses require extended bare-ground management, favoring photosystem II inhibitors with soil persistence.
- Industrial vegetation management:Railway and utility corridors in the US Southeast are formalizing scheduled treatment programs that specify uracil-based herbicides for hard-to-control perennials.
Market Restraints
- Active ingredient concentration limits:EPA label amendments are restricting maximum application rates near vulnerable soils, compressing per-acre revenue potential for standard formulations.
- Groundwater monitoring mandates:California's Department of Pesticide Regulation imposes well-sampling requirements that disqualify certain emulsifiable concentrates from coastal watershed applications.
- Biological herbicide alternatives:Bio-based weed control products derived from microbial metabolites are capturing maintenance contracts in organic-certified buffer zones.
Strategic Opportunities
- Precision application equipment:Drone-mounted variable-rate sprayers in Florida citrus operations enable spot-treatment protocols that reduce total chemistry load while maintaining efficacy.
- Greenhouse and nursery channels:Controlled-environment agriculture facilities in the Netherlands and Spain are adopting soluble powder formulations for substrate drench applications.
- IR-4 minor use program:USDA-supported residue studies are opening specialty crop registrations for vegetables and herbs previously excluded from bromacil labels.
Industry Challenges
- Formulation chemist scarcity:Expertise in uracil stability and adjuvant compatibility is concentrating among retiring specialists at legacy manufacturers, constraining new product development pipelines.
- Tank-mix certification complexity:State-level compatibility testing requirements for bromacil-fungicide combinations are extending product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bromacil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $240.27 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid Concentrates, Soluble Powders, Emulsifiable Concentrates Application: Weed Control, Soil Treatment, Crop Protection, Turf Management End User: Agricultural Producers, Turf Managers, Greenhouse Operators, Landscape Professionals Distribution Channel: Online Retail, Agricultural Supply Stores, Distributors, Direct Sales |
| Companies Covered | Corteva Agriscience, Syngenta Group, FMC Corporation, Adama Agricultural Solutions, Bayer CropScience, UPL Limited, Nufarm Limited, AMVAC Chemical Corporation, Alligare LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bromacil Market Emerging Trajectories
Formulation chemistry and application precision are converging to reshape how residual herbicides reach end users, with digital agriculture tools compressing traditional distribution hierarchies.
Micro-encapsulated delivery systems are supplanting conventional emulsifiable concentrates in high-value crop segments. These polymer-shell formulations release active ingredients through moisture-triggered degradation, enabling citrus growers in Florida to reduce leaching losses by half. The technology is compressing reapplication frequencies while extending residual control windows in sandy soils.
REACH authorization requirements for persistent organic pollutants are tightening purity specifications for technical-grade imports entering EU formulation facilities. ECHA's substance evaluation process is flagging trace impurity profiles that previously passed border inspections, forcing suppliers to invest in recrystallization capacity or exit the European market entirely. German and Dutch distributors are consolidating procurement around qualified manufacturers with certified impurity documentation.
Direct-to-grower digital platforms are fragmenting traditional agrochemical distribution in North American specialty crops. Florida citrus cooperatives and Hawaiian pineapple associations are pooling orders through proprietary procurement portals, bypassing regional distributor markups. The shift is most visible in volume contracting for pre-season herbicide programs, where grower-controlled buying committees now negotiate formulation specifications directly with manufacturers.
Bromacil Market Segmentation
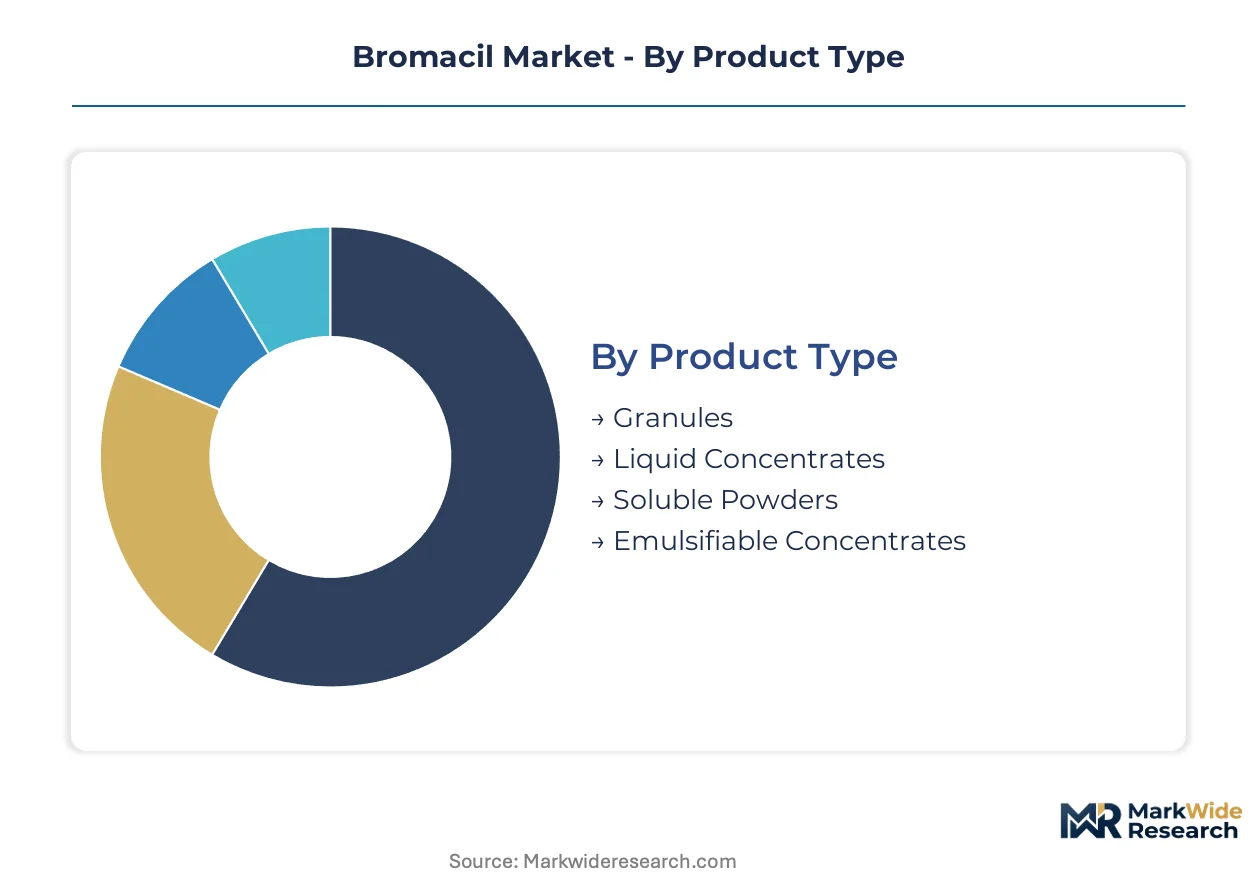
Bromacil procurement patterns fragment across formulation physics, application protocols, and channel economics. Understanding where margin pools concentrate within each dimension reveals how manufacturers prioritize technical-grade investments and which customer segments command premium positioning.
Product Type:
Liquid concentrates and micro-encapsulated variants capture the deepest margin pools, while commodity granules compete on manufacturing scale.
- Liquid Concentrates:Emulsifiable and solution formulations dominate volume through ease of tank-mixing and calibrated metering in citrus grove operations. Florida's sandy soils favor root-absorbed delivery systems that integrate with existing spray infrastructure.
- Granules:Dry broadcast applications serve railway and utility corridor contracts requiring extended residual control without drift concerns. Formulation costs concentrate in binder systems that regulate dissolution rates.
- Soluble Powders:Precision dosing capabilities attract greenhouse operators in the Netherlands and Spain seeking substrate drench applications with reduced environmental loading.
- Emulsifiable Concentrates:Standard oil-in-water systems anchor industrial vegetation management programs where equipment compatibility drives specification adherence.
Liquid concentrates hold installed capacity. Soluble powders are rotating up the share rankings.
Application:
Turf management commands price premiums per treated acre, while soil treatment volumes scale through repeat-application contracts.
- Crop Protection:Citrus and pineapple operations in Florida and Hawaii specify residual photosystem II inhibitors for bare-ground management during replanting cycles. EPA label restrictions on maximum application rates compress per-acre chemistry loads.
- Turf Management:Golf course and sports field maintenance programs generate premium pricing through performance guarantees and aesthetic outcome requirements. Formulation purity specifications exceed commodity weed control tiers.
- Weed Control:Industrial vegetation management along transportation corridors favors cost-efficient broadcast applications with extended control windows.
- Soil Treatment:Pre-plant incorporated applications in specialty crop systems require precise depth placement to optimize root uptake while minimizing leaching.
Turf management maintains pricing power. Crop protection is gaining volume fastest through replanting programs.
End User:
Agricultural producers drive formulation specification standards, while greenhouse operators represent the steepest expansion trajectory for precision delivery systems.
- Agricultural Producers:Citrus cooperatives in Florida and pineapple associations in Hawaii pool procurement through direct-to-manufacturer contracting, bypassing traditional distributor markups. Volume commitments shape technical-grade purity requirements.
- Greenhouse Operators:Controlled-environment agriculture facilities prioritize soluble powder formulations for substrate drench precision and worker safety profiles.
- Turf Managers:Municipal and private golf course superintendents specify performance-based contracts with guaranteed control duration clauses.
- Landscape Professionals:Commercial maintenance contractors favor ready-to-use formulations that minimize mixing labor and equipment calibration demands.
Agricultural producers anchor volume demand. Greenhouse operators are climbing the fastest among end-user categories.
Distribution Channel:
Distributor networks retain leverage in formulation-technical support bundles, while direct sales channels capture margin through grower cooperative consolidation.
- Distributors:Regional agrochemical wholesalers provide tank-mix compatibility testing and application training that justifies markup retention in Florida and California markets.
- Direct Sales:Manufacturer-to-grower portals fragment traditional hierarchies as citrus cooperatives negotiate pre-season volume contracts with specification control.
- Agricultural Supply Stores:Independent retailers serve smaller-scale producers with break-bulk packaging and localized technical consultation.
- Online Retail:E-commerce platforms capture maintenance-grade and consumer-oriented formulations with standardized labeling and reduced regulatory complexity.
Distributors hold relationship infrastructure. Direct sales channels are expanding share through cooperative procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical-grade manufacturing clusters in the United States, China, and Germany supply formulation facilities across three continents. Regulatory divergence on groundwater monitoring and residue limits fragments procurement standards by destination market. Demand concentrates in citrus belts, pineapple zones, and industrial corridor maintenance programs.
United States
Florida citrus replanting after HLB disease drives bare-ground herbicide specifications, while Hawaiian pineapple ratoon fields extend residual control programs. EPA re-registration under FIFRA compresses maximum application rates near vulnerable soils. The Lake Wales Ridge citrus cluster and Central Oahu pineapple zone anchor North American volume demand.
Brazil
São Paulo state citrus expansion and Minas Gerais coffee renovation pull uracil-based chemistries into specialty crop protection. ANVISA residue limit harmonization with Codex standards filters which formulation types reach domestic growers. The Ribeirão Preto agricultural corridor concentrates procurement through cooperative buying pools.
China
Shandong Peninsula formulation plants export technical-grade material to Southeast Asian pineapple operations. MEE groundwater protection zones in the Yangtze Delta restrict emulsifiable concentrate applications near drinking water sources. The Nantong chemical cluster processes bromacil intermediates for export markets.
Spain
Valencia citrus cooperatives and Almería greenhouse complexes specify soluble powder formulations for precision substrate applications. ECHA REACH authorization flags impurity profiles in technical-grade imports, forcing recertification of legacy suppliers. The Murcia agricultural belt tests drone-mounted variable-rate sprayers for spot-treatment protocols.
Australia
Queensland pineapple growers and New South Wales citrus operations specify residual herbicides for ratoon field management. APVMA label amendments restrict buffer zones near Great Barrier Reef catchments, compressing per-acre application windows. The Sunshine Coast processing corridor consolidates procurement through grower-owned distribution cooperatives.
Bromacil Market Vendor Landscape
Concentration sits with diversified agrichemical conglomerates that anchor residual herbicide portfolios through integrated seed-and-chemistry bundling. Three archetypes dominate: global crop protection majors with manufacturing scale, regional specialists with formulation flexibility, and generic producers with cost-positioned technical-grade supply. Competitive moves center on direct-to-grower portal development and micro-encapsulation technology licensing.
Among the diversified majors, Corteva Agriscience, Syngenta Group, and FMC Corporation exemplify scale-driven positioning across North American specialty crop channels. Corteva leverages distribution infrastructure for citrus and pineapple procurement consolidation. Syngenta anchors tropical agriculture through bundled input programs. FMC differentiates via emulsifiable concentrate manufacturing capacity. Each occupies a distinct tier in formulation-technical support bundling.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Syngenta Group |
| FMC Corporation |
| Adama Agricultural Solutions |
| Bayer CropScience |
| UPL Limited |
| Nufarm Limited |
| AMVAC Chemical Corporation |
| Alligare LLC |
| Others |
Supply Flow & Price Mechanics
EPA re-registration protocols under FIFRA gate both supplier qualification and price differentiation simultaneously, compressing formulation flexibility while concentrating procurement around certified technical-grade manufacturers. Technical-grade purity specifications and state-level groundwater monitoring mandates fragment pricing tiers across qualified and legacy suppliers.
Pricing Analysis
EPA label amendments dictate the pricing tier structure across micro-encapsulated premium formulations, standard emulsifiable concentrates, and commodity granules. Price differentiation rests on certification grade for groundwater compliance and volume scale in cooperative procurement pools. Cost compression in standard concentrates is intensifying because California well-sampling requirements disqualify certain formulations from coastal watersheds. Agricultural cooperatives in Florida exhibit highest price sensitivity through pooled direct contracting, while turf management programs show lowest sensitivity due to performance guarantee requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites technical-grade shipment security for Southeast Asian pineapple operations. Manufacturing concentrates in the United States, China, and Germany, with Shandong Peninsula formulation plants processing intermediates for export markets. Raw material dependencies encompass bromine derivatives, sec-butylamine, and methyl isocyanate precursors. Single-source vulnerability concentrates in legacy uracil stability expertise among retiring formulation chemists. Distribution runs through regional agrochemical wholesalers providing tank-mix compatibility testing and direct-to-grower portals fragmenting traditional hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against bio-based herbicide alternatives capturing organic-certified buffer zone contracts. Biological weed control products derived from microbial metabolites threaten maintenance contract retention in premium turf segments.
For Market Incumbents: Secure formulation chemist expertise through targeted retention programs and technical knowledge capture systems before specialist retirement waves constrain development pipelines. Deepen backward integration into technical-grade manufacturing to control impurity certification documentation required by ECHA REACH authorization. Anchor distributor relationships through bundled tank-mix compatibility testing services that justify markup retention against direct-to-grower portal erosion.
For New Entrants and Emerging Players: Differentiate on precision application equipment integration, targeting Florida citrus cooperatives adopting drone-mounted variable-rate sprayers for spot-treatment protocols. Penetrate greenhouse operator channels in the Netherlands and Spain with soluble powder formulations for substrate drench applications. Pursue USDA IR-4 minor use program partnerships to open specialty crop registrations for vegetables and herbs previously excluded from established labels.
For Investors and Strategic Acquirers: EPA re-registration timeline reshapes the acquisition landscape, favoring targets with certified impurity documentation and state 24(c) special local need registration portfolios. Long-term viability hinges on micro-encapsulation technology licensing positions and direct-to-grower portal infrastructure. Watch ECHA substance evaluation flagging patterns as the inflection indicator for European market access compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Encapsulation Technology Licensing | Enables moisture-triggered release systems that halve leaching losses in Florida sandy soils. |
| Direct-to-Grower Portal Development | Bypasses regional distributor markups through cooperative procurement consolidation in citrus belts. |
| IR-4 Minor Use Program Partnership | Opens residue study pathways for vegetable and herb registrations previously excluded from labels. |
| Formulation Chemist Retention Program | Captures uracil stability expertise before specialist retirement constrains product development pipelines. |
| Groundwater Compliance Certification Investment | Qualifies emulsifiable concentrates for California coastal watershed applications under DPR mandates. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with formulation chemists, citrus cooperative procurement managers, greenhouse technical directors, and state regulatory affairs specialists; and secondary validation through EPA docket filings, state 24(c) registration databases, customs trade records, and SEC 10-K agrichemical segment disclosures. Bottom-up volume modeling triangulated against top-down market sizing across technical-grade manufacturing clusters.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning formulation physics, application protocol, end-user archetype, and regional regulatory cluster. CAGRs derived from trend extrapolation of replanting cycle intensity, acreage conversion rates, and label restriction trajectories. Industry-specific inputs incorporated HLB disease recovery patterns in Florida citrus and ratoon field management expansion in Hawaiian pineapple operations.
Material uncertainties — EPA re-registration outcome timing, ECHA impurity threshold adjustments, and biological herbicide substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions on cooperative procurement consolidation velocity and precision equipment adoption curves. Practitioners should keep alternative scenarios live as state groundwater monitoring mandate expansion and REACH authorization scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Global Internal Olefins Market