
 Global Bleach Wipes Market | 2026-2036
Global Bleach Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bleach Wipes Market Foresight
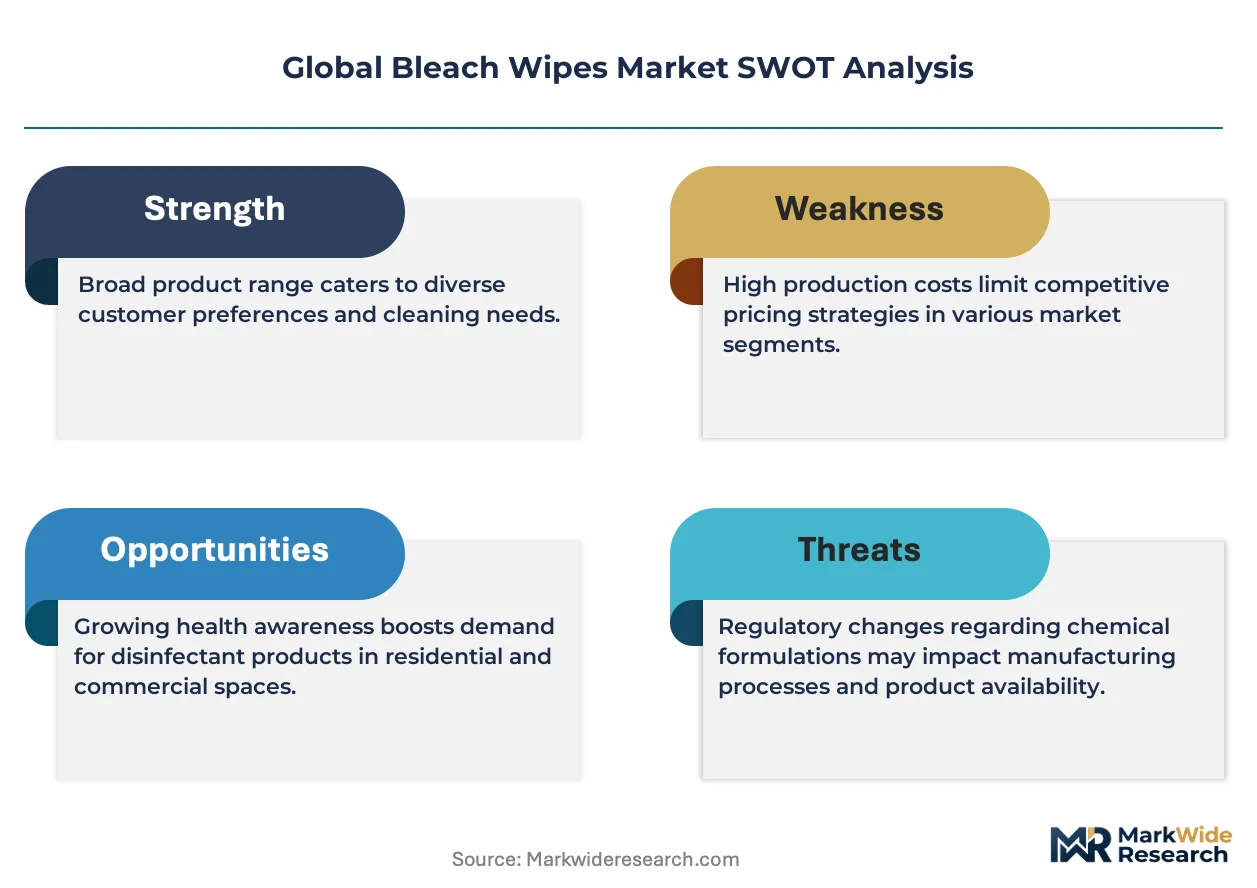
Quaternary ammonium compounds is recalibrating product economics across the bleach wipes category as formulators balance efficacy claims against material compatibility concerns. The Clorox Company leverages its EPA master label portfolio to sustain institutional channel dominance. Reckitt Benckiser Group plc anchors European healthcare procurement through differentiated Lysol Professional formulations. Seventh Generation Inc. competes in the plant-derived segment with sodium hypochlorite alternatives that target LEED-certified facility managers.
Bleach wipes are nonwoven substrates impregnated with sodium hypochlorite solutions typically ranging from 0.5% to 5.25% concentration, designed for one-step disinfection of hard nonporous surfaces in clinical and commercial environments. The manufacturing process involves controlled saturation of spunlace or meltblown fabrics with stabilized bleach solutions to preserve active chlorine content through shelf life. Disposable Wipes command the largest volume position due to infection control protocols that mandate single-use protocols in hospitals and laboratories. Surface Disinfection generates the deepest margin pools as healthcare facilities prioritize EPA-registered hospital-grade claims over commodity household positioning.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act govern product claims and label language, while OSHA bloodborne pathogen standards mandate disinfectant availability in occupational settings. The EU Biocidal Products Regulation and REACH compliance frameworks restrict active ingredient concentrations and labeling formats across European markets. Stakeholders must monitor evolving pathogen-specific efficacy testing protocols and emerging state-level chemical disclosure laws that threaten to fragment compliance requirements across jurisdictions.
Market Dynamics
EPA's emerging viral pathogen guidance is compressing formulation timelines while forcing manufacturers toward dual-registered product portfolios that satisfy both hospital-grade and emerging pathogen claims simultaneously. This regulatory pressure is restructuring competitive economics across the bleach wipes category.
Growth Catalysts
- Healthcare-associated infection protocols:Acute care facilities in the United States are mandating single-use surface disinfection protocols under CDC guidelines, institutionalizing bleach wipe procurement at the facility level rather than departmental purchasing.
- OSHA bloodborne pathogen standards:Occupational safety mandates require disinfectant availability in clinical laboratories and emergency response settings, creating baseline demand that survives budget compression cycles.
- Spunlace nonwoven substrate advances:Improved fabric saturation control is extending active chlorine stability, reducing spoilage rates and enabling extended distribution reach into secondary markets.
Market Restraints
- Sodium hypochlorite feedstock volatility:Chlor-alkali production concentration on the US Gulf Coast exposes formulators to hurricane-related supply disruptions and caustic soda price spikes.
- Material compatibility limitations:Bleach chemistries degrade stainless steel instrument surfaces and discolor fabrics, restricting application scope in surgical suites and textile-heavy environments.
- EU Biocidal Products Regulation:REACH compliance and active substance review timelines are delaying product launches across European markets by 18-36 months versus US registration pathways.
Strategic Opportunities
- Long-term care expansion:Skilled nursing facilities in Germany and Japan are adopting hospital-grade disinfection protocols previously reserved for acute care, opening premium positioning for EPA-registered formulations.
- LEED-certified facility procurement:Plant-derived sodium hypochlorite alternatives are penetrating commercial real estate management contracts where sustainability scoring influences vendor selection.
- E-commerce institutional channels:Group purchasing organizations are consolidating procurement through digital platforms, enabling direct manufacturer relationships that bypass traditional distribution markups.
Industry Challenges
- EPA master label acquisition timelines:New entrants face 12-24 month registration delays for hospital-grade claims, concentrating market access among established registrants with existing label portfolios.
- Active chlorine stability engineering:Formulation chemists with stabilized bleach expertise command premium compensation, constraining R&D expansion at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bleach Wipes Market |
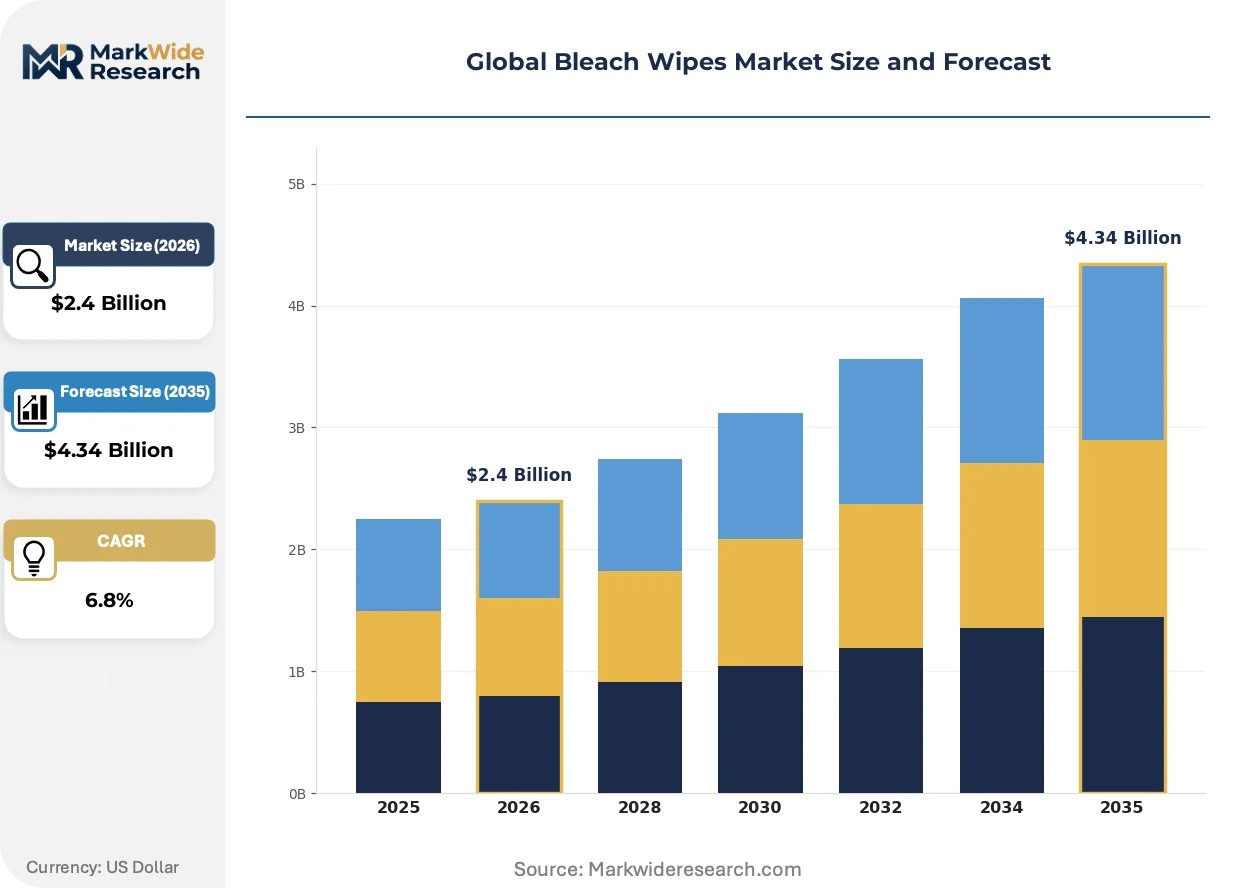
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Wipes, Reusable Cloths, Pre-Moistened Towelettes, Foaming Wipes, Gel-Based Wipes Application: Surface Disinfection, Equipment Sterilization, Food Safety, Household Cleaning, Laboratory Maintenance End User: Hospitals, Laboratories, Food Processing, Hospitality, Janitorial Services Packaging Type: Canisters, Sachets, Refill Packs, Flow Packs, Buckets |
| Companies Covered | The Clorox Company, Reckitt Benckiser Group plc, Procter & Gamble Company, Kimberly-Clark Corporation, Essendant Receivables LLC, Seventh Generation Inc., AngeliniPharma Inc., Metrex Research LLC, Dreumex USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bleach Wipes Market Shifts & Advancements
Reformulation investments are accelerating across the bleach wipes category as manufacturers balance efficacy expansion against substrate compatibility and shelf-life extension requirements. Three distinct vectors are reshaping product development priorities.
Controlled-release bleach encapsulation is modularizing how active chlorine deploys across surface contact times. Surgical suite operators in tertiary hospitals are adopting these formulations to reduce corrosion on carbon steel instruments while maintaining sporicidal claims. The technology is compressing the trade-off between material safety and pathogen kill spectrum that previously segmented product lines.
REACH authorization requirements are restricting quaternary ammonium compound concentrations in European healthcare formulations. Manufacturers serving EU markets are reformulating toward sodium hypochlorite bases to maintain disinfectant claims under tightened biocidal product frameworks. German hospital procurement associations are negotiating multi-year supply agreements to secure compliant inventory ahead of 2025 review deadlines.
Consolidated sourcing through group purchasing organizations is compressing vendor rosters at US health systems. Regional distributors are losing shelf space to direct manufacturer contracts that bundle bleach wipes with broader infection control portfolios. This concentration is most visible in the Southeast, where hospital network mergers have reduced active supplier counts by half since 2020.
Global Bleach Wipes Market Segmentation
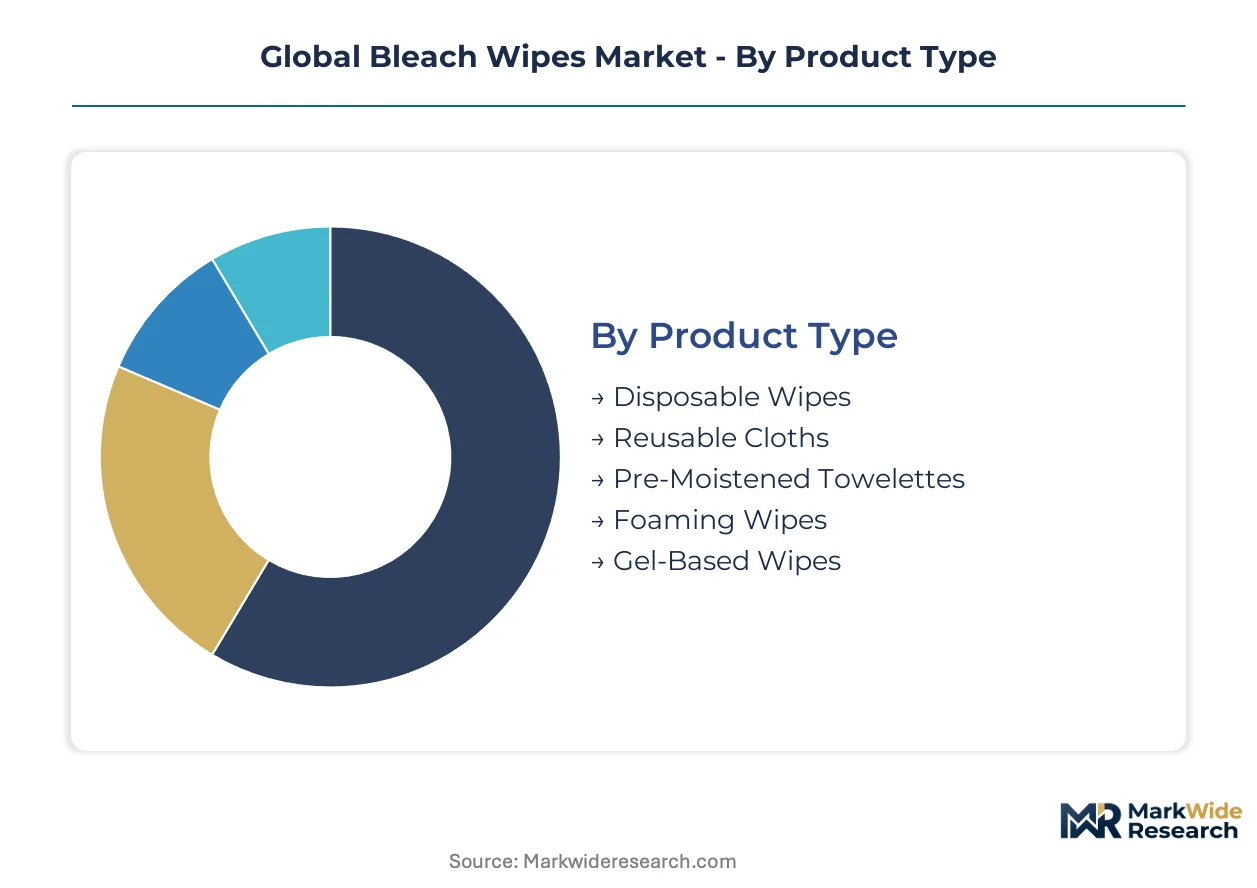
Bleach wipes manufacturers configure product portfolios across four distinct segmentation axes. Each dimension captures different buyer priorities, from infection control protocols to operational logistics.
Product Type:
Cost tier separates institutional buyers from consumer and commercial segments.
- Disposable Wipes:Single-use spunlace or meltblown substrates saturated with stabilized sodium hypochlorite solutions. Acute care facilities in the United States mandate these under CDC single-use protocols, creating the deepest procurement volumes.
- Reusable Cloths:Launderable fabrics with bleach-compatible synthetic blends designed for multiple decontamination cycles. Janitorial services in Germany and Japan adopt these to reduce waste disposal costs under tightening environmental regulations.
- Pre-Moistened Towelettes:Individually packaged wipes with extended shelf-life formulations for field deployment.
- Foaming Wipes:Substrates impregnated with bleach-based foaming agents for vertical surface adhesion.
- Gel-Based Wipes:Viscous bleach formulations for controlled application on irregular surfaces.
Disposable Wipes leads volumes today; Gel-Based Wipes is gaining share fastest.
Application:
Application scope determines regulatory registration requirements and margin structure.
- Surface Disinfection:Hard nonporous surface treatments requiring EPA hospital-grade or emerging viral pathogen claims. Healthcare facilities in the United States prioritize these formulations over commodity alternatives, generating premium positioning.
- Equipment Sterilization:Pre-operative instrument wiping protocols in surgical suites. Material compatibility constraints with stainless steel and carbon steel limit bleach concentration ranges in tertiary hospital adoption.
- Food Safety:FDA-compliant formulations for food contact surface sanitation.
- Household Cleaning:Consumer-grade efficacy claims with reduced active chlorine concentrations.
- Laboratory Maintenance:Biosafety cabinet and fume hood decontamination protocols.
Surface Disinfection captures the largest revenue pool; Food Safety is expanding most quickly.
End User:
Customer type dictates procurement channel and compliance framework.
- Hospitals:Acute care and long-term care facilities governed by Joint Commission standards and OSHA bloodborne pathogen requirements. Group purchasing organizations consolidate vendor rosters, favoring manufacturers with EPA master label portfolios.
- Laboratories:Clinical and research facilities requiring sporicidal claims for biosafety level containment. CDC select agent regulations mandate specific disinfection protocols for these operators.
- Food Processing:USDA-inspected facilities requiring FSIS-compliant sanitation procedures.
- Hospitality:Hotels and cruise operators balancing guest safety with surface material preservation.
- Janitorial Services:Contract cleaners serving commercial real estate with LEED certification requirements.
Hospitals dominate procurement volumes; Janitorial Services shows the steepest expansion trajectory.
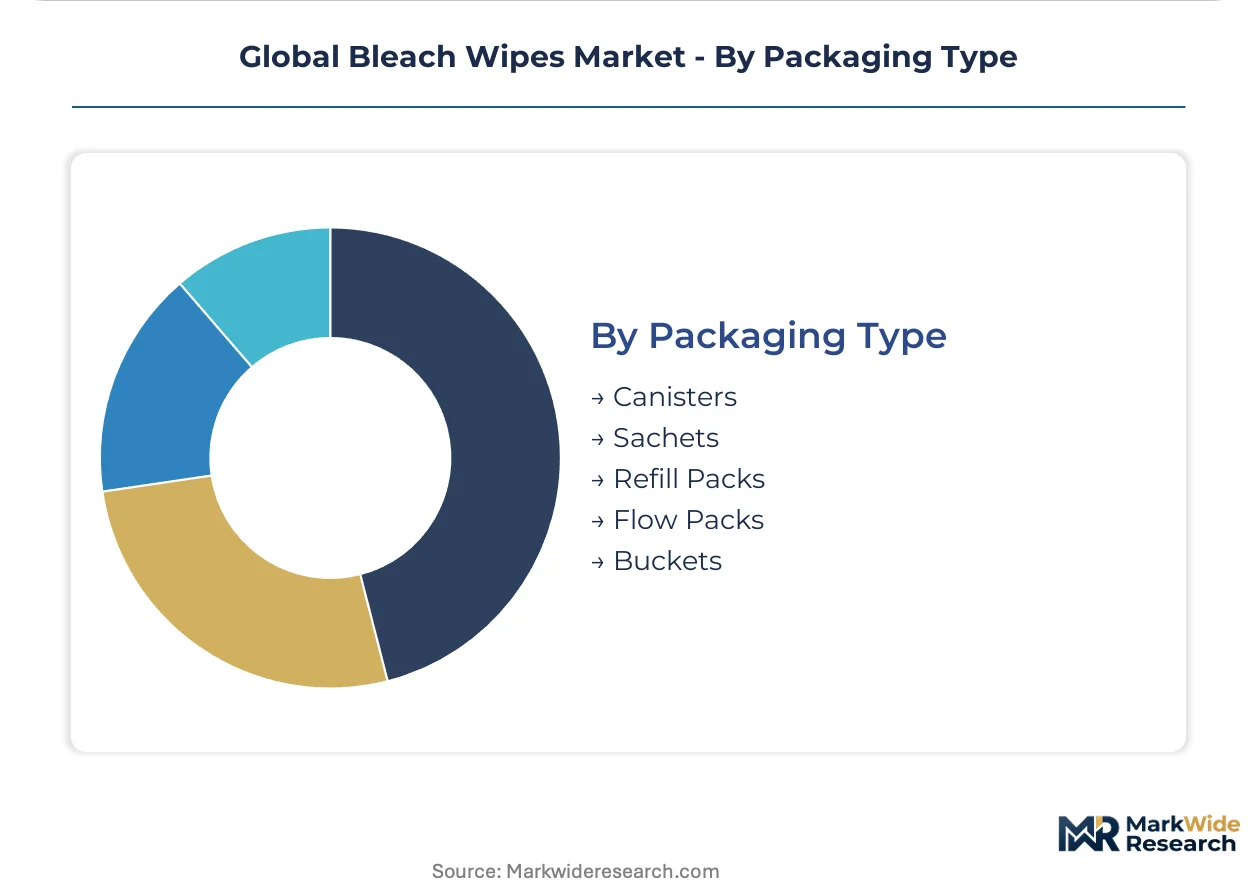
Packaging Type:
Packaging configuration shapes distribution economics and point-of-use convenience.
- Canisters:Rigid containers with pop-up dispensing and resealable lids for high-frequency use environments. Central supply departments in United States hospitals standardize on these for nursing unit distribution.
- Sachets:Single-unit foil or polymer pouches for field deployment and emergency response kits. OSHA requirements for portable disinfectant availability drive baseline demand across occupational settings.
- Refill Packs:Bulk flexible packaging for dispenser replenishment in high-volume facilities.
- Flow Packs:Continuous roll formats for automated dispensing systems.
- Buckets:Large-format rigid containers for industrial-scale applications.
Canisters lead unit volumes today; Sachets is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acute care facilities in the United States drive procurement volumes through CDC-mandated single-use protocols. Hospital networks in Germany and Japan are adopting equivalent disinfection standards. Manufacturing clusters in China and India supply substrate materials and active ingredient precursors to formulators worldwide.
United States
Joint Commission accreditation standards and OSHA bloodborne pathogen mandates institutionalize bleach wipe procurement across hospital systems. EPA master label portfolios determine vendor eligibility for group purchasing organization contracts. The Southeast hospital corridor from Atlanta to Tampa has consolidated supplier rosters by half since 2020 through network mergers.
Germany
REACH authorization timelines and EU Biocidal Products Regulation reviews are compressing formulation launch windows to 18-36 months. German hospital procurement associations negotiate multi-year supply agreements ahead of 2025 active substance deadlines. The Rhine-Ruhr industrial belt hosts concentrated nonwoven substrate manufacturing for European distribution.
Japan
Long-term care facilities are importing hospital-grade disinfection protocols previously restricted to acute care settings. METI guidelines on chemical safety in healthcare facilities shape product registration requirements. The Kansai region around Osaka anchors domestic manufacturing of stabilized bleach formulations for institutional buyers.
China
Chlor-alkali production on the Yangtze River Delta supplies sodium hypochlorite feedstock to regional formulators. GB standards for disinfectant efficacy testing diverge from EPA protocols, requiring parallel registration investments. The Pearl River Delta cluster exports spunlace nonwoven substrates to Southeast Asian wipe converters.
India
Central Drugs Standard Control Organization oversight of surface disinfectants is tightening labeling and efficacy documentation requirements. BIS certification for healthcare cleaning products is becoming mandatory for institutional procurement. Maharashtra's pharmaceutical manufacturing corridor generates concentrated demand from FDA-inspected contract research organizations.
Global Bleach Wipes Market Competitive Landscape
Global majors compete with regional champions across EPA registration portfolios and institutional distribution networks. Market access concentrates among established registrants with existing master label portfolios, while mid-tier manufacturers face 12-24 month approval delays for hospital-grade claims. Three archetypes dominate: legacy household brands with institutional extensions, pure-play healthcare disinfectant specialists, and private-label converters serving group purchasing organizations. Competitive dynamics center on M&A activity to acquire label portfolios and strategic partnerships with nonwoven substrate suppliers to secure material allocation.
Within the legacy brand tier, The Clorox Company and Reckitt Benckiser Group plc exemplify multinational positioning across consumer and institutional channels. Seventh Generation Inc. occupies a specialist position in plant-derived formulations targeting sustainability-scored procurement contracts. These three anchors demonstrate how regulatory registration assets and substrate sourcing relationships determine competitive mobility in concentrated buyer environments.
| Leading Market Players |
|---|
| The Clorox Company |
| Reckitt Benckiser Group plc |
| Procter & Gamble Company |
| Kimberly-Clark Corporation |
| Essendant Receivables LLC |
| Seventh Generation Inc. |
| AngeliniPharma Inc. |
| Metrex Research LLC |
| Dreumex USA Inc. |
| Others |
Supply & Pricing Matrix
Captive backward integration into chlor-alkali production anchors pricing power for the largest bleach wipes manufacturers, with US Gulf Coast producers controlling sodium hypochlorite feedstock economics that cascade through formulation costs and ultimately determine margin capture at the institutional buyer level.
Pricing Analysis
Input-cost pass-through from caustic soda and chlorine derivatives governs contract renegotiation cycles between formulators and group purchasing organizations. Three-tier pricing structure across EPA master label, hospital-grade registered, and commodity household tiers separates premium positioning from standard institutional procurement from economy private-label alternatives. Pricing pressure stems from GPO consolidation reducing vendor rosters by half in merged US hospital networks. Janitorial services exhibit highest price sensitivity due to LEED scoring constraints, while acute care facilities prioritize registration portfolio breadth over unit cost.
Supply Chain Analysis
EPA master label and EU BPR active substance qualification requirements gate supply chain participation, restricting viable formulators to established registrants with 12-24 month approval timelines. Manufacturing concentrates in the United States, Germany, and China, with the Yangtze River Delta supplying sodium hypochlorite precursors and the Rhine-Ruhr belt producing spunlace nonwoven substrates. Raw material dependencies span chlor-alkali outputs, spunlace fabrics, and stabilized bleach chemistry expertise. Single-source vulnerability concentrates in US Gulf Coast chlor-alkali corridors exposed to hurricane disruption. Distribution runs through group purchasing organization platforms consolidating direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where acute care procurement is shifting toward dual-registered formulations satisfying both hospital-grade and emerging viral pathogen claims simultaneously, rewarding manufacturers with existing EPA label portfolios.
For Market Incumbents: Anticipate margin compression from private-label converters by securing multi-year substrate allocation agreements with spunlace suppliers in Germany and the US Southeast. Prioritize capacity addition in the Rhine-Ruhr corridor ahead of EU BPR 2025 active substance deadlines. Defensive certification investment in emerging viral pathogen master labels preserves GPO contract eligibility against mid-tier challengers. For New Entrants and Emerging Players: Enter via plant-derived sodium hypochlorite alternatives targeting LEED-certified commercial real estate contracts where sustainability scoring overrides brand loyalty. Skilled nursing facilities in Germany and Japan represent the most penetrable institutional segment, importing acute care protocols previously restricted to hospitals. A direct e-commerce institutional channel bypassing traditional distribution markups offers viable go-to-market positioning. For Investors and Strategic Acquirers: Roll-up economics work for regional private-label converters with existing EPA registrations because GPO vendor consolidation is compressing supplier counts and creating captive demand for compliant manufacturing capacity. Five-to-ten year viability hinges on biocidal regulatory asset accumulation rather than brand equity. Watch EPA emerging viral pathogen guidance expansion as the inflection signal for premium formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Master Label Acquisition | Hospital-grade registration unlocks GPO contract eligibility across merged US health systems. |
| Backward Integration into Chlor-Alkali | Captive sodium hypochlorite supply insulates margins from Gulf Coast feedstock volatility. |
| EU BPR Compliance Reformulation | Sodium hypochlorite pivot secures German hospital procurement ahead of quaternary ammonium restrictions. |
| Controlled-Release Encapsulation R&D | Surgical suite material compatibility expands addressable market beyond surface disinfection. |
| Direct E-Commerce Institutional Channel | Digital GPO platforms enable manufacturer bypass of traditional distribution markups. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market combining interviews with infection control officers, GPO contracts managers, chlor-alkali procurement leads, and nonwoven substrate technical directors with secondary validation from EPA registration databases, EU BPR active substance review timelines, and SEC 10-K filings of listed disinfectant manufacturers. Bottom-up facility-level procurement modeling triangulates against top-down category spend estimates.
Granularity-level modeling operates at the product-type by application by end-user by country intersection, with disposable wipes, surface disinfection, and hospital procurement modeled as distinct revenue pools. CAGRs derive from facility expansion pipelines, regulatory registration backlogs, and infection control protocol adoption curves across the projection horizon. Forecast inputs incorporate chlor-alkali capacity utilization, spunlace substrate pricing indices, and EPA master label approval velocity.
Inputs from hospital procurement databases and GPO contract disclosure were available through the study window; gaps in private-label converter financials introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding regulatory timeline stability and feedstock supply continuity. A model refresh is warranted upon material change in EPA emerging viral pathogen guidance scope or EU BPR active substance authorization deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Cleanroom Consumables Market