
 Laboratory Balances and Scales Market | 2026-2036
Laboratory Balances and Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Balances and Scales Market Analysis
Multi-source procurement for load cells and electromagnetic force compensation sensors is realigning supply strategies among precision instrument manufacturers. Mettler Toledo leverages its captive sensor production to sustain margin control across analytical and micro balance lines. Sartorius anchors European demand through deep specialization in biopharma weighing workflows. A&D Company competes aggressively in Asia-Pacific price-sensitive segments with standardized digital platforms.
Laboratory balances and scales are precision mass measurement instruments employing electromagnetic force restoration or strain gauge load cell mechanisms, with readability thresholds spanning 0.1 micrograms to several kilograms and draft shield enclosures for environmental isolation; they enable quantitative analysis, formulation compliance, and gravimetric sample preparation across regulated industries. Analytical balances command the deepest margin pools due to pharmaceutical validation requirements and ISO 17025 calibration protocols, while micro balances represent the fastest-growing product type as gene therapy and nanomaterial research intensify. Electromechanical technology dominates installed bases, though digital platforms with embedded connectivity are displacing legacy mechanical units in environmental testing and food safety laboratories.
FDA 21 CFR Part 11 and EU GMP Annex 15 both mandate audit trails and user access controls for weighing data in pharmaceutical applications, compelling equipment upgrades and software validation investments. ISO 9001 and OIML R 76 certification requirements shape market access barriers, particularly for suppliers targeting European metrology institutes and North American contract research organizations. Stakeholders must monitor evolving USP general chapters on weighing accuracy and emerging EPA methods for gravimetric environmental sample analysis to anticipate specification shifts and compliance-driven replacement cycles.
Market Dynamics
Electromagnetic force compensation sensor supply is consolidating among three German and Japanese component houses, forcing balance manufacturers to secure multi-year procurement contracts or invest in captive coil-winding capabilities to protect margin structures.
Growth Catalysts
- Gene therapy manufacturing scale-up:Cell and gene therapy facilities require micro balance precision for viral vector dosing. FDA's process analytical technology guidance mandates real-time mass verification during fill-finish operations.
- EU GMP Annex 15 data integrity mandates:European pharmaceutical manufacturers must upgrade legacy balances with audit-trail software. Equipment replacement cycles compress as national inspectorates enforce ALCOA+ principles.
- Baden-Württemberg precision cluster expansion:Stuttgart-Tübingen corridor instrumentation firms anchor sensor R&D and calibration service density for European contract research organizations.
Market Restraints
- Electromagnetic coil copper and permalloy concentration:Force restoration sensors depend on specialized alloys sourced from limited Japanese and German metallurgical suppliers. Price volatility in rare earth magnetic materials strains component cost structures.
- ISO 17025 calibration infrastructure scarcity:Accredited mass metrology laboratories concentrate in national standards institutes across Germany, Switzerland, and the United States. Regional manufacturers face extended lead times for validation services.
- Strain gauge substitution in industrial applications:Lower-precision weighing in environmental and food testing migrates to piezoelectric and MEMS alternatives. This displacement compresses addressable volume for entry-level balance lines.
Strategic Opportunities
- Indian pharmaceutical contract manufacturing expansion:CDSCO's revised Schedule M requirements for active pharmaceutical ingredient weighing accuracy create upgrade demand among Mumbai and Hyderabad formulation facilities.
- Cloud-connected balance-as-a-service models:Equipment vendors deploy subscription pricing with embedded calibration management and predictive maintenance. Biopharma startups in Boston and Basel reduce capital commitment through operational expenditure structures.
- Dual carbon goal compliance in Chinese research infrastructure:NMPA's green laboratory initiative incentivizes energy-efficient electromagnetic designs. Domestic manufacturers in Shanghai and Suzhou capture replacement demand from thermal-mechanical legacy units.
Industry Challenges
- Metrology technician certification bottlenecks:ISO 17025 lead assessor and balance service engineer credentials require 18-24 month training pipelines. European and North American service networks struggle to match installation base growth.
- Legacy LIMS integration complexity:Pharmaceutical quality control departments maintain 15-20 year-old laboratory information management systems. New balance data formats require custom middleware development for audit trail synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Balances and Scales Market |
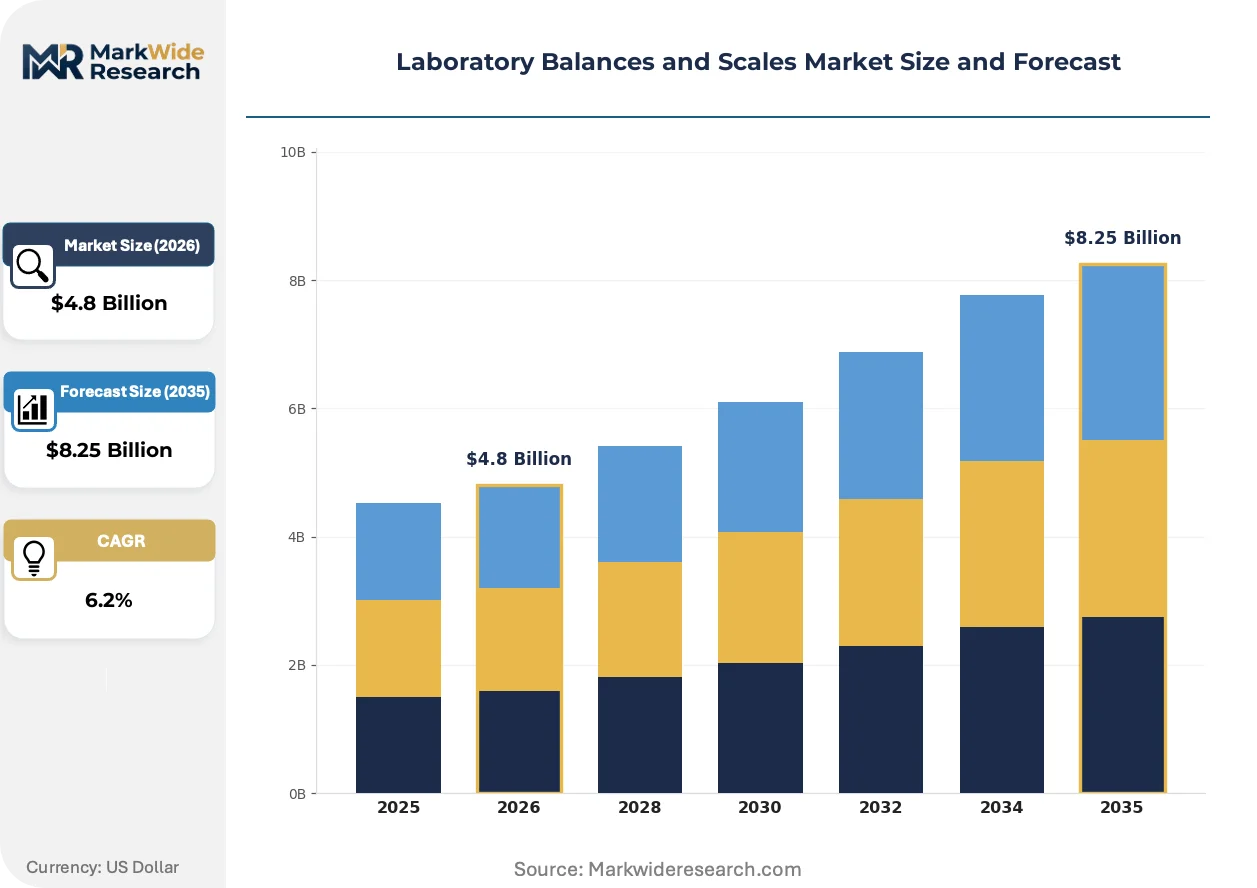
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Balances, Precision Balances, Top-loading Balances, Micro Balances Technology: Electromechanical, Digital, Semi-analytical, Mechanical End User: Pharmaceuticals, Academic Institutions, Food & Beverage, Environmental Testing Capacity: 0-200g, 200-500g, 500-1000g, Over 1000g |
| Companies Covered | Ohaus, Adam Equipment, Mettler Toledo, RADWAG, Kern & Sohn, Sartorius, A&D Company, Precisa Gravimetrics, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Balances and Scales Market Emerging Trajectories
Digital connectivity architectures are absorbing weighing instrumentation into broader laboratory automation ecosystems. Three developments define current investment patterns.
Electromagnetic force restoration with embedded IoT diagnostics is absorbing service revenue from third-party calibration providers. Pharmaceutical quality control departments in Basel and Research Triangle Park deploy predictive algorithms that flag drift before tolerance breach. This capability compresses unplanned downtime and shifts vendor relationships toward platform subscription models.
REACH restrictions on mercury-containing tilt sensors and EU F-Gas Regulation phase-downs are forcing redesign of environmental isolation systems. Balance manufacturers substitute mechanical draft shield damping for legacy thermal expansion compensation. German and Swiss precision instrument houses accelerate solid-state sensor development to maintain IP65 enclosure ratings without regulated materials.
Biopharma procurement departments now unbundle hardware purchase from validation and calibration service contracts. Large molecule manufacturers in Massachusetts and Bavaria negotiate multi-site framework agreements with single-source metrology providers. This consolidation pressures regional distributors and shifts margin capture toward integrated service platforms with ISO 17025 accreditation depth.
Laboratory Balances and Scales Market Segmentation
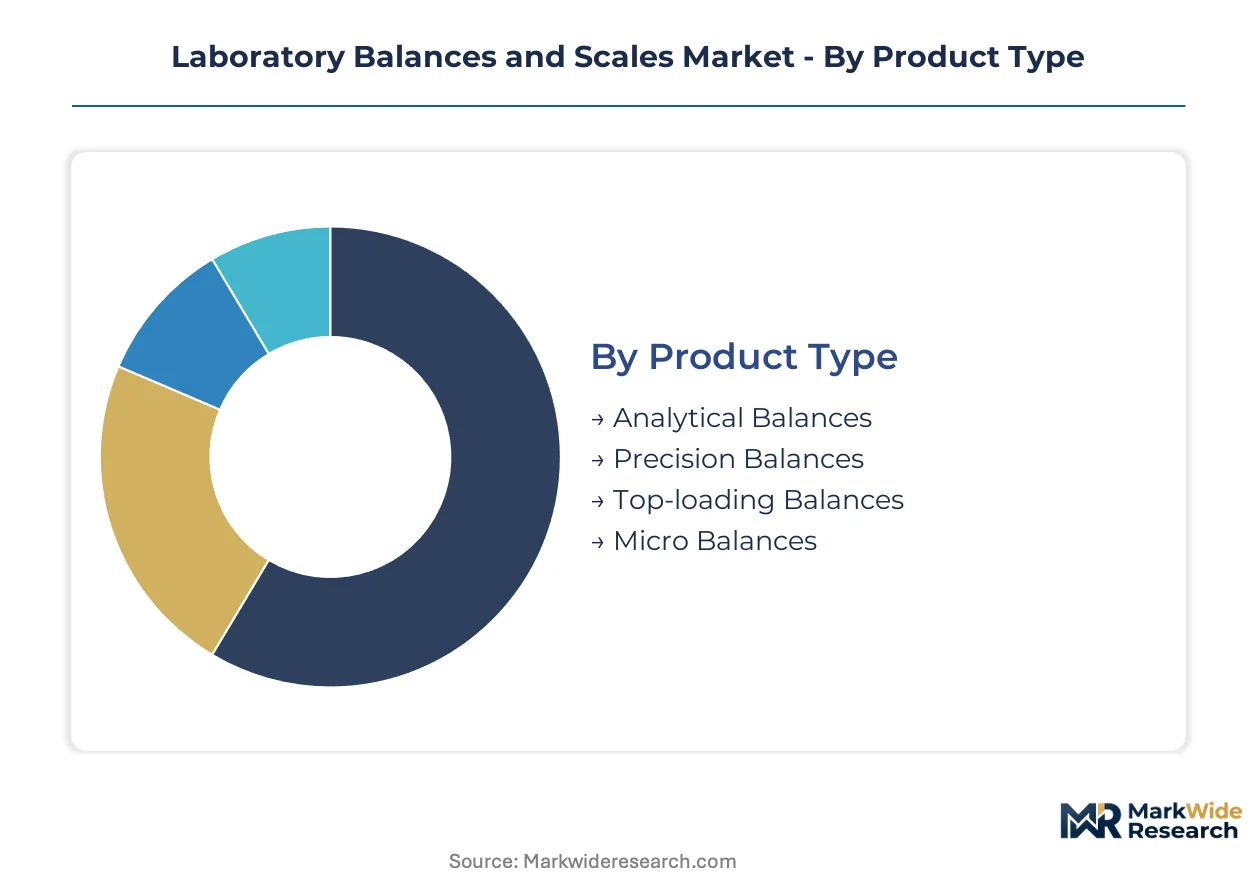
Laboratory balances and scales fragment across four structural axes that determine procurement patterns and margin capture. Product type and capacity specifications anchor pharmaceutical validation workflows, while technology architecture and end-user concentration shape replacement cycles and service attachment rates.
Product Type:
Readability thresholds and draft shield specifications define the technology-product alignment.
- Analytical Balances:Electromagnetic force restoration mechanisms deliver 0.1mg readability with enclosed draft shields. German pharmaceutical quality control laboratories in Saxony and Baden-Württemberg concentrate procurement for ISO 17025-compliant formulation validation.
- Micro Balances:Sub-microgram resolution enables viral vector dosing in cell and gene therapy manufacturing. FDA process analytical technology guidance accelerates deployment in Boston and Basel biopharma clusters for real-time mass verification during fill-finish operations.
- Precision Balances:Strain gauge load cells serve routine quantitative analysis with 1mg resolution across environmental testing laboratories.
- Top-loading Balances:Open-pan designs prioritize speed over environmental isolation for industrial quality control and educational settings.
Mature deployment sits with analytical balances. Newer deployment is concentrated in micro balances.
Technology:
Sensor architecture and connectivity integration determine calibration protocols and compliance readiness.
- Electromechanical:Force restoration coils with analog-to-digital conversion dominate installed bases. Japanese and German component houses supply specialized copper and permalloy alloys, forcing manufacturers into multi-year procurement contracts or captive winding investments.
- Digital:Embedded IoT diagnostics and cloud-native data architectures enable predictive drift detection. Basel and Research Triangle Park pharmaceutical quality control departments compress unplanned downtime through algorithmic tolerance monitoring.
- Semi-analytical:Hybrid designs bridge precision and throughput for food safety and environmental gravimetric analysis.
- Mechanical:Thermal expansion compensation and manual dial mechanisms persist in legacy educational infrastructure and budget-constrained regional laboratories.
Electromechanical systems anchor current revenue. Digital platforms are climbing the fastest.
End User:
Regulatory stringency and validation burden differentiate procurement sophistication across verticals.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU GMP Annex 15 mandate audit trails and user access controls. European manufacturers compress replacement cycles as national inspectorates enforce ALCOA+ data integrity principles.
- Academic Institutions:Grant-funded research infrastructure in Boston and Basel prioritizes multi-user access and LIMS integration over standalone precision.
- Food & Beverage:HACCP compliance and rapid throughput favor top-loading and precision balance categories with minimal environmental isolation.
- Environmental Testing:EPA gravimetric methods and REACH-restricted material bans force draft shield redesigns away from mercury-containing tilt sensors.
Pharmaceuticals concentrate premium procurement. Academic institutions drive standardization.
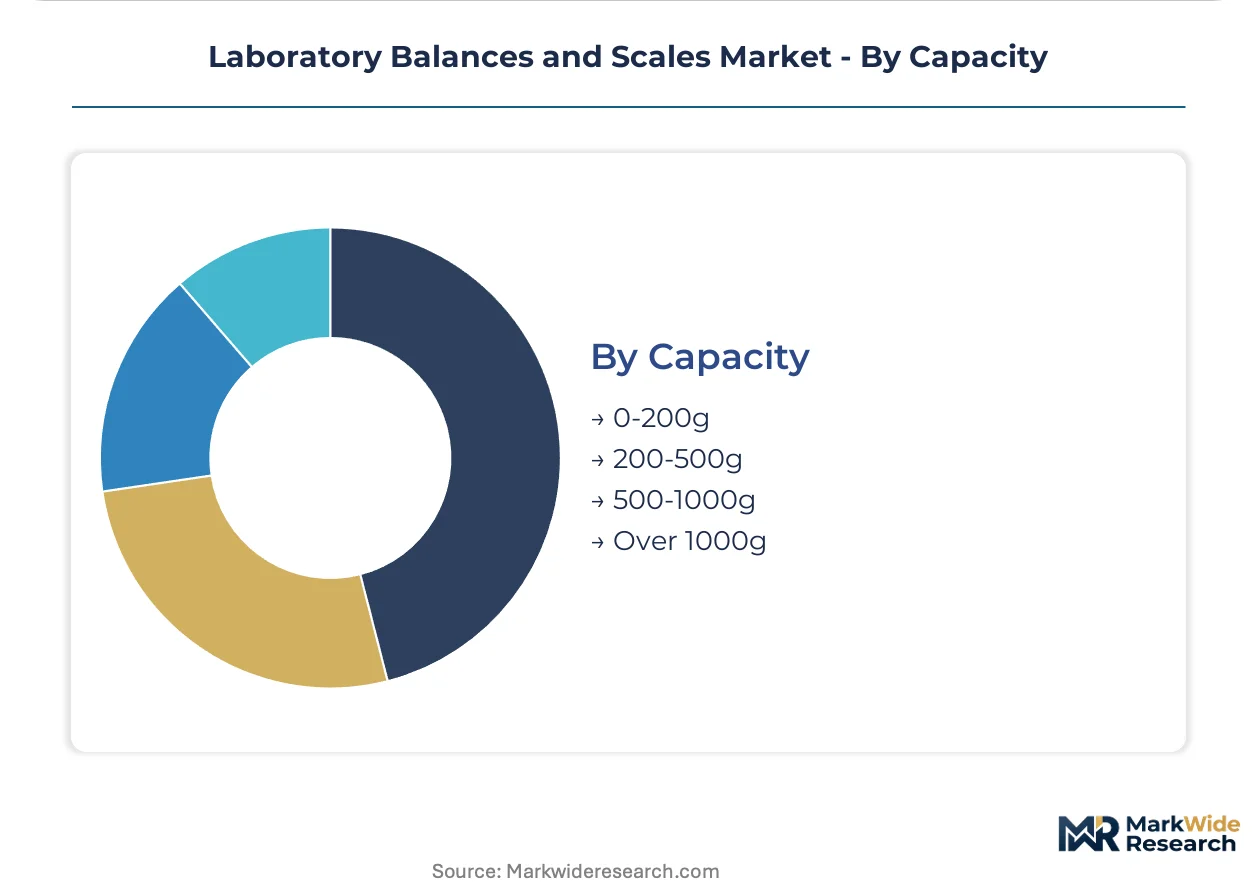
Capacity:
Mass range determines sensor mechanism selection and application suitability.
- 0-200g:Micro and analytical balance territory where electromagnetic force restoration achieves highest precision. Gene therapy viral vector dosing and nanomaterial research concentrate demand.
- 200-500g:Precision balance sweet spot for pharmaceutical formulation and quality control workflows requiring moderate throughput.
- 500-1000g:Strain gauge load cell economics improve for food safety sample preparation and environmental gravimetric analysis.
- Over 1000g:Industrial-grade platforms with reduced readability serve bulk chemical handling and educational demonstrations.
0-200g capacity anchors margin pools. 200-500g capacity is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized copper and permalloy alloy supplies from Japanese and German metallurgical houses anchor precision sensor production. These material flows concentrate electromagnetic force restoration manufacturing in established instrumentation clusters. National metrology institutes and pharmaceutical regulatory stringency differentiate regional demand intensity.
United States
Cell and gene therapy manufacturing scale-up in Massachusetts and North Carolina drives micro balance procurement. FDA 21 CFR Part 11 enforcement compels audit-trail upgrades across legacy pharmaceutical quality control laboratories. The Research Triangle Park biopharma cluster concentrates real-time mass verification deployments for viral vector dosing workflows.
Germany
European pharmaceutical contract research organizations anchor analytical balance demand through ISO 17025 validation requirements. EU GMP Annex 15 data integrity mandates compress replacement cycles as national inspectorates enforce ALCOA+ principles. The Stuttgart-Tübingen corridor in Baden-Württemberg hosts sensor R&D density and calibration service infrastructure for precision instrument supply.
Switzerland
Large molecule manufacturers in Basel negotiate multi-site framework agreements for integrated metrology services. Swissmedic oversight of biopharmaceutical quality systems mandates user access controls and audit trail documentation. The Basel pharmaceutical cluster unbundles hardware procurement from validation contracts, shifting margin capture toward accredited service platforms.
China
Domestic pharmaceutical contract manufacturing expansion in Shanghai and Suzhou creates upgrade demand from NMPA green laboratory initiatives. Dual carbon goals incentivize energy-efficient electromagnetic designs displacing thermal-mechanical legacy units. The Yangtze River Delta precision instrument manufacturing base captures replacement demand through localized sensor assembly and calibration infrastructure.
India
Active pharmaceutical ingredient formulation facilities in Mumbai and Hyderabad face CDSCO Schedule M requirements for weighing accuracy. National pharmaceutical regulator inspections accelerate compliance-driven equipment upgrades among contract manufacturers. The Maharashtra and Telangana pharmaceutical manufacturing belts concentrate demand for standardized digital platforms with embedded connectivity.
Laboratory Balances and Scales Market Vendor Landscape
Global majors compete with regional champions across sensor technology and service integration dimensions. The vendor base stratifies between captive sensor producers and assembly-dependent fabricators, with electromagnetic force restoration coil supply concentrating competitive leverage. Three archetypes dominate: integrated precision instrument houses with in-house metallurgical capabilities, regional specialists anchoring national metrology ecosystems, and Asian-scale fabricators competing on standardized digital platforms. Capacity expansion in sensor winding and multi-year procurement contracting represent the dominant competitive moves.
Among integrated precision instrument houses, Mettler Toledo and Sartorius occupy positions defined by captive production of electromagnetic force restoration components. Mettler Toledo leverages its sensor manufacturing depth to sustain margin control across analytical and micro balance lines. Sartorius anchors European demand through specialization in biopharma weighing workflows. A&D Company exemplifies the Asian-scale fabricator archetype, competing in price-sensitive segments with standardized digital platforms.
| Leading Market Players |
|---|
| Ohaus |
| Adam Equipment |
| Mettler Toledo |
| RADWAG |
| Kern & Sohn |
| Sartorius |
| A&D Company |
| Precisa Gravimetrics |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Metrology technician certification density in Saxony and Baden-Württemberg feeds into labor-cost differentials that widen pricing-tier spreads between ISO 17025-accredited premium offerings and unbundled economy platforms. Electromagnetic force restoration coil winding demands specialized copper and permalloy handling skills that concentrate in German and Japanese precision clusters, compressing margins for assembly-dependent fabricators while sustaining premium capture for captive producers.
Pricing Analysis
Warranty and calibration service bundling separates premium electromagnetic force restoration systems from unbundled hardware transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 17025 certification grade and embedded IoT diagnostic depth. Cost compression in economy strain-gauge segments is intensifying because MEMS alternatives erode addressable volume. Academic institutions and environmental testing laboratories exhibit highest price sensitivity; gene therapy manufacturers show lowest sensitivity due to FDA process analytical technology compliance mandates.
Supply Chain Analysis
ISO 17025 calibration accreditation gates market access for component suppliers and finished balance manufacturers alike. Electromagnetic force restoration sensor production anchors in Germany and Japan, drawing from specialized copper and permalloy alloy feeds. Single-source vulnerability concentrates in Japanese metallurgical houses supplying force restoration coil materials. Distribution runs through national metrology institutes and pharmaceutical-focused distributors serving ISO 17025 validation workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where electromagnetic force restoration coil winding capabilities determine margin sustainability. Players are pursuing upstream control over permalloy and copper alloy sourcing to defend pricing power against component cost volatility.
For Market Incumbents: Extend captive sensor production investments to protect margin structures against multi-year procurement contract inflation. Deepen ISO 17025 accreditation infrastructure in Basel and Research Triangle Park to capture biopharma service contract consolidation. MEMS substitution in industrial applications threatens entry-level volume; respond with predictive maintenance platform subscriptions that shift revenue toward recurring streams. For New Entrants and Emerging Players: Begin with cloud-native balance-as-a-service models targeting Boston and Basel biopharma startups seeking operational expenditure structures. Indian pharmaceutical contract manufacturing expansion under CDSCO Schedule M requirements offers the most penetrable geography for standardized digital platforms without legacy LIMS integration burdens. Pursue direct calibration service partnerships with national metrology institutes to bypass distributor margin extraction. For Investors and Strategic Acquirers: Re-rating potential sits with integrated precision instrument houses possessing captive electromagnetic force restoration capabilities given gene therapy manufacturing scale-up catalysts. Long-term viability over a multi-year horizon favors targets with in-house metallurgical processing and multi-site ISO 17025 accreditation depth. Watch FDA 21 CFR Part 11 enforcement intensity as the signal indicating replacement cycle acceleration and audit-trail software attach-rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sensor Production Expansion | In-house electromagnetic force restoration coil winding insulates Mettler Toledo and Sartorius from permalloy price volatility. |
| ISO 17025 Accreditation Depth Buildout | Multi-site calibration infrastructure captures biopharma unbundling of hardware from validation service contracts in Basel. |
| Cloud-Native Platform Development | Embedded IoT diagnostics enable predictive drift detection for Research Triangle Park pharmaceutical quality control departments. |
| Multi-Year Procurement Contracting | Long-term copper and permalloy supply agreements protect margin structures against Japanese metallurgical supplier concentration. |
| Biopharma Workflow Specialization | Deep integration with viral vector dosing protocols anchors Sartorius positioning in cell and gene therapy manufacturing scale-up. |
Methodological Framework
SEC filings, OIML R 76 certification registries, and pharmaceutical quality control equipment procurement databases formed the secondary backbone of this analysis. Primary interviews with metrology service engineers, pharmaceutical quality control directors, and precision instrument procurement managers at contract research organizations combined with secondary validation. Bottom-up and top-down triangulation cross-checked sensor shipment data against end-user installation base estimates.
Bottom-up modeling of electromagnetic force restoration and strain gauge load cell unit economics fed into segment-level revenue builds across the projection horizon. Product type, technology architecture, end-user vertical, and capacity specifications anchored segmentation dimensions alongside regional regulatory cluster intensity. CAGRs derived from weighted average of historical replacement cycle compression rates and compliance-driven upgrade elasticity. Gene therapy manufacturing facility buildouts and FDA data integrity enforcement patterns served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; micro balance and analytical balance categories carry tighter precision than precision balance and top-loading categories due to pharmaceutical validation workflow visibility. Forecasts reflect assumptions regarding CDSCO Schedule M implementation timelines and EU GMP Annex 15 inspectorate resource allocation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Rheology Controller Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
CHS (Carbon Hydrogen Sulfur) Analyzers Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Leather Testing Machine Market