
 Americas Seeds Market | 2026-2036
Americas Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Seeds Market Outlook
Plant breeding talent is rotating toward computational genomics and marker-assisted selection, tightening the labor pool for classical field breeders. Bayer AG leverages its digital breeding platform to compress cycle times for corn and soybean varieties. Corteva Inc anchors its Americas position through proprietary CRISPR pipelines and direct-to-farmer seed distribution networks. Syngenta Group competes via integrated crop protection bundles that lock in seed-chemistry combinations across Argentine wheat zones.
Seeds are reproductive plant units—embryos encased in protective coats with stored nutritive tissue—engineered for specific germination rates, disease resistance profiles, and yield potentials under defined agroclimatic stress thresholds. Their commercial purpose centers on propagating cultivars with uniform phenotypic expression for mechanized harvesting and supply chain predictability. Cereals occupy the dominant value pool given corn and soybean acreage dominance, while vegetables command premium margins through protected cultivation expansion in Mexico and Chile. Horticulture end-use is accelerating fastest as controlled-environment agriculture spreads across Canadian greenhouse clusters and Colombian flower export zones.
USDA-APHIS oversees plant-incorporated protectant regulations and gene-edited trait deregulation pathways in the United States, while Health Canada's PMRA governs novel trait environmental release authorizations; Brazil's CTNBio applies biosafety standards that determine market access for transgenic and gene-edited seeds. These frameworks shape product development timelines, field trial locations, and cross-border seed movement protocols throughout the hemisphere. Stakeholders must monitor evolving gene-editing classification debates across federal and provincial jurisdictions to anticipate compliance cost shifts and trait commercialization sequencing.
Market Dynamics
Gene-edited trait deregulation under USDA-APHIS protocols is compressing product development timelines and redrawing competitive boundaries between transgenic and gene-edited seed portfolios across the hemisphere.
Growth Catalysts
- Brazil's Cerrado Expansion:Specialty crop growers in Mato Grosso and Goiás are expanding hybrid seed procurement for double-cropping soy-corn rotations on newly cleared savanna acreage.
- USDA-APHIS Regulatory Streamlining:The SECURE rule framework exempts certain gene-edited traits from case-by-case review, accelerating field trial-to-commercialization pathways for drought-tolerant varieties.
- Controlled-Environment Agriculture:Canadian greenhouse clusters and Colombian flower export zones are driving demand for high-germination vegetable and ornamental seed with precision phenotypic uniformity.
Market Restraints
- Input Cost Volatility:Parent seed production and cold-chain logistics face pressure from diesel and nitrogen fertilizer price swings that compress margins for foundation seed multiplication.
- Supply Concentration Risk:Proprietary germplasm pools for elite inbred lines concentrate among three breeding hubs in the US Corn Belt, creating vulnerability to localized weather shocks.
- Regulatory Friction:Brazil's CTNBio maintains distinct biosafety classification protocols for gene-edited versus transgenic traits, forcing parallel dossier preparation for cross-border variety registration.
Strategic Opportunities
- Argentina Wheat Belt Penetration:Integrated crop protection bundles combining seed-chemistry combinations remain underdeveloped in Buenos Aires and Córdoba provinces relative to Brazilian soybean zones.
- Direct-to-Farmer Digital Channels:E-commerce platforms and farm management software integrations enable seed ordering with embedded agronomic prescriptions, bypassing traditional distributor markups.
- Canadian Varietal Registration Reform:Health Canada's streamlined PMRA environmental release authorizations for gene-edited traits create first-mover advantage windows for CRISPR-enabled disease resistance.
Industry Challenges
- Computational Genomics Talent Gap:Classical field breeders with deep phenotype evaluation expertise are retiring faster than universities can produce data scientists with combined agronomic and bioinformatics training.
- Trait Integration Complexity:Stacking multiple gene-edited modifications into commercial varieties requires synchronized regulatory dossiers across USDA-APHIS, EPA, and FDA jurisdictions for stacked-trait approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Seeds Market |
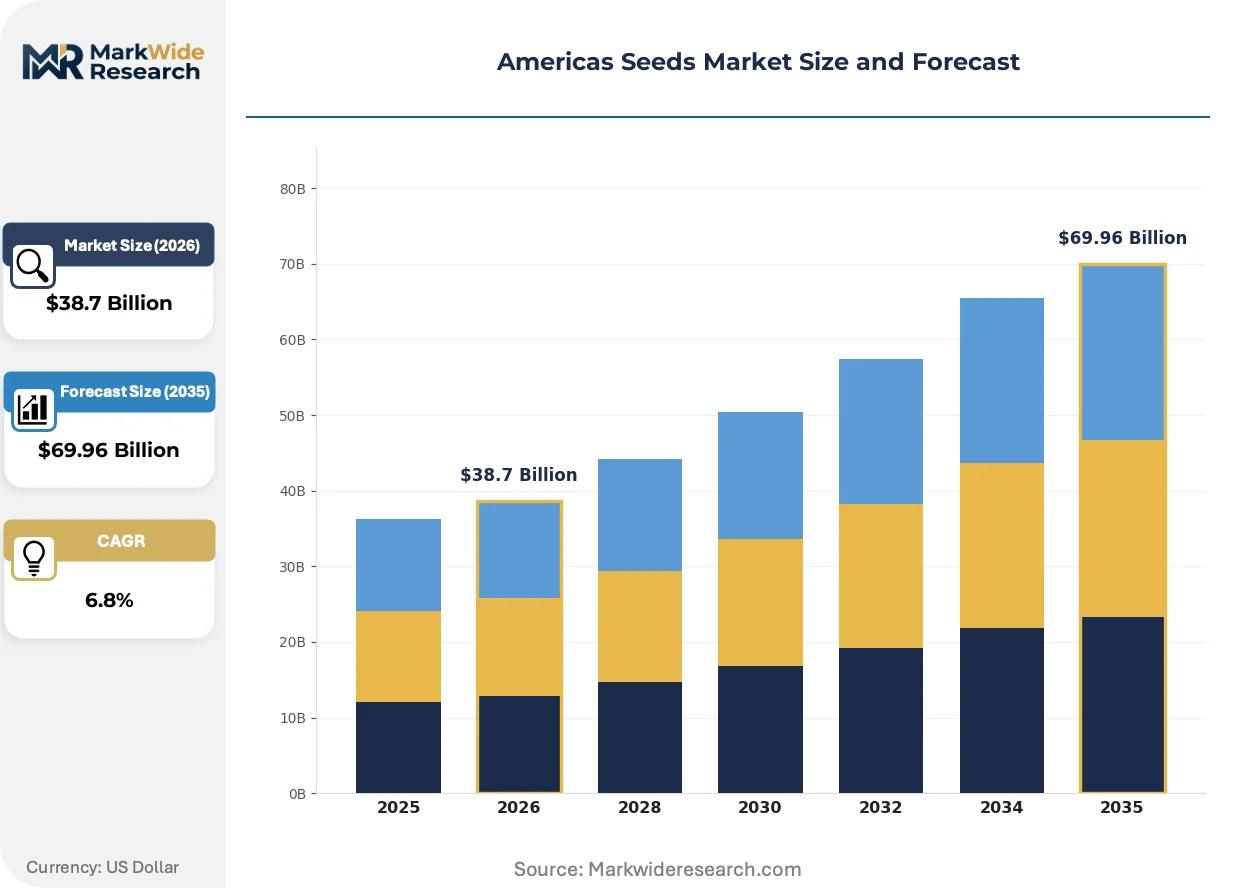
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Pulses, Vegetables, Flowers End Use Industry: Agriculture, Horticulture, Landscaping, Research Packaging Type: Bulk, Retail, Vacuum Sealed, Sachets Distribution Channel: Online, Supermarkets, Agricultural Stores, Distributors |
| Companies Covered | Bayer AG, Corteva Inc, Syngenta Group, BASF SE, Land O'Lakes Inc, UPL, FMC, Nufarm, KWS AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Seeds Market Strategic Shifts
Digital breeding platforms and marker-assisted selection protocols are compressing variety development cycles while regulatory frameworks race to classify novel gene-edited products.
CRISPR-Cas9 gene editing is displacing transgenic insertion methods for trait development in corn and soybean programs. Large-scale breeding operations in Iowa and Illinois are adopting the technology for rapid generation of herbicide-tolerance and disease-resistance profiles. The shift is displacing multi-year Agrobacterium-mediated transformation timelines with 12-18 month editing cycles, forcing reconfiguration of intellectual property licensing structures around guide RNA designs rather than promoter-gene constructs.
USDA-APHIS implemented the SECURE rule in 2020, exempting gene-edited plants with traits achievable through conventional breeding from regulatory oversight. The policy consequence is bifurcated compliance pathways where developers self-determine regulatory status based on trait novelty assessments. Corn and soybean seed developers in the US Corn Belt are responding by front-loading legal review to preempt state-level patchwork restrictions, particularly in California and New York where consumer-facing labeling debates persist.
Farmer purchasing behavior is consolidating around bundled input decisions where seed selection precedes and constrains chemistry and biological product choices. Argentine wheat growers in the Pampas region are migrating toward multi-year variety loyalty contracts that lock in seed-crop protection combinations. The pattern is most visible in Brazil's Mato Grosso, where 2,000-hectare operations negotiate direct volume commitments with breeding companies, displacing independent distributor networks that previously intermediated variety trials and credit extension.
Americas Seeds Market Segmentation
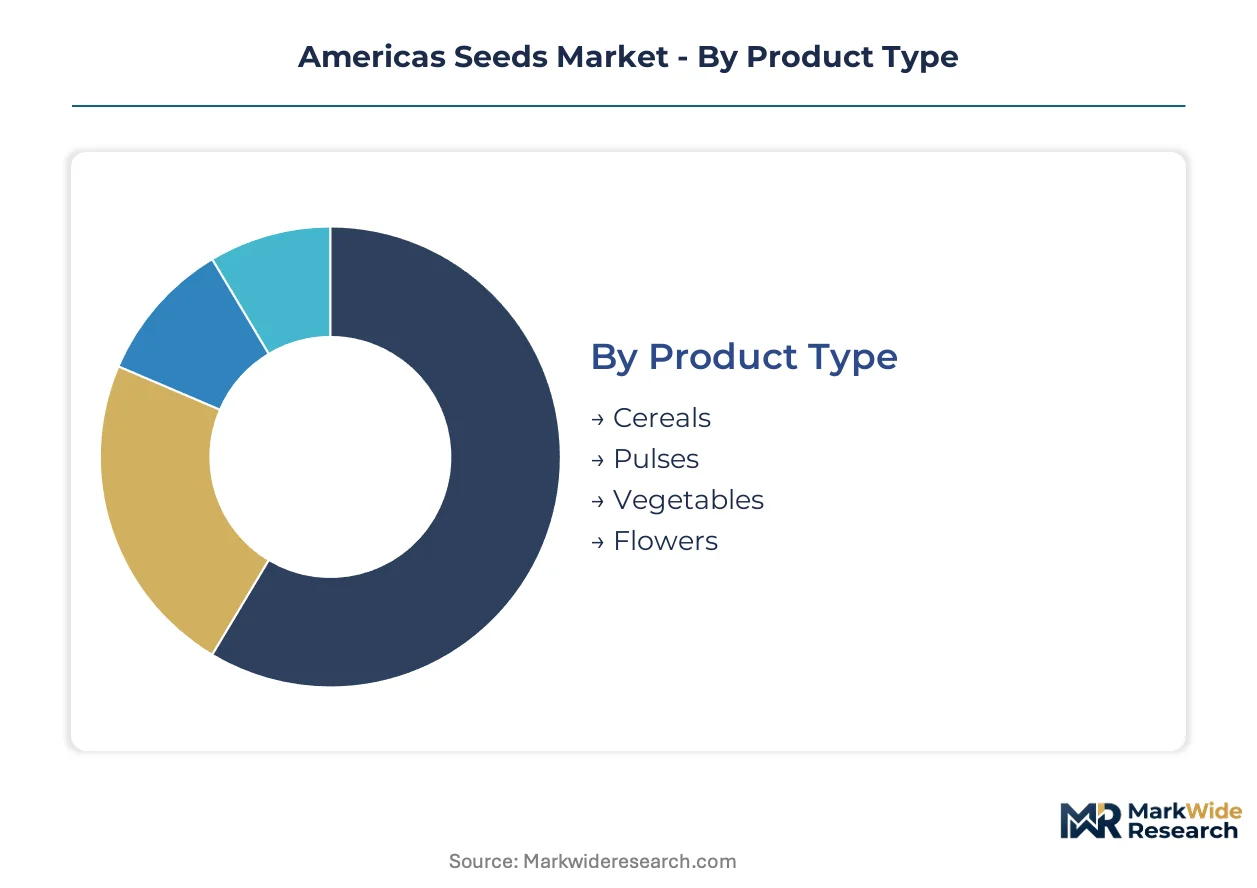
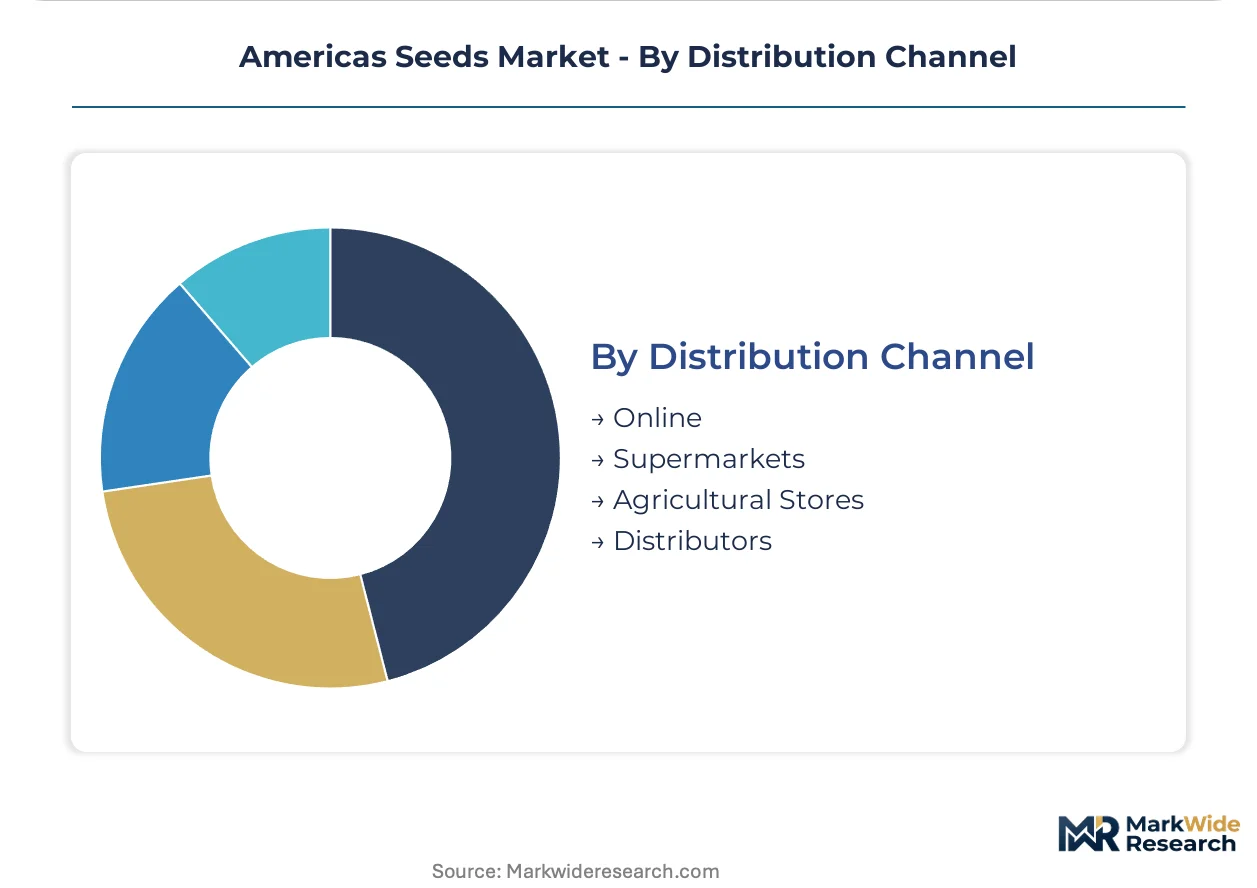
Seed segmentation across the Americas reflects divergent commercial pathways. Bulk cereal genetics flow through distributor networks to Mato Grosso soybean operations, while vacuum-sealed vegetable varieties reach Canadian greenhouse clusters via direct e-commerce channels.
Product Type:
Channel mix varies sharply by crop biology and farmer scale. Cereals dominate distributor-led volume, while vegetables and flowers concentrate in retail and direct digital procurement.
- Cereals:Corn and soybean seed engineered for herbicide tolerance and drought resistance constitutes the revenue foundation. Demand concentrates in Brazil's Cerrado expansion belt and the US Corn Belt, driven by double-cropping intensity and mechanized harvesting requirements for uniform phenotypic expression.
- Vegetables:High-germination hybrids for tomatoes, peppers, and leafy greens command premium positioning. Mexican protected cultivation clusters and Canadian greenhouse operations in Leamington and Delta drive procurement, fueled by year-round production schedules and export-grade quality specifications.
- Pulses:Bean and lentil varieties optimized for nitrogen fixation efficiency serve rotational cropping systems. Argentine pulse growers in Córdoba and Santa Fe provinces represent concentrated demand nodes.
- Flowers:Ornamental seed with precision color uniformity targets Colombian export zones around Bogotá and Medellín. Sachet packaging dominates this segment given small lot sizes and high value-to-weight ratios.
By volume, cereals lead. By growth pace, vegetables are climbing the fastest.
End Use Industry:
Cost tier stratification separates commodity agriculture from premium horticulture and specialized research applications.
- Agriculture:Broad-acre row crop production consumes hybrid seed at industrial scale. Brazilian soybean-corn rotations and US Midwest corn operations represent the core demand pool, with procurement consolidating around multi-year volume contracts that bundle genetics with crop protection chemistries.
- Horticulture:Controlled-environment agriculture in Canadian greenhouse clusters and Chilean berry export zones requires seed with germination rates exceeding 95 percent and disease resistance calibrated to hydroponic stress conditions. Premium pricing reflects phenotypic uniformity demands.
- Landscaping:Turf grass and ornamental varieties for golf courses and municipal parks operate through seasonal retail channels. US Sun Belt expansion sustains steady demand for warm-season grass cultivars.
- Research:Foundation seed and breeder stock supply university field trials and private R&D stations. Iowa State University and Embrapa facilities in Brazil anchor this niche segment.
Agriculture generates absolute volume; horticulture captures margin expansion.
Packaging Type:
Supply concentration in foundation seed multiplication shapes packaging economics and cold-chain requirements.
- Bulk:Tote and bin configurations for corn and soybean seed serve 2,000-hectare Brazilian operations and US Midwest farms. Vacuum sealing is absent given rapid planting turnover and on-farm treatment capabilities.
- Retail:Paper and woven poly bags for vegetable and flower seed reach home gardeners and small-scale producers through agricultural stores and supermarket garden centers.
- Vacuum Sealed:Moisture-barrier pouches preserve germination viability for high-value vegetable genetics during transoceanic shipment to Colombian and Chilean import points.
- Sachets:Unit-dose packaging for herbs and specialty flowers dominates Mexican retail channels and US home improvement store seed racks.
Bulk packaging commands tonnage leadership; vacuum sealed formats are gaining share fastest in cross-border vegetable trade.
Distribution Channel:
Customer type and farm scale determine channel selection, with digital platforms eroding traditional distributor intermediation.
- Distributors:Independent and captive networks handle credit extension, variety trialing, and agronomic advice for Brazilian soybean growers and Argentine wheat producers. Corteva and Bayer maintain dedicated distributor partnerships across the Pampas and Cerrado.
- Agricultural Stores:Co-op and independent retailers serve mid-scale US Corn Belt operations with seasonal inventory and localized seed treatment services.
- Online:Direct-to-farmer platforms with embedded prescription tools bypass markup layers. Canadian greenhouse operators and Colombian flower exporters increasingly procure through integrated farm management software portals.
- Supermarkets:Mass retail garden centers capture seasonal home gardener demand for vegetable and flower seed in US and Mexican urban markets.
Distributors retain volume dominance; online channels are expanding most quickly in high-value horticulture procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and the United States consume seeds at industrial scale for commodity agriculture, while Canada and Colombia concentrate procurement on high-value horticulture and ornamental genetics with precision germination requirements.
United States
USDA-APHIS gene-edited trait exemptions under the SECURE rule accelerate drought-tolerant corn and soybean variety approvals. The Iowa-Illinois Corn Belt anchors foundation seed multiplication for elite inbred lines, with digital breeding platforms compressing development cycles for herbicide-tolerance stacking.
Brazil
Double-cropping soy-corn rotations across Mato Grosso and Goiás drive hybrid seed procurement at 2,000-hectare scale. CTNBio maintains distinct biosafety protocols for gene-edited versus transgenic traits, forcing parallel dossier preparation for cross-border registration.
Canada
Health Canada's PMRA streamlines environmental release authorizations for CRISPR-enabled disease resistance. Leamington and Delta greenhouse clusters in Ontario and British Columbia demand vegetable seed with germination rates exceeding 95 percent for year-round hydroponic production.
Argentina
Wheat growers in Buenos Aires and Córdoba provinces migrate toward multi-year variety loyalty contracts bundling seed with crop protection chemistries. The Pampas region remains underdeveloped for integrated bundles relative to Brazilian soybean zones.
Colombia
Flower export zones around Bogotá and Medellín require ornamental seed with precision color uniformity for transoceanic shipment. Sachet packaging dominates procurement given small lot sizes and high value-to-weight ratios in protected cultivation.
Americas Seeds Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the top tier controlling proprietary germplasm pools and gene-editing pipelines. The market structure reflects consolidation around three breeding hubs with captive distribution networks. Strategic archetypes include integrated agrochemical-seed conglomerates, farmer-owned cooperatives with captive genetics, and regional specialists in vegetable or cereal germplasm. Dominant competitive moves center on direct-to-farmer digital channel expansion and CRISPR licensing portfolio assembly.
Among integrated agrochemical-seed conglomerates, Bayer AG and Corteva Inc exemplify the scale-driven archetype with hemisphere-spanning breeding operations. Syngenta Group occupies a position within the crop protection bundle tier, anchoring integrated seed-chemistry combinations across Argentine and Brazilian cultivation zones. These three entities represent the competitive core around which mid-tier specialists and regional cooperatives position for access to elite germplasm and trait licensing.
| Leading Market Players |
|---|
| Bayer AG |
| Corteva Inc |
| Syngenta Group |
| BASF SE |
| Land O'Lakes Inc |
| UPL |
| FMC |
| Nufarm |
| KWS AG |
| Others |
Value Chain & Pricing Dynamics
Ninety-day foundation seed multiplication cycles concentrate pricing power among three Corn Belt breeding hubs, where parent seed inventory buffers and diesel-driven logistics costs interact to compress margins for distributor networks serving Brazilian soybean operations.
Pricing Analysis
Long-term offtake contracts dominate procurement for 2,000-hectare Brazilian operations, while spot purchases persist for mid-scale Argentine wheat growers. Three-tier pricing structure across premium, standard, and economy levels separates gene-edited trait bundles from conventional hybrids and saved seed. Price differentiation rests on germination certification tiers and volume scale commitments. Cost compression in standard-tier cereal seed is intensifying because nitrogen fertilizer price volatility feeds into parent seed production economics. Mid-scale US Corn Belt operations exhibit highest price sensitivity; Canadian greenhouse operators show least sensitivity given germination rate premiums for hydroponic systems.
Supply Chain Analysis
The United States and Brazil anchor elite inbred line multiplication, while Argentina and Canada concentrate on varietal registration and greenhouse import channels. Proprietary germplasm draws from controlled pollination facilities in Iowa and Illinois, with parent seed resting on diesel-dependent cold-chain logistics and nitrogen-intensive field production. Single-source vulnerability concentrates in three US breeding hubs exposed to localized drought shocks. Distribution runs through captive distributor networks for Brazilian Cerrado expansion zones, with direct-to-farmer digital platforms eroding traditional markup layers in Canadian horticulture procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated 2,000-hectare Brazilian operations and Canadian greenhouse clusters, fragmenting price-setting authority away from independent distributor networks.
For Market Incumbents: Shield germplasm portfolios from CRISPR licensing fragmentation by deepening backward integration into guide RNA design capabilities. Secure captive distribution partnerships across Mato Grosso before direct-to-farmer platforms disintermediate variety trial and credit extension functions. Priority defensive investment centers on computational genomics talent pipelines as classical field breeders retire. For New Entrants and Emerging Players: Lead with precision phenotyping services for Canadian controlled-environment agriculture operators seeking germination rates exceeding 95 percent. White-space targets include Colombian flower export zones around Bogotá and Argentine wheat belt integrated bundles in Buenos Aires province. Go-to-market angle: embedded farm management software portals with seed-chemistry prescription tools. For Investors and Strategic Acquirers: Carve-out targets emerge from agrochemical conglomerates divesting non-core vegetable germplasm units. Long-term viability over the coming decade hinges on gene-edited trait regulatory alignment across USDA-APHIS and CTNBio jurisdictions. Acquisition archetype: regional specialists with CRISPR-enabled disease resistance pipelines and Health Canada PMRA pre-submission dossiers. Signal to watch: CTNBio reclassification of gene-edited traits to harmonize with SECURE rule frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Farmer Digital Channel Expansion | Bypasses distributor markups for Brazilian soybean operations and Canadian greenhouse clusters. |
| CRISPR Licensing Portfolio Assembly | Captures guide RNA intellectual property as transgenic promoter-gene constructs lose competitive relevance. |
| Computational Genomics Talent Pipeline Investment | Addresses retiring classical breeder shortage through university partnership programs in Iowa and Illinois. |
| Integrated Seed-Chemistry Bundle Penetration | Locks in multi-year variety loyalty contracts across Argentine Pampas wheat zones. |
| Health Canada PMRA Pre-Submission Dossier Preparation | Accelerates first-mover windows for CRISPR-enabled disease resistance in Leamington greenhouse clusters. |
Study Parameters
Cross-validation between USDA-APHIS regulatory filing databases and CTNBio biosafety approval records anchors the qualitative findings on gene-edited trait commercialization timelines. Primary interviews with plant breeding directors, distributor network managers, greenhouse procurement officers, and agronomic prescription software developers combined with secondary validation from SEC 10-K filings, customs seed trade data, and Health Canada PMRA environmental release authorizations. Bottom-up acreage projections and top-down input cost models triangulate volume estimates.
Sensitivity analysis around diesel price bands and nitrogen fertilizer cost scenarios tests forecast robustness across the projection horizon. Segmentation dimensions modeled include crop biology (cereals, vegetables, pulses, flowers), end-use intensity (broad-acre agriculture versus controlled-environment horticulture), packaging format (bulk, retail, vacuum-sealed, sachet), and distribution channel structure (distributor, agricultural store, online, supermarket). CAGRs derive from trend extrapolation of double-cropping expansion rates and regulatory approval velocity. Industry-specific inputs include CTNBio dossier preparation timelines and greenhouse germination rate certification thresholds.
Forecasts assume regulatory continuity in USDA-APHIS SECURE rule frameworks and CTNBio biosafety classification protocols; material policy shifts would require re-modeling. Specific risks that could revise projections include gene-editing reclassification debates in Brazilian federal jurisdictions and diesel price shocks affecting parent seed multiplication economics. Recalibration cycles align with material shifts in trait approval timelines and Cerrado clearing regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Sesame Seed Market
Seeds
Brazil Forage Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
North America Maize Seed Treatment Market
Seeds
Vietnam Seed Market
Seeds
Seed Cracker Market
Seeds
Avena Sativa Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Hemp Seeds Market
Seeds
Cherry Tomato Seeds Market
Seeds
Flaxseed (Linseed) Market
Seeds
Africa Peas Market
Seeds
Genetically Modified Seeds Market
Seeds
Flax Seed Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Watermelon Seeds Market