
 North America Vegetable Seed Market | 2026-2036
North America Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vegetable Seed Market Analytics
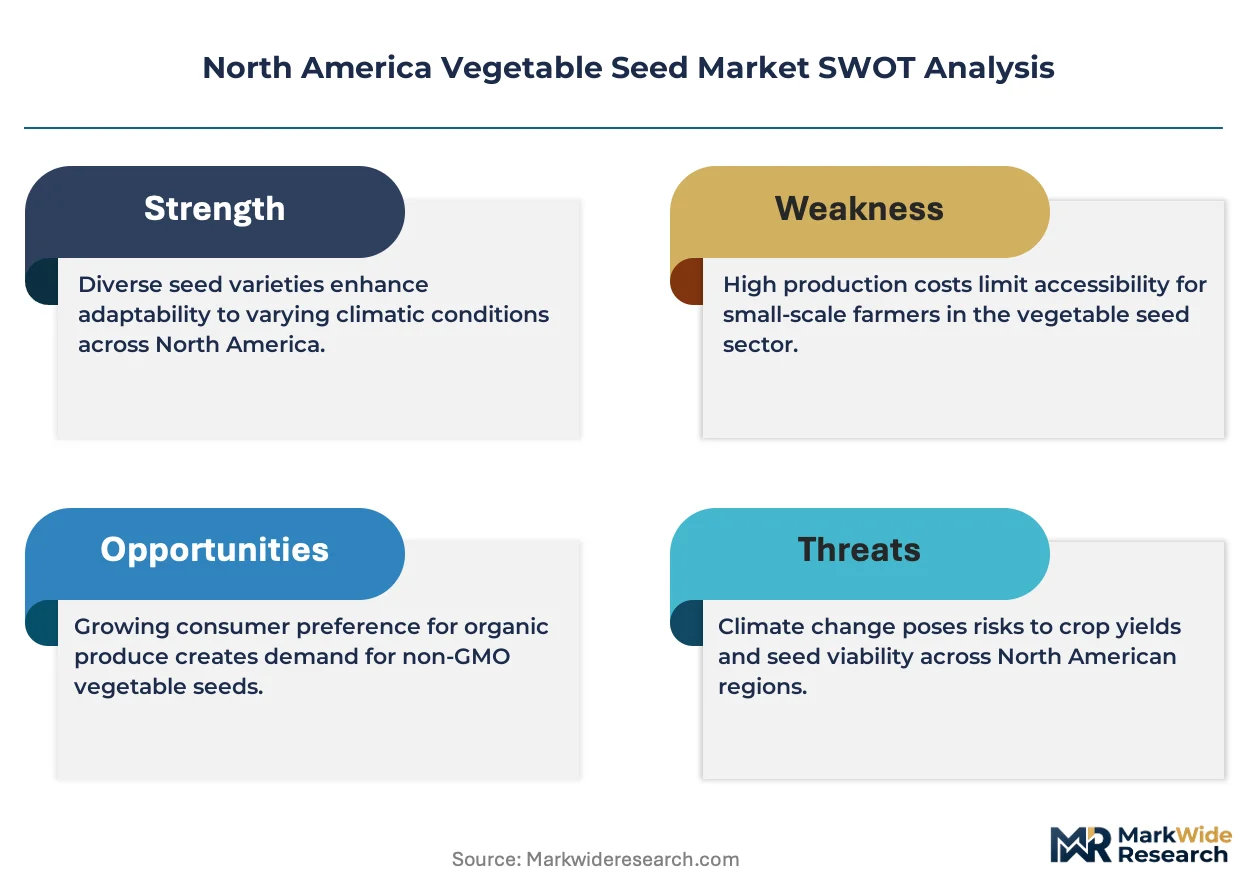
Gene-editing platforms like CRISPR-Cas9 is fragmenting traditional breeding pipelines, allowing smaller programs to develop trait-specific varieties without decade-long backcross cycles. Corteva Agriscience leverages its proprietary gene-editing stack to compress development timelines for disease-resistant tomatoes. Syngenta Group sustains broad germplasm libraries across Solanaceae and Brassicaceae families. Johnny's Selected Seeds differentiates through farmer-participatory breeding programs that prioritize flavor and regional adaptation over yield maximization.
North America vegetable seeds constitute sexually propagated planting material engineered for specific agronomic performance, typically specified by germination rate (minimum 80% for certified lots), genetic purity thresholds, and pathogen indexing standards; their commercial purpose centers on transferring uniform yield potential, pest resistance, and post-harvest shelf stability from breeding stations to field production. Hybrid seed lines capture premium pricing through proprietary parent-line control and first-generation vigor expression, while organic-certified categories expand fastest as supply chains segregate to prevent synthetic input contamination. Open-pollinated varieties retain footholds among home gardeners and preservation networks seeking seed-saving autonomy outside intellectual property restrictions.
The USDA's Plant Variety Protection Office and Canada's Plant Breeders' Rights Office establish parallel exclusivity frameworks that shape R&D investment allocation across the US-Canada border. The EPA regulates pesticidal traits in genetically engineered seeds through residue tolerance setting, while state-level seed certification programs in California, Florida, and Texas enforce field inspection protocols for phytosanitary compliance. Stakeholders must track divergence between US and Canadian organic seed equivalence standards as trade-dependent supply chains face potential border friction from asynchronous rulemaking.
Market Dynamics
Gene-editing platforms are compressing variety development timelines from decade-long backcross cycles to multi-year trait stacking, while regulatory divergence between the USDA National Organic Program and Canada's Organic Regime forces dual-track certification investments across the US-Canada border.
Growth Catalysts
- Protected Cultivation Expansion:Commercial greenhouse operators in California and Ontario are expanding acreage under controlled-environment agriculture, driving demand for compact, high-yielding varieties optimized for vertical production systems.
- USDA National Organic Program:Tightening seed provenance requirements for organic certification are accelerating segregation investments and creating premium price tiers for certified organic planting material.
- Gene-Editing Democratization:CRISPR-Cas9 platforms are fragmenting traditional breeding pipelines, enabling smaller programs to develop trait-specific varieties without proprietary parent-line dependencies.
Market Restraints
- Parent-Line Concentration:Hybrid seed production depends on tightly controlled proprietary inbred lines held by a narrow set of breeders, creating supply vulnerability and royalty stacking.
- Asynchronous Rulemaking:Divergence between US and Canadian organic seed equivalence standards threatens border friction for integrated North American supply chains.
- Phytosanitary Compliance Costs:State-level seed certification programs in California, Florida, and Texas enforce field inspection protocols that escalate operational overhead for multi-state distributors.
Strategic Opportunities
- Great Lakes Corridor Demand:Concentrated vegetable production stretching from Michigan through southwestern Ontario offers geographic clustering advantages for regional variety trialing and localized distribution.
- Farmer-Participatory Breeding:Direct collaboration between seed developers and commercial growers allows flavor-forward and regionally adapted varieties to bypass yield-maximization constraints of centralized R&D.
- Open-Pollinated Autonomy:Home gardener and preservation networks seeking seed-saving independence outside intellectual property restrictions represent a stable niche resistant to hybrid premium erosion.
Industry Challenges
- Genetic Purity Maintenance:Cross-pollination risks in Brassicaceae and Solanaceae production require isolation distances and temporal staggering that complicate multi-crop operations.
- Pathogen Indexing Bottlenecks:Certified lots must meet minimum germination rates and pathogen standards, creating testing queue delays during peak planting windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vegetable Seed Market |
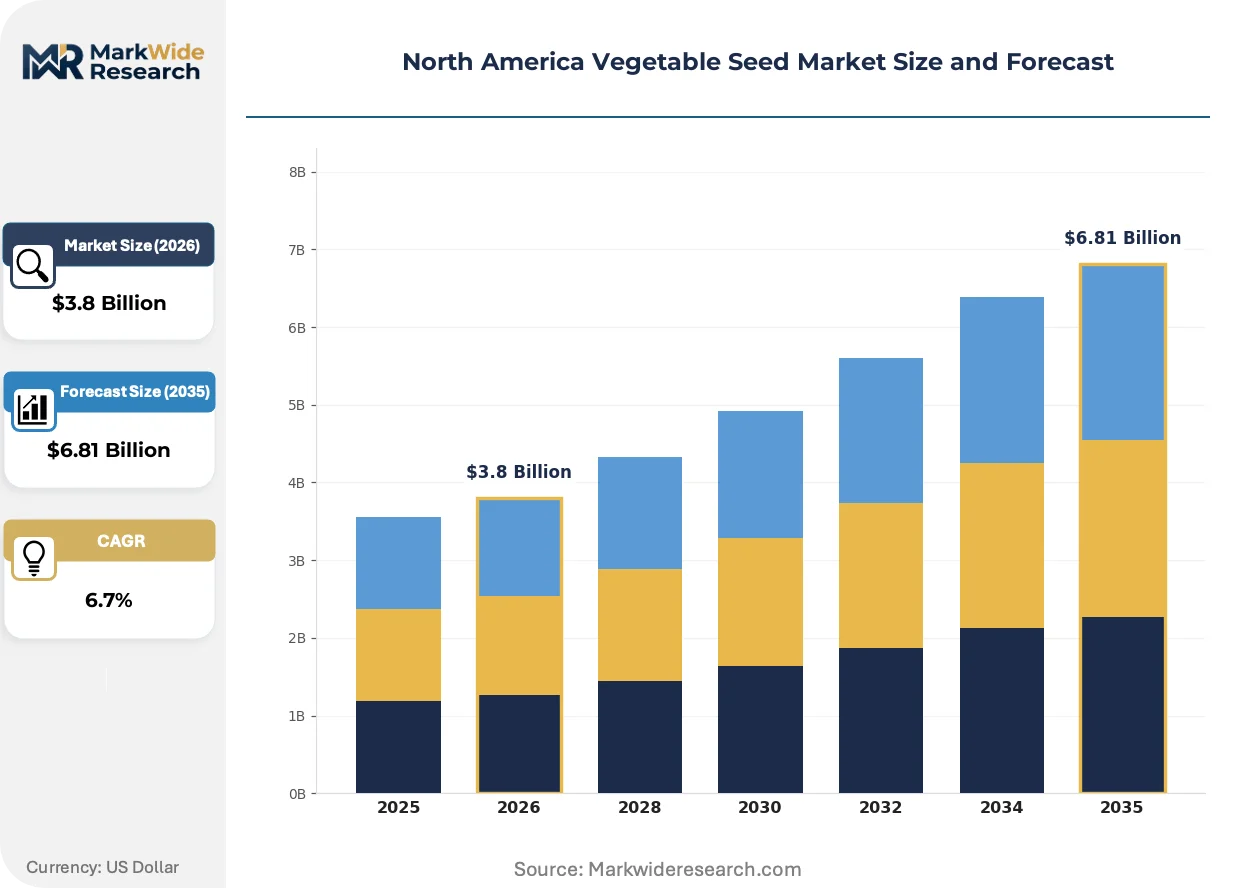
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Open-Pollinated, Organic, GMO End User: Commercial Growers, Home Gardeners, Greenhouses, Agricultural Cooperatives Distribution Channel: Online Retail, Agricultural Supply Stores, Wholesalers, Direct Sales Packaging Type: Bulk Packs, Retail Packs, Seed Tapes, Seed Pellets |
| Companies Covered | Groupe Limagrain, Corteva Agriscience, Syngenta Group, High Mowing Organic Seeds, Johnny's Selected Seeds, Bayer AG, BASF SE, Sakata Seed Corporation, Rijk Zwaan Zaadteelt en Zaadhandel BV, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vegetable Seed Market Evolving Landscape
Biotechnology, regulatory tightening, and buyer fragmentation are simultaneously compressing development cycles and expanding the addressable market for specialized vegetable genetics across North American production zones.
Gene-editing stacks combining multiple disease-resistance traits are hybridizing conventional breeding timelines, allowing trait pyramiding in tomato and pepper lines that previously required sequential backcrossing. Protected cultivation operators in Ontario and California are adopting these varieties at accelerated rates. The technology is hybridizing competitive positioning between established breeders with germplasm libraries and agile entrants with platform-based development.
The EPA's residue tolerance setting for pesticidal traits in genetically engineered seeds is tightening data submission requirements for novel trait introductions. This regulatory compression extends development timelines for stacked-trait varieties targeting conventional production. Organic-certified categories face parallel pressure from the USDA National Organic Program's seed provenance documentation mandates, forcing supply chain segregation investments most acute in California's Central Valley operations.
Direct-to-grower seed procurement is displacing traditional distributor intermediation among mid-scale vegetable operations seeking variety trial support and technical agronomy. Johnny's Selected Seeds and similar participatory breeding programs are capturing this channel shift through farmer-collaborative development models. The behavioral pivot is most visible across the Great Lakes corridor, where Michigan and Ontario growers prioritize regional adaptation data over standardized performance metrics.
North America Vegetable Seed Market Segmentation
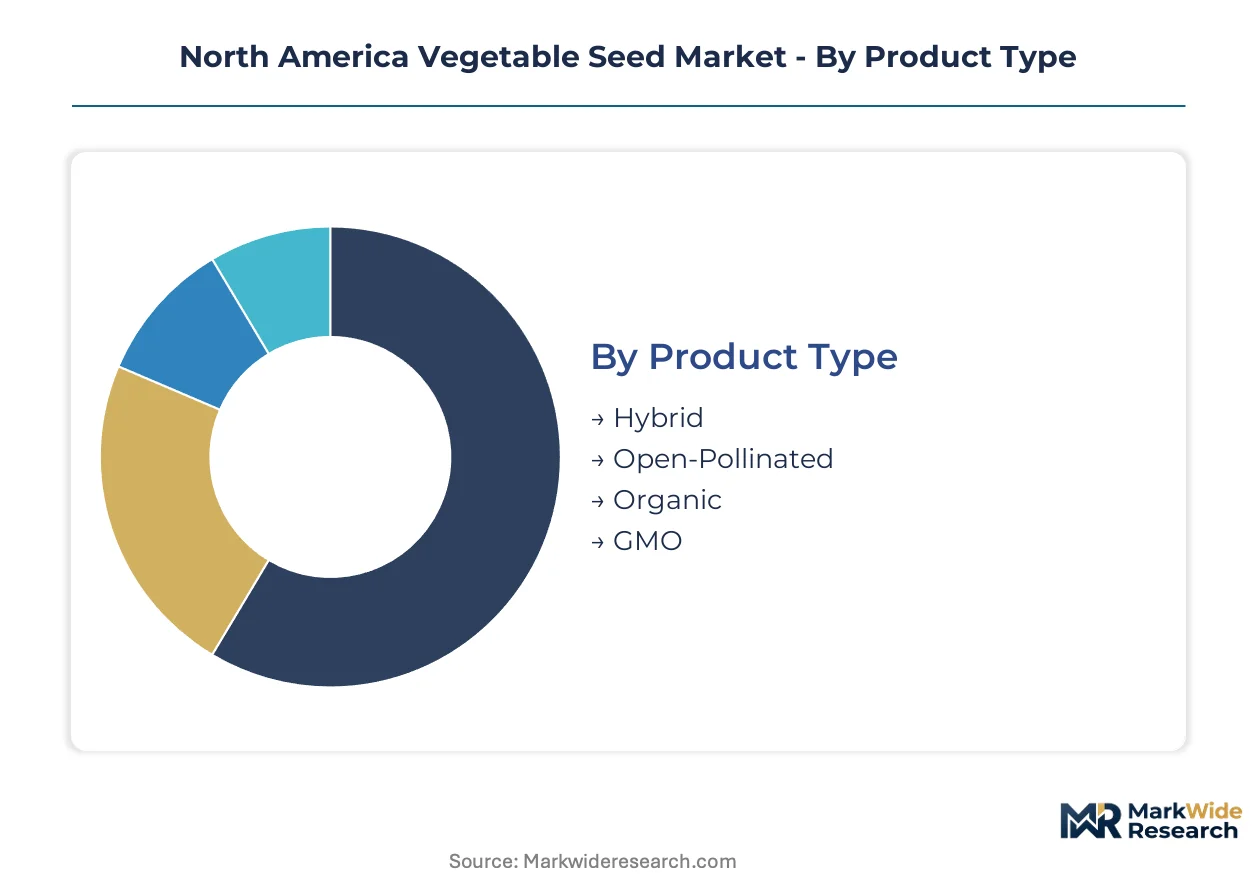
Segmentation in the North America vegetable seed market reveals divergent commercial logics across breeding technology, customer scale, and supply chain configuration. Each dimension carries distinct margin profiles, regulatory exposure, and vulnerability to gene-editing disruption.
Product Type:
Mature hybrid platforms dominate revenue concentration while emerging organic and gene-edited categories reshape competitive entry points.
- Hybrid:Proprietary parent-line control enables first-generation vigor expression and premium pricing tiers. Demand concentrates among California and Ontario greenhouse operators seeking uniform germination rates above 85% and disease-stacked trait packages.
- Open-Pollinated:Seed-saving autonomy preserves genetic diversity outside intellectual property restrictions. Michigan and Ontario preservation networks and home gardener cooperatives drive regional trialing programs prioritizing flavor over yield maximization.
- Organic:USDA National Organic Program and Canada's Organic Regime documentation mandates force supply chain segregation investments.
- GMO:EPA residue tolerance requirements for pesticidal traits extend development timelines for stacked-trait introductions.
Hybrid handles the majority of throughput; organic is the fastest mover on share.
End User:
Customer scale determines price elasticity, technical service requirements, and susceptibility to direct-to-grower channel displacement.
- Commercial Growers:Mid-scale operations across the Great Lakes corridor are bypassing traditional distributors for farmer-participatory breeding programs with regional adaptation data. Technical agronomy support and variety trial infrastructure determine supplier selection.
- Greenhouses:Controlled-environment operators in California and Ontario demand compact, high-yielding varieties optimized for vertical production systems and automated harvesting compatibility.
- Home Gardeners:Seed-saving networks and flavor-forward preservationists sustain open-pollinated demand outside hybrid premium structures.
- Agricultural Cooperatives:Volume aggregation enables negotiated parent-line access and shared phytosanitary compliance costs across member operations.
Commercial growers command the largest absolute volume; greenhouses are expanding most quickly.
Distribution Channel:
Channel structure reflects customer scale fragmentation and the erosion of traditional intermediary control.
- Agricultural Supply Stores:Counter-based technical consultation and immediate availability sustain relevance for time-constrained planting windows. California, Florida, and Texas state certification programs elevate compliance overhead for multi-state retail networks.
- Direct Sales:Breeder-to-grower relationships displace distributor margins among operations seeking participatory breeding collaboration and localized performance data.
- Online Retail:Home gardener and small-scale producer convenience purchasing accelerates SKU proliferation and inventory complexity.
- Wholesalers:Bulk consolidation functions persist for cooperatives and large-scale operations with standardized variety requirements.
Agricultural supply stores maintain the deepest penetration; direct sales are gaining share fastest.
Packaging Type:
Packaging configuration aligns with operational scale, planting precision requirements, and labor cost structures.
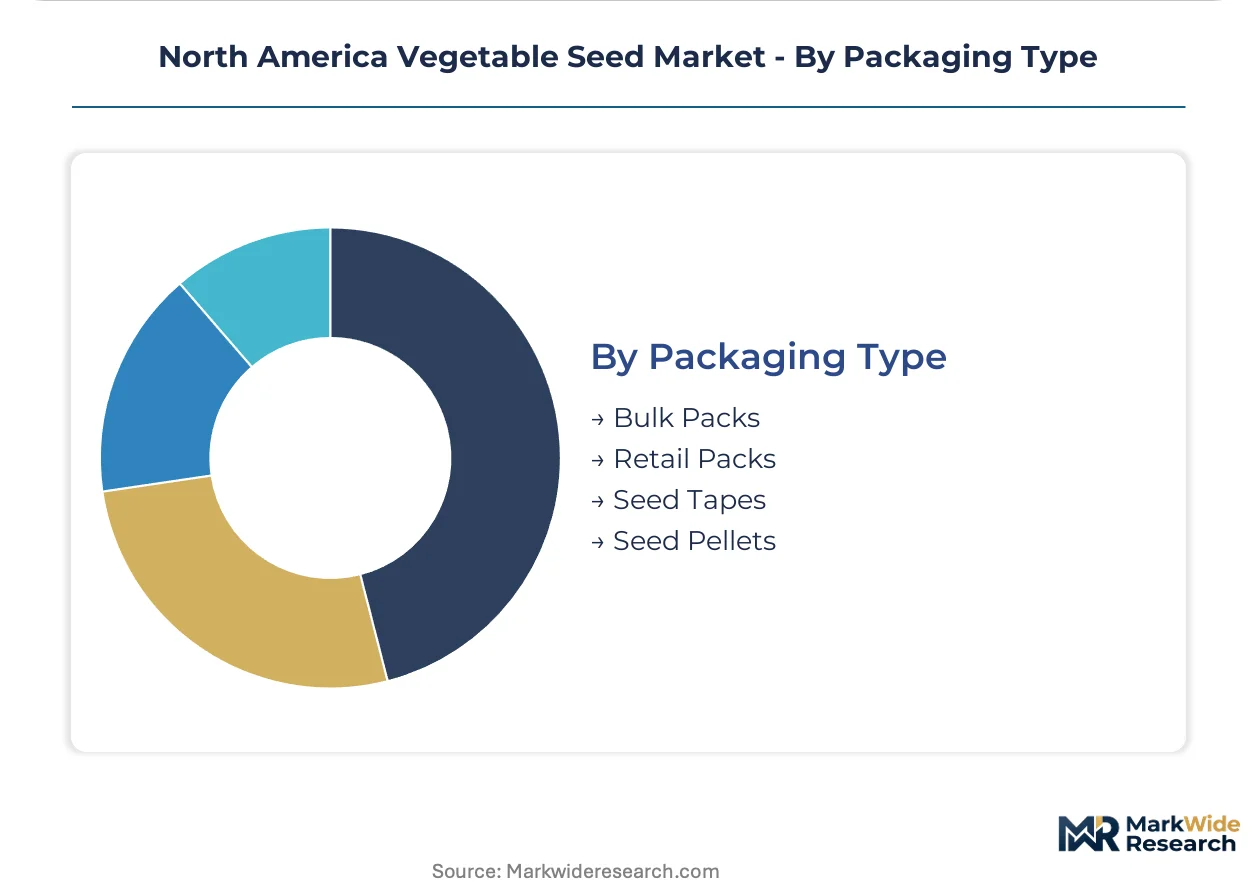
- Bulk Packs:Large-scale commercial operations and cooperatives minimize per-unit packaging costs for standardized variety deployment across extensive acreage.
- Retail Packs:Consumer-facing unit sizes with germination rate labeling and cultivar provenance documentation satisfy home gardener regulatory awareness.
- Seed Tapes:Pre-spaced embedding reduces thinning labor for precision-planted crops in high-wage production zones.
- Seed Pellets:Uniform sizing enables mechanical singulation and flowability for automated greenhouse seeding equipment.
Bulk packs handle the majority of commercial throughput; seed pellets are climbing the fastest among protected cultivation operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial greenhouse operators and organic-certified growers concentrate demand across distinct North American production corridors, with regulatory divergence between US and Canadian organic regimes shaping cross-border supply chain configuration.
United States
California's Central Valley greenhouse operators drive demand for compact, disease-stacked tomato and pepper varieties optimized for vertical production systems. The USDA National Organic Program's tightening seed provenance documentation mandates force segregation investments across certified operations. Michigan's Great Lakes corridor hosts regional variety trialing programs that prioritize flavor-forward selection over yield maximization metrics.
Canada
Southwestern Ontario's controlled-environment agriculture sector expands acreage under protected cultivation, sourcing germplasm optimized for automated harvesting compatibility. Canada's Organic Regime maintains equivalence negotiations with USDA standards, creating potential border friction for integrated North American supply chains. The Quebec-Ontario corridor concentrates farmer-participatory breeding collaborations that emphasize regional climate adaptation.
Mexico
Baja California and Sinaloa's export-oriented vegetable operations generate demand for hybrid varieties with uniform germination rates and extended post-harvest shelf stability. Mexico's national seed certification authority enforces phytosanitary field inspection protocols that align with US import requirements for cross-border planting material movement. The Bajío region's emerging greenhouse cluster adopts compact varieties designed for high-density production systems.
North America Vegetable Seed Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressures concentrate around proprietary parent-line control and germplasm library depth, while fragmentation persists among regional participatory breeding programs. Three archetypes dominate: multinational agrochemical conglomerates with integrated seed platforms, specialized vegetable breeding houses with family-owned germplasm legacies, and farmer-collaborative seed developers prioritizing flavor and regional adaptation. Dominant competitive moves include gene-editing technology licensing to compress variety development timelines and strategic partnerships with protected cultivation operators for variety trialing infrastructure.
Among the multinational tier, Bayer AG and BASF SE exemplify integrated agrochemical-seed platforms with broad germplasm libraries spanning Solanaceae and Brassicaceae families. Corteva Agriscience occupies a distinct position through proprietary gene-editing stacks that enable disease-resistance trait compression without decade-long backcross cycles. Within the participatory breeding segment, Johnny's Selected Seeds represents farmer-collaborative development models that capture direct-to-grower channel shifts across the Great Lakes corridor.
| Leading Market Players |
|---|
| Groupe Limagrain |
| Corteva Agriscience |
| Syngenta Group |
| High Mowing Organic Seeds |
| Johnny's Selected Seeds |
| Bayer AG |
| BASF SE |
| Sakata Seed Corporation |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Others |
Value Network & Pricing Analysis
Parent-line concentration among Dutch and Japanese germplasm holders funnels margin capture toward proprietary hybrid developers while compressing royalty-stacked tiers downstream. Cost-plus contracts with breeder indexation clauses lock input volatility into distributor markups across California and Ontario procurement networks.
Pricing Analysis
Cost-plus breeder contracts indexed to field production inputs dominate commercial transactions, with USDA organic certification tier and germplasm licensing intensity as the primary price differentiation drivers. Pricing pressure stems from gene-editing platform proliferation eroding decade-long backcross premium structures. Commercial greenhouse operators in Ontario exhibit lowest price sensitivity due to automation compatibility requirements, while Michigan mid-scale growers prioritize regional adaptation data over standardized performance tiers.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities anchor working capital structures for distributors serving the Great Lakes corridor. Germplasm development concentrates in the Netherlands, Japan, and the United States, with production-phase labor and phytosanitary certification costs drawing from Mexico and Central America. Single-source vulnerability in proprietary inbred lines threatens continuity, while distribution runs through agricultural supply stores with direct-sales channel displacement accelerating among participatory breeding programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in CRISPR platform access and farmer-collaborative trialing infrastructure concentrates strategic leverage among holders of gene-editing stacks and regional adaptation datasets.
For Market Incumbents: Pre-empt gene-editing platform fragmentation by licensing trait-stacking capabilities to mid-tier breeders before participatory programs achieve comparable development velocity. Defend germplasm library value through exclusive protected-cultivation trialing partnerships in California and Ontario greenhouse clusters. Prioritize backward integration into phytosanitary certification infrastructure to offset state-level compliance cost escalation. For New Entrants and Emerging Players: Pursue open-pollinated variety development for preservation networks and home gardener cooperatives across Michigan and southwestern Ontario, where intellectual property independence commands stable niche pricing. White-space concentration sits in farmer-participatory breeding programs delivering flavor-forward regional adaptation data. Go-to-market execution through direct-to-grower technical agronomy support bypasses distributor margin capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty seed houses holding Solanaceae and Brassicaceae germplasm legacies but lacking gene-editing integration. Long-term viability hinges on trait-stacking capability acquisition or platform licensing within the coming consolidation window. Watch for USDA-Canada organic equivalence negotiation outcomes as cross-border supply chain reconfiguration signal.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Editing Platform Licensing | Trait-stacking partnerships compress development timelines for disease-resistant tomato and pepper lines. |
| Protected Cultivation Trialing Infrastructure | California and Ontario greenhouse partnerships validate compact varieties for vertical production systems. |
| Backward Integration into Phytosanitary Certification | In-house field inspection capabilities reduce state-level compliance overhead for multi-state distributors. |
| Farmer-Participatory Breeding Program Expansion | Direct grower collaboration captures channel shift across Great Lakes corridor mid-scale operations. |
| Organic Supply Chain Segregation Investment | USDA National Organic Program documentation mandates force certified lot traceability infrastructure. |
Research Methodology
A spread of perspectives from breeding program directors, greenhouse operations managers, seed certification officials, and agricultural supply distributors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against USDA germplasm registration data, EPA residue tolerance filings, state seed certification program records, and customs trade documentation for cross-border planting material movement. Bottom-up variety-level demand estimates and top-down sectoral revenue benchmarks were triangulated to anchor projections.
Demand-supply balance modeling across the projection horizon segmented the market by breeding technology platform, customer scale tier, and distribution channel configuration. CAGRs were derived from trajectory fitting to historical adoption curves for gene-edited and organic-certified categories, with protected cultivation acreage expansion and regulatory divergence between US and Canadian organic regimes as key forecast inputs.
Sensitivities concentrate around gene-editing regulatory reclassification, organic equivalence standard alignment, and parent-line supply disruption scenarios. Forecasts reflect documented assumptions regarding breeder R&D allocation and greenhouse operator variety adoption patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Bangladesh Seed Market
Seeds
Canary Seeds Market
Seeds
Global Grain Seed Market
Seeds
Ghana Seeds Market
Seeds
North America Forage Seed Market
Seeds
Australia Forage Seed Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Global Soybean Seed Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
India Seed Market
Seeds
United States Garden Seeds Market
Seeds
North America Chia Seeds Market
Seeds
Avena Sativa Market
Seeds
Global Sorghum Seed Market