
 Organic Chia Seeds Market | 2026-2036
Organic Chia Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Chia Seeds Market Analytics
Flaxseed meal is expanding its replacement by organic chia seeds in gluten-free bakery formulations due to superior omega-3 stability and neutral flavor profiles. The Chia Co. leverages vertical integration from Australian farmland to retail shelf, securing traceability premiums. Navitas Organics sustains its position through certified organic and fair-trade supply chains in South American growing regions. Nutiva Inc. anchors North American distribution through deep channel partnerships with natural grocery networks.
Organic chia seeds are the edible seeds of Salvia hispanica, containing approximately 18% protein, 34% dietary fiber, and 17% omega-3 alpha-linolenic acid by weight, with the hydrophilic capacity to absorb twelve times their weight in water for gel-forming applications in food systems. Black chia seeds dominate bulk commodity flows due to established harvesting infrastructure, while sprouted chia seeds command premium positioning among raw-food consumers seeking enhanced bioavailability. The food and beverage application segment channels the majority of volume through plant-based dairy alternatives and energy bar inclusions, whereas nutraceuticals extract higher per-kilogram value through encapsulated omega-3 concentrates.
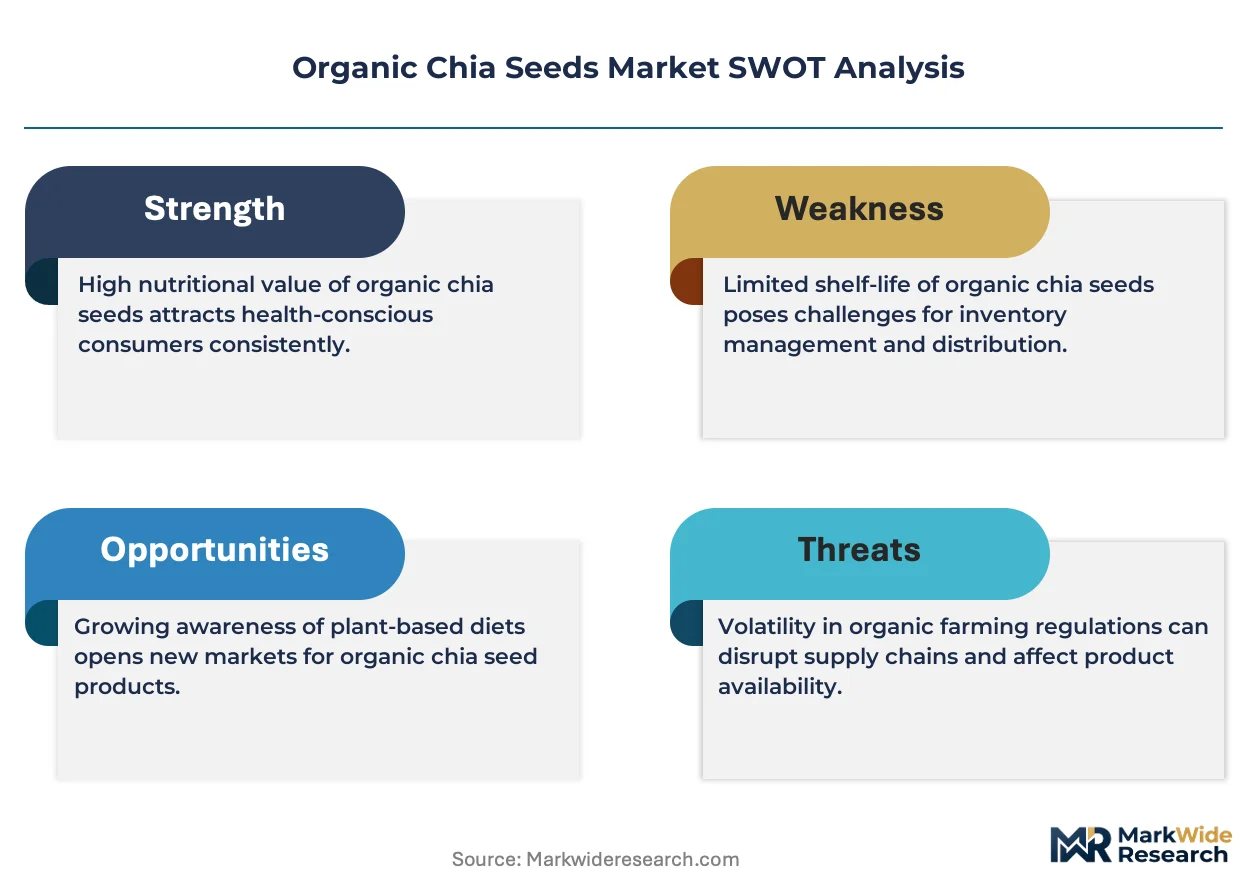
The USDA National Organic Program and EU Organic Regulation 2018/848 govern certification standards that determine market access for imported chia seeds into North American and European retail channels. FDA GRAS status and EFSA novel food evaluations shape ingredient permissibility for expanded food applications beyond traditional uses. Stakeholders must monitor evolving organic equivalency agreements between major producing nations and consuming regions to anticipate supply chain reconfigurations.
Market Dynamics
Clean-label certification requirements are compressing supplier margins while concentrating procurement power among vertically integrated organic handlers capable of maintaining USDA National Organic Program and EU Organic Regulation 2018/848 traceability across South American origin points.
Growth Catalysts
- EU Organic Regulation 2018/848:Harmonized certification standards across member states reduce border friction for Argentine and Bolivian exporters, expanding retail shelf access for imported organic chia.
- Plant-based dairy alternatives:Formulators in oat and almond milk categories substitute chia gel for hydrocolloid stabilizers, creating volume pull from beverage manufacturing.
- Sprouted seed processing:Raw-food consumers in California and New York metropolitan clusters absorb premium-priced sprouted chia, validating infrastructure investments in controlled germination systems.
Market Restraints
- Input cost volatility:Organic fertilizer prices and irrigation energy costs in Salta Province, Argentina fluctuate with diesel and natural gas benchmarks, squeezing farm-gate margins.
- Supply concentration risk:Black chia harvesting infrastructure clusters in northwestern Argentina and southern Bolivia, exposing buyers to regional drought or political disruption.
- Substitution threat:Flaxseed meal and hemp hearts compete in omega-3 bakery applications, particularly where price sensitivity dominates purchasing decisions.
Strategic Opportunities
- South Korean functional foods:MFDS novel food approvals for chia remain underutilized relative to domestic demand for digestive health positioning, creating first-mover white space.
- Encapsulated omega-3 concentrates:Nutraceutical extraction technologies enable higher per-kilogram value capture from oil-pressed chia meal, diverting volume from commodity bulk channels.
- Direct-to-consumer subscription:E-commerce platforms bypass conventional natural grocery slotting fees, allowing smaller organic brands to build recurring revenue with traceability storytelling.
Industry Challenges
- Organic equivalency negotiation delays:Bilateral agreements between Argentina and the United States remain incomplete, forcing redundant certification audits and extending time-to-market for new suppliers.
- Controlled atmosphere storage capex:Maintaining omega-3 stability through temperature and humidity management requires capital-intensive warehousing infrastructure that smaller handlers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Chia Seeds Market |
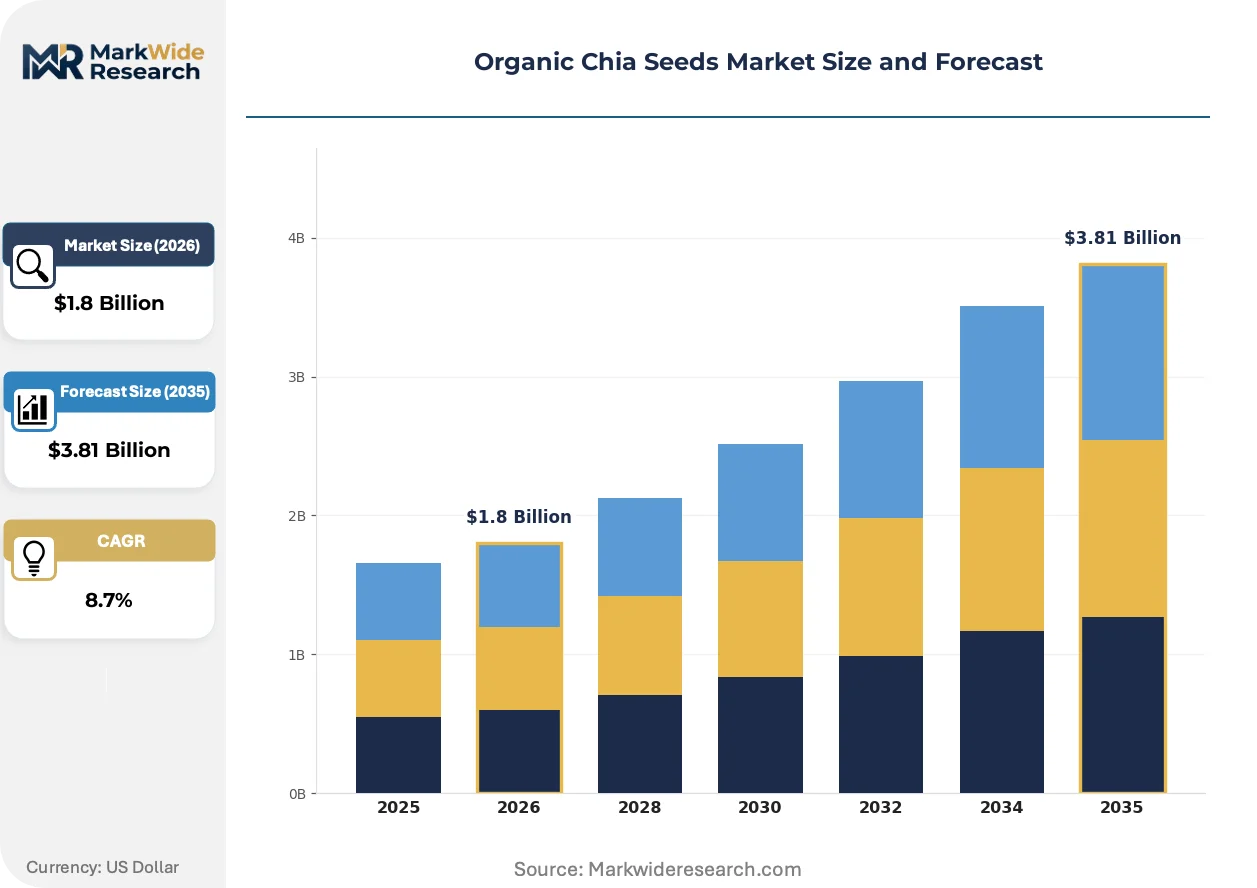
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Chia Seeds, White Chia Seeds, Sprouted Chia Seeds, Ground Chia Seeds Application: Food & Beverage, Nutraceuticals, Personal Care, Animal Feed Distribution Channel: Supermarkets, Health Stores, Online Retail, Wholesale End User: Households, Food Manufacturers, Health Enthusiasts, Fitness Centers |
| Companies Covered | Mamma Chia, The Chia Co., Navitas Organics, amoseeds, Benexia, Nutiva Inc., Salba Smart Natural Products, SunRidge Farms, Garden of Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Chia Seeds Market Evolving Landscape
Blockchain-enabled traceability systems are penetrating organic chia supply chains, driven by retailer demands for farm-level verification that satisfies both consumer transparency expectations and regulatory audit requirements.
Blockchain seed-to-shelf tracking platforms record germination dates, organic input applications, and harvest coordinates on immutable ledgers. Natural grocery chains in Germany and the Netherlands pilot these systems for private-label chia lines. This transparency infrastructure is decentralizing quality verification away from centralized laboratory testing toward distributed farmer-cooperative data entry.
EU Organic Regulation 2018/848 mandates stricter contamination thresholds and enhanced record-keeping for imported organic products entering European retail channels. Compliance costs favor larger exporters with dedicated regulatory affairs staff. Smaller Bolivian cooperatives face consolidation pressure or exclusion from premium market tiers.
Raw-food consumers now prioritize sprouted chia over conventional seeds, perceiving enhanced bioavailability and reduced antinutrient content. Specialty retailers in Los Angeles, London, and Sydney allocate expanded shelf space to sprouted variants. This preference rotation compresses demand for conventional black chia in high-income urban clusters while sustaining commodity flows into processed food manufacturing.
Organic Chia Seeds Market Segmentation
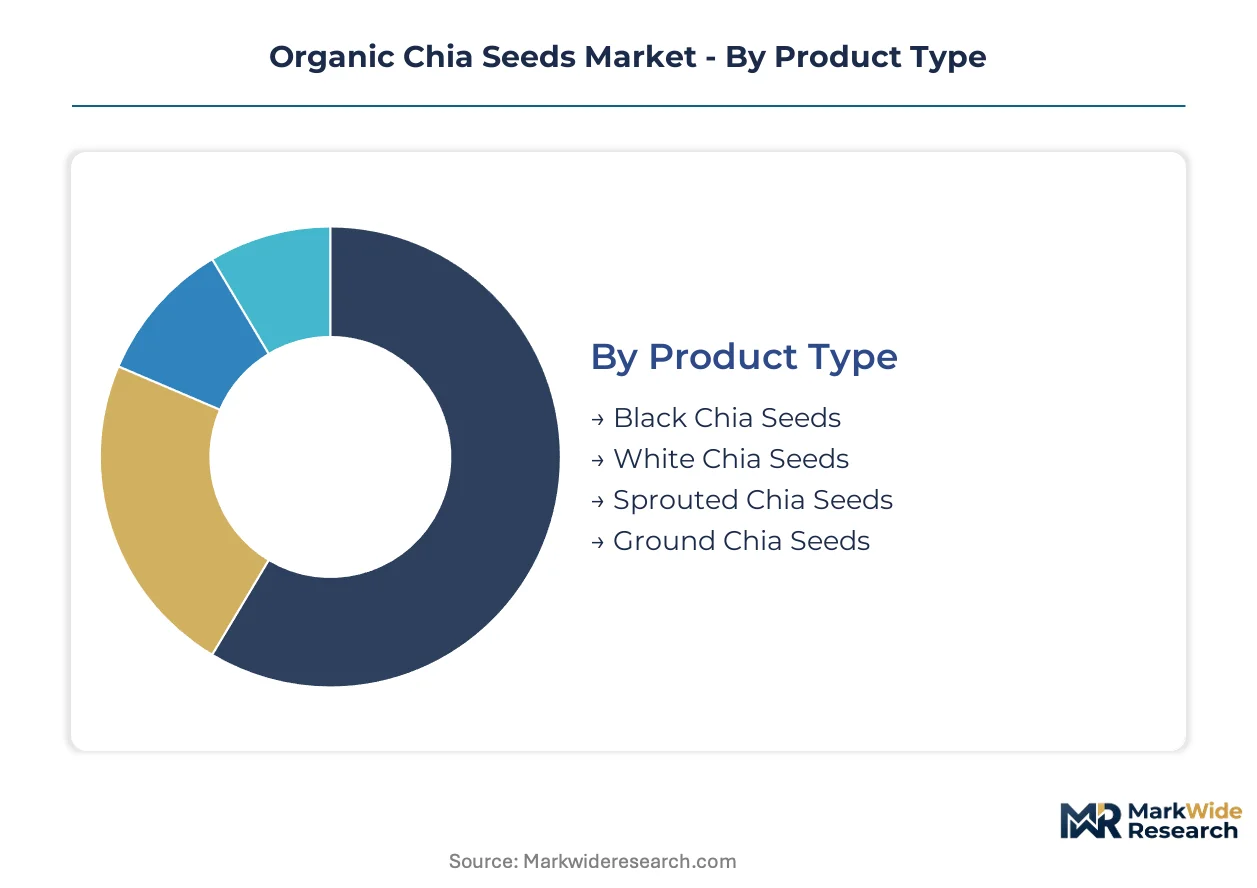
Organic chia seed buyers segment sharply by technical specification tolerance, application processing requirements, and channel access economics. These divisions determine pricing power, certification burden, and supplier relationship structures across the value chain.
Product Type:
Buyers in this category differentiate by color uniformity requirements, bioavailability preferences, and processing convenience thresholds.
- Black Chia Seeds:These seeds contain the full antioxidant profile of the Salvia hispanica plant with dark pigmentation from polyphenol density. Argentine and Bolivian bulk exporters channel the majority of harvest volume into food manufacturing applications where visual uniformity matters less than cost efficiency. Black chia leads volumes today; sprouted variants are gaining share fastest.
- White Chia Seeds:Golden-white coloration commands aesthetic premiums in premium bakery and beverage applications where visible seed inclusion enhances clean-label positioning. Australian growers dominate this niche through selective breeding programs that isolate the recessive color trait. White chia absorbs disproportionate shelf space in Sydney and Los Angeles specialty retail despite representing a minority of planted hectares.
- Sprouted Chia Seeds:Controlled germination reduces phytic acid content and activates enzyme systems for raw-food consumers prioritizing digestibility.
- Ground Chia Seeds:Milled flour format eliminates textural constraints in smoothie and baking applications where whole seed mouthfeel creates formulation barriers.
Black chia dominates planted acreage; sprouted processing commands the steepest price premiums per kilogram.
Application:
End-use concentration varies by omega-3 stability requirements, regulatory pathway complexity, and value-add processing depth.
- Food & Beverage:Plant-based dairy formulators substitute chia gel for carrageenan and xanthan gum in oat and almond milk stabilization. Energy bar manufacturers in California and Colorado embed whole seeds for texture and nutritional density claims. This segment channels the highest absolute tonnage through established GRAS status and familiar ingredient recognition.
- Nutraceuticals:Cold-pressed oil extraction yields alpha-linolenic acid concentrates for encapsulated omega-3 supplements targeting cardiovascular positioning. Per-kilogram value capture exceeds commodity bulk channels by multiples, though volume remains constrained by extraction capacity and clinical substantiation requirements.
- Personal Care:Hydrophilic gel properties drive inclusion in natural cosmetics for hydration and exfoliation formulations.
- Animal Feed:Organic poultry and aquaculture operations incorporate chia meal as an omega-3 enrichment pathway for egg and fillet nutritional claims.
Food and beverage absorbs the majority of raw seed flow; nutraceutical extraction delivers the highest margin realization per unit processed.
Distribution Channel:
Channel selection reflects buyer scale, certification verification needs, and slotting fee tolerance.
- Supermarkets:Conventional grocery chains in Germany and the Netherlands stock private-label organic chia alongside established branded lines, requiring suppliers to absorb promotional fund contributions and quarterly audit costs.
- Health Stores:Independent natural retailers in New York and London metropolitan clusters prioritize sprouted and fair-trade certified variants with traceability storytelling.
- Online Retail:Direct-to-consumer subscription models bypass conventional slotting structures, enabling smaller South American cooperatives to build recurring revenue through blockchain-verified origin narratives.
- Wholesale:Bulk ingredient distributors serve food manufacturers with pallet-scale procurement and specification documentation for USDA National Organic Program compliance.
Supermarkets and wholesale together move the largest tonnage; online retail is expanding most quickly among emerging brand entrants.
End User:
User categories separate by purchase frequency, technical specification knowledge, and price sensitivity gradients.
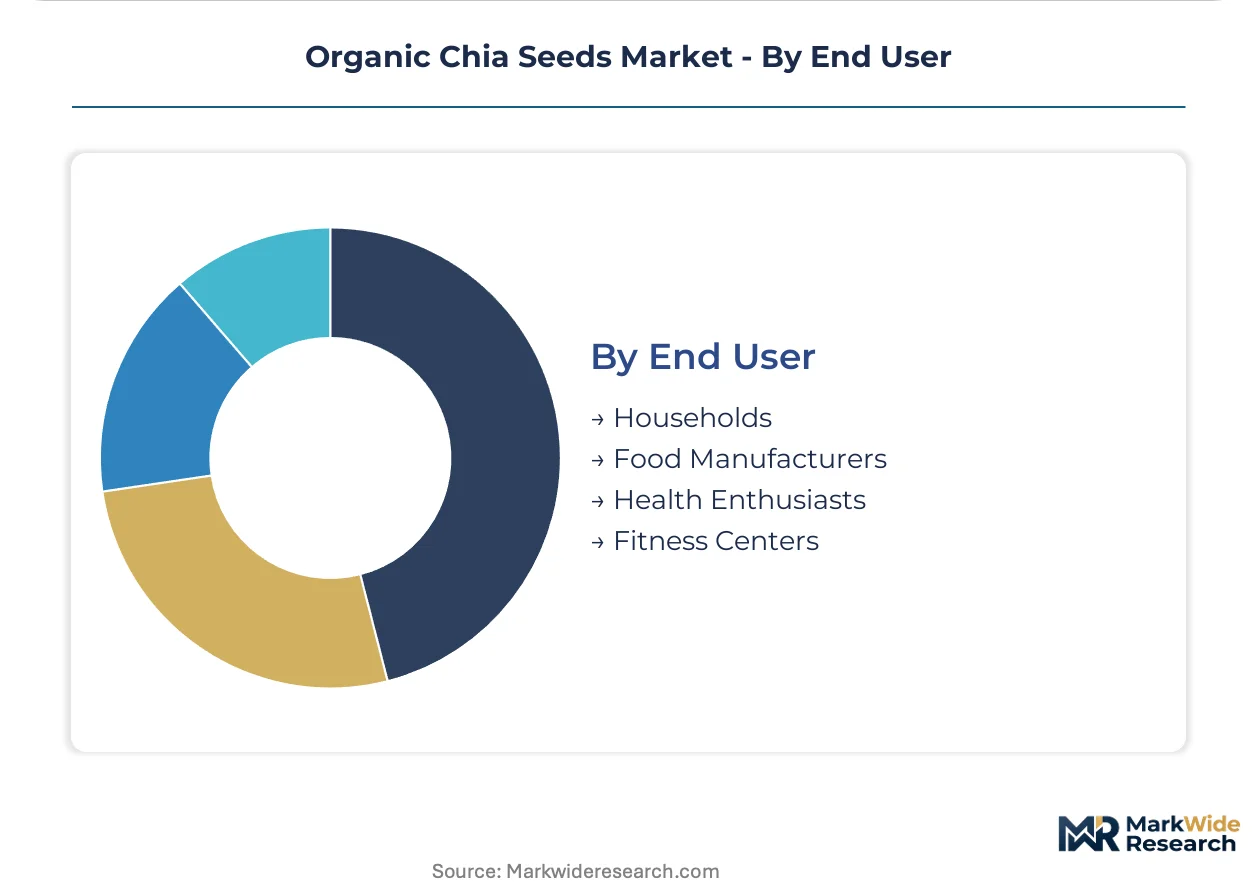
- Households:Individual consumers in high-income urban clusters prioritize convenience formats and origin transparency, driving demand for pre-portioned packets and subscription deliveries.
- Food Manufacturers:Industrial buyers in plant-based dairy and bakery categories enforce strict moisture content and microbial specification windows, consolidating procurement among vertically integrated handlers capable of batch consistency.
- Health Enthusiasts:Biohacking and raw-food communities in California absorb premium-priced sprouted chia through specialty retailers and direct farm relationships.
- Fitness Centers:Gym operators and sports nutrition retailers stock chia as a smoothie bar ingredient for post-workout recovery positioning.
Food manufacturers dominate procurement volume; health enthusiasts drive the fastest expansion in premium-tier product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine farmland in Salta Province anchors the dominant supply base for organic chia cultivation, with harvest infrastructure clustering in northwestern growing regions that channel bulk commodity flows into North American and European retail channels.
United States
California health enthusiasts and New York metropolitan consumers absorb premium-priced sprouted chia through specialty retailers and direct-to-consumer subscription platforms. The USDA National Organic Program governs certification requirements for imported seeds entering domestic retail channels. Los Angeles and San Diego clusters validate infrastructure investments in controlled germination systems for raw-food positioning.
Germany
Natural grocery chains in Berlin and Hamburg pilot blockchain-enabled traceability systems for private-label organic chia lines, satisfying consumer transparency expectations. EU Organic Regulation 2018/848 mandates stricter contamination thresholds and enhanced record-keeping for imported products. German retailers absorb promotional fund contributions and quarterly audit costs from South American suppliers seeking shelf access.
Australia
Selective breeding programs in New South Wales and Victoria isolate the recessive golden-white color trait for aesthetic premiums in premium bakery applications. Australian growers dominate the white chia niche despite representing a minority of planted hectares. Sydney specialty retail allocates disproportionate shelf space to domestically produced white variants.
South Korea
Domestic demand for digestive health positioning in functional foods outpaces MFDS novel food approvals for chia, creating first-mover white space for compliant entrants. Seoul-based formulators seek ingredient permissibility for expanded applications beyond traditional uses. The regulatory gap between demand and approval status concentrates opportunity among early movers.
Netherlands
Rotterdam and Amsterdam serve as distribution hubs for Argentine and Bolivian exports benefiting from harmonized EU certification standards that reduce border friction. Dutch natural grocery chains stock private-label organic chia alongside established branded lines. The country's logistics infrastructure consolidates procurement power among vertically integrated handlers.
Organic Chia Seeds Market Competitive Landscape
Backward integration into farmland and processing infrastructure dominates the current landscape, compressing supplier margins while concentrating procurement power among handlers capable of maintaining USDA and EU traceability across South American origin points. The vendor base stratifies across three archetypes: vertically integrated agricultural operators with captive supply, specialty organic brands leveraging fair-trade certification narratives, and bulk commodity traders serving food manufacturing procurement. M&A activity and capacity expansion in controlled atmosphere storage represent the dominant competitive moves as omega-3 stability requirements intensify capital demands.
Among vertically integrated specialists, The Chia Co. and Navitas Organics occupy positions that exemplify divergent geographic sourcing strategies—Australian farmland control versus South American fair-trade supply chains—while Nutiva Inc. anchors North American distribution archetypes through natural grocery network partnerships. These three entities represent the spectrum from origin-point control to channel-deepening approaches, with each structure reflecting different risk allocations across certification burden, climatic exposure, and consumer premium capture.
| Leading Market Players |
|---|
| Mamma Chia |
| The Chia Co. |
| Navitas Organics |
| amoseeds |
| Benexia |
| Nutiva Inc. |
| Salba Smart Natural Products |
| SunRidge Farms |
| Garden of Life |
| Others |
Value Network & Pricing Analysis
Organic fertilizer and diesel-powered irrigation costs in Salta Province, Argentina feed through farm-gate prices into three distinct buyer tiers: sprouted chia commands premium positioning among raw-food consumers, white chia absorbs aesthetic premiums in Sydney and Los Angeles specialty retail, and black chia flows through commodity bulk channels to food manufacturers.
Pricing Analysis
Input-cost pass-through from Argentine and Bolivian growing regions creates pricing pressure across all tiers, with organic certification audit costs and controlled atmosphere storage investments compressing handler margins. Price differentiation hinges on certification tier—USDA National Organic Program versus EU Organic Regulation 2018/848 equivalence—and volume scale, with pallet-scale food manufacturers extracting steepest discounts while direct-to-consumer subscriptions preserve premium realization. Food manufacturers exhibit highest price sensitivity due to substitution threats from flaxseed meal and hemp hearts; health enthusiasts in California and New York absorb least sensitivity, validating sprouted chia premiums.
Supply Chain Analysis
Direct-to-retail and wholesale distribution channels handle hyperscale buyer demand from German supermarket chains and North American natural grocery networks, with Rotterdam and Amsterdam consolidating Argentine and Bolivian export flows. Geographic supply concentrates in northwestern Argentina, southern Bolivia, and New South Wales, Australia for white chia niche production. Raw material dependencies include organic fertilizer inputs, diesel for harvest mechanization, and temperature-controlled warehousing infrastructure. Single-source vulnerability from drought exposure in Salta Province represents the dominant structural risk, with blockchain-enabled traceability systems emerging as a secondary distribution layer for subscription and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in organic chia rests on two vectors: premium-tier shift toward sprouted and white variants absorbing bioavailability and aesthetic premiums, and cost-down compression through blockchain-enabled traceability reducing redundant certification audit burdens.
For Market Incumbents: Cement backward integration into controlled germination infrastructure in California and New York metropolitan clusters to capture sprouted chia premiums before facility saturation. Deepen channel control through exclusive partnerships with natural grocery networks, defending against emerging direct-to-consumer subscription entrants leveraging blockchain origin storytelling.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route, bypassing conventional slotting fee structures that favor established handlers. Target South Korean functional foods as the underpenetrated geography, where MFDS novel food approval gaps concentrate first-mover opportunity among compliant entrants with digestive health positioning expertise.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale South American cooperatives with established USDA and EU organic certification because regulatory compliance costs favor consolidation, excluding smaller Bolivian handlers from premium market tiers. Watch bilateral organic equivalency negotiations between Argentina and the United States as the inflection signal—completion would eliminate redundant audits and accelerate supplier onboarding velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Germination Facility Investment | Captures sprouted chia premiums in Los Angeles and New York raw-food clusters. |
| Blockchain Traceability Platform Deployment | Satisfies German retailer demands for farm-level verification and audit compliance. |
| MFDS Novel Food Approval Pursuit | Unlocks South Korean functional foods demand ahead of competitor regulatory compliance. |
| EU Organic Equivalency Certification | Reduces border friction for Argentine exports into Rotterdam and Amsterdam distribution hubs. |
| Direct-to-Consumer Subscription Launch | Bypasses natural grocery slotting fees through recurring revenue with origin storytelling. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining interviews with organic certification auditors, South American farm cooperative managers, natural grocery category buyers, and nutraceutical extraction facility operators. Secondary validation draws from USDA National Organic Program filings, EU Organic Regulation 2018/848 compliance databases, MFDS novel food submission records, and customs trade flow data. Bottom-up acreage and harvest yield estimates triangulate against top-down retail channel volume absorption across supermarkets, health stores, and online retail.
Rate-of-change decomposition separates volume expansion from value realization across product type (black, white, sprouted, ground), application (food and beverage, nutraceuticals, personal care, animal feed), and distribution channel dimensions. CAGRs derive from segmented growth trajectory modeling with cross-validation against input cost elasticity and substitution threat parameters. Industry-specific forecast inputs include organic fertilizer price indices and controlled atmosphere storage capacity buildout rates.
The model assumes a particular technology adoption path for blockchain-enabled traceability; alternative pathways for distributed ledger verification would alter the outlook for smaller cooperative market access. Forecasts reflect assumptions around regulatory equivalency negotiation timelines and drought frequency in northwestern Argentina. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Africa Vegetable Seed Market
Seeds
Africa Sorghum Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Flower Seed Market
Seeds
Carrot Seed Oil Market
Seeds
China Rice Seed Market
Seeds
Australia Forage Seed Market
Seeds
Myanmar Maize Seed Market
Seeds
North America Grain Seed Market
Seeds
Pasture Seeds Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Chamomile Seeds Market
Seeds
United States Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
Sesame Seeds Market
Seeds
Vietnam Vegetable Seed Market