
 Europe Silage Inoculant Market | 2026-2036
Europe Silage Inoculant Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Silage Inoculant Market Foresight
Multi-source procurement of microbial strains is restructuring supply dynamics across the European silage inoculant sector. Chr. Hansen Holdings leverages its culture collection depth to dominate high-performance bacterial formulations for dairy applications. Alltech, Inc. competes through yeast-based additive integration that broadens functional claims beyond standard fermentation aids. Volac International Limited anchors its position in the British Isles through specialized technical advisory services bundled with product supply.
Silage inoculants comprise applied microbial cultures, primarily lactic acid bacteria such as Lactobacillus plantarum and Pediococcus species, that accelerate pH reduction in chopped forage to preserve nutritional value and inhibit spoilage organisms. Liquid inoculants lead volume deployment due to ease of tank-mixing and uniform spray application across large-scale harvest operations, though concentrated formulations gain traction among forage producers seeking reduced freight costs and extended shelf stability. Dry and granular variants occupy niche positions where on-farm storage constraints or equipment compatibility limit aqueous handling.
The European Food Safety Authority and national regulators under EU Feed Hygiene Regulation 183/2005 enforce additive authorization and labeling standards that filter non-compliant suppliers from commercial channels. REACH and the EU Green Deal's sustainability benchmarks further shape formulation chemistry and packaging material specifications. Stakeholders must monitor evolving strain registration pathways and carbon accounting requirements that will determine which product architectures retain market access.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing formulation timelines as producers race to certify bacterial strains under tightening feed quality standards before 2030 sustainability benchmarks lock in.
Growth Catalysts
- EU Green Deal mandates:The Farm to Fork strategy tightens feed hygiene requirements, forcing dairy operations toward certified inoculant formulations that guarantee fermentation stability and reduce dry matter losses.
- Intensive dairy expansion:Large-scale operations across the Netherlands and Belgium are standardizing inoculant protocols to meet cooperative procurement specifications and achieve batch-to-batch silage consistency.
- Multi-strain formulations:Advances in Lactobacillus plantarum and Pediococcus compatibility are enabling broader pH reduction windows that accommodate variable harvest moisture conditions.
Market Restraints
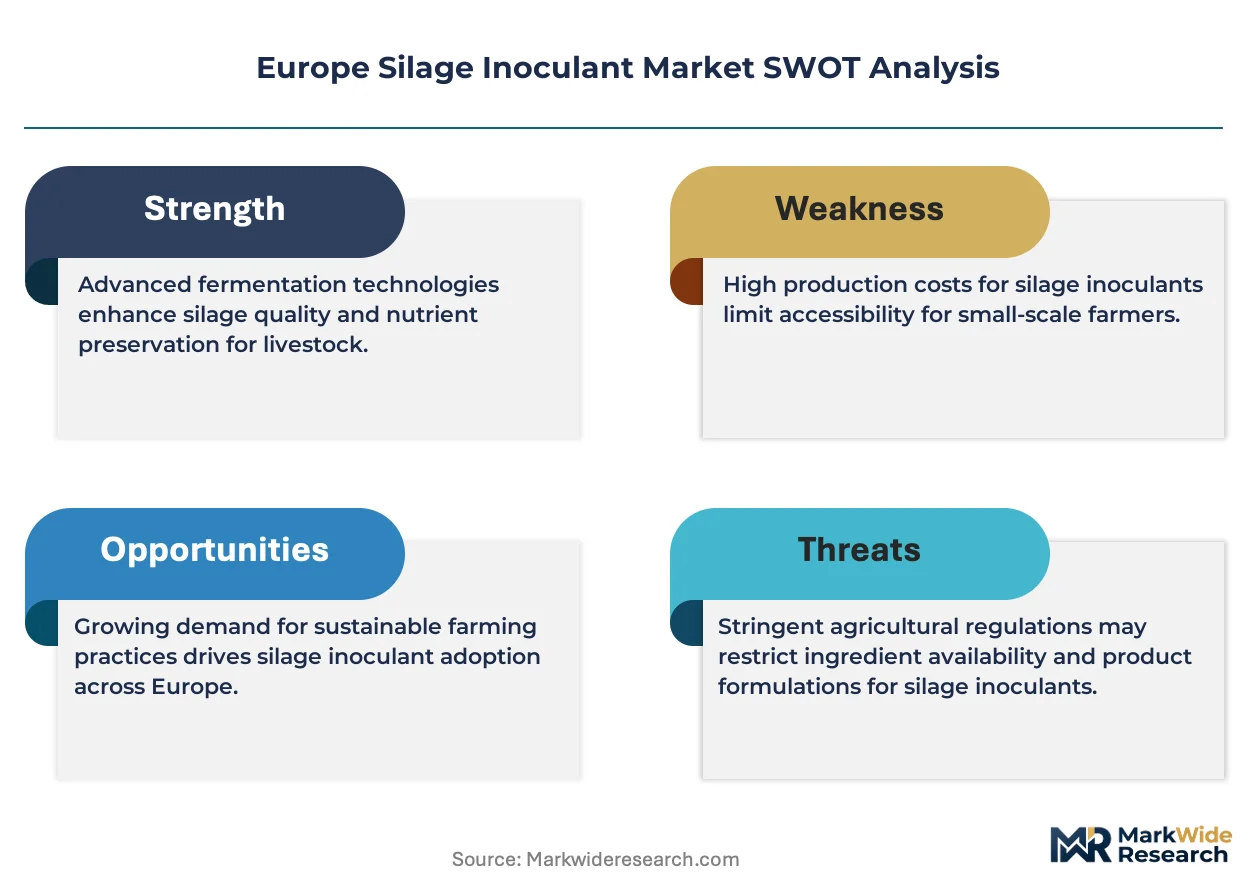
- Strain registration costs:EFSA authorization pathways under EU Feed Hygiene Regulation 183/2005 impose multi-year timelines and substantial dossier preparation expenses that filter smaller suppliers from commercial channels.
- Freight cost volatility:Concentrated liquid formulations face margin pressure from fuel price swings affecting tank-mix distribution across dispersed dairy regions.
- Yeast additive substitution:Alltech and comparable suppliers promote yeast-based alternatives that broaden functional claims beyond fermentation aids, capturing budget-conscious forage producers.
Strategic Opportunities
- Eastern European penetration:Poland and Romania dairy sectors remain underpenetrated relative to Benelux intensity, offering volume expansion for technical advisory bundled with product supply.
- Carbon accounting integration:The EU Green Deal's sustainability benchmarks reward documented dry matter loss reduction, creating premium positioning for inoculants with verified environmental performance data.
- Concentrated dry formats:Extended shelf stability and reduced freight costs are electrifying interest among remote forage producers in Scandinavia where aqueous handling logistics prove prohibitive.
Industry Challenges
- Microbiologist talent scarcity:Strain characterization and fermentation optimization require specialized expertise that outpaces agricultural university pipeline output across Germany and France.
- REACH compliance complexity:Chemical substance registration requirements for formulation additives create documentation burdens that delay product iteration cycles.
- Equipment compatibility gaps:Granular inoculant variants face adoption friction where existing spray infrastructure dominates harvest operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Silage Inoculant Market |
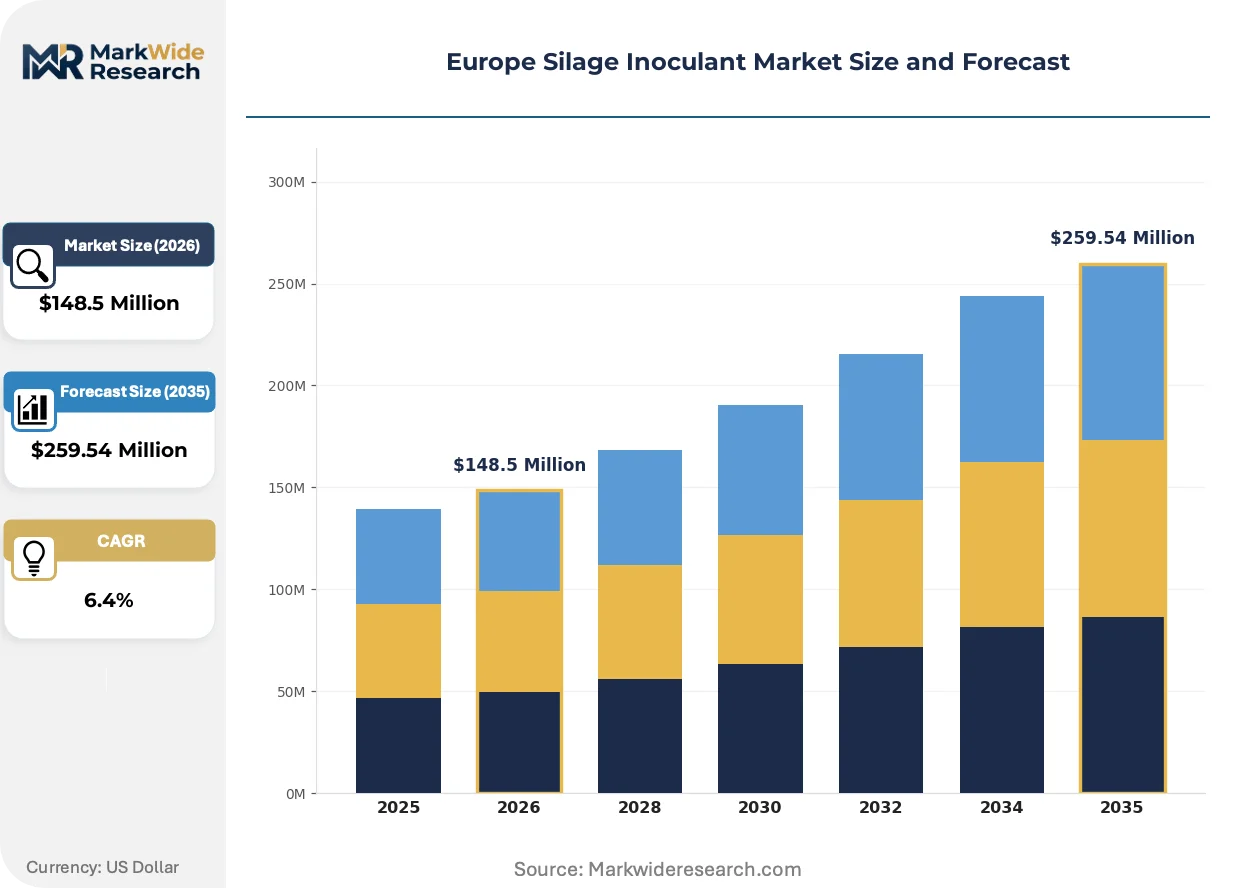
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $259.54 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Inoculants, Dry Inoculants, Granular Inoculants, Concentrated Inoculants End User: Dairy Farms, Beef Cattle Farms, Forage Producers, Agricultural Cooperatives Formulation: Bacterial, Enzymatic, Chemical, Mixed Strains Packaging Type: Packets, Bottles, Drums, Bags |
| Companies Covered | Chr. Hansen Holdings, Alltech, Inc., Cargill Inc., Volac International Limited, Kemin Industries, Archer Daniels Midland Company, Nutreco NV, Novonesis, Lallemand Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Silage Inoculant Market Shifts & Advancements
Formulation chemistry and application technology are converging to address the tension between fermentation performance and sustainability documentation requirements. Three developments are restructuring competitive positioning.
Multi-strain bacterial cocktails incorporating Lactobacillus buchneri for aerobic stability are electrifying product architecture in high-moisture forage segments. German dairy cooperatives are adopting these formulations at accelerated rates to meet processor specifications for extended bunk life. The technology is electrifying premium tier separation as suppliers compete on strain exclusivity rather than commodity fermentation aid positioning.
REACH and the EU Green Deal's packaging material specifications are forcing reformulation of carrier substrates and container compositions. Industrial consequence includes accelerated R&D spend on biodegradable film technologies and concentrated dry formats that reduce plastic intensity. Dairy operations in Denmark and Sweden are responding fastest, prioritizing suppliers with verified circular economy credentials in procurement scoring.
Cooperative purchasing structures in the Benelux region are consolidating procurement decisions at central technical committees rather than individual farm level. This concentrates volume with suppliers offering integrated advisory services and digital fermentation monitoring tools. The shift is most visible in the Netherlands, where Rabobank-linked dairy operations standardize inoculant specifications across member farms to achieve collective feed cost optimization.
Europe Silage Inoculant Market Segmentation
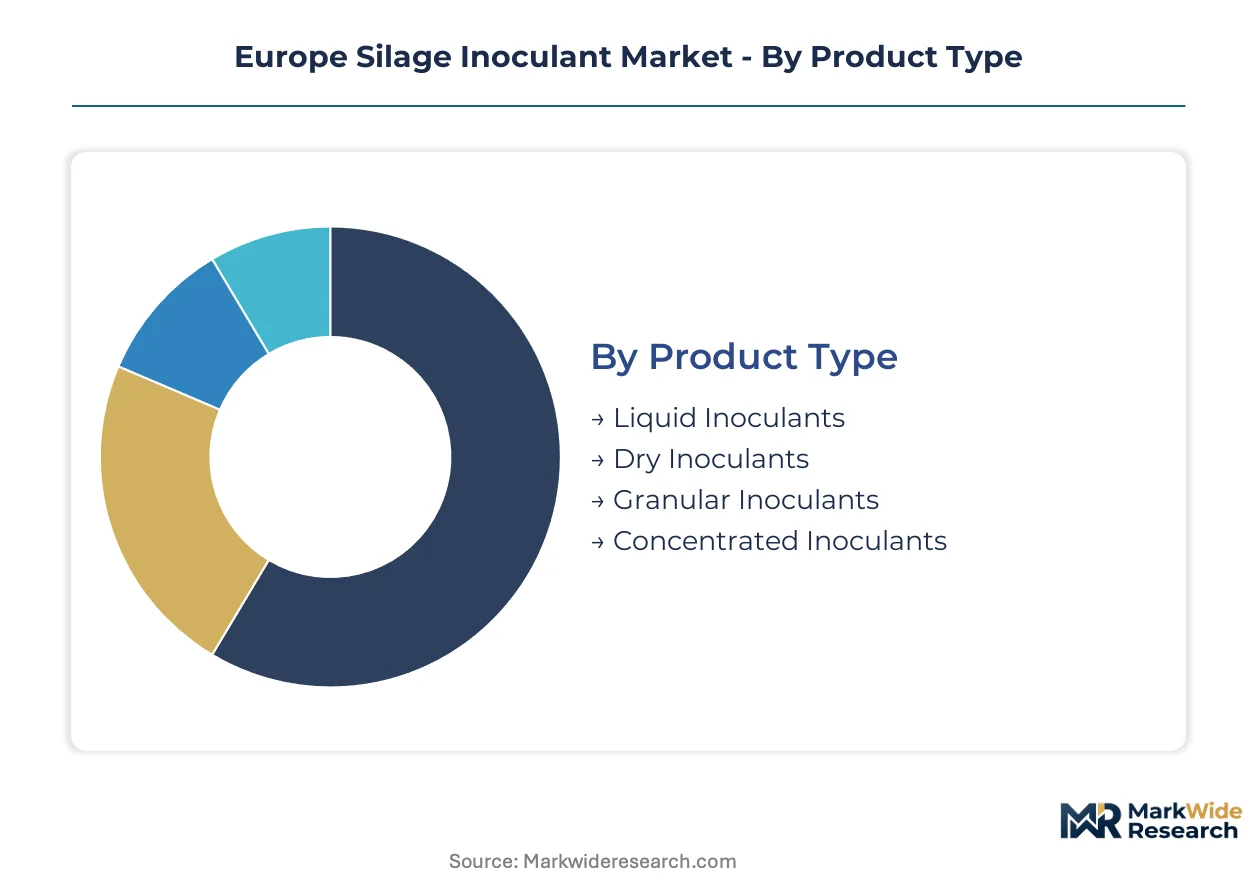
Silage inoculant procurement patterns across Europe diverge sharply between intensive dairy cooperatives and dispersed beef operations. Product architecture, formulation chemistry, and packaging logistics must align with distinct harvest scales, equipment infrastructure, and regulatory compliance requirements that vary by end-use segment.
Product Type:
Application equipment compatibility and freight economics separate buyers across these four delivery formats.
- Liquid Inoculants:Aqueous suspensions of lactic acid bacteria designed for tank-mixing and uniform spray application across large-scale harvest operations. Demand concentrates in the Netherlands and Belgium, where cooperative purchasing structures standardize liquid protocols across member farms to achieve batch-to-batch silage consistency.
- Dry Inoculants:Freeze-dried or desiccated bacterial preparations offering extended shelf stability and reduced storage constraints. Scandinavian forage producers favor these formats where remote locations and prohibitive aqueous handling logistics dominate procurement decisions.
- Granular Inoculants:Solid particulate carriers for direct application or integration into dry fertilizer spreaders. Equipment compatibility gaps limit adoption where existing spray infrastructure dominates harvest operations.
- Concentrated Inoculants:High-potency formulations requiring dilution prior to application, reducing freight costs and plastic intensity per treated ton.
Volume sits with Liquid Inoculants; growth tilts toward Concentrated Inoculants.
End User:
Operational scale and feed cost sensitivity determine formulation specifications and advisory service bundling.
- Dairy Farms:Operations prioritizing fermentation stability and dry matter loss reduction to meet processor milk quality specifications. German and French dairy cooperatives are expanding inoculant use to satisfy EU Green Deal Farm to Fork feed hygiene requirements.
- Beef Cattle Farms:Backgrounding and finishing operations with lower per-animal feed investment tolerance. Polish and Romanian beef sectors remain underpenetrated relative to Benelux dairy intensity.
- Forage Producers:Specialized contractors harvesting and ensiling feed for third-party livestock operations. Carbon accounting integration creates premium positioning for suppliers with verified environmental performance data.
- Agricultural Cooperatives:Centralized procurement bodies consolidating technical specifications across member farms. Rabobank-linked Dutch operations standardize inoculant choices to achieve collective feed cost optimization.
Revenue concentrates with Dairy Farms; expansion is steepest among Agricultural Cooperatives.
Formulation:
Functional claims and EFSA authorization status drive differentiation between biological and chemical approaches.
- Bacterial:Live cultures of Lactobacillus plantarum, Pediococcus species, and Lactobacillus buchneri accelerating pH reduction and aerobic stability. Multi-strain compatibility advances are broadening pH reduction windows for variable harvest moisture conditions.
- Enzymatic:Cellulase and hemicellulase additives targeting fiber digestibility improvement alongside fermentation aids. EFSA authorization pathways under EU Feed Hygiene Regulation 183/2005 impose multi-year timelines that filter smaller suppliers.
- Chemical:Acid-based preservatives including propionic and formic acid derivatives. REACH compliance complexity for chemical substance registration creates documentation burdens delaying product iteration cycles.
- Mixed Strains:Combinations of bacterial and enzymatic agents or bacterial-chemical hybrids. German dairy cooperatives are adopting these at accelerated rates to meet extended bunk life specifications.
Share clusters in Bacterial formulations; Mixed Strains are climbing the fastest.
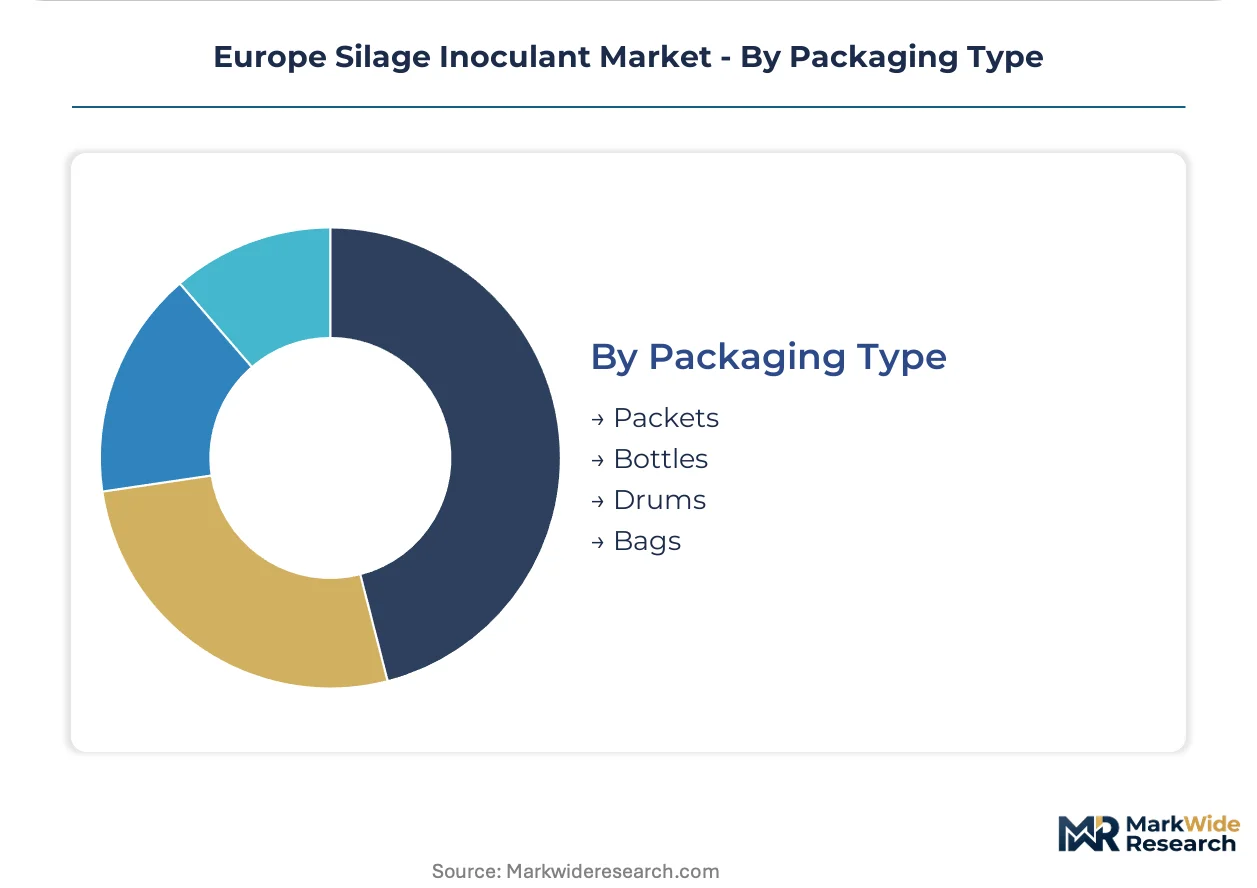
Packaging Type:
EU Green Deal packaging material specifications and circular economy credentials increasingly determine supplier selection.
- Packets:Single-use sachets for small-scale or trial applications. Denmark and Sweden prioritize suppliers with verified biodegradable film technologies in procurement scoring.
- Bottles:Rigid containers for liquid formulations with calibrated dosing mechanisms. Standard equipment across Benelux intensive operations.
- Drums:Intermediate bulk containers for cooperative-level volume procurement. Reduced plastic intensity per liter of active product aligns with sustainability benchmarks.
- Bags:Flexible packaging for dry and granular formats. Extended shelf stability requirements favor multi-layer barrier constructions.
Procurement weight rests with Drums; sustainability-driven conversion favors Packets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maize and grass silage production across the North European Plain anchors demand concentration for bacterial inoculant formulations. Dairy cooperative density and EFSA regulatory enforcement intensity create divergent procurement patterns across national markets.
Germany
Large-scale dairy operations in Lower Saxony and Bavaria are standardizing multi-strain inoculant protocols to meet processor milk quality specifications. EFSA authorization pathways under EU Feed Hygiene Regulation 183/2005 filter non-compliant suppliers from commercial channels. The Münsterland dairy cluster is consolidating procurement through cooperative technical committees that prioritize fermentation stability documentation.
Netherlands
Rabobank-linked dairy cooperatives are centralizing inoculant specifications across member farms to achieve collective feed cost optimization. REACH compliance requirements for formulation additives create documentation burdens that delay product iteration cycles. The Gelderland intensive livestock zone is adopting liquid inoculant protocols at scale to satisfy EU Green Deal Farm to Fork sustainability benchmarks.
France
Expanding dairy farms in Brittany and Normandy are integrating inoculant use to reduce dry matter losses and improve fermentation stability. The EU Green Deal's carbon accounting integration rewards documented environmental performance data from verified suppliers. The Brittany dairy basin is electrifying interest in concentrated dry formats where remote locations complicate aqueous handling logistics.
Poland
Dairy sector modernization in Masovia and Greater Poland is creating volume expansion opportunities for technical advisory bundled with product supply. National feed hygiene enforcement under EU alignment programs is tightening additive authorization standards. The Łódź agricultural belt remains underpenetrated relative to Benelux intensity, offering growth vectors for bacterial formulation suppliers.
Denmark
Cooperative purchasing structures are prioritizing suppliers with verified circular economy credentials and biodegradable packaging technologies. EU Green Deal packaging material specifications are forcing reformulation of carrier substrates and container compositions. The Jutland dairy heartland is responding fastest to sustainability-driven procurement scoring that rewards reduced plastic intensity per treated ton.
Europe Silage Inoculant Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers race to secure strain exclusivity and advisory service bundling. The vendor base concentrates around three tiers: culture collection specialists with deep bacterial strain libraries, diversified nutrition companies integrating inoculants into broader feed additive portfolios, and regional technical service providers anchoring local market penetration. Dominant competitive moves include M&A activity targeting microbiologist talent pools and geographic expansion into Eastern European dairy sectors.
Within the culture collection specialist tier, Chr. Hansen Holdings and Novonesis exemplify players leveraging fermentation science depth to secure premium positioning. Among diversified nutrition conglomerates, Cargill Inc. and Archer Daniels Midland Company occupy positions where inoculant offerings integrate into comprehensive feed solution portfolios. Volac International Limited represents the technical advisory archetype, bundling specialized services with product supply to anchor market presence in the British Isles and adjacent regions.
| Leading Market Players |
|---|
| Chr. Hansen Holdings |
| Alltech, Inc. |
| Cargill Inc. |
| Volac International Limited |
| Kemin Industries |
| Archer Daniels Midland Company |
| Nutreco NV |
| Novonesis |
| Lallemand Inc. |
| Others |
Supply & Pricing Matrix
Microbiologist talent scarcity in Lower Saxony and Bavaria widens pricing-tier spreads as specialized fermentation expertise commands premium compensation that filters into bacterial formulation costs. Labor-cost differentials between German technical centers and Eastern European agricultural universities force suppliers to stratify advisory service bundling across premium and economy product lines.
Pricing Analysis
Technical advisory bundling separates premium bacterial formulations from unbundled commodity inoculants, with Chr. Hansen and Novonesis commanding price premiums for strain exclusivity and on-farm fermentation monitoring. Certification grade under EU Feed Hygiene Regulation 183/2005 and volume scale through cooperative procurement drive price differentiation. Cost compression in standard fermentation aids is intensifying because yeast-based additive substitution from Alltech captures budget-conscious Polish and Romanian producers. Beef cattle farms exhibit highest price sensitivity; agricultural cooperatives in the Netherlands and Belgium demonstrate lowest sensitivity due to collective feed cost optimization frameworks.
Supply Chain Analysis
Microbiologist pipeline constraints in Germany, France, and Denmark concentrate high-performance bacterial strain development in established culture collection centers. Raw material dependencies center on specialized growth media, cryoprotectant carriers, and biodegradable film substrates for EU Green Deal-compliant packaging. Single-source vulnerability in Lactobacillus plantarum master seed stocks creates supply chain risk for multi-strain formulation suppliers. Distribution runs through cooperative technical committees in the Benelux region and Rabobank-linked procurement networks, consolidating volume decisions away from individual farm level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EFSA authorization pathways under EU Feed Hygiene Regulation 183/2005 erect multi-year barriers that filter non-compliant suppliers and protect incumbent margins.
For Market Incumbents: Extend strain exclusivity agreements with German and Dutch dairy cooperatives to lock out emerging bacterial formulation competitors. Build captive supply of Lactobacillus buchneri aerobic stability cultures through backward integration into specialized fermentation capacity, neutralizing yeast-based substitution threats from diversified nutrition conglomerates. For New Entrants and Emerging Players: The premium-to-economy price gap in bacterial formulations opens viable entry space in Polish and Romanian dairy sectors where technical advisory bundling remains underdeveloped. Target Masovia and Greater Poland for volume expansion through advisory-service-led penetration, leveraging EU alignment program enforcement gaps before full EFSA compliance mandates tighten. For Investors and Strategic Acquirers: The window for entry favors culture collection specialists with deep Lactobacillus plantarum libraries and established EFSA dossier expertise. Watch for microbiologist talent migration signals from agricultural universities into commercial strain development as inflection indicators of competitive intensity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Registration Acceleration | EFSA authorization speed determines market access timing under tightening Farm to Fork benchmarks. |
| Technical Advisory Bundling | On-farm fermentation monitoring integration locks cooperative procurement decisions in the Netherlands. |
| Biodegradable Packaging Transition | EU Green Deal material specifications force carrier substrate reformulation for Denmark and Sweden buyers. |
| Eastern European Expansion | Poland and Romania dairy modernization creates volume growth for advisory-integrated suppliers. |
| Carbon Accounting Integration | Verified dry matter loss documentation commands premium positioning under sustainability procurement scoring. |
Research Methodology
EFSA additive authorization databases, EU Feed Hygiene Regulation 183/2005 compliance filings, and national agricultural statistics formed the secondary backbone for this analysis. Primary interviews with dairy cooperative technical directors, bacterial strain procurement managers at feed additive distributors, microbiology R&D leads, and farm advisory service providers combined with secondary validation. Bottom-up farm-level inoculant adoption estimates triangulated against top-down supplier shipment data across the European Union.
Historical trendline analysis of bacterial formulation adoption rates, cooperative procurement consolidation patterns, and EFSA authorization timelines anchored the projection framework. Segmentation modeling incorporated product type, end-user operational scale, formulation chemistry, and packaging material specifications across the analysis window. CAGRs derived from curve-fitting approaches applied to dairy farm expansion trajectories and EU Green Deal implementation phases, with strain registration pipeline velocity and REACH compliance cost burdens as key forecast inputs.
Underlying measurement precision varies by segment; liquid inoculant volume estimates carry tighter precision than granular format projections due to cooperative procurement transparency. Forecasts reflect assumptions about EFSA enforcement intensity and EU Green Deal sustainability benchmark timing. Material deviation in Farm to Fork implementation schedules or REACH chemical substance registration delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
India Feed Enzymes Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Humic-Based Biostimulants Market