
 Specialty Pesticides Market | 2026-2036
Specialty Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Pesticides Market Analytics
ISO 17025 accreditation for analytical testing is bifurcating the competitive landscape into laboratories that can certify residue compliance and those that cannot. Bayer AG leverages its integrated crop science platform to sustain R&D pipelines across multiple modes of action. Syngenta Group anchors its position through proprietary seed treatment formulations that bundle chemical and biological actives. BASF SE differentiates via selective herbicide portfolios tailored to resistance management protocols.
Specialty pesticides comprise formulated chemical or biological agents designed for targeted pest, weed, or disease control in high-value or niche agricultural systems, typically requiring application rates below one kilogram per hectare for ultra-low-volume chemistries. These products function primarily to protect yield quality and crop safety margins in intensive horticulture, permanent cropping, and seed production where commodity broad-spectrum solutions underperform. Herbicides dominate value contribution in row-crop specialty applications where resistance pressures mandate rotational chemistry, while biopesticides represent the fastest-expanding formulation class as residue thresholds tighten across import-sensitive supply chains. Liquid formulations capture disproportionate margin pools in precision application systems, whereas wettable powders retain cost advantages in smallholder-accessible segments across South Asia and Sub-Saharan Africa.
The EPA governs residue tolerance setting and product registration timelines in the United States, while REACH and the EU Green Deal impose substance hazard reclassification and sustainable use reduction targets across European member states. Brazil's ANVISA and the national environmental regulator coordinate concurrent toxicological and ecotoxicological reviews that lengthen market entry cycles but elevate product safety benchmarks. Stakeholders must monitor evolving MRL harmonization between export destination markets and domestic production zones to anticipate portfolio obsolescence risks and reposition active ingredient investments accordingly.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing residue tolerance windows and forcing active ingredient portfolios toward biological alternatives faster than reformulation cycles can accommodate.
Growth Catalysts
- Precision Application Hardware:Drone-mounted electrostatic sprayers are decomposing traditional ground-based application economics in Brazil's Mato Grosso soybean belt.
- REACH Substance Reclassification:ECHA's hazard category upgrades for organophosphates are redirecting R&D investment toward microbial fermentation platforms.
- Seed Treatment Bundling:Proprietary biological-chemical coating technologies are capturing margin pools previously lost to generic post-emergent sprays.
Market Restraints
- Active Ingredient Concentration:Chinese manufacturers control 70% of technical-grade pyrethroid and neonicotinoid supply, creating geopolitical exposure.
- Ecotoxicological Review Cycles:ANVISA's concurrent toxicological and environmental assessments extend Brazilian registration timelines beyond patent protection windows.
- Biological Efficacy Variability:Temperature-sensitive microbial formulations underperform in India's monsoon humidity, limiting substitution rates.
Strategic Opportunities
- Sub-Saharan Smallholder Access:Wettable powder sachet distribution through Kenya's agro-dealer networks addresses ultra-low-volume chemistry gaps.
- Carbon Credit Integration:Biological pesticide application protocols are qualifying for EU ETS-linked agricultural carbon removal certifications.
- Gene Editing Convergence:CRISPR-modified biocontrol strains paired with RNA interference sprays are opening resistance-proof modality combinations.
Industry Challenges
- Formulation Chemist Scarcity:The intersection of microbial physiology and adjuvant chemistry requires hybrid expertise absent from standard agricultural science curricula.
- ISO 17025 Accreditation Burden:Residue testing laboratories face 18-month certification cycles that outpace MRL harmonization updates between export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Pesticides Market |
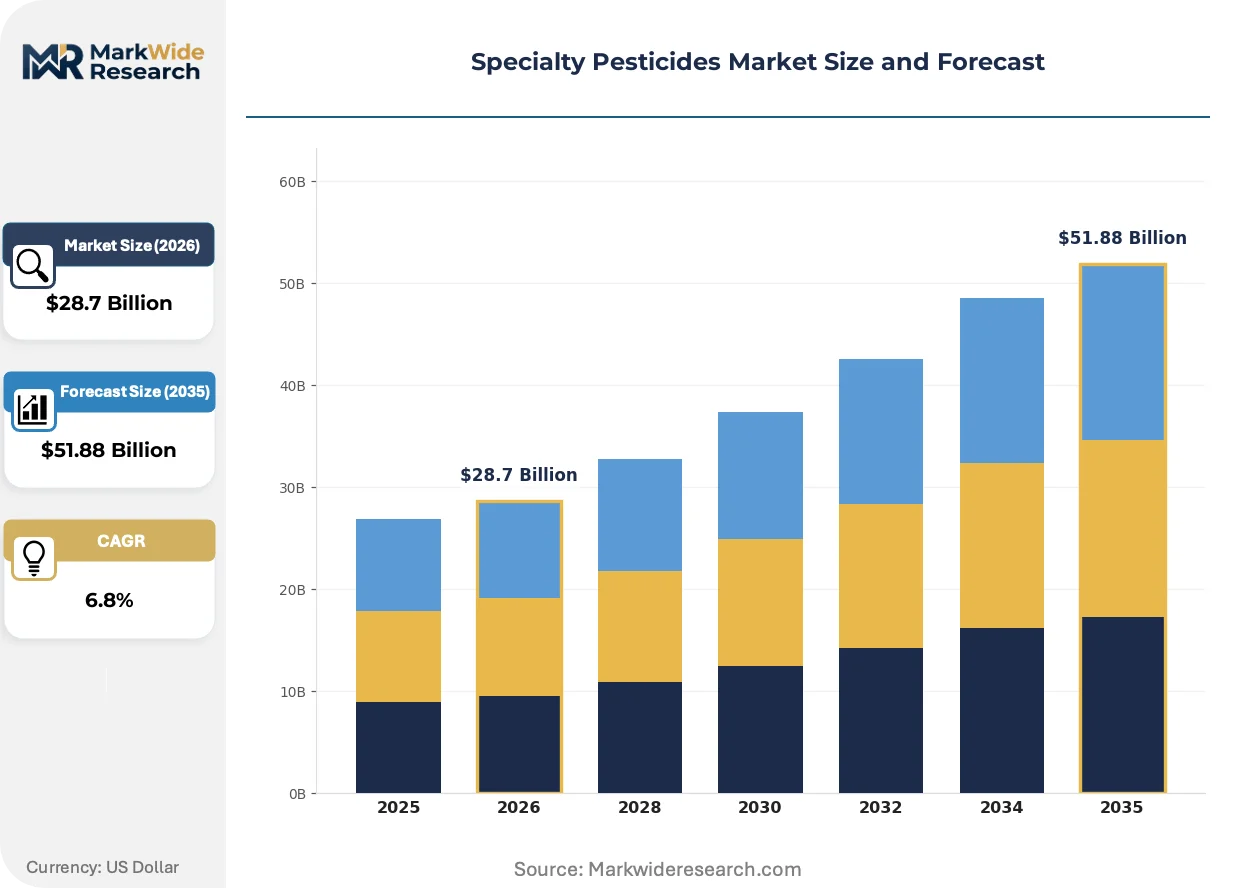
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Herbicides, Fungicides, Biopesticides Formulation: Granules, Liquids, Wettable Powders, Emulsifiable Concentrates Application Method: Foliar Spray, Soil Treatment, Seed Treatment, Drip Irrigation End User: Agricultural Producers, Horticulturists, Turf Managers, Home Gardeners |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, Corteva Agriscience, FMC Corporation, ADAMA Ltd., Nufarm Limited, UPL Limited, Sumitomo Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Pesticides Market Evolving Landscape
Formulation science is pivoting from chemical stability optimization toward biological viability preservation as residue thresholds tighten across import-sensitive supply chains.
RNA interference spray technology is decomposing conventional mode-of-action resistance management protocols. Greenhouse vegetable producers in the Netherlands and Spain are piloting dsRNA formulations against thrips and whitefly at commercial scale. The technology is decomposing the historical 3-5 year resistance development timeline into single-season vulnerability windows, forcing manufacturers to accelerate trait stacking.
EPA's 2024 updated Endangered Species Act consultation requirements are extending registration review timelines for conventional chemistries by 12-18 months. The agency's biological evaluation procedures now mandate watershed-scale runoff modeling for all new herbicide actives. Specialty pesticide developers are responding by front-loading ecological risk assessment data before formal submission.
Certification-driven procurement is consolidating buyer power among export-oriented cooperatives. Dutch and German vegetable auction houses now require residue testing documentation at harvest, not just at import. Kenyan flower exporters to EU markets are pre-positioning analytical testing capacity at packhouse level to avoid rejection at Rotterdam cold storage facilities.
Specialty Pesticides Market Segmentation
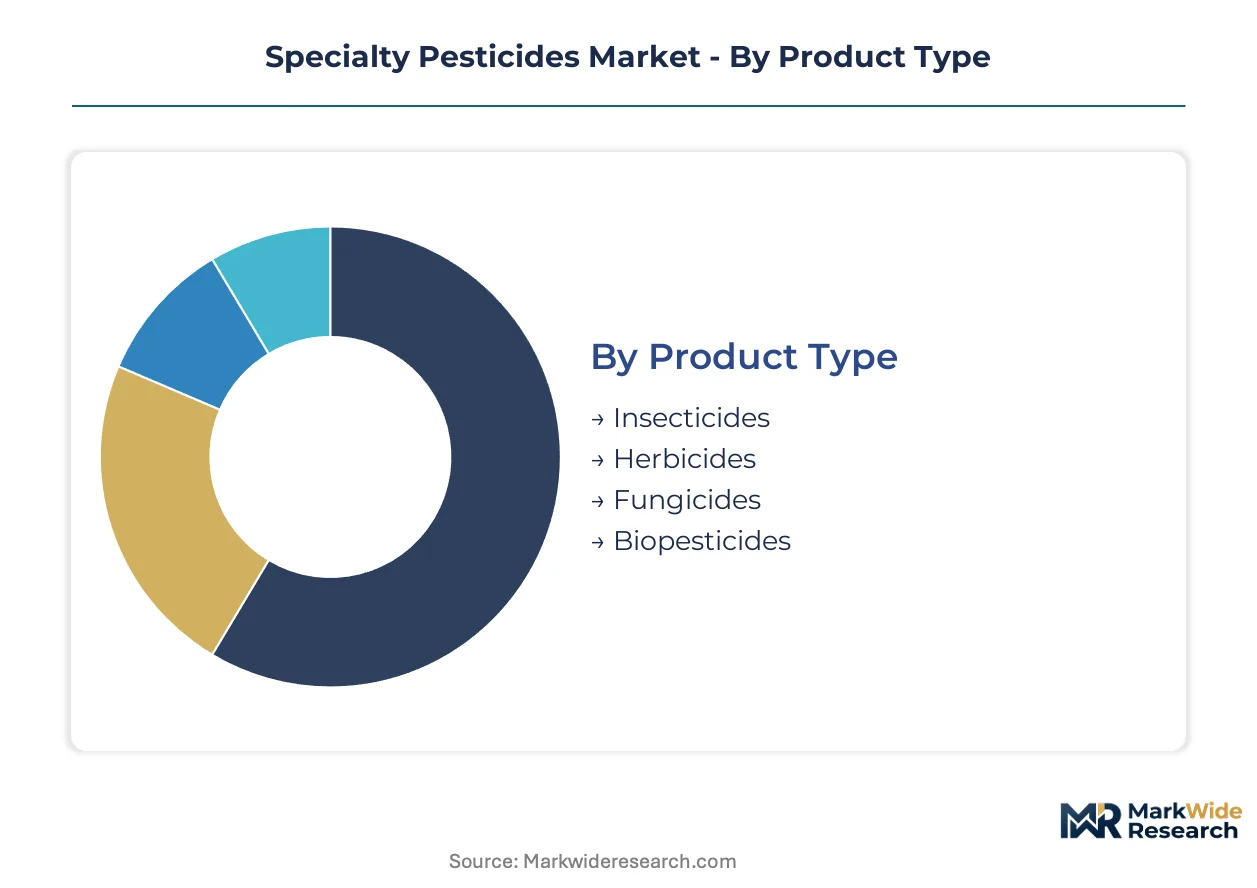
Specialty pesticide segmentation reveals where formulation chemistry, application precision, and end-user sophistication intersect to capture margin pools. Product differentiation across active ingredient classes and delivery systems determines competitive positioning in residue-sensitive supply chains.
Product Type:
Margin concentration sits with products addressing resistance management pressures in high-value cropping systems.
- Herbicides:Selective chemistries targeting resistant weed populations in soybean and cotton rotations command premium positioning. Brazil's Mato Grosso growers rotate modes of action to preserve efficacy windows against Palmer amaranth and morning glory infestations.
- Insecticides:Pyrethroid and neonicotinoid formulations face regulatory compression under ECHA hazard reclassifications. Demand is shifting toward Brazil's Cerrado greenhouse complexes where thrips and whitefly pressure necessitates precision application.
- Fungicides:Systemic triazoles protect yield quality in permanent cropping where latent infection risks threaten harvest premiums.
- Biopesticides:Microbial fermentation platforms qualify for EU ETS-linked carbon removal certifications. Dutch greenhouse operators pilot Bacillus-based formulations against aphid pressure in residue-zero production protocols.
The dominant share belongs to Herbicides, while Biopesticides is closing the gap fastest.
Formulation:
Cost-to-performance ratios separate smallholder-accessible formats from precision-agriculture delivery systems.
- Liquids:Electrostatic-ready formulations integrate with drone-mounted sprayers in Brazil's soybean belt. Mato Grosso operators report 30% reduction in water volumes through ultra-low-volume chemistries.
- Emulsifiable Concentrates:Oil-based carriers enhance cuticular penetration in arid-zone horticulture. Spanish Almería greenhouse producers favor EC formats for systemic uptake in hydroponic tomato production.
- Wettable Powders:Sachet packaging penetrates Kenya's agro-dealer networks serving smallholder vegetable growers.
- Granules:Controlled-release matrices extend protection windows in perennial cropping systems.
Liquids capture the largest volume position, though Emulsifiable Concentrates demonstrate the steepest expansion trajectory in protected cultivation.
Application Method:
Technology adoption curves determine where hardware investment unlocks chemistry efficiency gains.
- Seed Treatment:Biological-chemical coating technologies bundle protection at germination. Bayer and Syngenta proprietary formulations capture margin pools previously lost to generic post-emergent applications.
- Foliar Spray:Drone-mounted electrostatic systems decompose ground-based economics. Brazilian cotton producers in Mato Grosso deploy swarm spraying for bollworm management across 10,000-hectare operations.
- Soil Treatment:Fumigant alternatives address nematode pressure in Kenya's flower export zones.
- Drip Irrigation:Chemigation compatibility requires formulation stability in fertigation matrices.
Seed Treatment holds the premium positioning, while Foliar Spray is scaling fastest through precision hardware penetration.
End User:
Certification requirements and residue liability create tiered pricing power across buyer sophistication levels.
- Horticulturists:Greenhouse operators in the Netherlands and Spain face Dutch auction house documentation mandates at harvest. Pre-positioned ISO 17025 testing at packhouse level prevents Rotterdam cold storage rejections.
- Agricultural Producers:Export-oriented cooperatives in Brazil's Cerrado coordinate ANVISA registration timelines with patent protection windows.
- Turf Managers:Golf course superintendents balance aesthetic thresholds with watershed runoff constraints under EPA Endangered Species Act consultations.
- Home Gardeners:Retail sachet formats dominate South Asian and Sub-Saharan African point-of-sale distribution.
Horticulturists command the highest value-per-hectare intensity, while Agricultural Producers represent the deepest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented cooperatives and integrated crop science platforms concentrate procurement power in jurisdictions with residue-sensitive import protocols. Regulatory divergence between the EPA, ECHA, and ANVISA is fragmenting registration strategies across major production zones. Precision application hardware penetration varies sharply by labor cost structures and farm scale.
Brazil
Mato Grosso soybean operators and Cerrado greenhouse complexes drive demand for ultra-low-volume chemistries and drone-mounted electrostatic systems. ANVISA's concurrent toxicological and ecotoxicological reviews extend registration timelines beyond patent protection windows, compressing commercialization windows. São Paulo-based formulation facilities serve as the distribution hub for Latin American specialty pesticide exports.
United States
Midwest row-crop producers and California specialty vegetable growers anchor herbicide and biopesticide consumption respectively. EPA's 2024 Endangered Species Act consultation requirements extend registration review timelines by 12-18 months for conventional chemistries. The Central Valley's permanent cropping systems concentrate systemic fungicide demand for latent infection management in tree nuts and stone fruits.
Germany
REACH substance reclassifications and the EU Green Deal's Farm to Fork strategy are accelerating biological active ingredient substitution. ECHA's hazard category upgrades for organophosphates redirect R&D investment toward microbial fermentation platforms. The Rhine-Ruhr industrial corridor hosts formulation science capabilities serving greenhouse horticulturists across the Netherlands and Spain.
India
Maharashtra and Gujarat cotton belt intensification generates insecticide demand for bollworm resistance management. Temperature-sensitive microbial formulations underperform during monsoon humidity, limiting biopesticide substitution rates in field applications. Karnataka's protected cultivation clusters in Bengaluru's peri-urban zone pilot residue-zero protocols for export-oriented gherkin and capsicum production.
Netherlands
Greenhouse vegetable producers in Westland and Venlo face Dutch auction house documentation mandates requiring ISO 17025 residue testing at harvest. EU ETS-linked agricultural carbon removal certifications create procurement preferences for biological pesticide application protocols. Wageningen University's research corridor anchors CRISPR-modified biocontrol strain development paired with RNA interference spray technologies.
Specialty Pesticides Market Competitive Landscape
Player mix skews toward integrated crop science platforms with seed treatment bundling capabilities and formulation specialists serving residue-sensitive supply chains. Market structure consolidates around three to five global entities with multi-mode-of-action R&D pipelines, while regional blenders capture cost-driven segments through wettable powder sachet distribution. Strategic archetypes include integrated life science conglomerates, biological fermentation specialists, and generic technical-grade manufacturers. Dominant competitive moves encompass proprietary biological-chemical coating technology licensing and backward integration into microbial strain libraries.
Within the integrated platform tier, Bayer AG, Syngenta Group, and BASF SE exemplify divergent strategic positioning. Bayer's crop science division represents the fully integrated archetype spanning germplasm, seed treatment, and post-emergent chemistry. Syngenta sits within the proprietary formulation-bundling vector, while BASF occupies selective herbicide portfolio specialization. These three entities anchor competitive dynamics through distinct resistance management protocol architectures rather than direct product substitution.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| ADAMA Ltd. |
| Nufarm Limited |
| UPL Limited |
| Sumitomo Chemical |
| Others |
Value Network & Pricing Analysis
Technical-grade active ingredient capacity utilization above 80% in Chinese manufacturing zones compresses margin buffers for downstream formulators while elevating price floors for Brazilian and Indian blenders dependent on imported technicals. Scale concentration in pyrethroid and neonicotinoid intermediates allows contract manufacturers to enforce quarterly price reviews indexed to benzene and phosphorus trichloride benchmarks.
Pricing Analysis
Cost-plus contracts with quarterly indexation to benzene and phosphorus trichloride benchmarks dominate technical-grade procurement between Chinese manufacturers and Brazilian formulators. Three-tier pricing structure across residue-certified premium, standard registration-grade, and economy generic tiers separates ISO 17025-accredited laboratories from uncertified competitors. Cost compression in economy-tier wettable powders is intensifying because Kenyan agro-dealer networks source sachet formats from Indian blenders with minimal brand premium. Export-oriented horticulturists in the Netherlands exhibit lowest price sensitivity due to auction house documentation mandates, while Sub-Saharan smallholders demonstrate highest sensitivity to per-hectare application costs.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Brazilian Mato Grosso operators deploying drone-mounted electrostatic systems, whereas European greenhouse complexes maintain strategic stockpiles of temperature-sensitive microbial formulations to buffer fermentation batch variability. Technical-grade supply concentrates in China, India, and Germany, with formulation blending distributed across Brazil, Kenya, and the Netherlands. Raw material flows draw from benzene derivatives, phosphorus-based intermediates, and microbial fermentation substrates. Single-source vulnerability in Chinese pyrethroid technicals creates geopolitical exposure for Latin American formulators. Distribution runs through São Paulo-based hubs serving Latin America, Rotterdam cold storage facilities for EU horticulture, and Kenya's agro-dealer networks for East African smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty pesticides constitute a defensive-moat market where regulatory entrenchment through ANVISA, EPA, and EU Green Deal registration timelines creates switching costs that protect incumbent formulation portfolios from rapid displacement.
For Market Incumbents: Fortify proprietary biological-chemical seed treatment coating technologies through backward integration into microbial strain libraries, countering generic post-emergent spray substitution. Expand ISO 17025 accreditation capacity in São Paulo and Nairobi to preempt residue documentation bottlenecks at Rotterdam and EU auction houses. Prioritize R&D investment in RNA interference spray platforms to decompose conventional resistance management protocols before patent cliffs erode selective herbicide margins. For New Entrants and Emerging Players: Anchor in Kenya's agro-dealer networks and Maharashtra's cotton belt smallholder segments where wettable powder sachet distribution gaps persist beneath multinational radar. Target India's protected cultivation clusters in Karnataka's peri-urban zones piloting residue-zero protocols for gherkin and capsicum exports. Pursue carbon credit certification bundling with biological pesticide application protocols to qualify for EU ETS-linked procurement preferences among Dutch greenhouse operators. For Investors and Strategic Acquirers: Biological fermentation specialists with captive Bacillus and Trichoderma strain libraries represent the most defensible acquisition archetype as ECHA hazard reclassifications accelerate substitution timelines. Monitor ANVISA registration queue velocity as inflection indicator—compression toward 24-month cycles signals portfolio obsolescence risk for conventional chemistry-dependent assets, while extension beyond 36 months validates biological platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Strain Libraries | Captures margin pools from generic fermentation substrates while securing Bacillus thuringiensis supply for Dutch greenhouse contracts. |
| ISO 17025 Accreditation Expansion | Enables residue certification at harvest for Kenyan flower exporters facing Rotterdam cold storage rejection protocols. |
| RNA Interference Spray Platform Development | Decomposes 3-5 year resistance timelines into single-season windows for Netherlands and Spain thrips management. |
| Carbon Credit Certification Bundling | Qualifies biological application protocols for EU ETS-linked procurement among Westland and Venlo vegetable producers. |
| Drone-Mounted Electrostatic Formulation Licensing | Captures 30% water volume reduction economics in Brazil's Mato Grosso soybean belt precision agriculture expansion. |
Research Methodology
Desk research of customs and trade flow databases, ANVISA and EPA registration filings, and EU Green Deal implementation protocols preceded structured interviews with formulation R&D directors, agro-dealer network managers, greenhouse operations managers, and residue testing laboratory accreditation officers. Secondary validation drew from SEC 10-K disclosures of integrated crop science platforms, ECHA substance evaluation reports, and Brazilian agricultural census data. Bottom-up triangulation across active ingredient demand by crop hectare and top-down validation through manufacturer revenue segmentation ensured cross-verified outputs.
Variance decomposition across product type, formulation chemistry, application method, and end-user sophistication dimensions shaped the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves for precision application hardware penetration and biological substitution rates, with segment-level growth calibrated against ANVISA registration approval velocity and EU MRL harmonization updates. Industry-specific inputs included drone-mounted electrostatic sprayer adoption curves in Brazil and ISO 17025 laboratory capacity expansion timelines in Kenya and the Netherlands.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal implementation pace and stable Chinese technical-grade export licensing; material deviation in either would warrant model refresh. Revision becomes warranted when ANVISA concurrent review timelines cross 36-month thresholds or ECHA hazard reclassification velocity accelerates beyond current organophosphate category upgrades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
China Fungicide Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Isoxaflutole Market
Crop Protection
Europe Molluscicides Market
Crop Protection
US Pest Control Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Tebuconazole Market
Crop Protection
Global Termite Control Market
Crop Protection
Iprodione Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Fruit and Vegetable Crop Protection Market