
 Slow Release NPK Fertilizer Market | 2026-2036
Slow Release NPK Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Slow Release NPK Fertilizer Market Insights
Project finance tied to sustainable agriculture certification programs is reconfiguring competitive access for mid-tier producers lacking balance-sheet depth. Nutrien Ltd. leverages its integrated potash-nitrogen network to control upstream raw material costs across North American slow-release formulation plants. Yara International anchors European demand through precision agriculture partnerships that bundle coated NPK with digital nutrient management platforms. Haifa Group specializes in water-soluble and coated technologies for high-value horticultural export markets.
Slow release NPK fertilizer combines nitrogen, phosphorus, and potassium in matrices or polymer coatings that meter nutrient availability across 6-12 week crop cycles, reducing leaching losses and application frequency versus conventional soluble grades. Coated formulations command premium positioning in specialty agriculture where labor scarcity and environmental compliance justify higher input costs, while granular products dominate commodity row-crop volume through established dealer networks. The horticultural application segment captures concentrated margin pools in greenhouse and nursery operations requiring precise nutrient timing, whereas agricultural end users drive absolute tonnage through corn, wheat, and soybean programs.
The EPA's Clean Water Act nutrient discharge standards and the EU Green Deal's Farm to Fork 50% pesticide and fertilizer reduction targets constrain conventional soluble product placement, directly advantaging coated and controlled-release alternatives in regulated watersheds. China's MEE enforces GB standard limits on residual polymer coatings in agricultural runoff, reshaping formulation chemistry for suppliers targeting domestic Chinese production. Brazil's MAPA fertilizer registration requirements and India's FSSAI-adjacent state-level fertilizer control orders create layered compliance barriers that favor established multinationals with regulatory affairs infrastructure. Stakeholders must weigh biodegradable coating R&D commitments against the durability performance that commodity farmers still demand at scale.
Market Dynamics
Polymer coating chemistry is pivoting toward biodegradable matrices as China's MEE discharge rules and California's nitrogen management protocols simultaneously tighten, forcing formulation R&D spend toward compliance rather than pure agronomic performance optimization.
Growth Catalysts
- California Nitrogen Management Protocols:Specialty crop growers in the Central Valley face state-mandated nutrient budgeting that favors coated formulations reducing application frequency and leaching risk.
- Brazil's Labor Scarcity:Large-scale soybean operations in the Cerrado belt prioritize single-pass fertilization programs that coated NPK enables through extended nutrient release windows.
- EU Green Deal Farm to Fork Targets:The 50% fertilizer reduction mandate advantages controlled-release products in watersheds where conventional soluble runoff faces escalating penalties.
Market Restraints
- Potash Supply Concentration:Canadian and Belarussian potash mining cartels create input cost volatility that compresses margin buffers for downstream coating operations.
- Technical Durability Trade-offs:Biodegradable coating alternatives struggle to match synthetic polymer release precision in high-rainfall tropical zones, limiting addressable acreage.
- India's FSSAI-Adjacent State Control Orders:Layered registration requirements across 28 state jurisdictions create compliance friction that delays product launch timelines by 18-24 months.
Strategic Opportunities
- Underpenetrated Indonesian Palm Sector:Plantation operators in Sumatra and Kalimantan represent untapped volume for labor-saving coated NPK in perennial crop systems.
- Precision Agriculture Convergence:Variable-rate application hardware paired with coated fertilizer prescription algorithms creates bundled service revenue streams.
- US IRA Conservation Incentives:USDA Environmental Quality Incentives Program cost-share structures subsidize enhanced-efficiency fertilizer adoption in Chesapeake Bay and Mississippi River watersheds.
Industry Challenges
- Coating Chemistry Talent Scarcity:Formulation scientists capable of balancing biodegradability with release kinetics command premium compensation that mid-tier producers struggle to match.
- Legacy Dealer Network Integration:Established granular fertilizer distribution infrastructure resists inventorying higher-cost coated SKUs without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slow Release NPK Fertilizer Market |
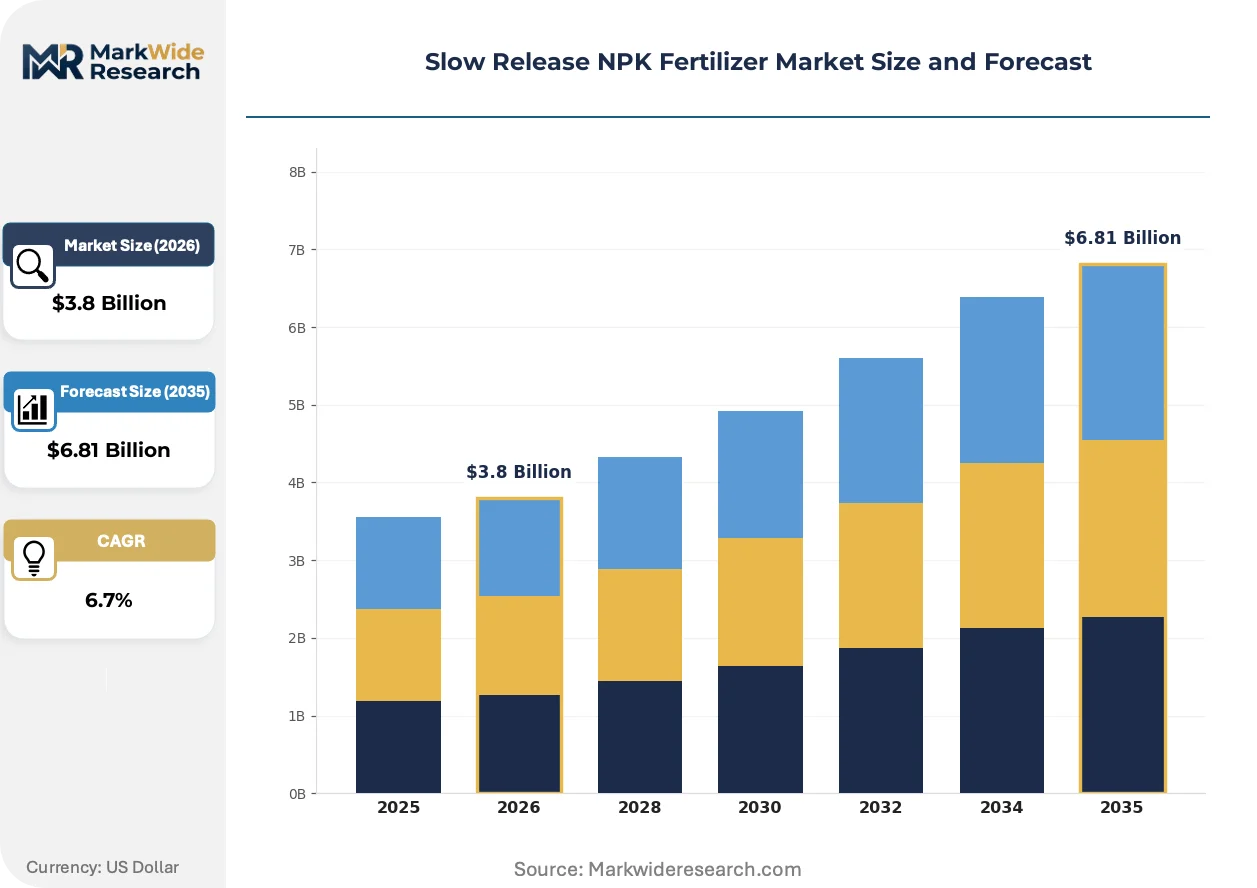
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Coated, Liquid, Powder Application: Agricultural, Horticultural, Turf, Ornamental Formulation: Organic, Inorganic, Synthetic, Biological End User: Farmers, Landscapers, Garden Centers, Retailers |
| Companies Covered | Nutrien Ltd., Yara International, ICL Group Ltd, The Mosaic Company, Kingenta Ecological Engineering Group Co. Ltd, Haifa Group, Sociedad Química y Minera S.A. (SQM), CF Industries, EuroChem Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slow Release NPK Fertilizer Market Trends and Innovations
Coating technology is converging with digital agriculture platforms while regulatory chemistry standards diverge across major agricultural economies, creating parallel innovation tracks rather than unified product development roadmaps.
Sensor-enabled release monitoring is digitizing nutrient availability forecasting. Polymer-embedded microsensors transmit soil moisture and temperature data to farm management software, enabling predictive application timing. Specialty greenhouse operators in the Netherlands and Spain are piloting these systems at scale, compressing the feedback loop between fertilizer placement and plant uptake response.
China's GB standard limits on residual synthetic polymers in agricultural runoff are forcing domestic manufacturers toward starch-based and polylactic acid coating alternatives. The MEE enforcement timeline accelerates R&D investment but degrades release curve precision in early-generation biodegradable formulations. Export-oriented Chinese suppliers targeting Brazil and Southeast Asia must maintain dual product lines to serve regulatory divergences.
Direct-to-farm procurement platforms are disintermediating traditional dealer networks for coated NPK volumes. Large-scale Midwestern corn operations and Australian wheat belt cooperatives negotiate bulk contracts through digital marketplaces, bypassing county-level agronomist relationships that historically controlled product placement. This channel shift concentrates buyer power and compresses distributor margins while demanding manufacturer logistics flexibility for split-ship delivery windows.
Slow Release NPK Fertilizer Market Segmentation
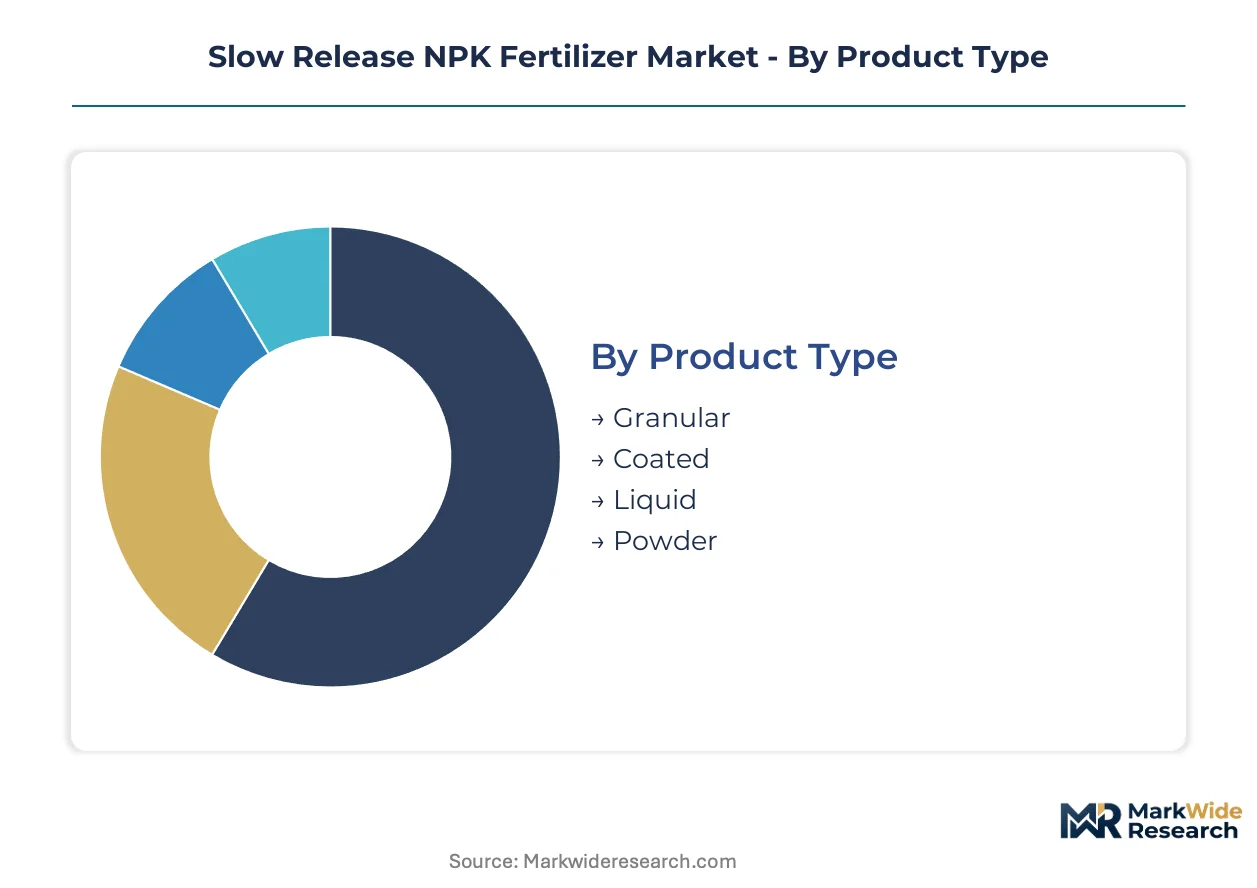
Slow release NPK fertilizer segmentation reflects divergent technical service requirements across application intensities. Coated formulations demand precision agronomy support, while commodity granular products move through established dealer networks with minimal technical intervention.
Product Type:
After-sales service intensity varies dramatically by physical form, with coated products requiring application training and release-curve troubleshooting that granular volumes rarely need.
- Coated:Polymer or sulfur-coated granules meter nutrient release across 6-12 week windows through moisture-activated diffusion mechanisms. Specialty crop growers in California's Central Valley purchase these formulations to satisfy state nitrogen management protocols while reducing labor inputs. The segment commands premium positioning where environmental compliance justifies higher input costs.
- Granular:Uncompressed or compacted bulk blends dominate commodity row-crop tonnage through established dealer infrastructure across the US Corn Belt and Brazil's Cerrado. Large-scale soybean operations prioritize these lower-cost options where single-pass application economics outweigh extended-release precision benefits.
- Liquid:Suspension concentrates suit fertigation systems in greenhouse and nursery operations requiring rapid nutrient adjustment.
- Powder:Fine-ground formulations serve specialty blending operations and controlled-environment agriculture with precise dosing requirements.
Granular holds the largest share; momentum sits with Coated as regulatory pressure intensifies.
Application:
Margin concentration follows application complexity, with high-value horticultural systems capturing disproportionate value per ton compared to broadacre commodity programs.
- Horticultural:Greenhouse, nursery, and protected-crop operations demand precise nutrient timing for high-value export production. Dutch and Spanish greenhouse operators pilot sensor-embedded coated formulations that transmit soil moisture data to farm management platforms, compressing feedback loops between placement and plant response.
- Agricultural:Corn, wheat, and soybean programs drive absolute tonnage through volume purchasing agreements. Brazilian large-scale farmers in Mato Grosso and Goiás states adopt coated NPK to address labor scarcity in the Cerrado belt, enabling single-pass fertilization across extended release windows.
- Turf:Golf course and sports field maintenance programs prioritize uniform greening with minimal growth surge.
- Ornamental:Landscape and garden applications favor convenience-oriented retail packaging over technical performance specifications.
Agricultural dominates absolute volume; Horticultural climbs the fastest on margin expansion.
Formulation:
Raw material sourcing chemistry determines regulatory compliance pathways across divergent national standards.
- Synthetic:Urea-formaldehyde and isobutylidene diurea matrices provide predictable release kinetics through controlled hydrolysis rates. China's MEE tightened discharge rules on residual synthetic polymers in agricultural runoff, forcing domestic manufacturers toward alternative chemistries while export-oriented suppliers maintain dual product lines for regulatory divergences.
- Biological:Microbial-activated release systems align with EU Green Deal Farm to Fork targets for 50% fertilizer reduction. These formulations gain share in watersheds where conventional soluble runoff faces escalating penalties under EPA Clean Water Act enforcement.
- Organic:Plant-derived and animal-waste-based matrices serve certified organic production systems with restricted synthetic input allowances.
- Inorganic:Mineral-based slow-release mechanisms include magnesium ammonium phosphate and potassium magnesium sulfate compounds.
Synthetic retains dominant share; Biological gains share fastest on regulatory tailwinds.
End User:
Procurement scale and technical sophistication create distinct service tiers across customer categories.
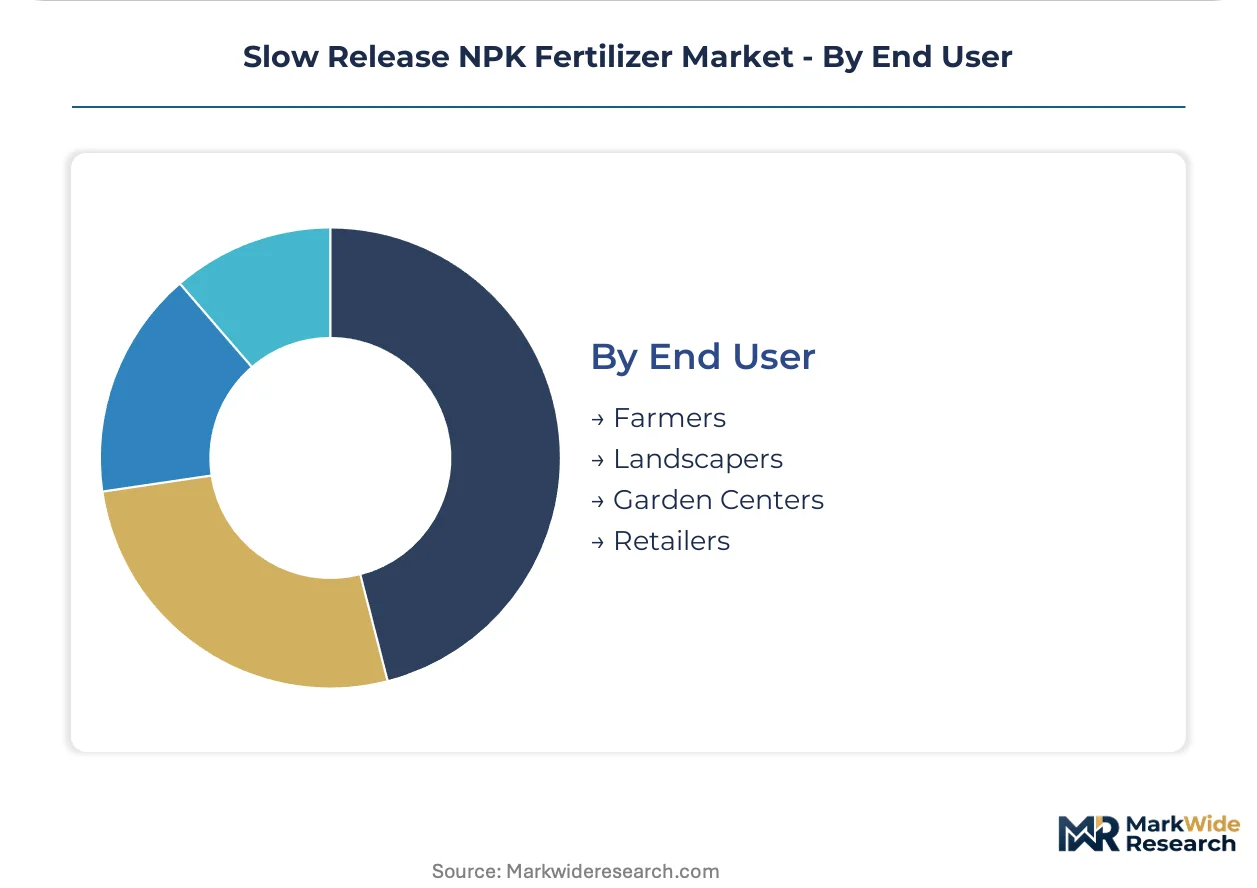
- Farmers:Large-scale commercial operations in Brazil, the US, and Australia negotiate direct-to-farm procurement contracts through digital marketplaces, bypassing traditional county-level agronomist relationships. These buyers demand logistics flexibility for split-ship delivery windows aligned with planting calendars.
- Retailers:Agricultural supply cooperatives and farm store chains inventory coated SKUs only with guaranteed volume commitments from manufacturers, creating working capital barriers for mid-tier producers lacking balance-sheet depth.
- Landscapers:Commercial maintenance contractors prioritize labor-saving application schedules over per-unit nutrient cost optimization.
- Garden Centers:Consumer-oriented outlets stock convenience-packaged formats with minimal technical specification requirements.
Farmers command the largest procurement volume; Retailers concentrate margin capture through inventory control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in China and North America supply coated NPK formulations to Brazil and Southeast Asia, while import-dependent European markets prioritize regulatory-compliant biological alternatives. Trade flows concentrate around potash-rich Canada and nitrogen-producing Gulf Coast corridors.
United States
Midwestern corn operations in Iowa and Illinois drive bulk granular demand through established dealer networks. The EPA's Clean Water Act nutrient discharge standards push Chesapeake Bay and Mississippi River watershed farmers toward enhanced-efficiency coated products. California's Central Valley specialty crop belt anchors premium coated NPK consumption under state nitrogen management protocols.
Brazil
Mato Grosso and Goiás soybean operations in the Cerrado belt prioritize single-pass fertilization programs that reduce labor requirements. ANVISA fertilizer registration requirements create compliance barriers favoring established multinationals with regulatory infrastructure. Port terminals at Santos and Paranaguá concentrate import volumes for domestic distribution.
China
Domestic manufacturers pivot toward biodegradable coating alternatives as the MEE enforces GB standard limits on residual synthetic polymers in agricultural runoff. Shandong and Jiangsu provinces host formulation plants serving both domestic production and Southeast Asian export markets. Dual product lines emerge to address regulatory divergences between domestic and export destinations.
Germany
The EU Green Deal's Farm to Fork 50% fertilizer reduction mandate advantages controlled-release products in regulated watersheds. Precision agriculture partnerships in Bavaria and North Rhine-Westphalia bundle coated NPK with digital nutrient management platforms. ECHA chemical registration requirements shape formulation chemistry for suppliers targeting continental European markets.
India
FSSAI-adjacent state-level fertilizer control orders across 28 jurisdictions delay product launches by 18-24 months, favoring producers with established regulatory affairs capacity. Punjab and Haryana wheat belts represent volume opportunities for labor-saving coated formulations. Gujarat and Maharashtra industrial corridors host blending operations serving domestic agricultural demand.
Slow Release NPK Fertilizer Market Competitive Landscape
On the supply side, the industry is consolidating around integrated nutrient producers with captive raw material access and specialized coating technology developers. Tier-one players leverage potash mining and nitrogen production assets to control input costs, while mid-tier formulators compete on regional regulatory expertise and application-specific technical service. Three archetypes dominate: vertically integrated mining-to-coating conglomerates, precision agriculture technology bundlers, and regional formulation specialists. Competitive moves concentrate on backward integration into polymer chemistry and strategic partnerships with variable-rate application hardware providers.
Among integrated nutrient producers, Nutrien Ltd. and Yara International occupy positions that exemplify scale-driven raw material control, while Haifa Group represents the specialized coating technology tier. Nutrien anchors North American supply through its potash-nitrogen network. Yara exemplifies European precision agriculture convergence. Haifa sits within the high-value horticultural export specialization segment.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Yara International |
| ICL Group Ltd |
| The Mosaic Company |
| Kingenta Ecological Engineering Group Co. Ltd |
| Haifa Group |
| Sociedad Química y Minera S.A. (SQM) |
| CF Industries |
| EuroChem Group |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese coating formulation plants is compressing margin buffers and forcing suppliers toward extended payment terms to retain offtake commitments from Brazilian and Southeast Asian buyers. This utilization dynamic simultaneously erodes pricing power for commodity-grade granular products while concentrating premium realization in biodegradable-coated alternatives serving California and EU regulatory markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation stems from EU Green Deal compliance tiers and after-sales agronomy support intensity. Pricing pressure intensifies in standard-grade granular products as Canadian potash input costs transmit downstream. Smallholder cooperatives in India exhibit highest price sensitivity; Dutch greenhouse operators show lowest sensitivity due to labor-cost arbitrage from reduced application frequency.
Supply Chain Analysis
Extended payment terms from Brazilian distributors now stretch 90-120 days, forcing manufacturers to draw from supply-chain finance facilities anchored in Singapore trade corridors. Raw material sourcing centers on Canadian potash, Chinese nitrogen, and Moroccan phosphate rock. Distribution runs through port terminals at Santos, Paranaguá, and Rotterdam with containerized bulk handling. Single-source vulnerability concentrates in Belarusian potash rail corridors subject to sanctions exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct-to-farm procurement platforms that disintermediate traditional dealer networks, with large-scale Brazilian and Australian cooperatives consolidating purchasing volumes.
For Market Incumbents: Pre-empt coating chemistry talent scarcity by acquiring regional formulation specialists with biodegradable R&D capabilities before Chinese MEE enforcement accelerates. Lock in multi-year potash supply agreements with Canadian producers to defend margin buffers against input volatility. Secure exclusive distribution partnerships with variable-rate application hardware providers to bundle digital nutrient management platforms. For New Entrants and Emerging Players: Indonesian palm plantations in Sumatra and Kalimantan represent the most penetrable geography for labor-saving coated NPK in perennial crop systems. Target specialty horticultural exporters in Spain and the Netherlands with sensor-embedded formulations that transmit soil moisture data to farm management software. Pursue white-label manufacturing partnerships with established Chinese exporters to bypass India's FSSAI-adjacent state registration barriers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier coating technology developers with biodegradable formulation pipelines and established regulatory affairs capacity in China and Brazil. Long-term viability favors suppliers capable of serving divergent national chemistry standards through dual product lines. Watch for inflection in California nitrogen management protocol enforcement timelines as signal for premium-coated demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Coating R&D Expansion | Chinese MEE GB standard enforcement accelerates reformulation investments for domestic and export markets. |
| Precision Agriculture Partnership | Bundling coated NPK with Yara International digital platforms captures margin in EU Green Deal compliance watersheds. |
| Direct-to-Farm Procurement Platform | Bypassing dealer networks concentrates buyer power and demands logistics flexibility for split-ship delivery windows. |
| Backward Integration into Polymer Chemistry | Captive coating supply reduces dependency on synthetic polymer discharge regulations across multiple jurisdictions. |
| Long-term Supply Agreement with Potash Producers | Canadian mining cartel concentration creates input cost volatility that compressed margin buffers threaten downstream coating operations. |
Research Methodology
A spread of perspectives from coating formulation scientists, Brazilian large-scale farm operators, Chinese regulatory affairs specialists, and EU precision agriculture platform engineers converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from customs trade data, SEC 10-K filings, EPA Clean Water Act enforcement records, and MEE GB standard documentation. Bottom-up volume modeling and top-down value triangulation anchored the analysis.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeled by product type, application intensity, formulation chemistry, and end-user procurement scale. CAGRs derived from regression analysis against historical adoption curves in regulated watersheds. Key inputs included California nitrogen management protocol compliance timelines and Brazilian labor scarcity indices in Mato Grosso soybean operations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed coating manufacturers or sudden potash cartel supply disruptions would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Organic Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market