
 Russia Seed Market | 2026-2036
Russia Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Seed Market Analytics
Russia's national seed certification framework is restructuring the cost-of-entry calculus for foreign genetics suppliers. Bayer AG leverages its global breeding pipeline to sustain variety registration momentum despite localization mandates. Corteva Agriscience anchors its position through in-house production of adapted hybrids. Moscow Seed Company competes on proximity to Black Earth zone distribution networks.
Russia seeds comprise genetically stable propagules—typically exhibiting germination rates above 85% and varietal purity exceeding 98%—that serve as the biological foundation for commercial crop production across temperate and continental agro-climatic zones. Cereals occupy the dominant volume position, reflecting the structural priority of wheat and barley in national food security planning. Oilseeds represent the fastest-expanding product type, driven by sunflower and soybean processing capacity additions. The wholesale distribution channel controls margin pools through bulk procurement relationships with agricultural cooperatives.
Russia's Federal Service for Veterinary and Phytosanitary Surveillance (Rosselkhoznadzor) enforces quarantine and import protocols that determine which foreign varieties gain market access. The national seed registry maintained under Ministry of Agriculture standards dictates which cultivars qualify for state subsidy programs. Stakeholders must monitor regulatory alignment between Eurasian Economic Union technical regulations and domestic varietal testing requirements.
Market Dynamics
Russia's seed certification tightening under Rosselkhoznadzor protocols is restructuring competitive entry costs. Foreign genetics suppliers now face mandatory multi-year varietal testing before state registry inclusion.
Growth Catalysts
- Central Federal District demand concentration:Agricultural cooperatives around Moscow and Voronezh are scaling certified seed procurement for winter wheat and barley rotations.
- Eurasian Economic Union technical alignment:Harmonized phytosanitary protocols reduce cross-border registration friction for adapted varieties.
- Oilseed processing capacity expansion:Sunflower and soybean crushing facility additions in the Black Earth zone pull hybrid seed demand.
Market Restraints
- Localization mandates:Ministry of Agriculture rules require domestic production or joint-venture structures for foreign genetics, raising fixed cost thresholds.
- Variety approval timelines:Rosselkhoznadzor field testing cycles stretch 3-5 years, compressing effective patent windows.
- Input cost volatility:Fertilizer and crop protection price swings destabilize farm budgeting for certified seed premiums.
Strategic Opportunities
- Volga Federal District penetration:Samara and Saratov regions show underdeveloped certified seed coverage relative to cereal acreage.
- Digital traceability integration:Blockchain-based seed origin verification aligns with tightening export documentation requirements.
- Organic certification pathway:State subsidy programs for organic conversion create demand for non-GMO, open-pollinated varieties.
Industry Challenges
- Plant breeder rights enforcement:IP infringement in farm-saved seed networks erodes returns on hybrid development.
- Climate adaptation lag:Breeding pipelines struggle to match accelerating drought frequency in southern zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Seed Market |
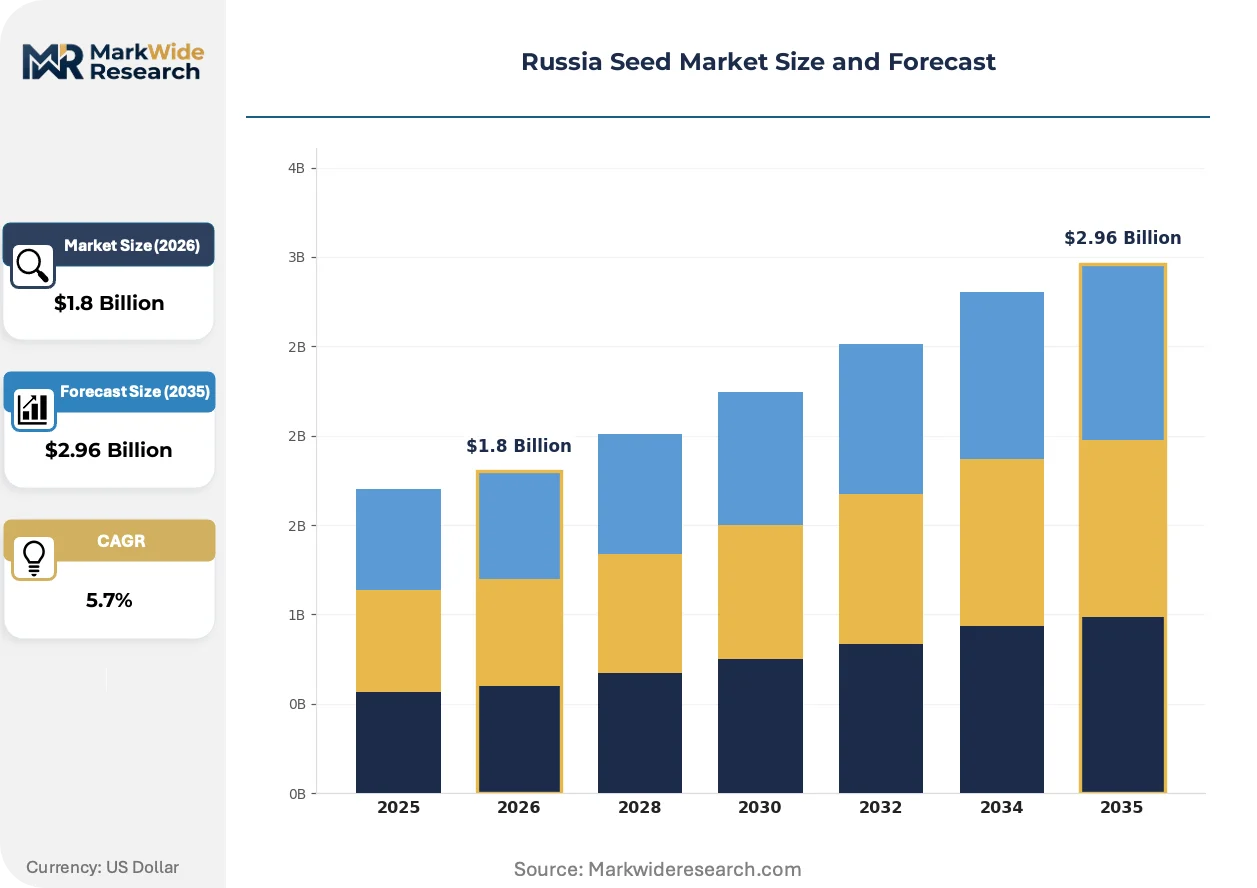
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Vegetables, Pulses, Oilseeds End User: Farmers, Seed Companies, Agricultural Cooperatives, Research Institutions Distribution Channel: Direct Sales, Retail, Online, Wholesale Application: Agriculture, Horticulture, Landscaping, Research |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Syngenta Group, Groupe Limagrain, Moscow Seed Company, Krista Seeds, PhosAgro, UralChem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Seed Market Evolving Landscape
Molecular breeding tools and regulatory digitization are compressing variety development cycles. Demand-side consolidation among agricultural holdings reshapes procurement relationships.
Marker-assisted selection is expanding into Russia's sunflower and soybean breeding programs. Large-scale agricultural holdings in Voronezh and Belgorod oblasts are adopting these platforms at accelerating rates. The technology is expanding into shorter-cycle variety turnover, compressing the gap between foreign pipeline releases and domestic adaptation.
Rosselkhoznadzor's electronic certification registry mandates are tightening documentation requirements for seed lot traceability. The industrial consequence is forced IT infrastructure investment across wholesale distributors. Smaller regional seed houses in the Central Federal District face the steepest compliance cost absorption.
Agricultural cooperative consolidation is compressing buyer concentration at the procurement interface. Direct contracting between seed houses and mega-farms is displacing traditional dealer networks in key cereal zones. The Volga and Southern Federal districts exhibit the most visible channel restructuring.
Russia Seed Market Segmentation
Seed procurement patterns in Russia diverge sharply across crop categories and buyer types. Certification requirements from Rosselkhoznadzor and subsidy eligibility rules reshape how each segment captures value.
Product Type:
Capital intensity concentrates in breeding infrastructure and multi-year varietal testing pipelines, with divergent cost recovery timelines across crop categories.
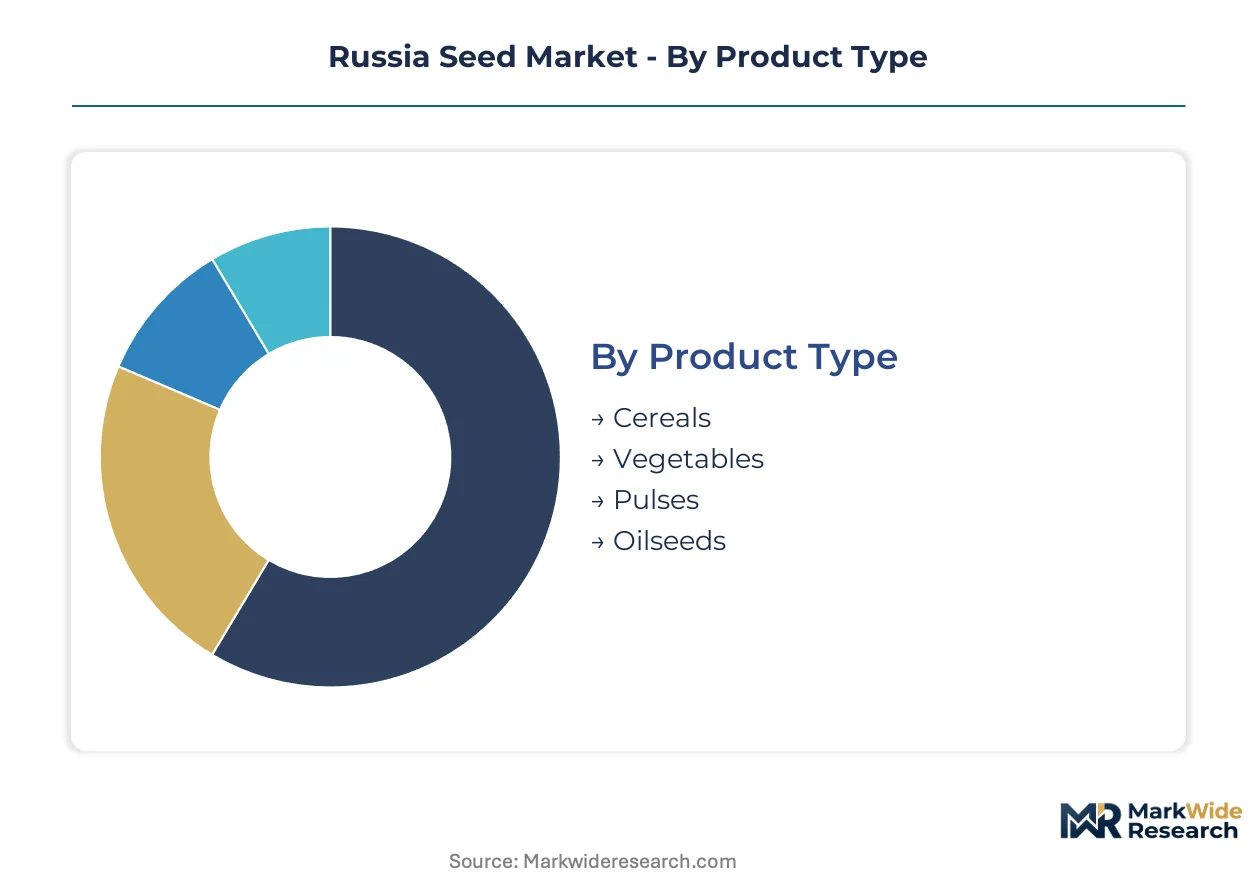
- Cereals:Certified wheat and barley seeds require extensive field trials for state registry inclusion, absorbing the largest share of domestic breeding R&D expenditure. Central Federal District cooperatives around Voronezh and Moscow dominate procurement volumes, driven by winter wheat rotation expansion and state grain security mandates.
- Oilseeds:Sunflower and soybean hybrids demand proprietary parent line development and controlled pollination infrastructure. Black Earth zone crushing facility additions in Belgorod and Kursk oblasts pull hybrid seed demand, though foreign genetics face localization requirements under Ministry of Agriculture rules.
- Vegetables:Open-field and protected cultivation varieties with shorter breeding cycles.
- Pulses:Pea and lentil varieties for crop diversification and protein crop substitution programs.
Cereals absorb the bulk of installed breeding capacity; oilseeds are expanding most quickly.
End User:
Buyer scale determines procurement sophistication, with large operators capturing certification cost efficiencies unavailable to smaller counterparts.
- Agricultural Cooperatives:Consolidated holdings in Voronezh and Belgorod oblasts execute bulk certified seed contracts directly with registered seed houses, bypassing traditional dealer markups. Their procurement scale justifies dedicated quality assurance staff and on-farm variety trialing infrastructure.
- Farmers:Individual operators rely on regional distributor networks for smaller lot purchases, facing higher per-unit certification documentation costs.
- Seed Companies:Licensed producers maintaining breeding nurseries and foundation seed multiplication.
- Research Institutions:State agricultural academies conducting varietal testing under Rosselkhoznadzor protocols.
Agricultural cooperatives command the largest procurement volumes; seed companies show the steepest technology investment trajectory.
Distribution Channel:
Channel selection locks in margin capture and traceability compliance burdens, with divergent IT infrastructure requirements.
- Wholesale:Bulk procurement relationships with mega-farms and cooperative networks concentrate margin pools in the Black Earth and Central Federal districts. Rosselkhoznadzor electronic certification mandates force substantial ERP investments among surviving distributors.
- Direct Sales:Seed houses contract directly with large agricultural holdings, displacing intermediaries in key cereal zones. Voronezh oblast exhibits the most visible channel restructuring as mega-farms consolidate procurement functions.
- Retail:Regional agro-supply stores serving smaller operators with bagged certified seed.
- Online:Emerging platform sales for variety documentation and traceability transparency.
Wholesale channels handle the majority of certified seed volume; direct sales are climbing the fastest.
Application:
Application scope determines regulatory scrutiny intensity and subsidy eligibility, with commercial agriculture commanding disproportionate policy attention.
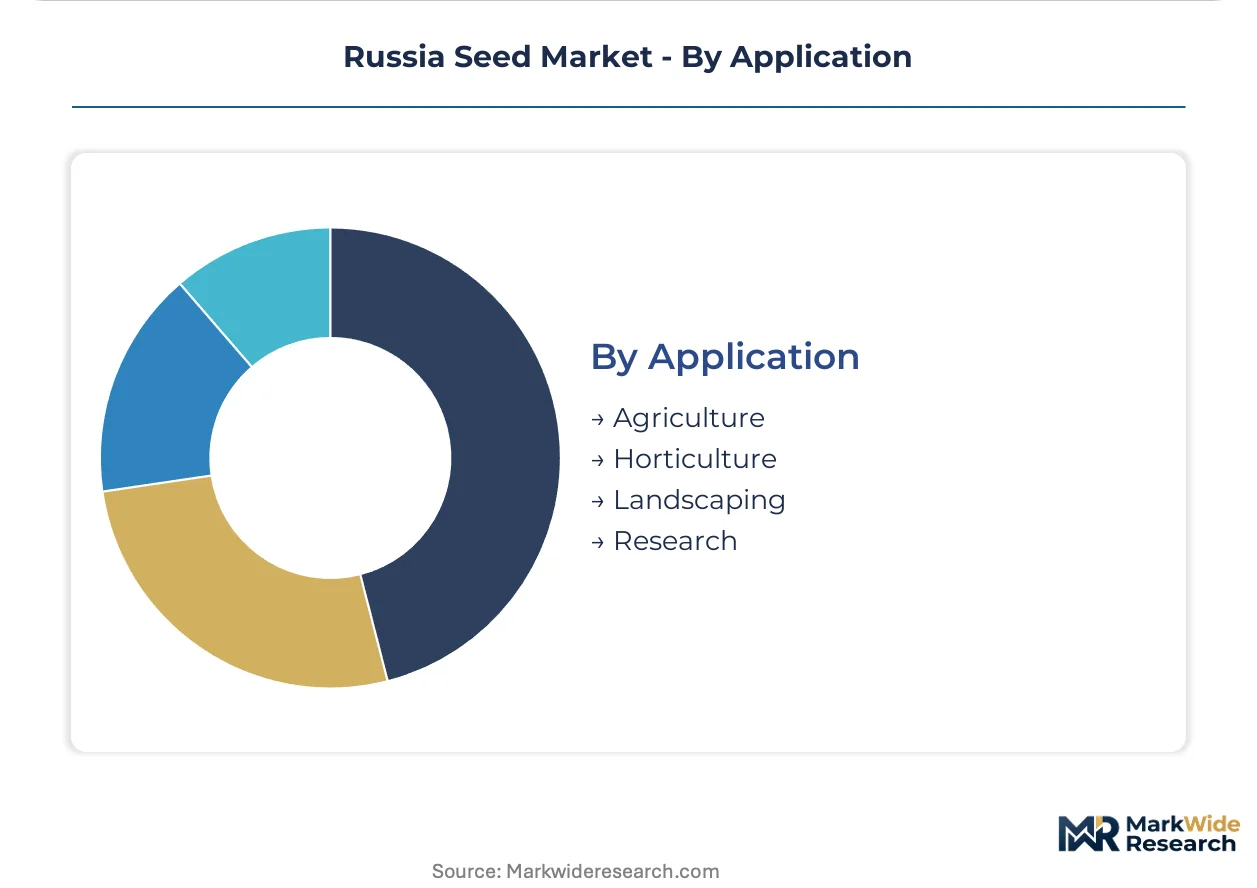
- Agriculture:Commercial crop production accounts for dominant seed consumption, with wheat, barley, sunflower, and soybean rotations driving varietal registration priorities. State subsidy programs tie directly to Ministry of Agriculture registry inclusion, concentrating breeder investment in eligible categories.
- Horticulture:Protected cultivation and open-field vegetable production with distinct phytosanitary protocols.
- Landscaping:Turf and ornamental varieties for municipal and private development projects.
- Research:Controlled varietal testing and breeding pipeline development.
Agriculture captures nearly all certified seed deployment; horticulture is gaining share fastest on greenhouse expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central Black Earth Special Economic Zone incentives are concentrating breeding infrastructure investment around Voronezh and Belgorod. Federal subsidy programs tied to regional agricultural development targets channel procurement volume toward certified seed houses with localized production.
Central Federal District
Agricultural cooperatives in Moscow and Voronezh oblasts are scaling winter wheat and barley rotations under state grain security mandates. Rosselkhoznadzor's electronic certification registry requires seed houses to maintain traceability infrastructure for subsidy eligibility. Mega-farms around Voronezh are consolidating direct procurement relationships, displacing traditional dealer networks.
Volga Federal District
Samara and Saratov regions show underdeveloped certified seed coverage relative to cereal acreage, creating penetration opportunities for registered producers. Ministry of Agriculture varietal testing protocols apply uniform standards across all federal districts, extending approval timelines. Agricultural holdings in the Middle Volga are building dedicated quality assurance staff to manage bulk procurement contracts.
Southern Federal District
Sunflower and soybean crushing facility additions in Rostov oblast pull hybrid seed demand from Black Earth zone suppliers. Rosselkhoznadzor phytosanitary surveillance intensifies border controls for imported genetics, favoring domestic production structures. Krasnodar Krai clusters are adopting marker-assisted selection platforms for shorter-cycle variety turnover.
Northwestern Federal District
St. Petersburg serves as the primary entry point for imported genetics undergoing varietal testing before state registry inclusion. Eurasian Economic Union technical alignment reduces cross-border registration friction for adapted varieties from Belarus and Kazakhstan. Regional distributors face forced ERP investments to comply with electronic certification mandates.
Ural Federal District
Chelyabinsk and Kurgan oblasts concentrate pulse crop diversification programs supporting protein crop substitution. Federal Service for Veterinary and Phytosanitary Surveillance enforces quarantine protocols that determine foreign variety market access. Regional seed houses are developing open-pollinated varieties for organic certification pathways tied to state conversion subsidies.
Russia Seed Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Russia's seed certification tiers. Market structure tilts toward consolidated procurement relationships as agricultural cooperative mergers reduce buyer fragmentation. Three archetypes dominate: global breeders with localized production, domestic seed houses with distribution proximity, and fertilizer-chemical conglomerates with backward integration into genetics. Competitive moves center on multi-year varietal testing pipeline investment and direct contracting with mega-farms.
Within the global breeder tier, Bayer AG and Corteva Agriscience occupy positions sustained by global breeding pipelines and in-house hybrid production. Moscow Seed Company anchors the domestic proximity archetype through Black Earth zone distribution networks. BASF SE and Syngenta Group exemplify diversified chemical-seed conglomerates navigating localization mandates through joint-venture structures. Krista Seeds represents regional specialization in adapted varieties for Central Federal District conditions.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| Syngenta Group |
| Groupe Limagrain |
| Moscow Seed Company |
| Krista Seeds |
| PhosAgro |
| UralChem |
| Others |
Value Network & Pricing Analysis
Mega-farm procurement consolidation in Voronezh and Belgorod oblasts is compressing dealer margins and forcing seed houses toward direct contracting models that reshape cost recovery structures across certification tiers.
Pricing Analysis
Short lead-time premiums for certified seed lots with immediate Rosselkhoznadzor electronic documentation run 15-25% above standard contract pricing. Three-tier pricing structure across premium certified, standard registered, and economy-grade farm-saved seed segments reflects germination rate guarantees and varietal purity thresholds. Cost compression in the economy tier is intensifying because agricultural cooperatives are internalizing quality assurance functions. Individual farmers show highest price sensitivity due to per-unit documentation cost burdens, while consolidated mega-farms capture volume discounts through multi-year offtake agreements.
Supply Chain Analysis
Parent line development for sunflower and soybean hybrids rests on proprietary germplasm controlled by multinational breeders with centralized R&D in Germany, the United States, and France. Foundation seed multiplication draws from controlled pollination facilities in the Black Earth zone, while commercial production hinges on grower networks in Voronezh, Belgorod, and Kursk oblasts. Single-source vulnerability concentrates in hybrid parent line supply, where foreign genetics face Rosselkhoznadzor quarantine delays. Distribution runs through wholesale channels serving mega-farms and agricultural cooperatives, with direct sales displacing traditional dealer networks in cereal zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's seed market sits in a technology-transition phase where molecular breeding platforms and digital traceability systems are displacing conventional phenotypic selection and paper-based certification workflows.
For Market Incumbents: Anticipate regulatory digitization mandates by investing in blockchain-based seed origin verification infrastructure ahead of Rosselkhoznadzor's full electronic registry deployment. Secure backward integration into foundation seed production to offset localization requirements that raise fixed cost thresholds for foreign genetics suppliers. Channel control through direct mega-farm relationships in Voronezh oblast offers defensive positioning against cooperative procurement consolidation. For New Entrants and Emerging Players: Capture white-space opportunity in the Volga Federal District's underdeveloped certified seed coverage, particularly Samara and Saratov regions where cereal acreage exceeds registered supplier presence. Target organic certification pathways tied to state conversion subsidies, where non-GMO open-pollinated varieties face less entrenched competition from hybrid incumbents. A digital-first go-to-market angle emphasizing traceability transparency aligns with tightening export documentation requirements. For Investors and Strategic Acquirers: The window for entry favors domestic seed houses with established Rosselkhoznadzor registration pipelines and Black Earth zone distribution networks. Long-term viability hinges on breeding infrastructure capable of compressing varietal testing cycles that currently stretch 3-5 years. Watch for inflection signals in Ministry of Agriculture subsidy program adjustments that redirect procurement volume toward climate-adapted varieties.| Strategic Initiative | Industry Significance |
|---|---|
| Marker-Assisted Selection Platform Deployment | Accelerates variety turnover for sunflower and soybean breeding pipelines in Krasnodar Krai clusters. |
| Electronic Certification Registry Integration | Aligns seed houses with Rosselkhoznadzor mandates for lot traceability and subsidy eligibility. |
| Direct Mega-Farm Contracting Expansion | Displaces dealer networks in Voronezh oblast where agricultural holdings consolidate procurement. |
| Organic Variety Development Program | Captures state subsidy flows for conversion programs requiring non-GMO open-pollinated seed. |
| Volga Federal District Distribution Buildout | Addresses certified seed underpenetration in Samara and Saratov cereal production zones. |
Research Methodology
Document review covered Rosselkhoznadzor regulatory filings, Ministry of Agriculture varietal registry data, and Eurasian Economic Union technical regulations, complemented by interviews with seed house breeding directors, agricultural cooperative procurement managers, wholesale distributor operations heads, and farm agronomists. Secondary sources included customs records for imported genetics, state subsidy program disclosures, and regional agricultural development reports. Bottom-up acreage and procurement volume estimates were triangulated against top-down market sizing from certification registry flows.
Cross-referencing historical adoption curves for certified seed against panel input from breeding program executives shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include crop category, buyer scale, distribution channel, and regional federal district. CAGRs were derived from trend extrapolation of varietal registration volumes and subsidy program allocations. Forecast inputs incorporated crushing facility capacity additions in the Black Earth zone and electronic certification mandate compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Rosselkhoznadzor approval timeline shifts and climate adaptation breeding success. Forecasts reflect assumptions around subsidy program continuity and Eurasian Economic Union technical alignment maintenance. A small set of named triggers warrants ongoing watch: Ministry of Agriculture localization rule tightening, drought frequency acceleration in southern zones, and agricultural cooperative merger momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
E. Angustifolium Market
Seeds
Pasture Seeds Market
Seeds
Europe Vegetable Seed Market
Seeds
South America Chia Seeds Market
Seeds
Guar Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
Fruit Seed Waste Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Philippines Rice Seed Market
Seeds
India Vegetable Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Tomato Seed Market
Seeds
Flax Crop Market
Seeds
Myanmar Rice Seed Market
Seeds
Global Sports Turf Seed Market