
 Flax Crop Market | 2026-2036
Flax Crop Market Size, Share, and Industry Trends Forecast 2026-2036
Flax Crop Market Intelligence
Organic certification under USDA NOP and EU 2018/848 is rotating the competitive set by raising barriers for new entrants and rewarding established operators with compliant acreage. Cargill Incorporated leverages its grain origination infrastructure across the Canadian prairies to secure premium flax streams. Richardson International Limited anchors its position through vertically integrated oilseed processing assets in Manitoba and Saskatchewan. SunOpta Inc. differentiates by specializing in organic and non-GMO flax ingredients for food and nutraceutical channels.
Flax crop denotes an annual oilseed and fiber plant, Linum usitatissimum, containing 35-45% alpha-linolenic acid in its oil and 15-25% protein in its meal, cultivated for industrial oil extraction, textile fiber production, and nutritional ingredient applications. End use application segments show nutraceuticals commanding the fastest expansion as functional food formulators seek plant-based omega-3 sources, while textile production retains mature, steady offtake from European linen manufacturers. Fiber flax occupies concentrated margin pools in France and Belgium where long-line processing preserves premium fiber length for apparel-grade linen.
Health Canada and the PMRA govern maximum residue limits for crop protection inputs entering the food and feed supply chain, while the EU REACH framework restricts certain seed treatments from entering European textile and nutraceutical markets. The USDA's National Organic Program and the EU 2018/848 organic regulation together shape export eligibility for North American growers targeting premium European and domestic health-food segments. Stakeholders must monitor evolving seed treatment approvals and organic equivalency agreements to preserve cross-border market access.
Market Dynamics
The EU Green Deal's sustainable agriculture mandates are compressing input flexibility for flax growers while simultaneously opening premium price tiers for certified organic supply chains that can demonstrate compliance.
Growth Catalysts
- Nutraceutical demand pull:Functional food formulators in North America and Europe are sourcing flax oil as a plant-based omega-3 alternative to fish oil, expanding offtake volumes in health-food channels.
- REACH framework alignment:Seed treatment approvals under EU chemical regulations are streamlining market access for compliant North American exporters targeting European textile and food-grade segments.
- Canadian prairie concentration:Manitoba and Saskatchewan production clusters offer integrated crushing and export infrastructure that reduces logistics friction for international buyers.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings directly compress margins for prairie growers operating on thin operating buffers during planting and harvest windows.
- Fiber flax supply concentration:Long-line processing capacity for apparel-grade linen remains concentrated in France and Belgium, creating single-source risk for premium textile buyers.
- Protein meal substitution:Soybean and canola meal alternatives limit flax meal penetration in animal feed rations despite favorable amino acid profiles.
Strategic Opportunities
- USDA NOP certification expansion:Growers converting conventional acreage to organic flax can capture price premiums of 40-60% above conventional grades in North American health-food channels.
- Bioplastics feedstock pivot:Linseed oil's drying properties position it as a renewable feedstock for coatings and composites manufacturers seeking petroleum alternatives.
- Direct-to-ingredient channel development:Bypassing commodity exchanges to contract directly with nutraceutical extractors reduces price exposure and secures multi-year offtake agreements.
Industry Challenges
- Organic transition timeline:The 36-month soil management period required for USDA NOP certification locks up working capital before premium pricing becomes available.
- Specialized equipment scarcity:Fiber flax harvesting requires puller-combines and scutching infrastructure distinct from oilseed flax operations, limiting farmer flexibility to switch between crop types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flax Crop Market |
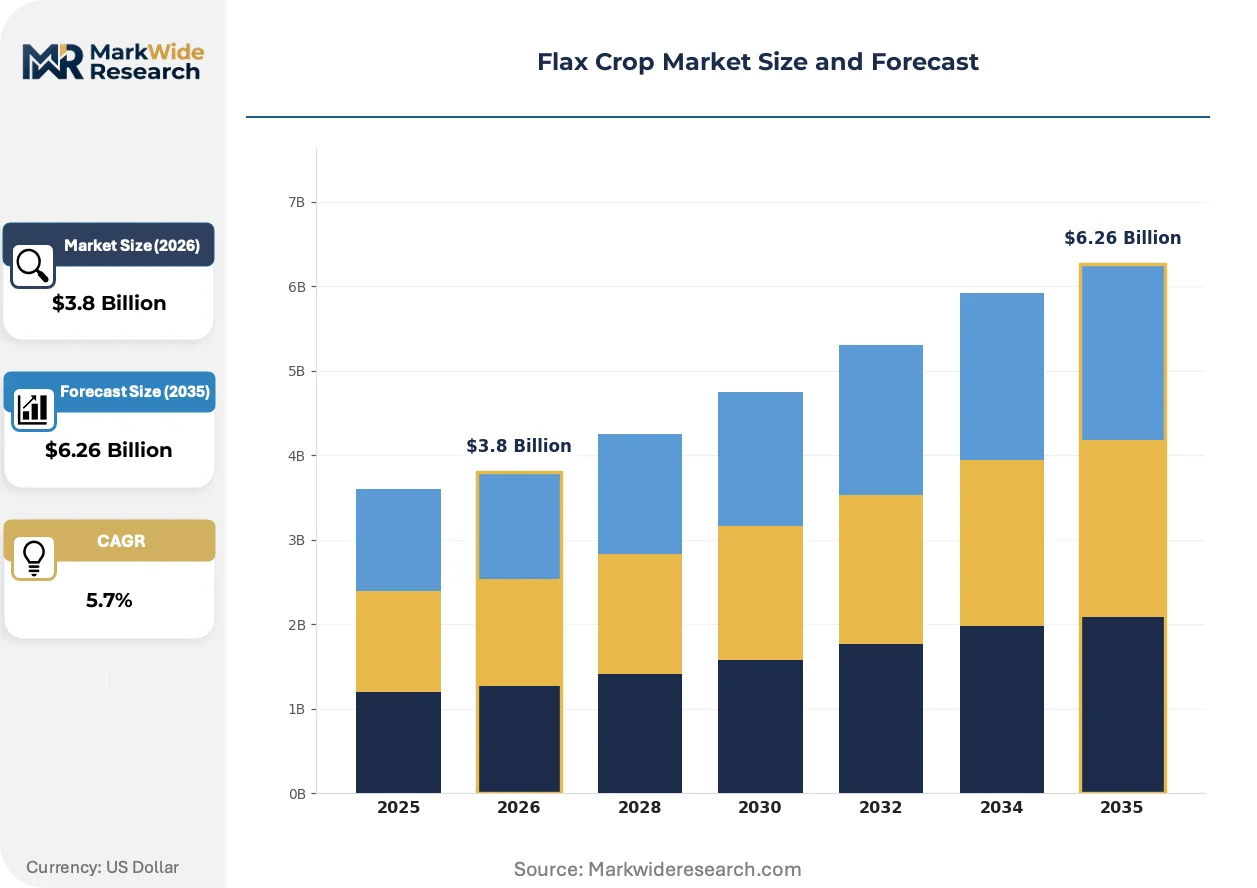
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Crop Variety: Brown Flax, Yellow Flax, Golden Linseed, Oilseed Flax, Fiber Flax End Use Application: Textile Production, Nutraceuticals, Animal Feed, Bio-composites, Pharmaceutical Ingredients Seed Treatment: Untreated, Fungicide Coated, Insecticide Coated, Bio-fertilizer Treated, Pelleted Seeds Distribution Channel: Direct Sales, Online Retailers, Agrochemical Dealers, Wholesale Markets, Agricultural Cooperatives |
| Companies Covered | Shaw's Flax Mill Ltd., The Scoular Company, Cargill Incorporated, Grain Millers Inc., SunOpta Inc., Archer-Daniels-Midland Company, Richardson International Limited, TA Foods Ltd., Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flax Crop Market Strategic Shifts & Innovations
Processing technology and certification protocols are actively reshaping how flax moves from field to end-use, compressing traditional commodity pathways and elevating traceability requirements across supply chains.
Mechanical fiber extraction systems are supplanting water-retting methods in European flax processing. French and Belgian textile cooperatives are retrofitting facilities with automated scutching lines that preserve fiber length while eliminating effluent discharge. This shift is enabling linen manufacturers to meet EU industrial emissions targets without sacrificing yarn quality.
EU 2018/848 organic regulation implementation is tightening equivalence requirements for North American exporters. The framework now demands full supply chain documentation from seed sourcing through oil extraction, with third-party audits required at each transfer point. Canadian organic flax shipments to European nutraceutical processors face extended customs clearance timelines as certification paperwork undergoes enhanced verification.
Contracting practices among ingredient buyers are compressing spot market reliance. Large functional food manufacturers in Germany and the Netherlands are negotiating direct multi-year supply agreements with prairie grower cooperatives, locking in alpha-linolenic acid specifications and organic certification status. This bypasses traditional grain elevator aggregators and transfers price risk onto production-side balance sheets.
Flax Crop Market Segmentation
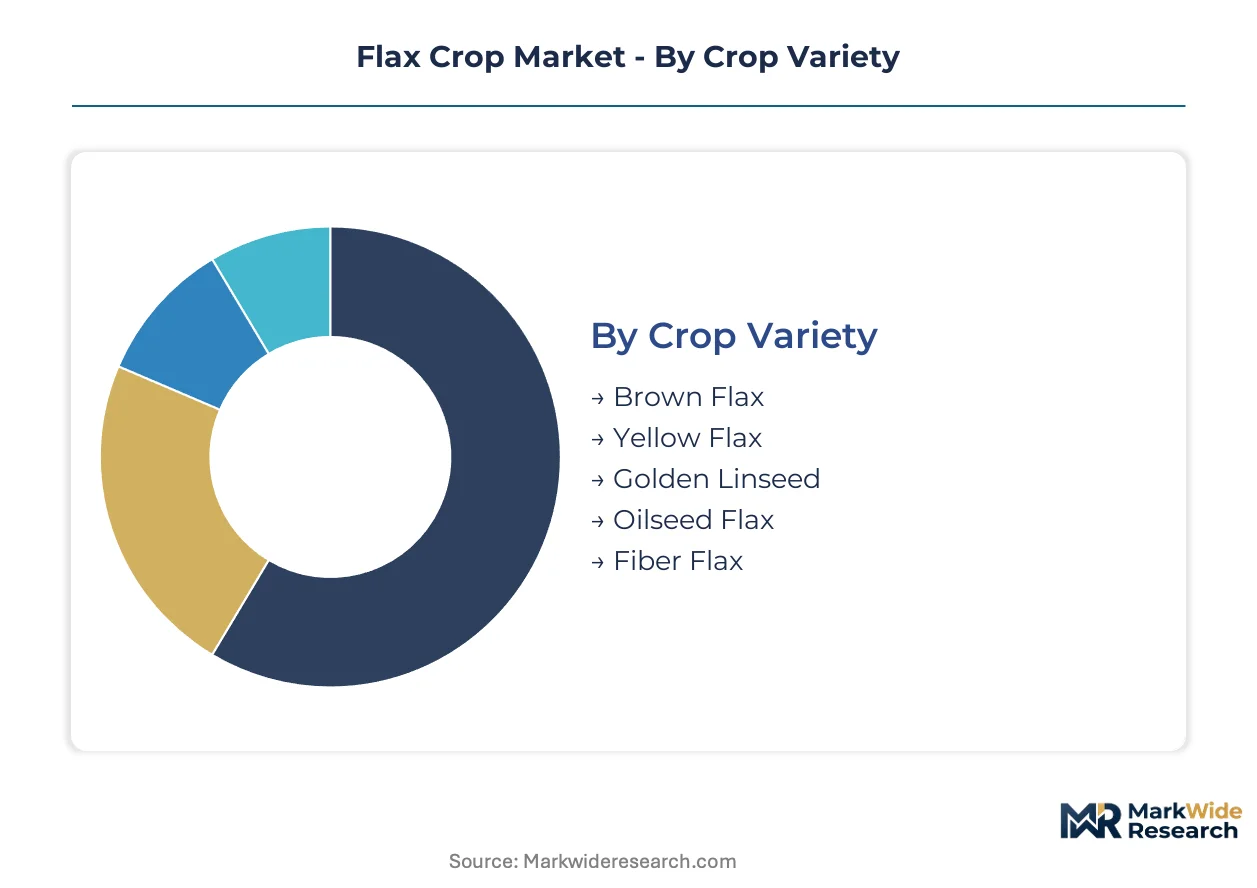
Flax crop segmentation reveals how processing requirements and end-use specifications create distinct margin pools. Each category channels supply toward fundamentally different buyer value chains with incompatible quality standards.
Crop Variety:
Oilseed flax faces the most intense substitution pressure from canola and camelina in omega-3 applications, while fiber flax maintains protected niches in premium textiles.
- Oilseed Flax:Contains 35-45% alpha-linolenic acid in its oil composition. Demand concentrates in Canadian nutraceutical extraction facilities as formulators seek plant-based omega-3 alternatives to fish oil, though canola oil competition limits pricing power.
- Fiber Flax:Produces long bast fibers measuring 60-90 cm in length suitable for apparel-grade linen. European textile manufacturers in France and Belgium absorb nearly all premium supply, with EU Green Deal emissions mandates reinforcing demand for domestically processed fiber.
- Brown Flax:Standard oilseed variety with darker seed coat and typical 40% oil content. Widely cultivated across Manitoba and Saskatchewan for commodity crushing operations.
- Yellow Flax:Lighter seed color preferred by certain food-grade applications for visual appeal in baked goods and cereals.
- Golden Linseed:Premium food-grade variant commanding higher prices in health-food retail channels for whole-seed consumption.
Oilseed flax retains volume leadership; fiber flax holds the steepest expansion curve.
End Use Application:
Margin structures diverge sharply across applications, with pharmaceutical and nutraceutical channels extracting value through certification premiums while commodity feed and composites compete on cost.
- Nutraceuticals:Flax oil serves functional food formulators seeking ALA-rich ingredients for heart-health positioning. German and Dutch buyers now contract directly with prairie grower cooperatives, bypassing traditional grain elevators to secure organic certification and fatty acid specifications.
- Textile Production:Long-line linen manufacturing requires specialized harvesting equipment and water-retting or mechanical scutching infrastructure. French and Belgian processors dominate premium yarn production, with automated scutching lines enabling EU emissions compliance without fiber quality degradation.
- Animal Feed:Flax meal provides 15-25% protein with favorable amino acid profiles for dairy rations. Soybean and canola meal alternatives constrain penetration despite nutritional benefits.
- Pharmaceutical Ingredients:High-purity lignan extracts require solvent extraction and GMP-certified processing facilities.
- Bio-composites:Short fiber fractions and shive enter automotive interior panels and construction materials as petroleum-free reinforcements.
Textile production anchors mature revenue bases; nutraceuticals are climbing the fastest.
Seed Treatment:
Regulatory fragmentation between jurisdictions creates compliance complexity, with EU REACH restrictions eliminating certain chemistries from export-bound supply chains.
- Untreated:Required for organic certification under USDA NOP and EU 2018/848 standards. Canadian organic acreage conversion is accelerating as growers pursue 40-60% price premiums in North American health-food channels.
- Fungicide Coated:Standard protection against soil-borne pathogens like Fusarium and Pythium in conventional production systems. Health Canada and PMRA maximum residue limits govern allowable chemistries entering food and feed supply chains.
- Insecticide Coated:Targets wireworm and seedcorn maggot pressure in prairie planting conditions.
- Bio-fertilizer Treated:Rhizobium and mycorrhizal inoculants supporting nitrogen fixation and phosphorus uptake.
- Pelleted Seeds:Uniform sizing for precision planting equipment, reducing seed waste and improving emergence consistency.
Untreated seed claims the premium tier; bio-fertilizer treatments are expanding most quickly as biological agriculture gains regulatory support.
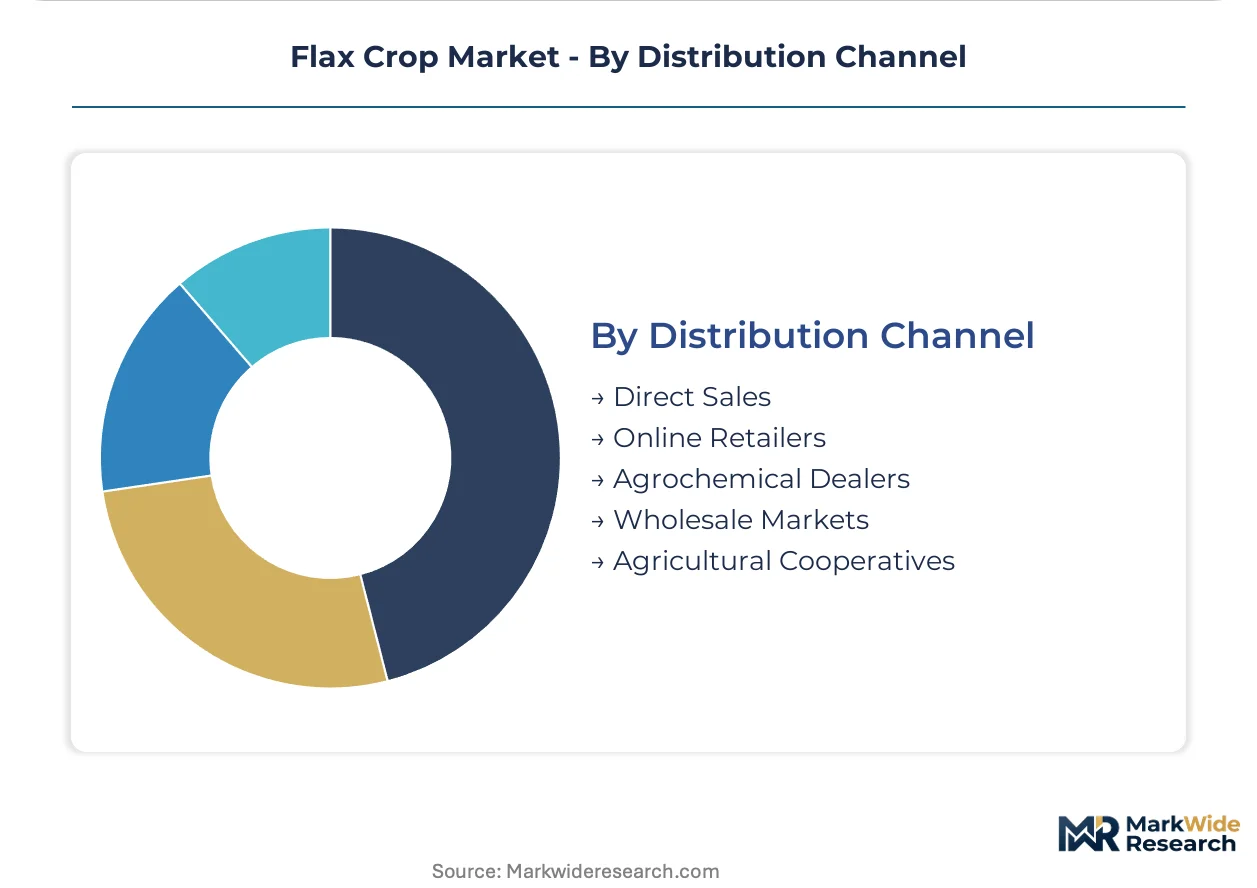
Distribution Channel:
Channel selection determines price discovery mechanisms and working capital requirements, with direct contracting displacing spot market reliance among large-volume buyers.
- Direct Sales:Multi-year supply agreements between grower cooperatives and nutraceutical extractors or textile processors. German functional food manufacturers now lock in alpha-linolenic acid specifications and organic status through this channel, transferring price risk to production-side balance sheets.
- Agricultural Cooperatives:Pool member production for collective bargaining power and shared logistics infrastructure. Manitoba and Saskatchewan cooperatives offer integrated crushing and export capabilities that reduce friction for international buyers.
- Agrochemical Dealers:Bundle seed with crop protection inputs and agronomic advisory services.
- Wholesale Markets:Commodity exchange pricing for undifferentiated oilseed flax into bulk crushing.
- Online Retailers:Small-lot garden seed and specialty food-grade flax for direct consumer purchase.
Direct sales capture the highest value per ton; agricultural cooperatives maintain the broadest farmer participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's sustainable agriculture mandates are redirecting subsidy flows toward certified organic production, while Canadian prairie provinces expand crushing capacity to capture nutraceutical export demand.
Canada
Manitoba and Saskatchewan dominate oilseed flax cultivation, with integrated crushing infrastructure serving German and Dutch nutraceutical extractors. Health Canada and the PMRA govern maximum residue limits for crop protection inputs entering food and feed channels. Winnipeg-based cooperatives pool prairie production for collective export bargaining.
France
French textile manufacturers absorb premium long-fiber flax for apparel-grade linen, with automated scutching lines replacing water-retting to meet EU industrial emissions targets. The EU 2018/848 organic regulation tightens equivalence documentation for North American imports. Normandy and Flanders processing clusters preserve fiber length through mechanical extraction.
Belgium
Belgian linen cooperatives command concentrated margin pools for high-end textile applications, sourcing raw fiber through specialized long-line contracts. REACH framework restrictions eliminate certain seed treatments from export-bound supply chains. The Flanders region hosts scutching facilities retrofitting for emissions compliance without quality degradation.
Germany
German functional food manufacturers negotiate direct multi-year supply agreements with prairie grower cooperatives, locking in alpha-linolenic acid specifications and organic certification. ECHA administers REACH compliance for chemical inputs entering European markets. Hamburg and Rotterdam serve as consolidation points for Canadian organic flax shipments facing extended customs clearance timelines.
United States
US health-food channels offer 40-60% price premiums for USDA NOP-certified organic flax, accelerating prairie acreage conversion despite the 36-month soil management lockup. The USDA's National Organic Program shapes export eligibility for European-bound supply. North Dakota production clusters feed domestic crushing and specialty food-grade channels.
Flax Crop Market Key Industry Players
Listed leaders compete with private specialists across origination and processing infrastructure, creating a tiered structure where scale advantages in logistics meet certification premiums in ingredients. The competitive set rotates around three archetypes: integrated grain traders with elevator networks, oilseed processors with captive crushing assets, and organic ingredient specialists with health-food channel access. Dominant competitive moves include backward integration into grower contracting and portfolio diversification toward certified organic streams.
Among North American integrated traders, Cargill Incorporated and Richardson International Limited exemplify scale-driven origination archetypes, while SunOpta Inc. occupies a position within the organic-specialist tier. These three anchors illustrate how market participants split between commodity volume plays and premium certification capture.
| Leading Market Players |
|---|
| Shaw's Flax Mill Ltd. |
| The Scoular Company |
| Cargill Incorporated |
| Grain Millers Inc. |
| SunOpta Inc. |
| Archer-Daniels-Midland Company |
| Richardson International Limited |
| TA Foods Ltd. |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
Canadian crushing capacity utilization above 85% creates scale economies that compress per-unit processing costs while simultaneously hardening price floors for prairie growers. This concentration of oilseed infrastructure in Manitoba and Saskatchewan funnels export-bound supply through a narrow corridor, amplifying buyer bargaining power in spot markets while rewarding contracted organic streams with premium stability.
Pricing Analysis
Certification level under USDA NOP and EU 2018/848 creates the primary spread between commodity and premium tiers. Three-tier pricing structure across organic, conventional food-grade, and commodity crushing grades captures 40-60% premiums for certified supply in North American health-food channels. Cost compression in commodity oilseed runs through canola substitution pressure and thin operating buffers during prairie planting windows. Nutraceutical extractors demonstrate lowest price sensitivity due to ALA specification requirements, while bulk crushers face intense margin pressure from alternative omega-3 sources.
Supply Chain Analysis
Canada and France anchor flax supply through distinct specializations—prairie provinces for oilseed crushing and Normandy-Flanders clusters for long-fiber textile processing. Canadian production draws from glyphosate-tolerant brown flax varieties and specialized puller-combine harvesting equipment distinct from European fiber operations. Single-source vulnerability concentrates in Belgian scutching capacity for apparel-grade linen, where automated mechanical extraction replaces water-retting under EU emissions mandates. Distribution runs through Winnipeg-based agricultural cooperatives for North American origination and Hamburg-Rotterdam consolidation for European-bound organic shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German and Dutch functional food manufacturers have consolidated procurement through direct multi-year contracting, shifting buyer power upstream and compressing spot market liquidity for undifferentiated supply. This concentration demands strategic repositioning across stakeholder archetypes.
For Market Incumbents: Secure organic certification pipelines through backward integration into prairie grower contracting before the 36-month soil management window locks out late converters. Cargill and Richardson International should expand Manitoba crushing capacity to capture ALA specification premiums, while SunOpta deepens health-food channel control through direct nutraceutical extractor relationships. Canola oil substitution in omega-3 applications threatens commodity pricing power; certification investment offers the defensive lever. For New Entrants and Emerging Players: Differentiate on bio-fertilizer treated seed and biological agriculture compliance as EU Green Deal subsidy flows redirect toward sustainable input systems. White-space targets include bioplastics feedstock supply to coatings manufacturers seeking petroleum alternatives and direct-to-ingredient contracting with German functional food formulators. The most penetrable entry point sits in organic flax meal for dairy rations, where amino acid profile advantages remain underexploited against soybean and canola alternatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors organic ingredient specialists with health-food channel access over commodity crushers facing input cost volatility. Long-term viability hinges on certification moats and multi-year offtake contract depth rather than spot market exposure. Acquisition target archetype: prairie-based cooperatives with USDA NOP acreage and existing German nutraceutical relationships. The signal to watch is EU 2018/848 equivalence agreement revisions that could extend customs clearance timelines and reroute North American export flows.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Expansion | USDA NOP conversion captures 40-60% premiums in health-food channels before competitor lock-in. |
| Backward Integration into Grower Contracting | Direct prairie cooperative agreements transfer price risk and secure ALA specifications for German extractors. |
| Mechanical Scutching Retrofit | Belgian and French facilities meet EU industrial emissions targets without degrading long-fiber quality. |
| Bioplastics Feedstock Pivot | Linseed oil drying properties position supply for coatings manufacturers seeking petroleum alternatives. |
| Multi-year Supply Agreement Structuring | Bypasses grain elevator aggregators and locks organic status for Dutch functional food manufacturers. |
Research Approach
A standing panel of agronomists at prairie agricultural cooperatives, procurement directors at German nutraceutical extractors, regulatory affairs specialists at Health Canada and PMRA, and textile processing engineers in Normandy provided ongoing calibration across the study period. Primary interviews with flax growers in Manitoba and Saskatchewan, organic certification auditors, and functional food formulators in the Netherlands were cross-validated against secondary sources including USDA National Organic Program filings, EU 2018/848 equivalence documentation, ECHA REACH seed treatment registries, and Canadian Grain Commission export data. Bottom-up acreage and yield estimates were triangulated with top-down crushing capacity and export flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including crop variety (oilseed versus fiber flax), certification status (USDA NOP, EU 2018/848, conventional), end-use application (nutraceutical, textile, feed, pharmaceutical, bio-composite), and distribution channel (direct sales, cooperative pooling, wholesale exchange). CAGRs were derived from trend extrapolation of prairie planting intentions, EU Green Deal subsidy allocation trajectories, and German functional food manufacturer capacity expansion announcements. Industry-specific forecast inputs included alpha-linolenic acid specification trends and mechanical fiber extraction technology adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU 2018/848 equivalence for North American organic supply, stable prairie fertilizer input costs, and continued German nutraceutical demand growth would require recalibration. Forecasts reflect documented assumptions regarding seed treatment approval timelines, organic transition completion rates, and scutching capacity utilization in Flanders. Specific risk factors that could revise projections include REACH framework expansion restricting additional chemistries, Canadian drought frequency affecting prairie yields, and lignan extraction technology disruption altering pharmaceutical ingredient demand. Recalibration cycles align with material shifts in EU subsidy allocation, organic equivalency agreement status, and crushing capacity utilization reports.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Uganda Seeds Market
Seeds
Russia Forage Seed Market
Seeds
Seed Cracker Market
Seeds
Genetically Modified Seeds Market
Seeds
South America Quinoa Seeds Market
Seeds
Eucommia Seed Oil Market
Seeds
Philippines Seed Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Dodder Seed Market
Seeds
India Forage Seed Market
Seeds
Global Wheat Seed Market
Seeds
Flower Seed Market
Seeds
Mexico Seed Market
Seeds
Lupin Market
Seeds
Europe Chia Seeds Market